
 Global Artificial Intelligence Chip Market | 2026-2036
Global Artificial Intelligence Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence Chip Market Foresight
Multi-source foundry partnerships is restructuring procurement across the AI chip landscape. Nvidia leverages Taiwan Semiconductor Manufacturing Company for advanced node production while sustaining design leadership in GPU architectures. Intel anchors its IDM strategy with in-house fabrication and competing foundry services. Advanced Micro Devices differentiates through chiplet-based designs that navigate supply constraints.
Artificial intelligence chips are semiconductor devices engineered to execute matrix-intensive computations with specialized arithmetic logic units, typically fabricated on sub-5nm process nodes with high-bandwidth memory integration. Their primary purpose is to accelerate neural network training and inference workloads that overwhelm general-purpose processors. GPU and ASIC categories dominate value capture, with GPU shipments occupying the largest installed base and ASIC designs recording the steepest growth trajectory among hyperscaler custom silicon programs. Neuromorphic and photonic technology segments remain nascent but concentrate long-term R&D margin pools as digital approaches face power-density ceilings.
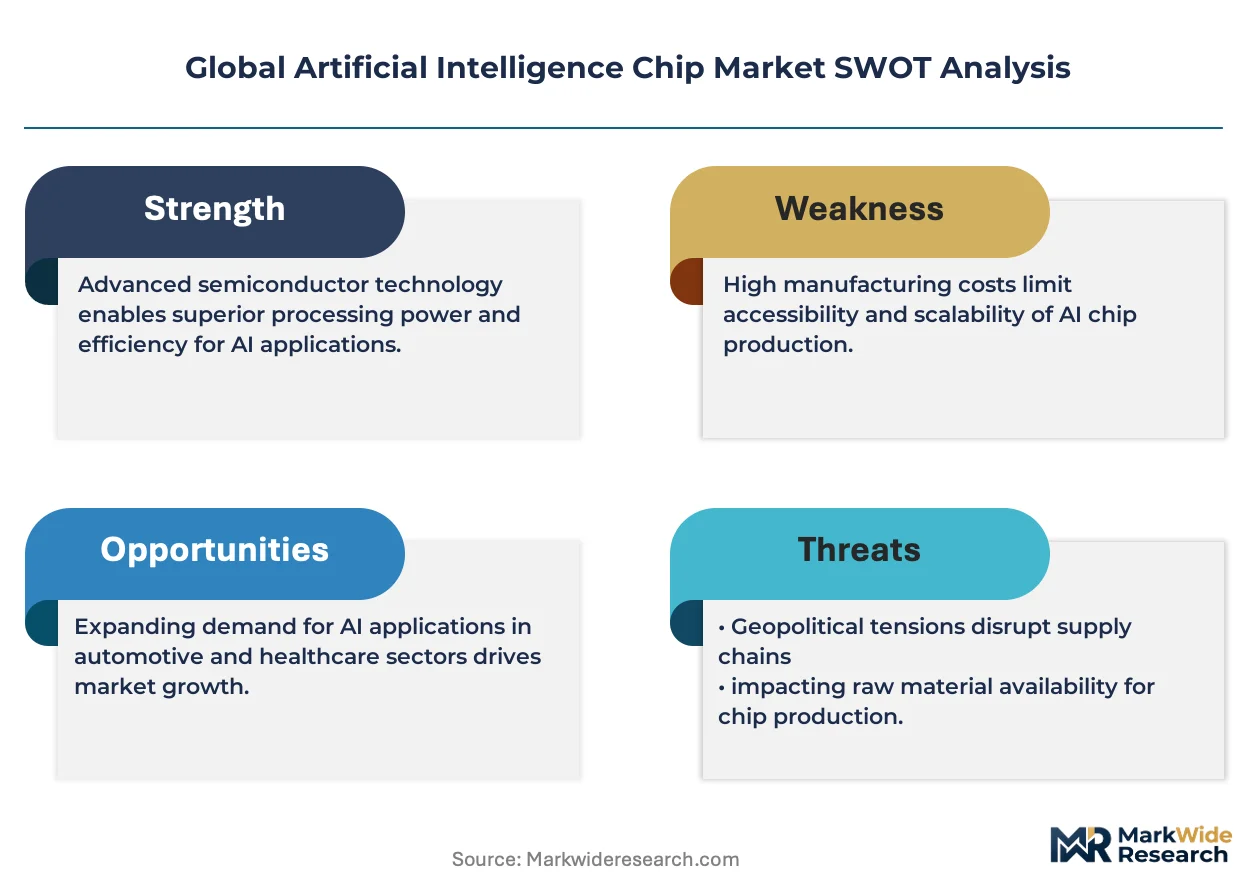
FDA scrutiny of AI-enabled medical devices, EU AI Act conformity requirements, and FCC spectrum allocations for edge AI deployments are collectively tightening product certification pathways and cross-border market access conditions. China's NMPA and MIIT are accelerating domestic substitution mandates that fragment semiconductor equipment sourcing. Stakeholders must monitor which regulatory jurisdiction captures standard-setting authority first, as compliance alignment will determine geographic revenue eligibility.
Market Dynamics
Cloud hyperscalers are consolidating AI training capacity around Taiwan's foundry ecosystem, compressing supply timelines while EU AI Act compliance mandates reshape product certification pathways for high-risk deployments.
Growth Catalysts
- EU AI Act Conformity Requirements:High-risk AI system classification is accelerating demand for traceable, auditable chip architectures that support explainable inference pipelines.
- Sub-3nm Process Migration:Gate-all-around transistor architectures are unlocking power-efficiency gains that enable larger model training clusters within fixed energy budgets.
- Edge AI Spectrum Allocation:FCC rulings on millimeter-wave bands for autonomous systems are expanding addressable silicon volumes beyond datacenter-centric demand.
Market Restraints
- Advanced Packaging Concentration:CoWoS and 3D-IC capacity bottlenecks in Taiwan are extending lead times for high-bandwidth memory integration.
- Extreme Ultraviolet Lithography Cost Structure:ASML equipment depreciation cycles are inflating wafer costs for sub-5nm nodes beyond mid-market affordability thresholds.
- Domestic Substitution Mandates:China's MIIT localization targets are fragmenting equipment sourcing and constraining cross-border technology transfer.
Strategic Opportunities
- Neuromorphic Inference at Endpoint:Event-driven spiking architectures are opening battery-constrained robotics and sensor fusion applications that digital GPUs cannot address.
- India PLI Scheme Incentives:Semiconductor fabrication and design-linked production subsidies are attracting assembly and test investments outside traditional East Asian nodes.
- Photonic Interconnect Convergence:Silicon photonics co-packaged with compute dies is reducing interconnect energy overhead in training clusters exceeding ten-thousand GPU scale.
Industry Challenges
- Compiler and Software Stack Fragmentation:Proprietary CUDA ecosystems versus open SYCL and MLIR pathways are forcing customers into costly porting exercises.
- High-Bandwidth Memory Supply Coordination:SK Hynix and Samsung capacity allocation disputes with foundries are creating mismatched die availability for advanced packaging.
- EU AI Act Certification Timelines:Conformity assessment body capacity constraints are extending product launch windows for medical and automotive inference accelerators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence Chip Market |
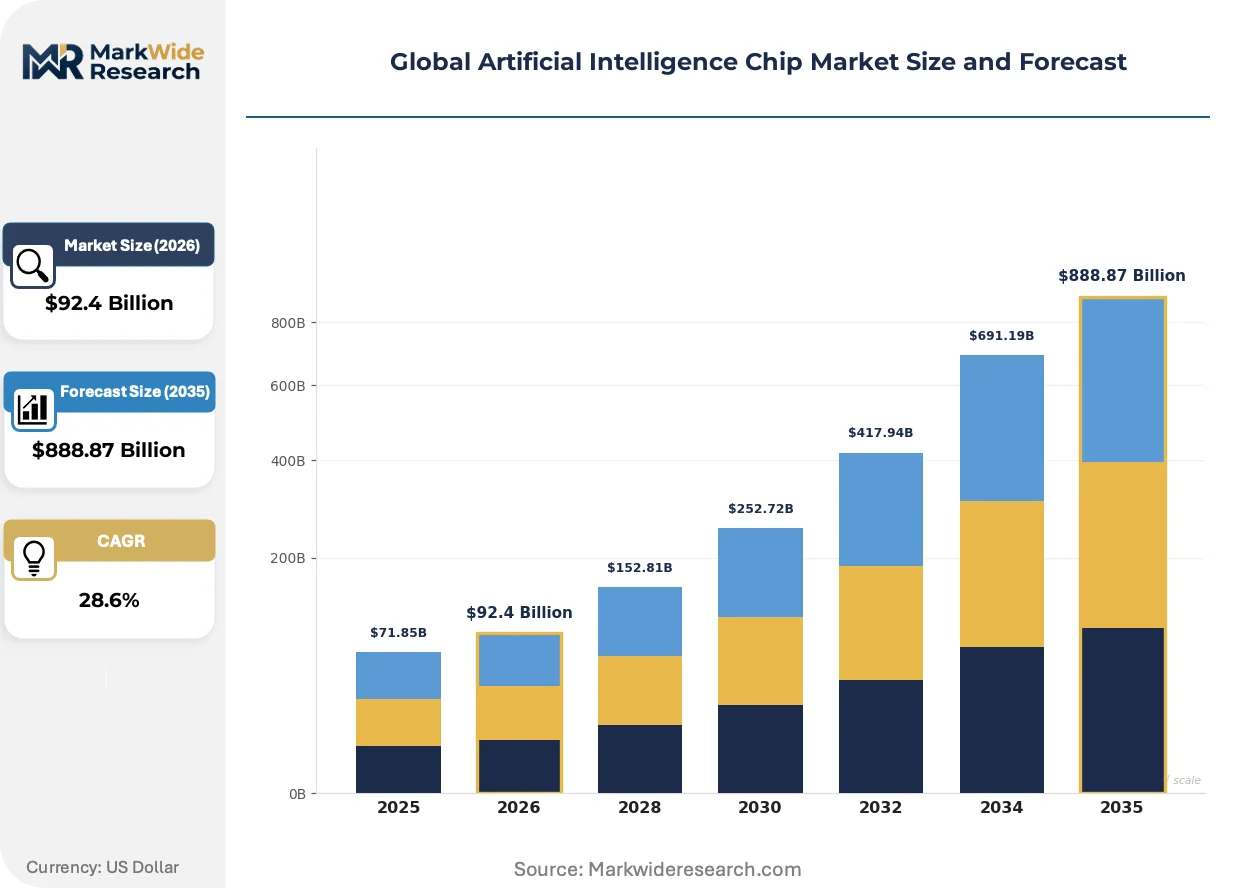
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $888.87 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Chip Type: GPU, FPGA, ASIC, TPU, CPU Technology: Neuromorphic, Digital Signal Processing, Quantum Computing, Photonic, Analog Use Case: Speech Recognition, Image Analysis, Predictive Analytics, Autonomous Robotics, Natural Language Processing Customer Type: Cloud Service Providers, Semiconductor Manufacturers, AI Research Labs, Data Center Operators, IoT Solution Providers |
| Companies Covered | Advanced Micro Devices, Intel, Nvidia, Micron Technology, Cerebras Systems, Broadcom, Qualcomm, IBM, Taiwan Semiconductor Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence Chip Market Shifts & Advancements
Chiplets are dismantling monolithic silicon economics while regulatory jurisdictions compete to capture standard-setting authority over AI hardware certification.
Chiplet-based disaggregation is integrating specialized compute, memory, and I/O dies through standardized interconnect protocols like UCIe. Hyperscaler custom silicon programs are adopting this approach to optimize yield and mix-and-match IP blocks. The structural consequence is integrating fabless design flexibility with foundry-scale manufacturing efficiency, compressing time-to-tapeout for domain-specific accelerators.
EU AI Act high-risk system requirements are mandating built-in accuracy, robustness, and cybersecurity specifications for AI chips deployed in critical infrastructure. Hardware vendors must now embed logging, audit trails, and fail-safe mechanisms at the silicon level. Medical device and autonomous vehicle segments are most affected, with ANSM and KBA aligning national implementation timelines ahead of the 2026 enforcement window.
Direct procurement relationships between cloud operators and foundries are displacing traditional merchant silicon distribution channels. Amazon, Microsoft, and Google are negotiating wafer starts and capacity reservations directly with TSMC and Samsung Foundry, bypassing semiconductor distributors. This pattern is most visible in the United States, where IRA clean energy incentives for domestic semiconductor manufacturing are accelerating onshore advanced packaging investments.
Global Artificial Intelligence Chip Market Segmentation
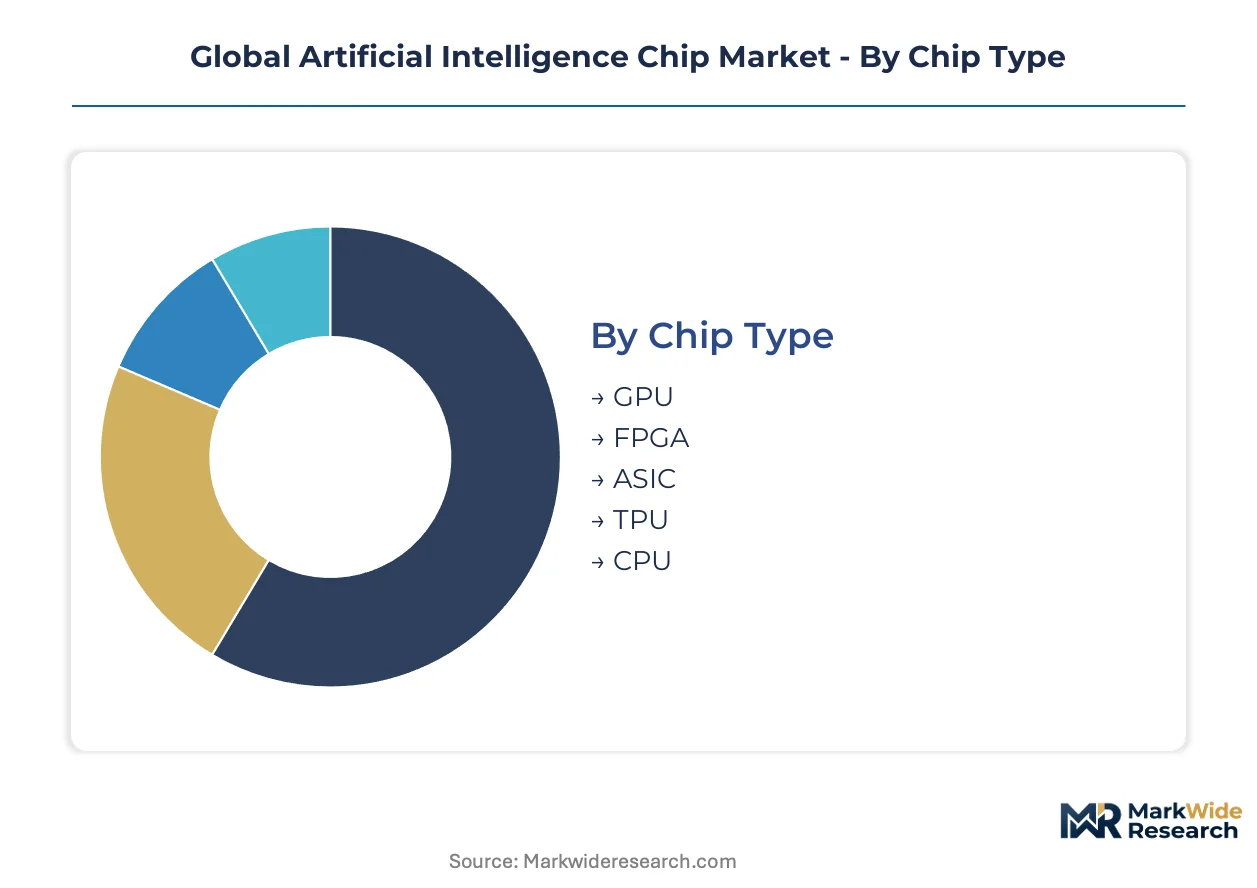
AI chip procurement patterns diverge sharply across compute paradigms, with training workloads favoring high-bandwidth architectures while inference at edge nodes prioritizes thermal efficiency. Understanding these segment boundaries clarifies why foundry capacity allocation and software ecosystem lock-in vary dramatically by deployment context.
Chip Type:
Process node specialization defines competitive boundaries within each silicon category, with memory integration density and interconnect bandwidth serving as the primary technical differentiators.
- GPU:Massively parallel streaming multiprocessors execute matrix operations across thousands of concurrent threads, with high-bandwidth memory stacks enabling parameter-dense model training. Demand concentrates among cloud hyperscalers building training clusters exceeding ten-thousand units, constrained by CoWoS advanced packaging capacity bottlenecks in Taiwan's foundry ecosystem.
- ASIC:Domain-specific datapaths eliminate general-purpose overhead for inference workloads at hyperscale deployment volumes, delivering superior operations-per-watt against programmable alternatives. Google's TPU program and Amazon's Trainium/Inferentia families anchor demand, with custom silicon adoption accelerating as model architectures stabilize.
- FPGA:Reconfigurable logic fabrics enable algorithmic flexibility for prototyping and low-volume production runs where NRE costs prohibit mask-based designs.
- TPU:Google's proprietary tensor processing architecture optimizes TensorFlow execution graphs through systolic array datapaths.
- CPU:General-purpose cores with AVX-512 or AMX extensions handle sparse inference and control-plane orchestration in heterogeneous deployments.
GPU leads on scale; ASIC leads on momentum.
Technology:
Physical layer innovation determines energy-delay product limits as digital CMOS scaling slows, with alternative compute paradigms targeting specific workload inefficiencies.
- Digital Signal Processing:Fixed-function multiply-accumulate arrays dominate embedded audio and sensor fusion applications, with TI and NXP portfolios anchoring automotive and industrial demand in Germany and Japan.
- Neuromorphic:Event-driven spiking architectures eliminate clocked power dissipation for always-on pattern recognition in battery-constrained robotics. Intel's Loihi and IBM's TrueNorth programs concentrate research investment, with commercial deployment pending algorithmic toolchain maturation.
- Photonic:Silicon photonics co-packaging reduces interconnect energy overhead in training clusters, with Ayar Labs and Lightmatter targeting exascale deployments.
- Quantum Computing:Superconducting and trapped-ion qubit systems address optimization and simulation workloads beyond classical tractability.
- Analog:In-memory compute architectures execute vector-matrix multiplication directly within crossbar arrays, bypassing von Neumann bottlenecks.
Digital Signal Processing anchors near-term revenue; neuromorphic approaches are climbing the fastest.
Use Case:
Application-specific latency and accuracy requirements dictate silicon selection, with safety-critical deployments imposing certification constraints that reshape hardware specifications.
- Natural Language Processing:Transformer architectures demand massive parameter storage and attention mechanism acceleration, driving demand for HBM-equipped training accelerators. OpenAI and Anthropic procurement patterns in the United States concentrate capacity allocation at TSMC's leading edge.
- Autonomous Robotics:Deterministic latency bounds and functional safety requirements per ISO 26262 constrain architecture selection for automotive and industrial deployment. KBA certification timelines in Germany and NHTSA guidance in the United States extend product validation cycles.
- Image Analysis:Convolutional and vision transformer workloads optimize for throughput-per-watt in surveillance and medical imaging endpoints.
- Speech Recognition:Recurrent and transformer-based acoustic models prioritize low-power continuous operation in consumer electronics.
- Predictive Analytics:Gradient-boosted and neural forecasting models execute on standard datacenter infrastructure with less specialized acceleration.
Natural Language Processing commands the largest silicon allocation; Autonomous Robotics faces the steepest certification barriers.
Customer Type:
Procurement scale and technical sophistication create distinct purchasing patterns, with direct foundry relationships displacing traditional distribution channels at the largest volumes.
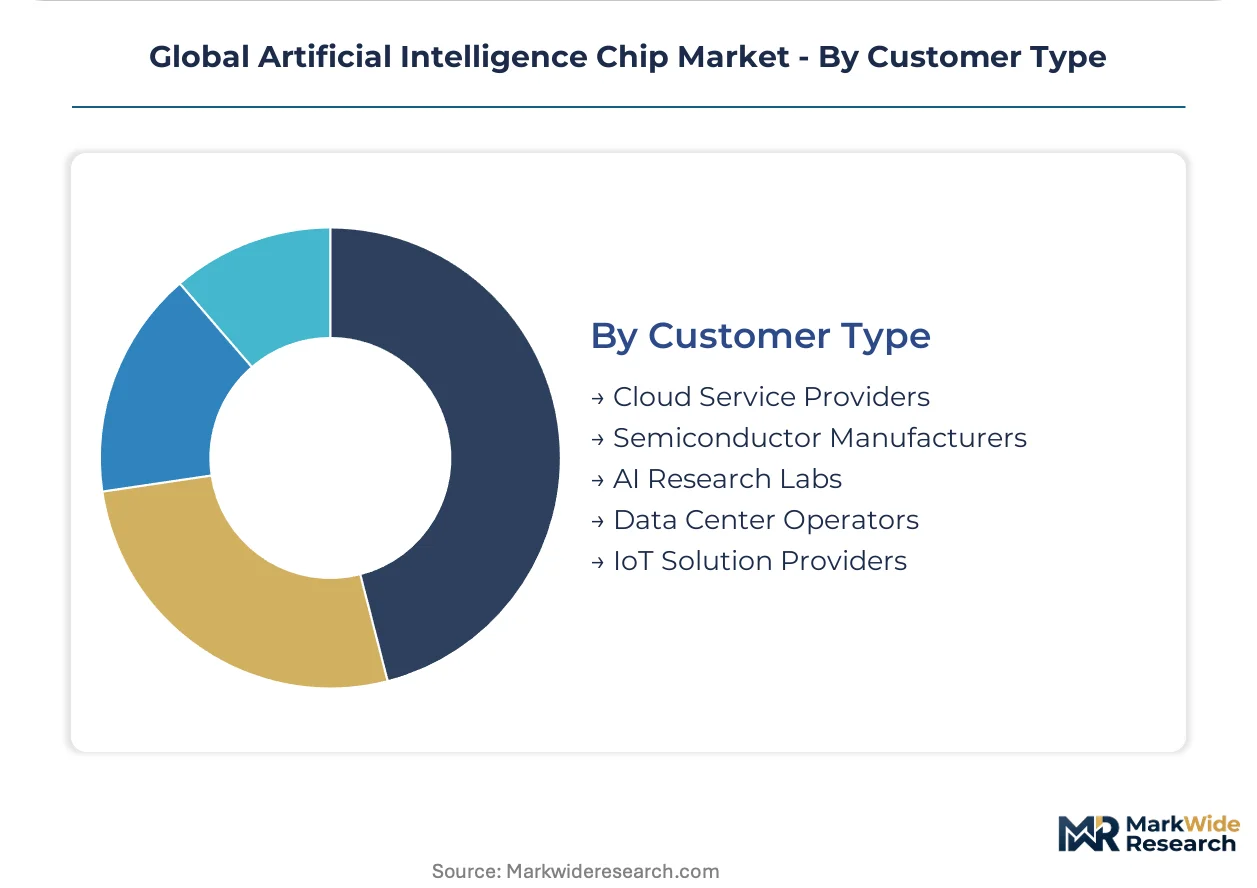
- Cloud Service Providers:Amazon Web Services, Microsoft Azure, and Google Cloud Platform negotiate wafer starts directly with TSMC and Samsung Foundry, bypassing semiconductor distributors. IRA clean energy incentives in the United States accelerate domestic advanced packaging investments for their training infrastructure.
- AI Research Labs:OpenAI, DeepMind, and national laboratory consortia access dedicated cluster allocations through cloud partnerships or direct hardware procurement.
- Data Center Operators:Colocation and enterprise facility providers deploy inference-optimized configurations for multi-tenant model serving.
- Semiconductor Manufacturers:IDM and fabless design houses procure AI accelerators for computational lithography and yield optimization workflows.
- IoT Solution Providers:Edge deployment specialists integrate low-power accelerators for distributed sensor networks and predictive maintenance endpoints.
Cloud Service Providers dominate wafer consumption; IoT Solution Providers are expanding most quickly at the network edge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's foundry ecosystem concentrates advanced node production for AI accelerators, with Hsinchu Science Park anchoring CoWoS packaging capacity that cloud hyperscalers depend upon. Regulatory fragmentation across major economies is reshaping where silicon certification and final assembly occur.
United States
Cloud hyperscalers in Seattle and San Francisco Bay Area drive wafer demand for training clusters exceeding ten-thousand units. The IRA channels clean energy incentives toward domestic advanced packaging investments in Arizona and Texas. Intel's IDM fabrication complex in New Mexico exemplifies reshoring momentum for leading-edge logic production.
China
Domestic substitution mandates from MIIT accelerate local design house procurement of inference accelerators for surveillance and industrial automation. NMPA certification requirements for AI-enabled medical devices constrain import eligibility for foreign silicon. Yangtze River Delta design clusters in Shanghai and Hangzhou concentrate fabless startup formation despite equipment sourcing restrictions.
Germany
Automotive OEMs in Stuttgart and Munich specify functional safety-compliant inference accelerators for autonomous driving platforms under KBA oversight. EU AI Act implementation through BSI conformity assessment extends product validation timelines for high-risk deployments. Dresden's silicon photonics research consortium targets interconnect energy reduction for exascale training infrastructure.
South Korea
Memory suppliers in Icheon and Yongin negotiate HBM capacity allocation directly with foundries to match die availability for advanced packaging. Government semiconductor R&D programs under METI-equivalent structures support 3D-IC process development. Pangyo's AI startup cluster consumes domestic GPU and NPU production for large language model training.
India
PLI scheme incentives attract assembly and test investments to Gujarat and Karnataka as alternatives to East Asian packaging nodes. CDSCO alignment with international medical device standards opens procurement pathways for diagnostic imaging accelerators. Bangalore's design services ecosystem supports global fabless houses with verification and physical implementation talent.
Global Artificial Intelligence Chip Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue domain-specific architectures outside general-purpose acceleration. The vendor base stratifies across three tiers: integrated device manufacturers with captive fabrication, fabless design houses leveraging foundry partnerships, and custom silicon programs operated by cloud end-users. Strategic archetypes include full-stack platform providers, memory-integrated specialists, and open-ecosystem challengers. Capacity reservation agreements and compiler ecosystem lock-in represent the dominant competitive moves.
Within the fabless design tier, Advanced Micro Devices exemplifies chiplet-based disaggregation strategies that navigate supply constraints. Nvidia anchors premium-tier GPU architectures through TSMC foundry partnerships. Among integrated manufacturers, Intel occupies a position spanning both merchant silicon and captive production for internal AI acceleration needs.
| Leading Market Players |
|---|
| Advanced Micro Devices |
| Intel |
| Nvidia |
| Micron Technology |
| Cerebras Systems |
| Broadcom |
| Qualcomm |
| IBM |
| Taiwan Semiconductor Manufacturing Company |
| Others |
Supply & Pricing Matrix
Gate-all-around transistor migration at sub-3nm nodes simultaneously inflates capital expenditure requirements and consolidates pricing power among foundries possessing extreme ultraviolet lithography capacity. Cloud hyperscalers absorb these cost escalations through long-term wafer agreements while mid-market buyers face exclusion from leading-edge procurement.
Pricing Analysis
Extreme ultraviolet lithography depreciation cycles pass through to wafer costs most acutely at nodes below 5nm. Pricing stratifies across premium, standard, and economy tiers based on process node sophistication and high-bandwidth memory integration density. Cost compression in standard-tier GPUs intensifies as AMD and Intel compete for datacenter share against Nvidia's CUDA ecosystem lock-in. Cloud service providers exhibit lowest price sensitivity due to volume scale and direct foundry relationships; IoT solution providers at the edge face highest sensitivity given thermal constraints and unit economics.
Supply Chain Analysis
EU AI Act conformity assessment requirements gate market access for medical and automotive inference accelerators, extending validation timelines and concentrating procurement among pre-certified vendors. Taiwan, South Korea, and the United States anchor advanced node production, with Hsinchu Science Park hosting critical CoWoS packaging capacity. Supply chains draw from neon gas purification facilities in Ukraine, high-purity silicon ingot suppliers in Japan, and photoresist chemical production in Belgium. Single-source vulnerability concentrates around ASML's extreme ultraviolet equipment monopoly. Distribution runs through direct foundry negotiations for cloud hyperscalers, with merchant silicon channels serving mid-tier enterprise demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's 2026 enforcement window compounds demand for traceable, auditable chip architectures that support explainable inference pipelines. This regulatory milestone elevates hardware certification from compliance checkbox to competitive differentiator.
For Market Incumbents: Deepen advanced packaging capacity investments in Arizona and Texas to capture IRA clean energy incentives while insulating against Taiwan concentration risk. Fortify compiler ecosystem moats through SYCL and MLIR pathway development to counter open-source challengers. Defensive consolidation around high-bandwidth memory supply agreements with SK Hynix and Samsung mitigates die availability mismatches that plague rival chiplet programs. For New Entrants and Emerging Players: Enter via neuromorphic inference architectures for battery-constrained robotics applications where digital GPUs face fundamental power-density limitations. Target India PLI scheme incentives for assembly and test investments outside traditional East Asian nodes. Pursue direct procurement relationships with German automotive OEMs seeking KBA-certified functional safety accelerators for autonomous platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among photonic interconnect specialists pursuing co-packaged silicon photonics for exascale training clusters. Long-term viability across the analysis window favors vendors with demonstrated EU AI Act conformity assessment progress and established foundry capacity reservations. Monitor ANSM and KBA alignment timelines as inflection indicators for medical and automotive segment revenue eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Expansion | Domestic CoWoS investments in Arizona reduce lead times for cloud hyperscaler training clusters. |
| EU AI Act Conformity Certification | BSI assessment body engagement secures market access for high-risk medical inference deployments. |
| High-Bandwidth Memory Supply Agreement | Direct HBM3E allocation negotiations with Samsung Foundry match die availability to packaging capacity. |
| Photonic Interconnect Co-Packaging | Silicon photonics integration with compute dies reduces interconnect energy overhead at ten-thousand GPU scale. |
| Chiplet Architecture Standardization | UCIe protocol adoption enables mix-and-match IP blocks for domain-specific accelerator optimization. |
Research Methodology
Coverage spans Taiwan, the United States, China, Germany, and South Korea, with primary inputs from each jurisdiction's foundry ecosystem and regulatory environment. Primary interviews with semiconductor design executives, foundry capacity planning officers, regulatory affairs specialists at medical device manufacturers, and cloud infrastructure procurement leads combined with secondary validation from SEC filings, hyperscaler capex disclosures, EU AI Act implementation guidance, and NMPA certification databases. Bottom-up wafer demand modeling triangulates against top-down AI training cluster deployment estimates.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions modeled include chip type, process node tier, memory integration density, end-use application, and customer procurement scale. CAGRs derive from foundry capacity expansion schedules, hyperscaler infrastructure investment trajectories, and regulatory enforcement timeline assumptions. Industry-specific forecast inputs incorporate extreme ultraviolet lithography equipment delivery schedules and high-bandwidth memory yield progression curves.
Inputs from ASML equipment order backlogs, TSMC revenue disclosures, and cloud operator capital expenditure statements were available through the study window; gaps in Chinese domestic substitution program implementation details introduce uncertainty bands around China market access assumptions. Forecasts reflect documented assumptions regarding EU AI Act conformity assessment body capacity expansion and foundry yield learning curves. A model refresh is warranted upon material change in extreme ultraviolet lithography equipment availability or EU AI Act enforcement timeline acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Citizen Services AI Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market
Artificial Intelligence (AI)
GCC Artificial Intelligence Market
Artificial Intelligence (AI)
Content Automation AI Tools Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
AI Industrial Defect Detection Market
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
United States Artificial Intelligence Market
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Global Deep Learning Neural Networks (Dnns) Market
Artificial Intelligence (AI)
Artificial Intelligence in Robots Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
Generative AI Market
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market
Artificial Intelligence (AI)
Brain Machine Interface Market