
 AI Search Engine Market | 2026-2036
AI Search Engine Market Size, Share, and Industry Trends Forecast 2026-2036
AI Search Engine Market Insights
The EU AI Act is decoupling compliance costs from scale, forcing smaller entrants to absorb disproportionate audit burdens. Google LLC leverages its proprietary tensor processing infrastructure to sustain inference cost advantages across multilingual deployments. Microsoft anchors enterprise demand through deep integration with productivity suites, while Perplexity AI competes on citation transparency and source attribution architecture.
AI search engines are retrieval systems that use neural ranking models, transformer-based encoders, and vector databases to match natural language queries against indexed content with sub-second latency. Their primary commercial purpose is to reduce information discovery friction in high-volume data environments. Cloud-based deployment dominates solution delivery, though edge configurations are gaining traction in latency-sensitive financial trading floors. Natural language processing occupies the largest solution share, while semantic search captures expanding margin pools as enterprises prioritize intent-based over keyword-based retrieval. Enterprise search leads use-case adoption, with knowledge management representing the fastest-expanding segment as hybrid work patterns persist.
The US Federal Trade Commission scrutinizes search algorithm bias under consumer protection statutes, while the EU AI Act mandates risk classification for generative search outputs. China's SAMR enforces algorithmic recommendation transparency rules that extend to AI-curated search results. Stakeholders must monitor divergent jurisdictional requirements for explainability, as compliance architecture designed for one regulatory regime may prove incompatible with another.
Market Dynamics
Transformer-based retrieval architectures are compressing query latency benchmarks while the EU AI Act imposes explainability mandates that fragment compliance architectures across jurisdictions.
Growth Catalysts
- EU AI Act transparency mandates:Risk classification requirements for generative search outputs are accelerating procurement of auditable retrieval systems among European financial institutions.
- Vector database maturation:Sub-second semantic matching capabilities are displacing keyword-indexed enterprise search deployments in legal and healthcare document management.
- Hybrid work persistence:Distributed knowledge retrieval demand is pulling cloud-based neural ranking into mid-market professional services firms previously served by on-premise solutions.
Market Restraints
- Inference cost concentration:Specialized tensor processing hardware dependency locks smaller providers into cloud vendor pricing tiers with limited negotiation leverage.
- Training data licensing friction:Copyright clearance complexity for large-scale web corpora is extending model development timelines and inflating legal overhead.
- Cross-border regulatory incompatibility:Divergent explainability standards between the EU AI Act and China's SAMR algorithmic transparency rules prevent unified product architectures.
Strategic Opportunities
- Edge deployment in financial trading:Latency-sensitive equity and derivatives venues are creating captive infrastructure demand for on-premise neural retrieval systems.
- Convergence with predictive analytics:Integration of ranking models with forecasting engines is opening new procurement budgets within enterprise planning departments.
- India's digitization push:Central government knowledge management modernization is creating tender opportunities for multilingual semantic search platforms.
Industry Challenges
- Retrieval-augmented generation expertise scarcity:The intersection of information retrieval engineering and large language model fine-tuning commands premium compensation that outpaces talent pipeline expansion.
- Legacy system integration complexity:Enterprise content management platforms built on relational database architectures require expensive middleware development for vector database connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Search Engine Market |
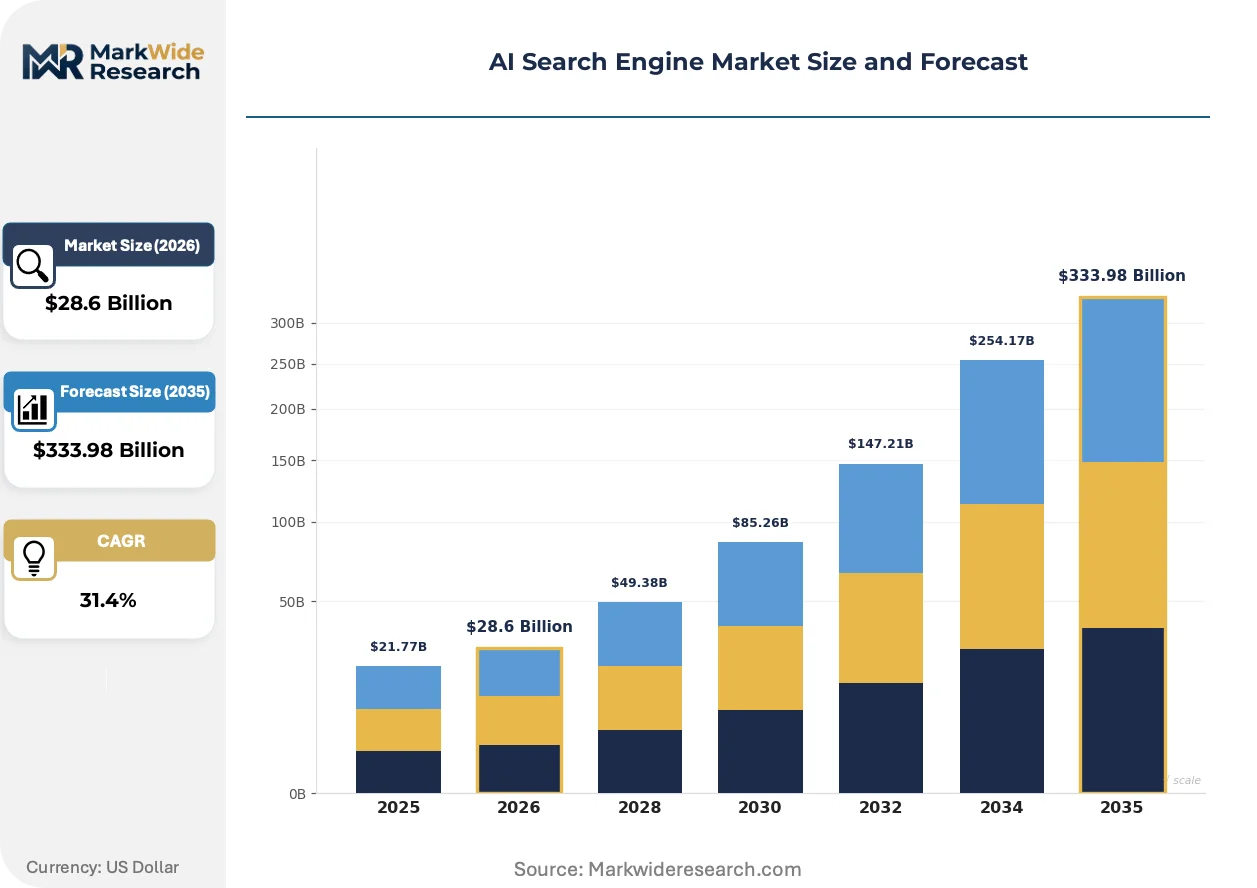
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $333.98 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Solution: Natural Language Processing, Image Recognition, Voice Search, Semantic Search, Predictive Analytics Use Case: Enterprise Search, E-Commerce, Content Discovery, Knowledge Management, Customer Support End User: Financial Institutions, Media & Publishing, Education Providers, Government Agencies, Technology Firms |
| Companies Covered | Google LLC, Microsoft, Amazon Web Services, IBM, Salesforce, Adobe, SAP SE, Oracle, Perplexity AI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Search Engine Market Trends and Innovations
Neural ranking architectures are migrating from cloud-centralized inference to distributed edge configurations as latency requirements tighten across financial and industrial applications.
Multimodal embedding models that fuse text, image, and tabular encoding into unified vector spaces are rewriting retrieval capability expectations. Pharmaceutical regulatory affairs teams are adopting these systems for compound documentation search at twice the pace of general enterprise verticals. The technology is compressing competitive differentiation timelines as open-source implementations erode proprietary model advantages.
The EU AI Act's risk-tiered obligations for generative search outputs are restructuring product development roadmaps. High-risk classification triggers mandatory conformity assessments that extend release cycles by six to nine months. Financial services deployments across Germany, France, and the Netherlands are absorbing these delays through phased rollout strategies that sequence low-risk internal search before customer-facing implementations.
Enterprise procurement of search infrastructure is fragmenting from monolithic platform licensing toward modular component sourcing. Buyers are separately contracting embedding model providers, vector database vendors, and ranking layer specialists. This unbundling is most pronounced in the United States, where technology firms with internal ML engineering capacity prefer best-of-breed assembly over integrated suites.
AI Search Engine Market Segmentation
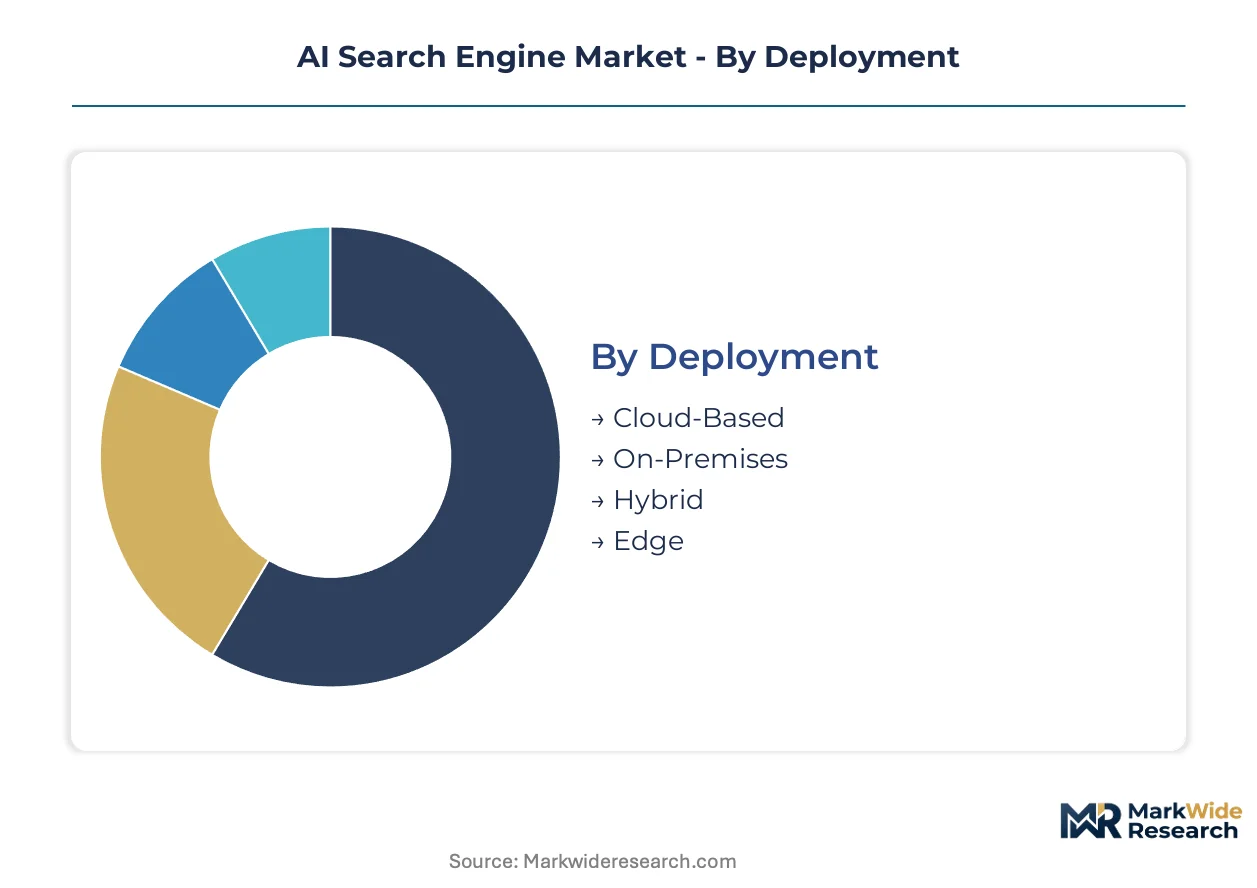
Segmentation in AI search engines reveals how procurement priorities diverge across infrastructure constraints, functional requirements, and regulatory exposure. Deployment architecture decisions cascade through solution selection and use-case prioritization, creating distinct competitive arenas with incompatible vendor qualification criteria.
Deployment:
Cloud-based configurations dominate procurement volumes among mid-market enterprises lacking captive data center capacity, while edge deployments concentrate where millisecond latency determines commercial outcomes.
- Cloud-Based:Multi-tenant inference clusters eliminate capital expenditure barriers for professional services firms scaling semantic search across distributed workforces. Procurement concentrates in the United States among technology firms integrating predictive analytics into internal knowledge management systems, though EU AI Act data residency requirements are fragmenting vendor selection criteria across member states.
- On-Premises:Dedicated tensor processing infrastructure sustains inference cost advantages for high-query-volume financial institutions subject to audit trail mandates. German banking regulators require on-premise deployments for compliance document retrieval systems processing sensitive trading data, creating procurement specifications incompatible with cloud-native alternatives.
- Hybrid:Split architectures route sensitive queries to on-premise vector databases while offloading generic retrieval to cloud inference endpoints. Media conglomerates deploy hybrid configurations to isolate pre-publication content from third-party infrastructure while leveraging cloud scale for archived material search.
- Edge:Sub-10ms latency requirements in equity trading venues demand on-premise neural ranking systems co-located with matching engines. Chicago and London derivatives exchanges specify edge deployments for pre-trade risk check queries, creating captive infrastructure demand resistant to cloud migration.
Mature deployment sits with Cloud-Based configurations. Newer deployment is concentrated in Edge architectures for latency-sensitive financial applications.
Solution:
Functional capability layering determines pricing architecture, with natural language processing commoditizing fastest and predictive analytics commanding premium positioning through integration complexity.
- Natural Language Processing:Transformer-based query encoding has achieved cost parity with legacy keyword indexing across English-language deployments. Technology firms in the United States consume the largest procurement volumes, though open-source encoder availability is compressing vendor differentiation timelines.
- Semantic Search:Intent-based vector matching displaces Boolean retrieval in legal and healthcare document management where query precision directly determines research economics. European financial institutions are accelerating procurement ahead of EU AI Act risk classification deadlines for generative outputs.
- Image Recognition:Multimodal embedding models fuse visual and textual indexing for pharmaceutical regulatory documentation. Patent search applications in Switzerland and Germany consume specialized deployments for molecular structure retrieval.
- Voice Search:Audio query encoding for hands-free industrial environments remains concentrated in Japanese manufacturing facilities with METI-supported voice interface standardization.
- Predictive Analytics:Ranking model integration with forecasting engines opens procurement budgets within enterprise planning departments. Steepest expansion trajectory appears in financial services scenario analysis applications where retrieval augments quantitative modeling.
Revenue concentration sits with Natural Language Processing. Capability expansion is concentrating in Predictive Analytics convergence applications.
Use Case:
Enterprise procurement fragmentation favors modular component sourcing over integrated platform licensing, with knowledge management representing the fastest-expanding budget category.
- Knowledge Management:Hybrid work persistence sustains demand for distributed expertise location systems across mid-market professional services. Cloud-based neural ranking displaces on-premise legacy deployments in accounting and consulting firms previously constrained by capital expenditure approval cycles.
- Enterprise Search:Internal document retrieval for compliance and litigation readiness dominates current procurement volumes among regulated industries. Financial institutions in the United States and Germany specify auditable ranking architectures under FTC and EU AI Act transparency mandates.
- E-Commerce:Product discovery optimization drives procurement among omnichannel retailers seeking to reduce search abandonment. Image-text multimodal retrieval is gaining traction in fashion and home goods verticals where visual similarity matching improves conversion metrics.
- Content Discovery:Media platforms deploy neural ranking for personalized recommendation systems subject to algorithmic transparency requirements. China's SAMR enforcement extends to AI-curated search results, creating compliance architecture specifications distinct from Western markets.
- Customer Support:Automated response retrieval for tier-1 inquiry deflection concentrates in telecommunications and utilities with high query volume, low complexity interaction profiles.
Procurement maturity sits with Enterprise Search. Budget expansion is concentrating in Knowledge Management as hybrid work patterns persist.
End User:
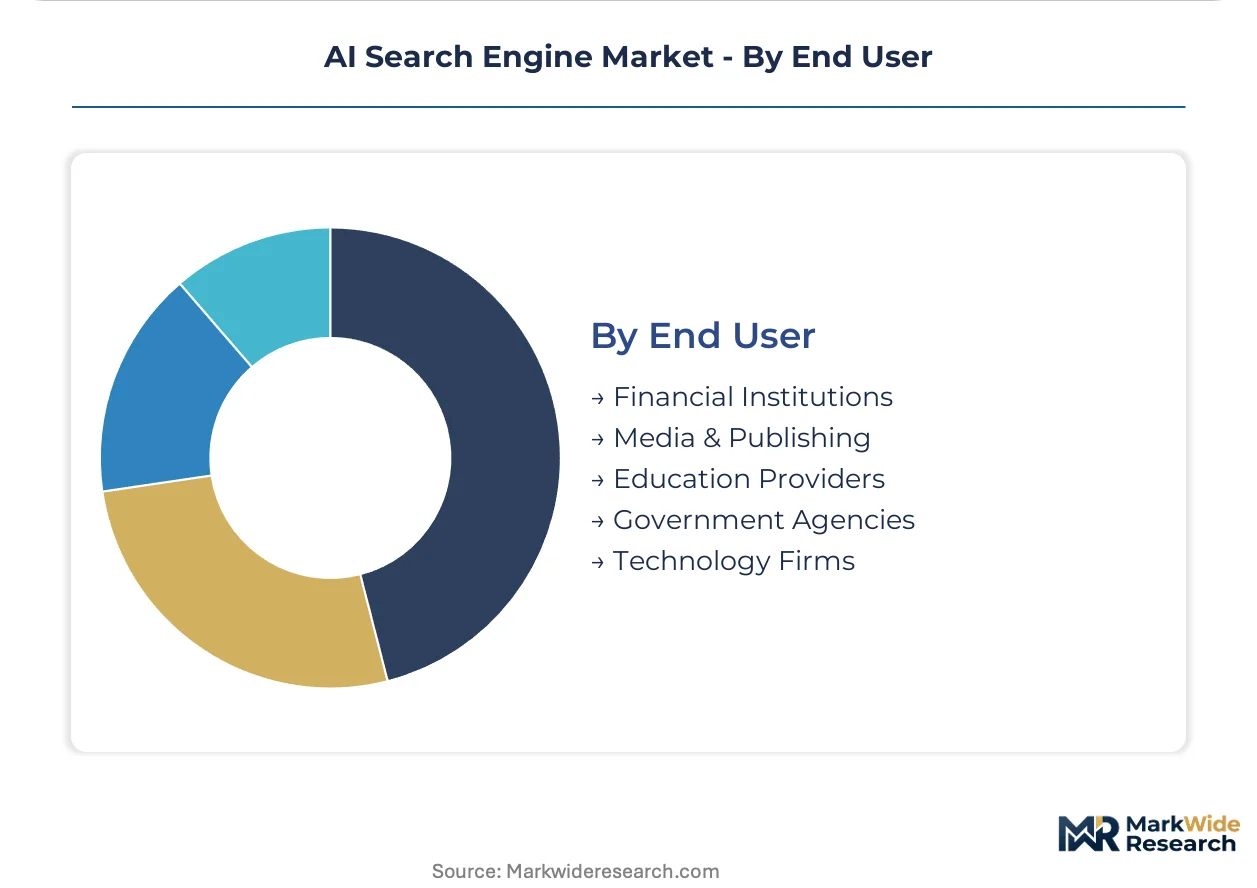
Industry-specific regulatory exposure and data sensitivity create incompatible vendor qualification requirements that fragment competitive positioning across verticals.
- Financial Institutions:Semantic search for compliance document retrieval absorbs disproportionate audit burden under EU AI Act risk-tiered obligations. German, French, and Dutch banks are sequencing phased rollouts to manage six-to-nine-month conformity assessment delays for customer-facing implementations.
- Government Agencies:India's central government knowledge management modernization is creating tender opportunities for multilingual semantic search platforms. Procurement specifications emphasize Indic language encoder performance and domestic data residency.
- Technology Firms:Internal ML engineering capacity in the United States drives preference for best-of-breed component assembly over integrated suites. Unbundled procurement separates embedding model, vector database, and ranking layer contracting.
- Media & Publishing:Pre-publication content isolation requirements favor hybrid deployment architectures with sensitive material retained on-premise. Citation transparency specifications are emerging as a competitive differentiator in newsroom research tool procurement.
- Education Providers:Academic licensing models for large-scale corpus search face training data copyright clearance complexity extending procurement timelines. University library consortia negotiate collective licensing for scholarly content indexing.
Regulatory complexity sits with Financial Institutions. Procurement momentum is concentrating in Government Agencies with digitization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bengaluru and Hyderabad concentrate AI search engine development through software technology park incentives and dedicated data center corridors. These zones attract multinational R&D centers alongside domestic startups.
United States
Technology firms in Silicon Valley and Seattle integrate predictive analytics into internal knowledge management systems, driving procurement of cloud-based neural ranking. The FTC scrutinizes search algorithm bias under consumer protection statutes. Enterprise adoption concentrates in San Francisco Bay Area financial services firms deploying semantic search for compliance document retrieval.
Germany
Financial institutions in Frankfurt and Munich absorb disproportionate audit burdens under EU AI Act risk-tiered obligations for generative search outputs. German banking regulators mandate on-premise deployments for compliance document retrieval systems processing sensitive trading data. Phased rollout strategies sequence low-risk internal search before customer-facing implementations.
China
SAMR enforces algorithmic recommendation transparency rules extending to AI-curated search results, creating compliance architecture specifications distinct from Western markets. Technology development clusters in Beijing and Shenzhen drive multimodal embedding model research. Domestic cloud providers compete with international vendors for enterprise knowledge management contracts.
India
Central government knowledge management modernization creates tender opportunities for multilingual semantic search platforms. Procurement specifications emphasize Indic language encoder performance and domestic data residency requirements. Development activity concentrates in Bengaluru and Hyderabad special economic zones with software technology park incentives.
United Kingdom
Enterprise procurement fragments toward modular component sourcing, with technology firms in London preferring best-of-breed assembly over integrated suites. The Information Commissioner's Office intersects with emerging AI governance frameworks for search transparency. Financial services in the City of London deploy hybrid architectures routing sensitive queries to on-premise vector databases.
AI Search Engine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered competitive positions. Cloud infrastructure providers leverage captive tensor processing hardware to sustain inference cost advantages. Three archetypes dominate: hyperscale platform integrators, specialized retrieval engine developers, and enterprise productivity suite anchors. M&A activity concentrates on vector database acquisitions and embedding model startups, while geographic expansion targets India's digitization tenders and EU compliance-ready deployments.
Within the hyperscale tier, Google LLC and Microsoft exemplify divergent strategic positioning. Google leverages proprietary infrastructure for multilingual deployment scale, while Microsoft anchors enterprise demand through productivity suite integration. Perplexity AI occupies a distinct specialist position, competing on citation transparency architecture rather than infrastructure scale.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft |
| Amazon Web Services |
| IBM |
| Salesforce |
| Adobe |
| SAP SE |
| Oracle |
| Perplexity AI |
| Others |
Pricing and Supply Chain Analysis
Specialized tensor processing hardware pricing indices cascade through AI search engine supply chains, compressing margins for cloud-dependent providers while concentrating pricing power among captive infrastructure owners. This cost structure stratifies procurement tiers across enterprise buyers with divergent latency tolerances and compliance exposure.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations, with financial trading venues absorbing surcharges for sub-10ms edge deployments while mid-market professional services secure spot discounts on standardized cloud inference. Three-tier pricing structure across premium, standard, and economy levels reflects deployment architecture complexity, with on-premise tensor processing clusters commanding highest positioning. Cost compression in cloud-native tiers is intensifying because hyperscaler volume leverage locks smaller providers into rigid pricing schedules. Technology firms with internal ML engineering capacity demonstrate least price sensitivity, while mid-market accounting and consulting firms exhibit acute responsiveness to subscription tier adjustments.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan Semiconductor Manufacturing capacity for advanced tensor processing units, constraining inference hardware availability for specialized retrieval engine developers. Supply concentration centers on Taiwan, South Korea, and the United States for neural accelerator fabrication, while vector database software development clusters in the United States, Germany, and India. Raw material dependencies encompass high-bandwidth memory modules, silicon photonics components, and rare earth elements for magnetics in cooling systems. Tariff exposure on semiconductor equipment imports threatens cost predictability for European edge deployment specialists. Distribution runs through hyperscaler marketplaces, direct enterprise sales forces, and systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vector database architectures are displacing legacy keyword-indexed enterprise search deployments, creating asymmetric opportunity windows across infrastructure ownership models and regulatory compliance readiness.
For Market Incumbents: Hedge against open-source encoder commoditization by deepening proprietary tensor processing infrastructure moats and accelerating EU AI Act conformity assessment pre-certification. Vertical integration into vector database kernel optimization preserves margin structure against unbundled component sourcing trends. Capacity addition in India's special economic zones captures tender momentum from central government digitization mandates. For New Entrants and Emerging Players: Begin with edge deployment configurations for Chicago and London derivatives exchanges, where latency specifications exclude hyperscale incumbents from qualification. India's multilingual semantic search modernization presents the most penetrable geography, with domestic data residency requirements favoring local partnership structures. Channel strategy should emphasize systems integrators with existing financial services compliance expertise. For Investors and Strategic Acquirers: The window for entry favors retrieval-augmented generation engineering specialists with demonstrated financial trading floor deployments. Long-term viability hinges on regulatory architecture adaptability across EU AI Act and SAMR jurisdictions. Watch for inflection in pharmaceutical regulatory affairs team procurement velocity for multimodal embedding platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Vector Database Acquisition | Consolidates embedding storage capabilities essential for sub-second semantic matching in financial compliance retrieval. |
| EU AI Act Conformity Pre-Certification | Accelerates procurement cycles among German, French, and Dutch banking institutions facing six-to-nine-month assessment delays. |
| Edge Deployment Partnership | Captures captive infrastructure demand from Chicago and London derivatives exchanges specifying sub-10ms latency. |
| Multilingual Encoder Development | Qualifies vendors for India's central government knowledge management tenders emphasizing Indic language performance. |
| Predictive Analytics Integration | Opens enterprise planning department budgets through ranking model convergence with forecasting engines. |
Research Methodology
Document review covered hyperscaler capex disclosures, EU regulatory filings, and vector database vendor technical specifications, complemented by interviews with CTOs at financial services firms, IT procurement officers at professional services organizations, platform engineers at cloud infrastructure providers, and integration specialists serving regulated industries. Secondary validation drew from SEC filings, SAMR algorithmic transparency enforcement notices, and Indian government tender databases. Bottom-up deployment volume estimates triangulated against top-down enterprise software spending benchmarks.
Market size outputs reflect segmentation across deployment architecture, solution capability layer, use-case priority, and end-user vertical, with growth trajectories derived from procurement cycle analysis and regulatory deadline mapping across the projection horizon. Modeled dimensions encompass cloud versus edge infrastructure, natural language processing versus predictive analytics solution types, and financial institution versus government agency end-user categories. CAGRs incorporate technology substitution curves for semantic search displacing Boolean retrieval and phased rollout sequencing under EU AI Act risk classifications.
Underlying measurement precision varies by segment; cloud-based deployment volumes carry tighter precision than edge configurations given hyperscaler disclosure practices. Forecasts reflect assumptions regarding EU AI Act enforcement consistency, tensor processing hardware supply continuity, and enterprise hybrid work persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI in Robotics Market
Artificial Intelligence (AI)
AI Consulting Services Market
Artificial Intelligence (AI)
AI in Fashion Market
Artificial Intelligence (AI)
Autonomous Agents Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
MENA Artificial Intelligence Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
NLP in Healthcare and Life Sciences Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market
Artificial Intelligence (AI)
Europe Artificial Intelligence Market
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
Artificial Intelligence in Big Data Analysis Market