
 Conversation Intelligence Software Market | 2026-2036
Conversation Intelligence Software Market Size, Share, and Industry Trends Forecast 2026-2036
Conversation Intelligence Software Market Analysis
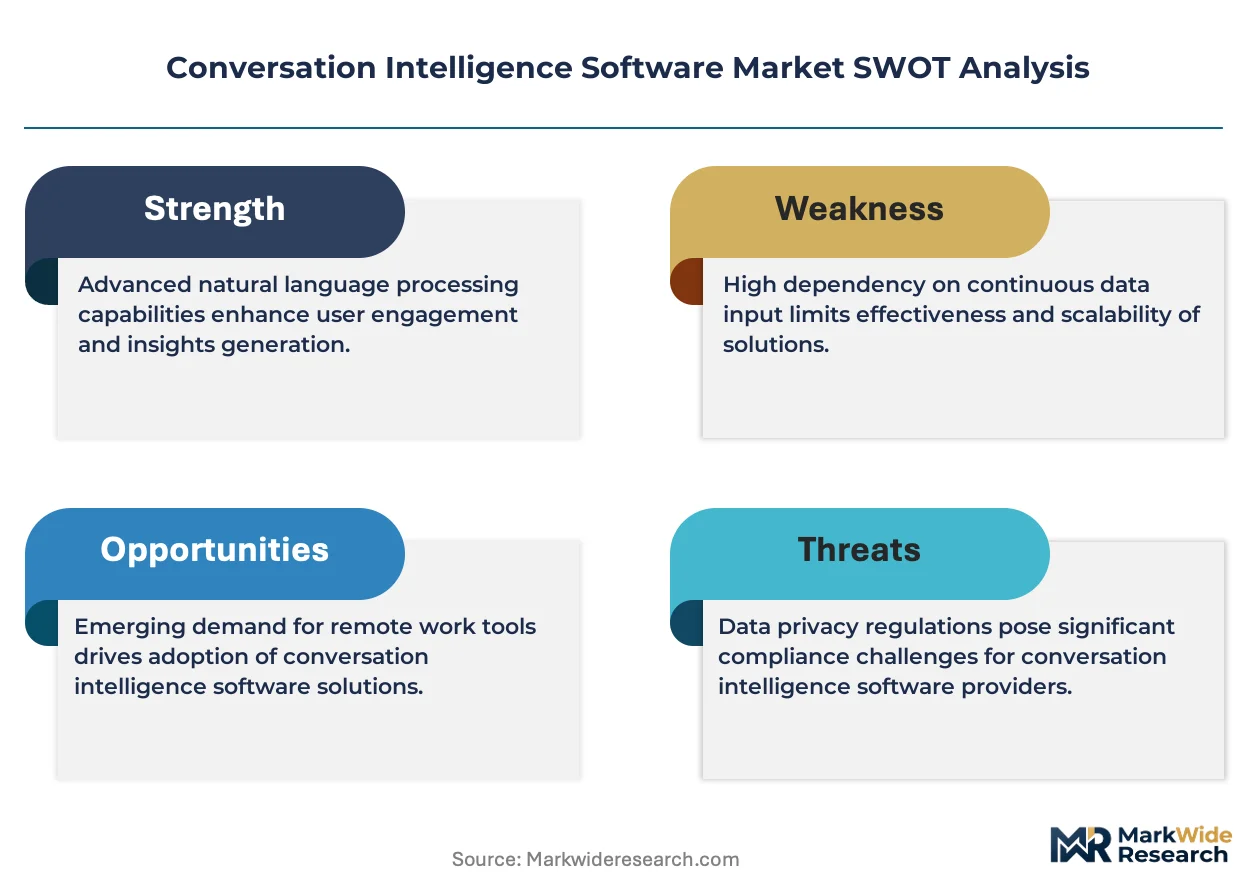
The capability gap between AI-native platforms and legacy call-recording tools is bifurcating competitive dynamics in conversation intelligence. Gong leverages proprietary machine learning models to dominate enterprise sales coaching workflows. Salesloft anchors its position through deep CRM integration and revenue-operations alignment. Observe.AI specializes in real-time agent assistance for customer support environments, differentiating through vertical-specific compliance features.
Conversation intelligence software captures, transcribes, and analyzes voice and video interactions using natural language processing and speaker-diarization algorithms to extract sentiment, intent, and actionable coaching signals. Speech analytics and transcription services lead solution-type adoption, while cloud-based and SaaS deployment models capture the fastest growth as enterprises abandon on-premise infrastructure. CRM integration represents the highest-margin integration tier, with API accessibility expanding among mid-market buyers seeking modular stack architectures.
GDPR and the EU AI Act shape European data residency and algorithmic transparency requirements, while HIPAA governs healthcare-provider deployments in the United States. The Federal Communications Commission's evolving stance on AI-generated content disclosure influences how vendors architect real-time coaching overlays. Stakeholders must monitor regulatory divergence across jurisdictions to calibrate product compliance investments against geographic expansion priorities.
Market Dynamics
The bifurcation between AI-native conversation intelligence platforms and legacy call-recording infrastructure is compressing vendor margins while accelerating enterprise migration toward real-time analytics stacks. This structural force rewards vendors with proprietary NLP pipelines and punishes those dependent on third-party transcription APIs.
Growth Catalysts
- GDPR-Compliant Cloud Migration:European financial services firms are replacing on-premise recording systems with SaaS platforms that embed automated data-residency controls and algorithmic transparency dashboards required under the EU AI Act.
- Real-Time Agent Assistance:Customer support operations in telecommunications and insurance are deploying streaming NLP to surface contextual guidance during live calls, reducing average handle time and compliance violations simultaneously.
- Sales Coaching Automation:Enterprise revenue operations teams are integrating conversation intelligence directly into CRM workflows to automate deal-risk scoring and rep-performance benchmarking without manual call review.
Market Restraints
- GPU Compute Cost Volatility:Training and inference for large language models underlying sentiment analysis and intent classification depends on NVIDIA datacenter chip availability, with pricing swings compressing vendor gross margins unpredictably.
- Transcription API Concentration:Three providers control the majority of enterprise-grade speech-to-text infrastructure, creating supplier power asymmetries for mid-tier conversation intelligence vendors without in-house acoustic models.
- HIPAA Compliance Friction:Healthcare-provider deployments require Business Associate Agreements with every subprocesser handling protected health information, extending sales cycles and legal review costs substantially.
Strategic Opportunities
- India BPO Expansion:Indian business process outsourcing firms serving North American and European clients represent an underpenetrated channel for real-time coaching tools that improve accent neutrality and script adherence.
- Revenue Operations Convergence:Bundling conversation intelligence with forecast automation and pipeline analytics creates stickier platform relationships than standalone call analytics.
- FCC AI Disclosure Rules:Proposed Federal Communications Commission mandates for bot-identification in consumer calls will force vendors to architect real-time disclosure overlays, creating first-mover advantage for compliant platforms.
Industry Challenges
- Prompt Engineering Talent Scarcity:Vendors struggle to hire specialists capable of tuning retrieval-augmented generation systems for domain-specific sales and support vocabularies without hallucination.
- CRM Integration Complexity:Enterprise buyers demand bidirectional synchronization with Salesforce, HubSpot, and Microsoft Dynamics, requiring dedicated engineering teams and certification maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conversation Intelligence Software Market |
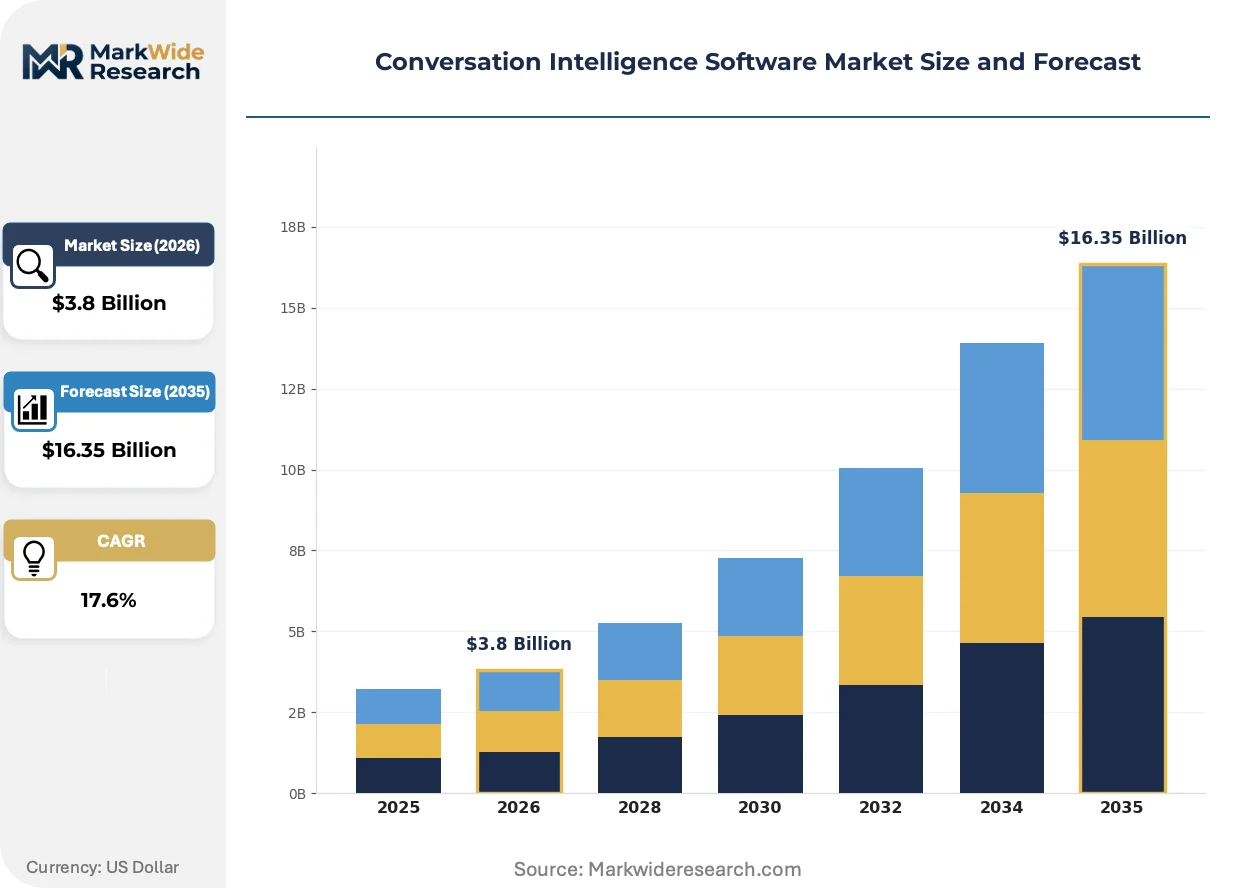
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Speech Analytics, Call Recording, Transcription Services, Data Visualization Deployment Model: On-premise, Cloud-based, Hybrid, SaaS End User: Customer Support, Sales Teams, Marketing Departments, Healthcare Providers Integration Level: CRM Integration, API Accessibility, Data Warehouse, Communication Platform |
| Companies Covered | Gong, Jiminny, Salesloft, Avoma, Observe.AI, Fathom, Chorus by ZoomInfo, Fireflies.ai, Echo AI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conversation Intelligence Software Market Emerging Trajectories
Foundation-model architectures are compressing the capability gap between specialized conversation intelligence vendors and general-purpose AI platforms, forcing differentiation through vertical data moats and workflow integration depth.
Multimodal foundation models that process audio, text, and video simultaneously are supplanting pipeline architectures that handled transcription, diarization, and analysis as discrete steps. Enterprise buyers in technology and financial services are piloting these unified systems for deal-review automation and regulatory examination preparation. The structural consequence is collapsing vendor differentiation previously built on proprietary acoustic models, compressing pricing power for transcription-centric offerings.
The EU AI Act's risk-classification framework for biometric and emotion-recognition systems is forcing vendors to rearchitect sentiment-scoring algorithms deployed in European call centers. Systems flagged as high-risk must undergo conformity assessment and maintain human-in-the-loop oversight, increasing compliance costs. Vendors are responding by segmenting product roadmaps, stripping emotion-detection features from EU-deployed instances while retaining them for US and Asia-Pacific markets.
Buyer preference is pivoting from perpetual licenses toward consumption-based pricing indexed to analyzed conversation volume. Mid-market SaaS companies and regional banks are rejecting seat-based models in favor of metered contracts that align vendor compensation with platform utilization. This shift is most visible in the United States, where procurement teams in private equity-backed portfolio companies prioritize variable cost structures that preserve EBITDA flexibility.
Conversation Intelligence Software Market Segmentation
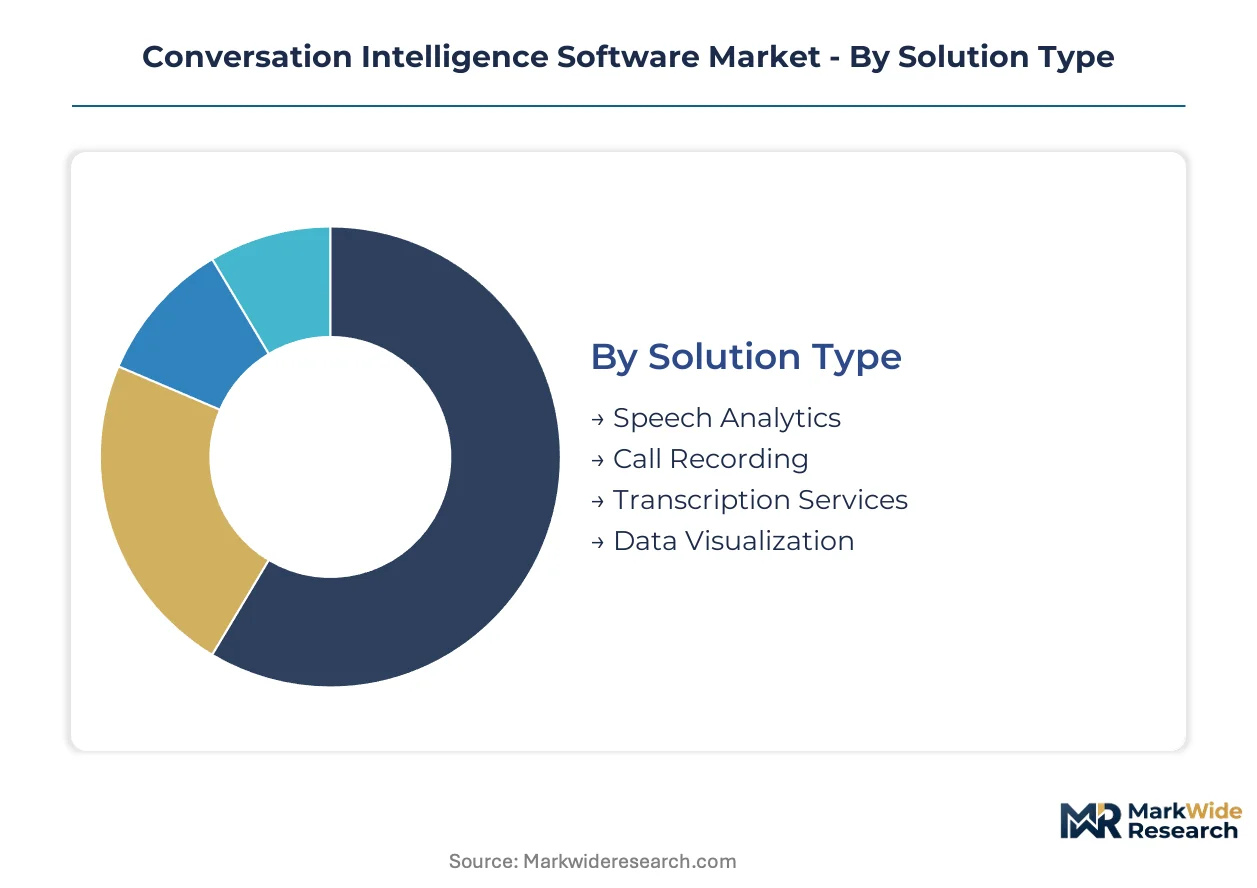
Segmentation in conversation intelligence software reveals how procurement patterns diverge across technical sophistication levels and regulatory exposure. Buyers prioritize different solution architectures based on whether they seek real-time coaching, compliance documentation, or revenue optimization.
Solution Type:
Speech analytics and transcription services flow through direct enterprise sales channels with professional services attachment, while call recording and data visualization segments distribute more heavily through telecom systems integrators and CRM marketplace listings.
- Speech Analytics:Natural language processing engines detect sentiment shifts, talk ratios, and competitive mentions during live or recorded conversations. Financial services firms in the United States deploy these tools for regulatory examination preparation and conduct surveillance.
- Transcription Services:Speaker-diarization algorithms separate multiple voices with timestamp precision, enabling searchable call archives. European deployments under GDPR require automated data-residency controls and algorithmic transparency dashboards that increase implementation complexity.
- Call Recording:Capture infrastructure for quality assurance and dispute resolution.
- Data Visualization:Dashboard layers translating conversation metrics into coaching workflows and pipeline risk scores.
By volume, speech analytics leads. By growth pace, transcription services are gaining share fastest as multimodal foundation models collapse previously separate pipeline steps.
Deployment Model:
Cost tiering separates these segments: SaaS and cloud-based options target mid-market buyers seeking variable cost structures, while on-premise and hybrid deployments serve regulated industries with captive infrastructure investments.
- Cloud-based:Scalable compute for training and inference without datacenter capital expenditure. GDPR-compliant cloud migration among European financial services firms is accelerating replacement of legacy recording systems.
- SaaS:Metered pricing indexed to analyzed conversation volume aligns vendor compensation with platform utilization. Private equity-backed portfolio companies in the United States favor this model for EBITDA flexibility.
- On-premise:Captive infrastructure for HIPAA-governed healthcare providers requiring Business Associate Agreements with every subprocessor.
- Hybrid:Split architectures preserving sensitive data locally while leveraging cloud analytics for non-regulated workloads.
By installed base, on-premise retains the largest footprint. By expansion trajectory, SaaS is climbing the fastest as procurement teams reject perpetual licenses.
End User:
Application urgency varies sharply: sales teams and customer support operations demand real-time capabilities, while marketing and healthcare users prioritize batch analysis and audit trails.
- Sales Teams:Revenue operations integrate conversation intelligence into CRM workflows for automated deal-risk scoring and rep-performance benchmarking. Enterprise technology firms deploy these tools at scale for coaching automation.
- Customer Support:Streaming NLP surfaces contextual guidance during live calls, reducing average handle time and compliance violations simultaneously in telecommunications and insurance operations.
- Marketing Departments:Voice-of-customer analysis for campaign optimization and competitive positioning.
- Healthcare Providers:Clinical documentation and patient interaction analysis under HIPAA constraints.
By deployment count, customer support leads. By technology investment intensity, sales teams are expanding most quickly.
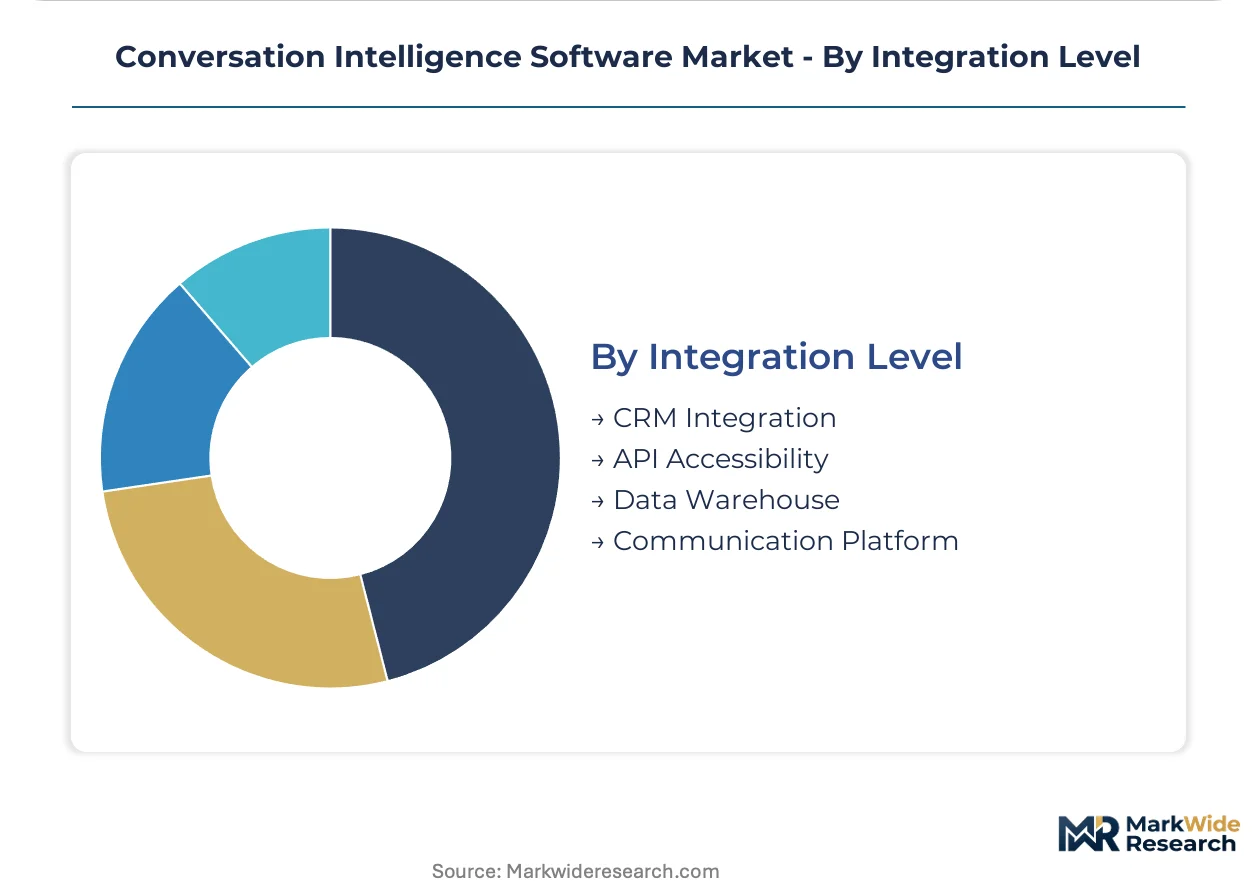
Integration Level:
Margin structure correlates with integration depth: CRM integration commands premium pricing, while API accessibility serves price-sensitive mid-market buyers building modular stacks.
- CRM Integration:Bidirectional synchronization with Salesforce, HubSpot, and Microsoft Dynamics requires dedicated engineering teams and certification maintenance. This tier captures the highest margins in the integration hierarchy.
- API Accessibility:RESTful endpoints enabling custom workflow embedding without native platform dependency. Mid-market SaaS companies favor this approach for stack architecture flexibility.
- Data Warehouse:Bulk export pipelines for enterprise analytics environments.
- Communication Platform:Native embedding within Zoom, Microsoft Teams, and telephony infrastructure.
By revenue concentration, CRM integration leads. By adoption velocity, API accessibility is expanding most quickly among developer-centric buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in India exhibit the highest price elasticity, driving rapid API-accessible adoption, while United States financial services firms absorb premium CRM-integrated deployments with minimal procurement friction.
United States
Large technology and financial services firms deploy conversation intelligence at scale for sales coaching automation and regulatory examination preparation. HIPAA governs healthcare-provider deployments, requiring Business Associate Agreements with every subprocessor handling protected health information. Silicon Valley and New York Metro clusters concentrate vendor engineering teams and enterprise sales operations.
Germany
Automotive and industrial conglomerates demand GDPR-compliant cloud migration with automated data-residency controls. The EU AI Act's risk-classification framework forces rearchitecture of sentiment-scoring algorithms for high-risk biometric systems. Munich and Frankfurt financial centers anchor early adoption of algorithmic transparency dashboards.
United Kingdom
Private equity-backed SaaS companies favor metered pricing models that preserve EBITDA flexibility through variable cost structures. The Information Commissioner's Office enforces GDPR-aligned algorithmic accountability requirements. London's fintech corridor drives demand for real-time coaching tools integrated into revenue operations workflows.
India
Business process outsourcing firms serving North American and European clients represent an underpenetrated channel for accent neutrality and script adherence tools. TRAI regulations govern telecommunications infrastructure without specific AI disclosure mandates. Bangalore and Hyderabad technology parks concentrate vendor development centers and pilot deployments.
Japan
Enterprise buyers pilot multimodal foundation models for deal-review automation and customer support quality assurance. METI guidelines shape AI governance expectations for emotion-recognition deployments. Tokyo's financial district and Osaka manufacturing hubs drive conservative adoption patterns favoring proven integration architectures.
Conversation Intelligence Software Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with AI-native platforms commanding premium pricing against API-dependent challengers. The vendor base stratifies across three tiers: proprietary NLP pipeline owners, third-party transcription integrators, and vertical-specialist compliance platforms. Dominant competitive moves include CRM certification maintenance and multimodal foundation model licensing partnerships.
Within the AI-native tier, Gong and Observe.AI exemplify divergent specialization strategies—Gong anchoring enterprise sales coaching workflows, Observe.AI occupying real-time agent assistance for customer support environments. Salesloft represents the revenue-operations convergence archetype through deep CRM integration. Jiminny and Avoma sit within the mid-market accessibility segment, emphasizing modular stack architectures for price-sensitive buyers.
| Leading Market Players |
|---|
| Gong |
| Jiminny |
| Salesloft |
| Avoma |
| Observe.AI |
| Fathom |
| Chorus by ZoomInfo |
| Fireflies.ai |
| Echo AI |
| Others |
Supply Flow & Price Mechanics
Third-party transcription API substitution for in-house acoustic models is redrawing supply geography toward NVIDIA-dependent cloud regions while compressing gross margins for vendors lacking proprietary NLP pipelines.
Pricing Analysis
Professional services and extended implementation contracts drive lifetime value beyond base SaaS subscriptions. Metered pricing indexed to analyzed conversation volume dominates, with premium-mid-economy pricing differentiation separating CRM-integrated enterprise tiers from API-accessible mid-market offerings. Cost compression in the mid-market tier intensifies as buyers reject seat-based models in favor of variable structures. Private equity-backed portfolio companies exhibit the highest price sensitivity, while United States financial services firms absorb premium deployments with minimal procurement friction.
Supply Chain Analysis
Just-in-time compute provisioning prevails among SaaS-native vendors, while strategic stockpiling of NVIDIA datacenter capacity characterizes enterprise-scale platform operators. Cloud infrastructure concentrates in the United States, Ireland, and Singapore, where GDPR-aligned data residency frameworks govern European deployments. The supply chain draws from specialized GPU foundries, third-party speech-to-text providers, and hyperscaler compute networks. Single-source vulnerability in NVIDIA chip availability creates pricing volatility for training and inference workloads. Distribution runs through direct enterprise sales channels with professional services attachment, supplemented by CRM marketplace listings for modular buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conversation intelligence functions as a service-attach opportunity where ongoing coaching automation and compliance monitoring subscriptions expand faster than initial platform licensing.
For Market Incumbents: Shield proprietary NLP pipeline advantages through continued R&D investment in multimodal foundation models, defending against general-purpose AI platform encroachment. Deepen CRM certification maintenance with Salesforce, HubSpot, and Microsoft Dynamics to lock in revenue-operations workflows. GPU compute cost volatility represents the primary margin pressure point requiring strategic cloud capacity commitments.
For New Entrants and Emerging Players: Lead with India BPO channel penetration, where accent neutrality and script adherence tools remain underdeployed among business process outsourcing firms serving North American and European clients. Target mid-market SaaS companies seeking API-accessible stack architectures with consumption-based pricing. Partner with telecom systems integrators for downstream distribution leverage.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors AI-native platforms with vertical data moats over API-dependent transcription integrators. Long-term viability hinges on workflow integration depth rather than standalone analytics capability. Monitor EU AI Act enforcement intensity as the signal to watch for geographic expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Multimodal Foundation Model Licensing | Unified audio-text-video processing collapses pipeline steps, threatening transcription-centric vendor differentiation. |
| GDPR-Compliant Cloud Migration | Automated data-residency controls unlock European financial services replacement cycles for legacy recording systems. |
| CRM Integration Certification | Bidirectional synchronization with Salesforce and HubSpot commands premium pricing and reduces churn. |
| Real-Time Coaching Overlay Architecture | FCC AI disclosure compliance creates first-mover advantage for platforms with built-in bot-identification capabilities. |
| Revenue Operations Convergence | Bundling conversation intelligence with forecast automation creates stickier platform relationships than standalone call analytics. |
Methodological Framework
The analysis maps speech analytics, transcription services, call recording, and data visualization segments, each validated through revenue operations leaders, customer support directors, CRM integration specialists, and compliance officers at financial services and healthcare providers. Primary interview insights triangulate against SEC filings from publicly traded vendors, hyperscaler capex disclosures, CRM marketplace data, and EU regulatory guidance documents. Bottom-up deployment counts and top-down enterprise spending estimates cross-validate market sizing.
Consistency checks against external benchmarks validate projection outputs across the modeling period. Segmentation dimensions include deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derive from trend extrapolation adjusted for technology substitution effects and regulatory implementation timelines. Forecast inputs incorporate GPU availability assumptions and CRM platform penetration rates.
Forecasts assume regulatory continuity in GDPR enforcement and FCC rulemaking; material policy shifts would require re-modeling sentiment-scoring algorithm deployment feasibility. Revision becomes warranted when EU AI Act high-risk system classification thresholds or NVIDIA supply allocation protocols cross material disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global AI in Social Media Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
Artificial Intelligence Platform Market
Artificial Intelligence (AI)
AI Industrial Defect Detection Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market
Artificial Intelligence (AI)
Autonomous Agents Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Retail Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
AI in Robotics Market
Artificial Intelligence (AI)
Robotic Vision Market
Artificial Intelligence (AI)
Artificial Intelligence Oven Market
Artificial Intelligence (AI)
Generative AI in Coding Market
Artificial Intelligence (AI)
AI Mirror Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market
Artificial Intelligence (AI)
Synthetic Data Generation Market