
 Home AI Oven Market | 2026-2036
Home AI Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Home AI Oven Market Insights
Embedded systems engineering talent is reorganizing competitive dynamics across the Home AI Oven landscape, with appliance manufacturers racing to secure scarce AI firmware developers and thermal sensor specialists. Samsung Electronics leverages its semiconductor supply chain to integrate proprietary neural processing units directly into oven control boards. Bosch anchors European demand through its industrial-grade temperature calibration protocols inherited from commercial baking equipment. Haier competes on manufacturing scale, operating some of the largest automated appliance assembly facilities serving Asia-Pacific markets.
A home AI oven constitutes an electric cooking appliance integrating artificial intelligence algorithms with thermal management systems, typically incorporating multi-spectral food recognition cameras, precision thermocouples accurate to within 0.5 degrees Celsius, and cloud-connected recipe databases to automate cooking parameters. Its primary commercial purpose centers on reducing user intervention while improving consistency in residential meal preparation. Smart ovens currently lead volume shipments as the default configuration for connected kitchen ecosystems, while machine learning-enabled units command the strongest margin pools due to their adaptive cooking refinement capabilities. Voice recognition technology is maturing fastest as a commodity feature, whereas IoT connectivity remains the critical infrastructure layer determining platform loyalty and aftermarket service revenue.
The EU Green Deal and F-Gas Regulation constrain refrigerant and insulation material choices for ovens with steam-combi functions, while the FDA's food contact substance notifications govern sensor materials that interact with cooking surfaces. CE marking requirements under the EU AI Act are beginning to impose algorithmic transparency obligations on automated cooking decision systems. Stakeholders must monitor whether national energy labeling schemes expand to include AI-driven standby power consumption before committing to regional product line configurations.
Market Dynamics
Embedded neural processing hardware is compressing development cycles across appliance control systems, forcing manufacturers to restructure firmware teams around real-time thermal inference capabilities rather than conventional PID-based architectures.
Growth Catalysts
- EU Green Deal energy mandates:Standby power regulations under the EU Green Deal are accelerating replacement demand for conventional ovens with AI-optimized thermal management systems in Germany, France, and Italy.
- Multi-spectral imaging convergence:Food recognition cameras combining visible and near-infrared wavelengths are enabling automated doneness detection without user calibration, pulling adoption among precision-cooking enthusiasts.
- Cloud recipe platform economics:Subscription-based recipe databases are generating recurring revenue streams that subsidize hardware margins and lock users into ecosystem-specific appliance purchases.
Market Restraints
- Semiconductor supply concentration:Neural processing units for edge AI inference depend on TSMC and Samsung foundry capacity concentrated in Taiwan and South Korea, creating single-source vulnerability.
- F-Gas Regulation material constraints:The EU F-Gas Regulation restricts hydrofluorocarbon-based insulation foams used in steam-combi oven variants, forcing costly material reformulation.
- Technical ceiling on sensor fusion:Current thermocouple-camera fusion algorithms struggle with reflective cookware surfaces, limiting reliability across stainless steel and copper vessel types.
Strategic Opportunities
- India smart kitchen penetration:BIS certification alignment and PLI scheme incentives for electronics manufacturing are opening white space for AI oven localization in Mumbai and Bangalore residential developments.
- Health-condition-specific meal automation:Diabetes and renal diet protocols represent emerging application segments where AI-driven macro-nutrient preservation commands premium positioning.
- Voice-IoT convergence:Integration with Matter protocol ecosystems is creating distribution advantages through smart home platform bundling with Amazon Alexa and Google Home hubs.
Industry Challenges
- Firmware talent scarcity:Real-time embedded AI development requires rare combinations of thermal physics and neural network optimization expertise, elongating product development timelines.
- CE marking algorithmic transparency:EU AI Act documentation requirements for automated cooking decisions are extending certification cycles by 8-14 months for first-mover products.
- Legacy kitchen electrical infrastructure:Older residential circuits in established markets lack 240V/40A capacity for high-power AI ovens with rapid pre-heat functions, complicating retrofit sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home AI Oven Market |
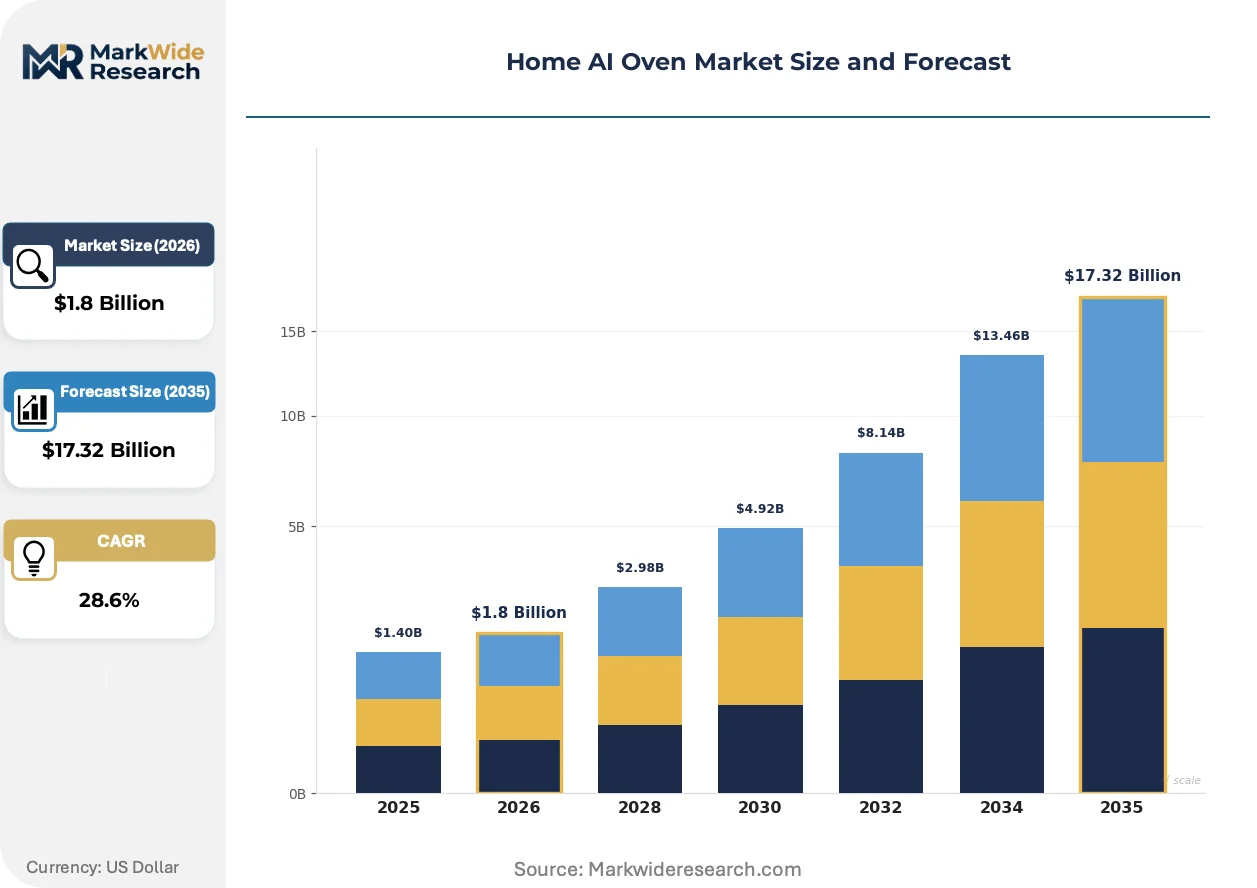
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Ovens, Conventional Ovens, Multi-Function Ovens, Countertop Ovens Technology: Voice Recognition, Machine Learning, IoT Connectivity, Touchscreen Interface End User: Homeowners, Chefs, Renters, Food Enthusiasts Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Bosch, LG Electronics, Electrolux Group, Haier, Samsung Electronics, Siemens, Midea, Whirlpool, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home AI Oven Market Trends and Innovations
Thermal sensor architectures and regulatory disclosure frameworks are converging to reshape how manufacturers differentiate AI cooking systems. Three developments are compressing competitive timelines.
Multi-spectral camera modules are miniaturizing from 12mm to 4mm form factors while maintaining 1080p resolution. Appliance OEMs are embedding these sensors directly into oven door frames rather than deploying bulky overhead mounts. This sensor miniaturizing is collapsing the physical distinction between premium and mid-tier product lines, forcing margin compression in previously protected price bands.
The EU AI Act's algorithmic transparency requirements for automated decision systems are mandating technical documentation for cooking parameter selection logic. Manufacturers must now maintain version-controlled explainability records for neural network weight updates. European importers are responding by establishing dedicated regulatory affairs teams in Brussels to pre-clear CE marking submissions.
Direct-to-consumer subscription bundling is displacing traditional retail channel dependence. Manufacturers are offering hardware-plus-recipe-service packages through proprietary apps, bypassing big-box electronics retailers. This channel shift is most visible in China and the United States, where smart home platform loyalty exceeds brand loyalty for standalone appliances.
Home AI Oven Market Segmentation
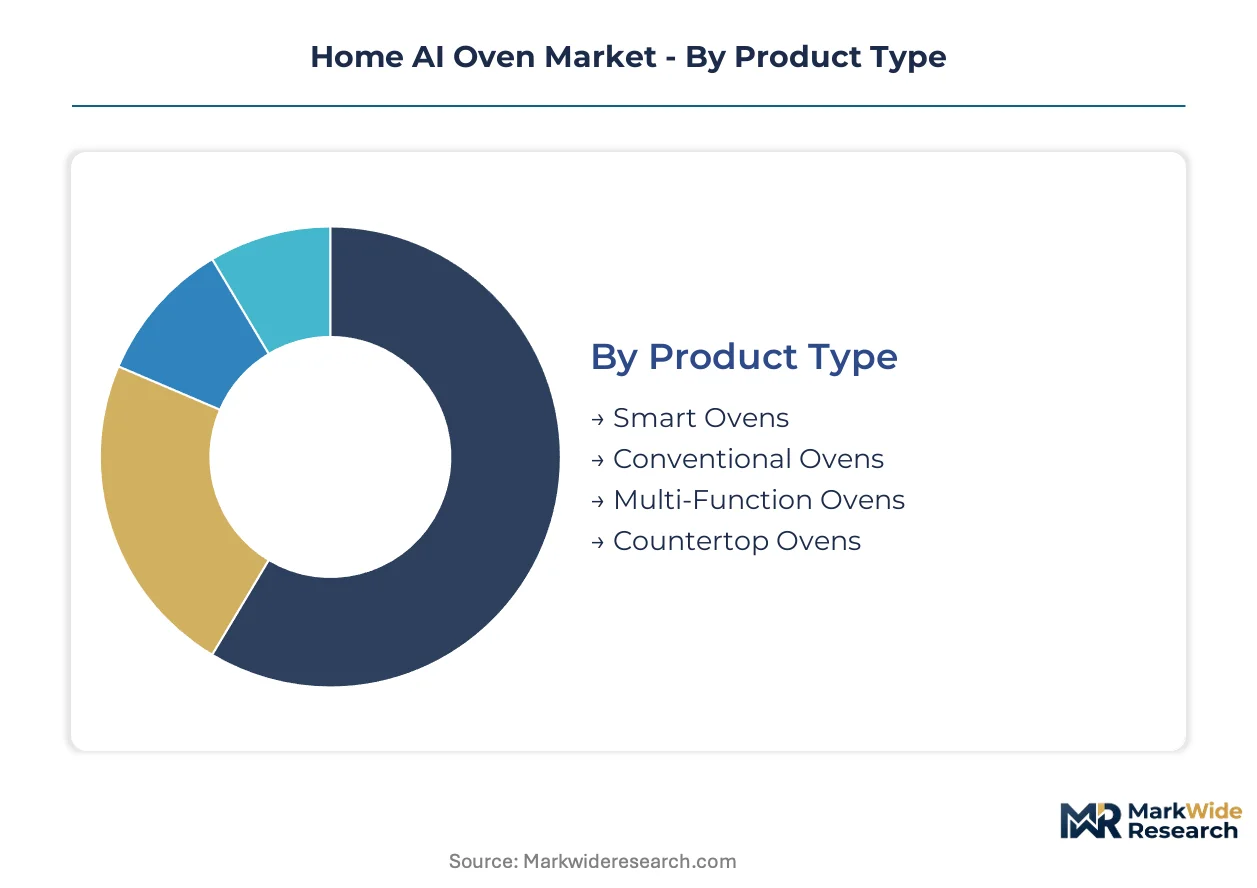
Segmentation in the Home AI Oven Market reveals how hardware specifications, interface technologies, and user sophistication stratify across distribution channels. Manufacturers configure product portfolios around distinct margin pools and installation requirements.
Product Type:
Channel mix varies sharply by form factor and installation complexity, with built-in units flowing through kitchen renovation specialists while portable variants dominate e-commerce direct sales.
- Smart Ovens:These units integrate cloud-connected recipe databases with automated thermal management and multi-spectral food recognition cameras. Demand concentrates among homeowners in Germany and the United States undertaking kitchen renovations, pulled by EU Green Deal standby power mandates that accelerate replacement cycles.
- Conventional Ovens:Basic electric heating elements without AI inference capabilities serve price-sensitive segments and rental property retrofits. Volume clusters in India and Southeast Asia where smart home infrastructure remains underdeveloped.
- Multi-Function Ovens:Steam-combi and convection-hybrid configurations with programmable modes.
- Countertop Ovens:Compact plug-in units targeting apartment dwellers and secondary cooking stations.
By volume, Smart Ovens leads. By growth pace, Countertop Ovens is ahead.
Technology:
Cost tier alignment determines which interface technologies ship at premium versus economy price points, with neural processing hardware commanding the widest spreads.
- Machine Learning:Edge-deployed neural networks refine cooking parameters through thermal feedback loops and adaptive doneness prediction. Adoption concentrates among food enthusiasts in China and the United States seeking precision without manual calibration.
- IoT Connectivity:Cloud telemetry enables remote preheating, usage analytics, and subscription recipe access. Demand clusters in Germany and France where smart home platform integration with Matter protocol drives ecosystem loyalty.
- Voice Recognition:Hands-free command processing through Alexa and Google Home integration.
- Touchscreen Interface:Graphical recipe browsing and manual parameter override panels.
By margin contribution, Machine Learning leads. By commoditization speed, Voice Recognition is ahead.
End User:
Application context shapes feature prioritization, with professional-adjacent users demanding calibration precision that casual cooks trade for convenience.
- Chefs:Former restaurant professionals and serious home cooks requiring temperature accuracy within 0.5 degrees Celsius and repeatable thermal profiles. Concentration in France and Japan where culinary technique preservation drives specification demands.
- Homeowners:Primary residence occupants purchasing built-in units through kitchen renovation channels. Volume clusters in the United States and China where new residential construction incorporates smart appliance pre-wiring.
- Food Enthusiasts:Hobbyist cooks pursuing precision techniques without professional training.
- Renters:Transient residents prioritizing portability and landlord-compatible installation.
By absolute volume, Homeowners leads. By specification intensity, Chefs is ahead.
Price Tier:
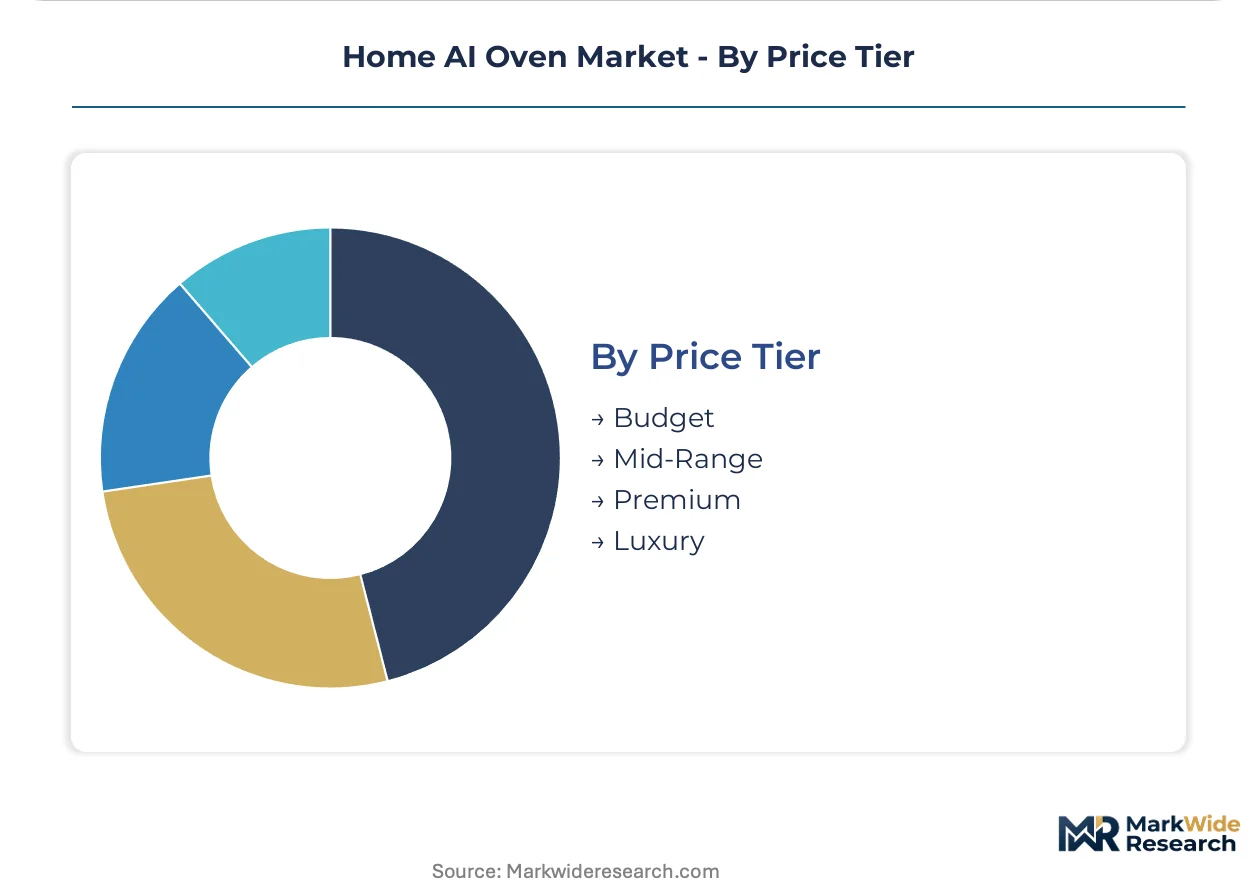
Maturity gradients separate segments, with premium tiers capturing technology validation costs while luxury segments absorb handcrafted enclosure materials.
- Premium:Units priced above mass-market thresholds incorporating proprietary neural processing units and industrial-grade thermocouples. Demand concentrates in Germany and Switzerland where CE marking under EU AI Act algorithmic transparency requirements extends certification timelines and justifies positioning.
- Mid-Range:Cloud-connected ovens with standardized sensor fusion and third-party recipe platform access. Volume clusters in China and the United States where direct-to-consumer subscription bundling displaces traditional retail markups.
- Budget:Basic IoT connectivity without edge AI inference capabilities.
- Luxury:Bespoke finishes and concierge installation services with limited production runs.
By revenue concentration, Premium leads. By volume expansion, Mid-Range is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors European demand acceleration for AI-enabled cooking appliances, with energy efficiency mandates reshaping replacement cycles across Germany, France, and Italy. China and the United States concentrate smart home infrastructure investment, while India opens new localization corridors through manufacturing incentives.
United States
Residential construction pre-wiring for smart appliances and Matter protocol ecosystem integration drive specification requirements. The FDA's food contact substance notifications govern sensor materials interacting with cooking surfaces. Seattle and Austin clusters concentrate direct-to-consumer subscription bundling experiments bypassing traditional retail channels.
Germany
Kitchen renovation specialists channel built-in AI oven demand among homeowners responding to EU Green Deal standby power regulations. CE marking under the EU AI Act imposes algorithmic transparency obligations extending certification timelines. Munich and Stuttgart industrial zones host regulatory affairs teams pre-clearing submissions with Brussels authorities.
China
New residential development incorporates smart appliance infrastructure at scale, pulling volume through automated assembly facilities serving Asia-Pacific markets. MIIT standards and dual carbon goals constrain product design cycles. Shenzhen and Hangzhou clusters concentrate neural processing unit integration into control board manufacturing.
India
BIS certification alignment and PLI scheme electronics manufacturing incentives enable white space entry for AI oven localization. Mumbai and Bangalore residential developments concentrate early smart kitchen penetration among premium housing segments. Central electricity authority grid stability programs influence power management feature prioritization.
Japan
Former restaurant professionals and serious home cooks demand temperature accuracy within 0.5 degrees Celsius, preserving culinary technique through precision equipment. METI industrial standards and JIS certification frameworks shape product validation requirements. Osaka and Nagoya clusters concentrate thermal calibration protocol development inherited from commercial baking equipment traditions.
Home AI Oven Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with semiconductor supply chain control and firmware development capabilities determining competitive position. The market structure compresses toward players commanding neural processing hardware and thermal sensor fusion expertise. Appliance manufacturers with captive semiconductor operations and industrial-grade calibration heritage represent distinct archetypes, while cloud platform operators and direct-to-consumer specialists occupy adjacent positions. Dominant competitive moves center on securing scarce embedded AI engineering talent and establishing regulatory pre-clearance capabilities in Brussels.
Within the integrated electronics tier, Samsung Electronics and LG Electronics occupy positions defined by semiconductor supply chain leverage and display technology integration. Bosch and Siemens exemplify the European industrial-calibration archetype, anchoring premium positioning through temperature protocol heritage. Haier represents scale-driven manufacturing concentration, with Midea occupying a parallel position in automated assembly capacity for Asia-Pacific distribution.
| Leading Market Players |
|---|
| Bosch |
| LG Electronics |
| Electrolux Group |
| Haier |
| Samsung Electronics |
| Siemens |
| Midea |
| Whirlpool |
| Panasonic |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU AI Act gates both supplier qualification timelines and premium tier price positioning, compressing margin structures for manufacturers lacking Brussels regulatory pre-clearance capabilities while amplifying returns for algorithmic transparency documentation leaders.
Pricing Analysis
Germany commands price spreads against India and Southeast Asia, with premium units incorporating proprietary neural processing units and industrial-grade thermocouples sustaining positioning through certification-grade sensor fusion. Three-tier pricing structure across premium, standard, and economy levels stratifies by algorithmic capability depth and thermal calibration precision. Cost compression in mid-range segments intensifies as multi-spectral camera miniaturization collapses hardware distinctions previously separating tiers. Budget-conscious homeowners in India and rental property managers exhibit highest price sensitivity, while former restaurant professionals in France and Japan absorb premiums for sub-0.5-degree Celsius accuracy.
Supply Chain Analysis
TSMC and Samsung foundry capacity in Taiwan and South Korea anchors neural processing unit availability, creating chokepoint vulnerability for edge AI inference hardware. Control board manufacturing draws from Shenzhen and Hangzhou clusters, while thermal sensor modules source from Osaka and Nagoya precision calibration facilities. Single-source vulnerability in semiconductor fabrication threatens production continuity for adaptive cooking refinement capabilities. Distribution runs through kitchen renovation specialists for built-in configurations and direct-to-consumer platforms for portable variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Matter protocol interoperability is reshaping platform economics, with ecosystem loyalty exceeding brand attachment and subscription bundling displacing transactional hardware margins.
For Market Incumbents: Secure scarce embedded AI engineering talent through acquisition of thermal physics-neural network optimization specialists before certification timeline elongation widens competitive gaps. Defend margin pools by establishing captive semiconductor supply relationships with TSMC or Samsung foundry allocations. CE marking pre-clearance capabilities in Brussels represent the critical defensive lever against algorithmic transparency documentation delays.
For New Entrants and Emerging Players: Health-condition-specific meal automation for diabetes and renal diet protocols offers under-served premium positioning where macro-nutrient preservation commands pricing power. India smart kitchen penetration through BIS certification alignment and PLI scheme electronics manufacturing incentives presents the most penetrable geography. Direct-to-consumer subscription bundling bypassing big-box retail markups provides the decisive go-to-market angle.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with dormant appliance firmware capabilities and underutilized thermal calibration heritage. Long-term viability hinges on neural processing hardware integration depth and regulatory affairs infrastructure rather than brand equity alone. Watch for EU AI Act algorithmic transparency enforcement intensity crossing thresholds that would extend certification cycles disproportionately for non-compliant portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Neural Processing Unit Integration | Proprietary edge AI inference hardware from Samsung and TSMC foundries locks thermal management differentiation. |
| Regulatory Pre-Clearance Investment | Brussels-based documentation teams compress CE marking timelines under EU AI Act algorithmic transparency mandates. |
| Direct-to-Consumer Subscription Launch | Hardware-plus-recipe-service bundling through proprietary apps bypasses retail markups in China and the United States. |
| Health-Condition Protocol Development | Diabetes and renal diet automation commands premium positioning through macro-nutrient preservation capabilities. |
| Matter Protocol Certification | Smart home platform integration with Amazon Alexa and Google Home ecosystems drives ecosystem loyalty lock-in. |
Research Methodology
Operator-level perspectives from appliance firmware engineering directors, thermal sensor procurement leads at OEMs, kitchen renovation channel partners, and smart home platform integration specialists anchored the qualitative base. Secondary validation drew from MIIT standards filings, EU AI Act algorithmic transparency documentation, FDA food contact substance notifications, and SEC 10-K appliance segment disclosures. Bottom-up shipment modeling and top-down smart home infrastructure penetration curves were triangulated against energy efficiency mandate implementation timelines.
Sensitivity analysis tested neural processing unit foundry allocation scenarios, F-Gas Regulation material reformulation cost pass-through rates, and Matter protocol adoption velocity assumptions across the projection horizon. Segmentation dimensions modeled included product type, technology tier, end-user sophistication, and price positioning band. CAGRs were derived from replacement cycle acceleration under EU Green Deal standby power mandates and smart home pre-wiring penetration in new residential construction.
Forecasts assume regulatory continuity in EU AI Act algorithmic transparency enforcement and CE marking documentation requirements; material policy shifts would require re-modeling certification timeline impacts. Semiconductor supply concentration in Taiwan and South Korea, F-Gas Regulation insulation material constraints, and legacy residential electrical infrastructure capacity limitations represent specific risk factors. Revision becomes warranted when TSMC or Samsung foundry allocation availability for neural processing units crosses critical threshold disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Industrial AI Software Market
Artificial Intelligence (AI)
Global Cloud Telecommunication AI Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
Decision Intelligence Market
Artificial Intelligence (AI)
Global Aiops Platform Market
Artificial Intelligence (AI)
No-Code AI Platform Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
US Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
Global Voice Assistant Application Market
Artificial Intelligence (AI)
Cognitive Services Platform Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Robotics Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
NLP in Healthcare and Life Sciences Market
Artificial Intelligence (AI)
Global Voice Cloning Market