
 Gesture Recognition for Smart TV Market | 2026-2036
Gesture Recognition for Smart TV Market Size, Share, and Industry Trends Forecast 2026-2036
Gesture Recognition for Smart TV Market Foresight
Buyer concentration in the consumer electronics sector is decoupling from traditional retail channels as streaming service providers and hospitality groups procure gesture systems directly. Samsung Electronics leverages its display semiconductor integration to control hardware-software coordination across premium TV lines. LG Electronics anchors its competitive stance through depth-sensing module specialization in OLED product tiers. Sony Corporation differentiates via low-latency computer vision algorithms optimized for gaming-centric applications.
Gesture recognition for smart TV denotes contactless human-machine interface technology that interprets body movements, hand positions, and spatial gestures through optical or electromagnetic sensing to execute commands on television systems. The technology typically operates with sub-100-millisecond latency thresholds using infrared or time-of-flight depth arrays to enable real-time content navigation without physical controllers. Computer vision and depth-sensing technology segments lead current deployment due to their precision in low-light living room environments. Software solutions and embedded modules capture expanding margin pools as manufacturers shift from external peripherals to integrated system-on-chip architectures. Application demand concentrates in content navigation and gaming control, where latency tolerance is narrowest and user experience differentiation proves most salient.
The FCC governs radio-frequency emission thresholds for ultrasonic and radar-based gesture sensors in the United States, while the EU AI Act imposes transparency requirements on biometric inference systems including gesture interpretation. CE marking under the Radio Equipment Directive shapes market access for European-bound hardware. Stakeholders must monitor evolving interoperability mandates between smart TV platforms and smart home ecosystems to anticipate which sensor modalities achieve dominant design status.
Market Dynamics
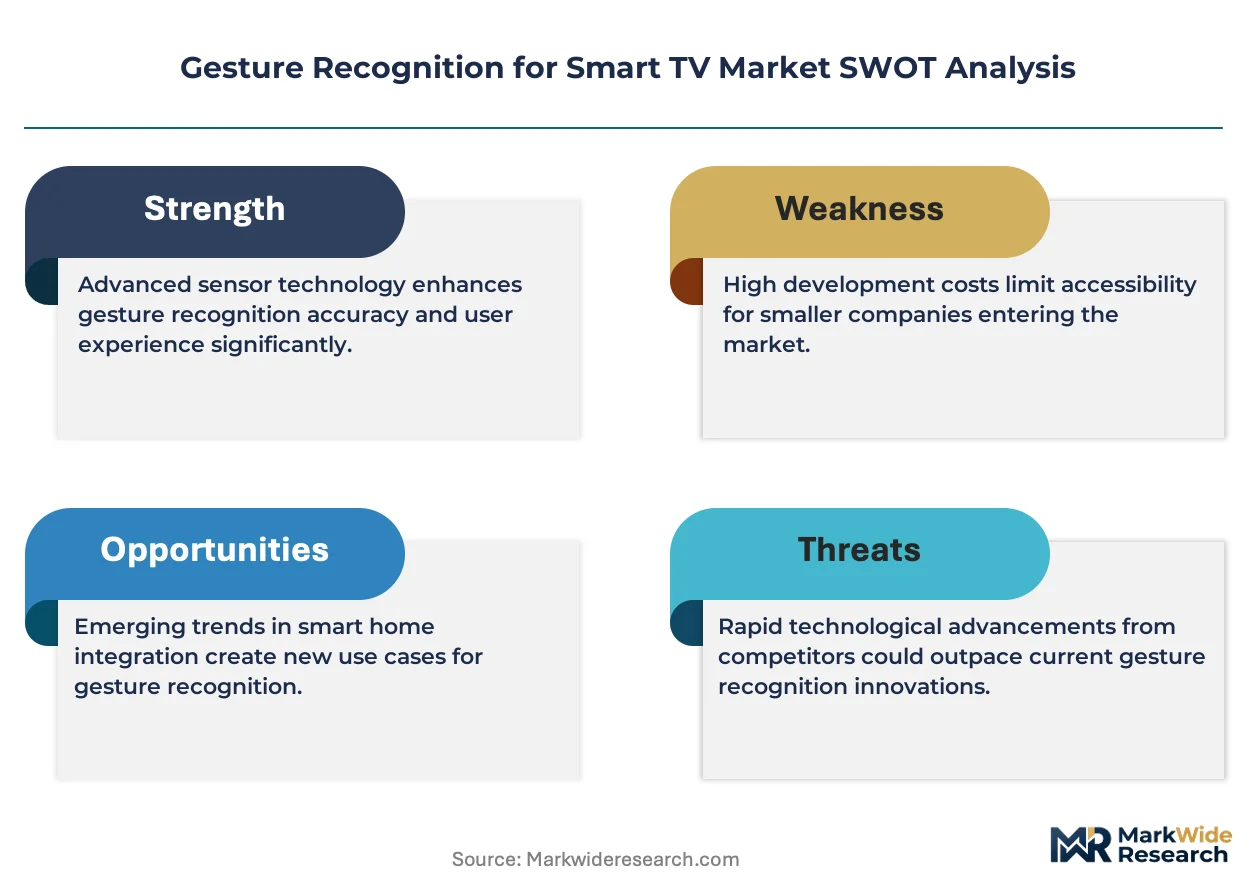
The migration from discrete gesture peripherals to system-on-chip integration is compressing hardware margins while concentrating value capture among semiconductor foundries with advanced packaging capabilities.
Growth Catalysts
- Residential smart home penetration:Touchless interface demand from connected living room ecosystems pulls gesture modules into premium television SKUs as standard configuration rather than accessory.
- FCC equipment authorization streamlining:Radio-frequency sensing device rules in the United States clarify compliance pathways for ultrasonic and radar-based sensors, accelerating product launch cycles.
- Time-of-flight depth array maturation:Infrared sensing precision improvements enable sub-100-millisecond latency thresholds that satisfy gaming and navigation use cases simultaneously.
Market Restraints
- Depth-sensor module cost structure:Specialized optical component fabrication requires capital-intensive cleanroom capacity concentrated among East Asian suppliers.
- EU AI Act biometric inference constraints:Transparency requirements for gesture interpretation systems impose documentation burdens that extend European market access timelines.
- Physical remote control persistence:Low-cost infrared handset substitutes retain preference among price-sensitive consumer segments and aging demographics.
Strategic Opportunities
- Hospitality direct procurement channels:Hotels and cruise operators bypass retail distribution to specify integrated gesture systems for in-room entertainment upgrades.
- Computer vision and edge AI convergence:On-device neural processing unit integration enables gesture recognition without cloud dependency, reducing latency and privacy exposure.
- South Korea smart city deployment:Government-backed digital infrastructure programs specify gesture-enabled public information displays for transit and municipal buildings.
Industry Challenges
- Computer vision algorithm talent scarcity:Low-latency spatial tracking expertise concentrates among gaming industry veterans and academic robotics programs.
- Interoperability certification complexity:Smart TV platforms and smart home ecosystem protocols lack unified gesture command mapping standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gesture Recognition for Smart TV Market |
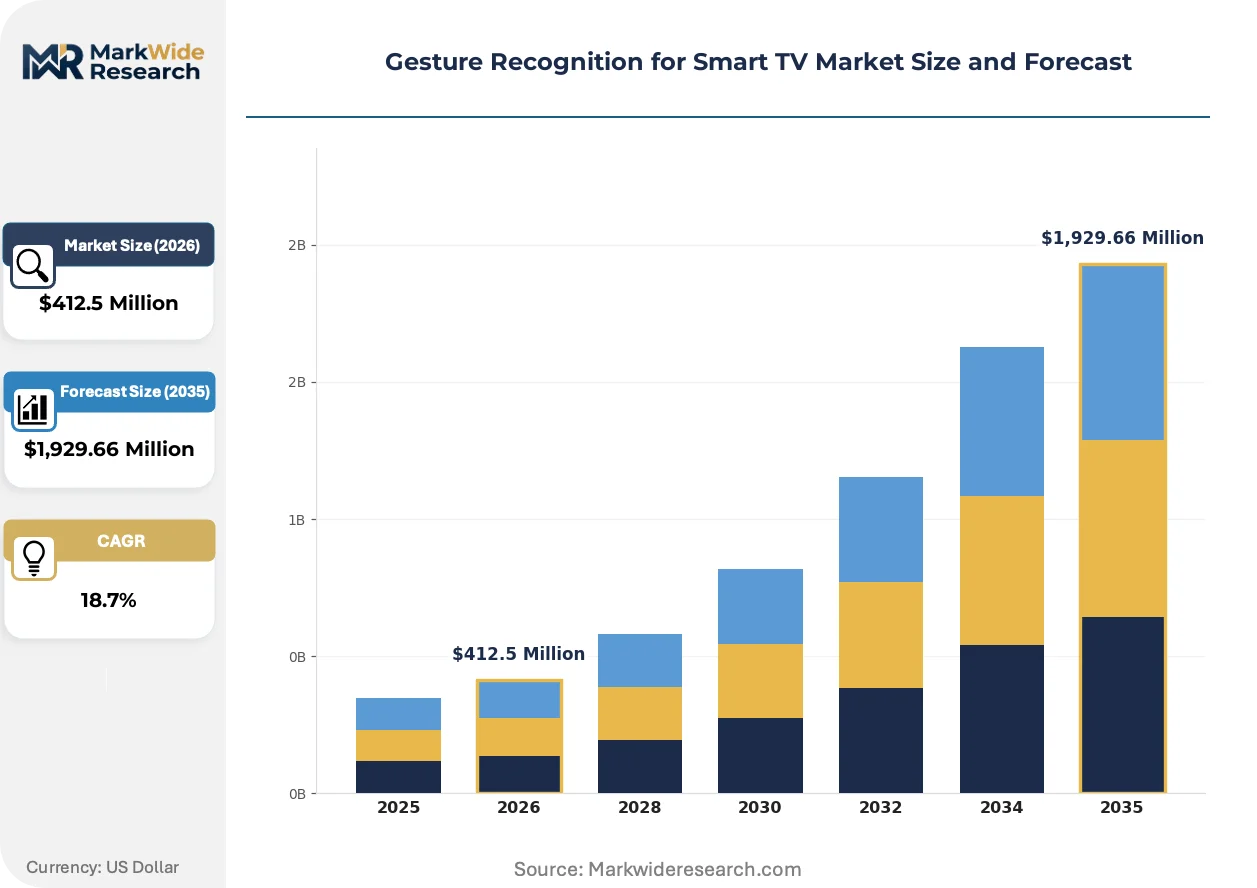
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Computer Vision, Ultrasonic Sensors, Infrared Sensors, Radar-Based Detection, Time-of-Flight, Depth Sensing Application: Content Navigation, Gaming Control, Voice Assistant Interaction, Smart Home Integration, Accessibility Features, Personalized Recommendations Product Type: Built-In Gesture Recognition, External Gesture Controllers, Software Solutions, SDKs, Middleware Platforms, Embedded Modules End User: Consumer Electronics Manufacturers, Streaming Service Providers, Hospitality Sector, Educational Institutions, Fitness & Wellness Centers, Advertising Agencies |
| Companies Covered | Samsung Electronics, LG Electronics, Sony Corporation, Panasonic Corporation, Texas Instruments, PointGrab, Eyesight Tech, SoftKinetic, OMRON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gesture Recognition for Smart TV Market Shifts & Advancements
Gesture recognition architecture is shifting from external USB peripherals toward embedded system-on-chip designs that fuse depth sensing with display driver silicon.
Time-of-flight depth arrays are automating spatial gesture capture through direct semiconductor integration with television display panels. Samsung Electronics and LG Electronics embed these sensors directly into bezel structures rather than attaching external modules. This integration is automating the elimination of peripheral hardware margins from the value chain.
The EU AI Act imposes algorithmic transparency documentation on biometric inference systems including gesture pattern recognition. Hardware manufacturers must now maintain technical files demonstrating how spatial data translates to command execution. European-bound products face extended conformity assessment periods compared to jurisdictions without comparable artificial intelligence governance frameworks.
Streaming service providers now procure gesture-enabled television hardware directly for bundled subscription offerings, bypassing traditional consumer electronics retail. This channel compression concentrates purchasing power among content platform operators rather than electronics distributors. The United States and South Korea exhibit the most advanced direct procurement arrangements between streaming services and original equipment manufacturers.
Gesture Recognition for Smart TV Market Segmentation
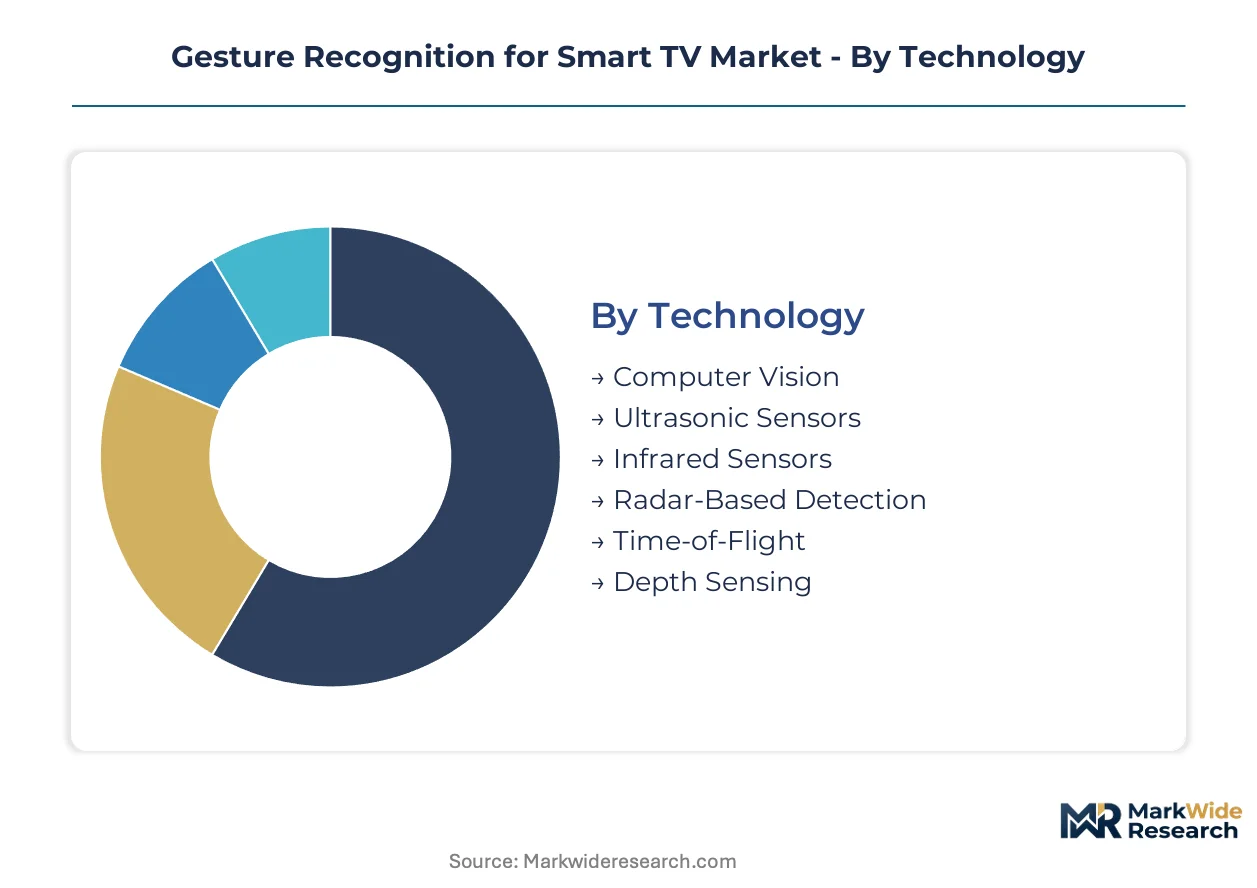
Gesture recognition architectures fragment across sensing modalities, integration depths, and procurement channels. Each segmentation axis reveals distinct margin structures and competitive moats that determine vendor positioning.
Technology:
Depth-sensing and computer vision technologies anchor precision thresholds while radio-frequency methods challenge cost structures.
- Computer Vision:Algorithms process 2D camera feeds to infer spatial hand positioning through skeletal mapping. Living room deployments in the United States and South Korea concentrate demand where low-light compensation and sub-100-millisecond latency justify premium module costs.
- Time-of-Flight:Direct depth measurement via modulated infrared light eliminates ambient light interference. Samsung Electronics and LG Electronics embed these arrays directly into display bezels, collapsing peripheral hardware margins and accelerating SoC integration timelines.
- Depth Sensing:Structured light and stereo camera fusion enables millimeter-accurate spatial tracking for gaming applications.
- Infrared Sensors:Legacy thermopile arrays detect hand presence through heat signatures at reduced computational overhead.
- Radar-Based Detection:Millimeter-wave frequency modulation penetrates fabric and operates through furniture occlusion.
- Ultrasonic Sensors:Piezoelectric transducers emit inaudible pulses for proximity-agnostic gesture capture.
Computer Vision leads on scale; Time-of-Flight leads on momentum.
Application:
Use case specificity determines latency tolerance and sensor modality selection across consumer and commercial deployments.
- Gaming Control:Competitive multiplayer titles demand sub-50-millisecond input-to-display pipelines. Depth-sensing arrays in South Korea and Japan anchor this segment where esports viewership drives hardware refresh cycles.
- Content Navigation:Menu browsing and playback control tolerate 100-150 millisecond latency, broadening sensor options. Hospitality procurement in Dubai and Singapore specifies these systems for cruise cabin and hotel suite installations.
- Smart Home Integration:Gesture commands trigger lighting, climate, and security systems through television hub functionality.
- Voice Assistant Interaction:Hand gestures complement microphone arrays for multimodal command confirmation.
- Accessibility Features:Motion-based interfaces serve mobility-impaired users unable to manipulate physical remotes.
- Personalized Recommendations:Viewer attention and posture data inform content suggestion algorithms.
Content Navigation dominates volume; Gaming Control commands premium pricing.
Product Type:
Integration depth separates margin capture between semiconductor foundries and peripheral hardware vendors.
- Embedded Modules:Co-packaged depth sensors and neural processing units mount directly to display driver boards. Taiwan Semiconductor Manufacturing Company and Samsung Foundry control advanced packaging capacity for these solutions.
- Software Solutions:Gesture recognition SDKs license per-unit royalties to television manufacturers seeking rapid feature deployment without silicon redesign.
- Built-In Gesture Recognition:Fully integrated SoC architectures eliminate external component procurement.
- External Gesture Controllers:USB-attached peripherals retain relevance for retrofit installations and legacy display upgrades.
- SDKs:Developer toolkits enable third-party application integration with standardized gesture vocabularies.
- Middleware Platforms:Abstraction layers harmonize multiple sensor inputs across operating system environments.
Embedded Modules concentrate value capture; Software Solutions expand addressable market.
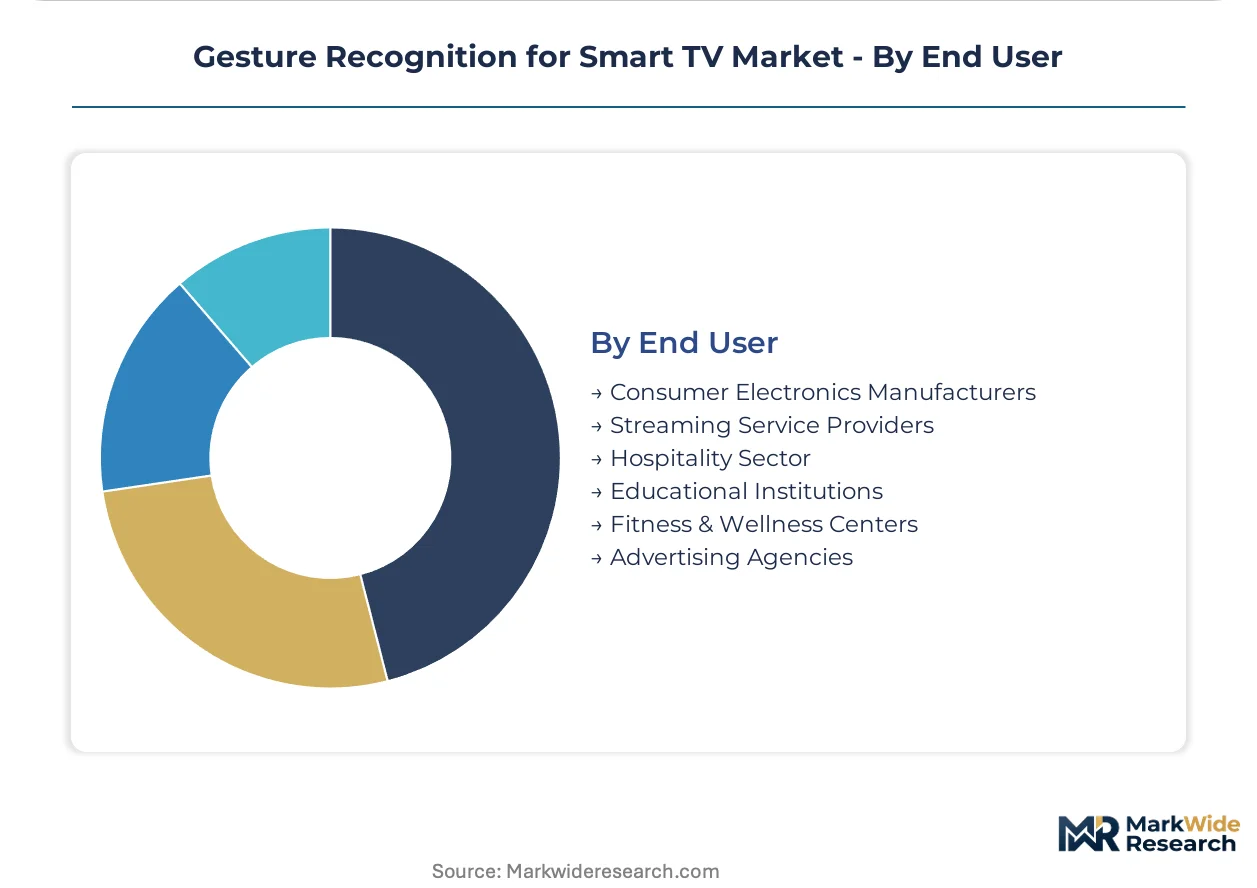
End User:
Procurement authority is shifting from electronics distributors to content platforms and commercial specifiers.
- Streaming Service Providers:Netflix, Disney+, and regional platforms in the United States and South Korea negotiate direct hardware bundles. These arrangements bypass retail markup and lock gesture-enabled SKUs to subscription commitments.
- Hospitality Sector:Marriott, Hilton, and cruise operators specify integrated systems for property-wide entertainment standardization.
- Consumer Electronics Manufacturers:Samsung Electronics, LG Electronics, and Sony Corporation retain in-house gesture development or license module designs.
- Educational Institutions:Universities deploy gesture-enabled displays for hybrid classroom interaction.
- Fitness & Wellness Centers:Mirror-style displays incorporate motion tracking for guided workout applications.
- Advertising Agencies:Interactive out-of-home installations employ gesture triggers for engagement metrics.
Consumer Electronics Manufacturers anchor current volume; Streaming Service Providers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates streaming-service procurement power while South Korea dominates depth-sensor manufacturing, creating a trans-Pacific split between demand orchestration and component supply. Germany and Japan anchor precision engineering for time-of-flight modules. China scales domestic smart TV deployment through government-backed digital infrastructure programs.
United States
Netflix and Disney+ negotiate direct hardware bundles that bypass traditional retail channels for gesture-enabled televisions. The FCC's equipment authorization rules for radio-frequency sensing devices clarify compliance pathways for ultrasonic and radar-based sensors. Austin and Silicon Valley host streaming platform headquarters where procurement teams specify integrated gesture systems for subscriber acquisition.
South Korea
Samsung Electronics and LG Electronics embed time-of-flight arrays directly into display bezels, collapsing peripheral hardware margins. The Ministry of Trade, Industry and Energy backs smart city deployments specifying gesture-enabled public information displays. Seoul anchors the Samsung Foundry and LG Display manufacturing clusters where SoC integration accelerates.
China
Domestic smart home adoption pulls gesture modules into premium television SKUs as standard configuration. MIIT governs radio-frequency emission standards for gesture sensors under GB certification requirements. Shenzhen and Dongguan concentrate contract manufacturers assembling depth-sensing modules for export markets.
Japan
Sony Corporation optimizes low-latency computer vision algorithms for gaming-centric applications where esports viewership drives hardware refresh. METI promotes next-generation display technology through regional innovation clusters. Osaka and Nagoya house precision optics suppliers feeding time-of-flight array production.
Germany
Hospitality groups including Marriott and Hilton specify integrated gesture systems for property-wide entertainment standardization across European properties. The EU AI Act imposes transparency documentation burdens on biometric inference systems that extend conformity assessment timelines. Munich and Stuttgart anchor automotive-grade sensor suppliers pivoting toward consumer electronics applications.
Gesture Recognition for Smart TV Market Competitive Landscape
South Korean producers anchor one tier; Japanese and German specialists hold precision engineering positions in depth-sensing components. The vendor base concentrates around display-integrated semiconductor architectures that compress hardware margins while concentrating value capture among foundries with advanced packaging capabilities. Three strategic archetypes dominate: vertically integrated display manufacturers, specialized depth-sensor module suppliers, and software-centric gesture recognition licensors. Capacity expansion in East Asian foundries and strategic partnerships between streaming platforms and OEMs constitute the dominant competitive moves reshaping procurement authority.
Within the vertically integrated tier, Samsung Electronics exemplifies display-semiconductor coordination across premium product lines, while LG Electronics anchors competitive positioning through OLED-integrated depth-sensing specialization. Sony Corporation occupies a position emphasizing low-latency algorithm optimization for gaming applications. These three companies represent the archetype of hardware-software convergence that displaces peripheral gesture controllers from the value chain.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Sony Corporation |
| Panasonic Corporation |
| Texas Instruments |
| PointGrab |
| Eyesight Tech |
| SoftKinetic |
| OMRON |
| Others |
Supply & Pricing Matrix
Low-latency computer vision algorithm talent concentrated among gaming industry veterans in South Korea and Japan widens pricing-tier spreads between premium gesture-integrated displays and standard infrared-remote configurations. Labor-cost differentials in optical cleanroom operations across Taiwan and China further stratify module pricing across premium, standard, and economy television SKUs.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for time-of-flight depth arrays as Samsung Foundry and Taiwan Semiconductor Manufacturing Company expand advanced packaging output. Three-tier pricing structure across premium, standard, and economy levels separates bezel-embedded SoC architectures from external peripheral modules and software-licensed solutions. Cost compression in external gesture controllers is intensifying because streaming service providers negotiate direct hardware bundles that bypass retail markup. Price-sensitive hospitality procurement teams in Dubai and Singapore favor software-licensed solutions, while gaming-centric consumers in Japan and South Korea absorb premiums for sub-50-millisecond latency configurations.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced semiconductor packaging capacity feeding time-of-flight array integration. The supply chain draws from Japan for precision optics, China for contract module assembly, and Germany for automotive-grade sensor components pivoting toward consumer applications. Raw material dependencies span indium phosphide substrates, specialized infrared emitters, and neural processing unit silicon. Tariff exposure on display driver components threatens margin stability for European-bound hardware. Distribution runs through direct procurement channels where Netflix, Disney+, and regional streaming platforms negotiate bundled hardware subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandates compound demand for compliant gesture interpretation systems, extending conformity assessment periods and concentrating procurement authority among vendors with regulatory documentation capabilities.
For Market Incumbents: Deploy backward integration into depth-sensor module production to capture margin pools collapsing from peripheral hardware elimination. Samsung Electronics and LG Electronics already embed time-of-flight arrays directly into display bezels, forcing peripheral vendors toward obsolescence. Certification investment in FCC equipment authorization and EU AI Act compliance documentation defends market access against emerging software-centric licensors. Channel control through streaming service direct partnerships locks subscription bundles to proprietary hardware configurations.
For New Entrants and Emerging Players: The EU AI Act in Germany and France opens a window for specialized compliance documentation services and transparent algorithm licensing to hardware manufacturers lacking in-house regulatory affairs capacity. Hospitality procurement in Dubai and Singapore represents the most penetrable segment, with property-wide entertainment standardization specifications bypassing entrenched consumer electronics retail relationships. A go-to-market angle anchored in retrofit external controllers for legacy display upgrades avoids direct competition with integrated SoC architectures.
For Investors and Strategic Acquirers: Streaming service providers are the most active acquirer in this space, negotiating direct hardware bundles that concentrate purchasing power away from electronics distributors. Long-term viability hinges on computer vision and edge AI convergence enabling on-device neural processing without cloud dependency. Acquisition target archetypes include specialized depth-sensor module suppliers with cleanroom capacity in East Asia and software-centric gesture recognition licensors with EU AI Act compliance documentation. The signal to watch is interoperability mandate announcements between smart TV platforms and smart home ecosystems, which will determine which sensor modalities achieve dominant design status.
| Strategic Initiative | Industry Significance |
|---|---|
| SoC Integration Acceleration | Samsung Foundry's advanced packaging eliminates peripheral hardware margins from value chains. |
| Direct Procurement Channel Development | Netflix and Disney+ bundles bypass retail markup and lock gesture-enabled SKUs to subscriptions. |
| EU AI Act Compliance Documentation | Technical file maintenance extends conformity assessment timelines for European market access. |
| Edge AI Neural Processing Unit Deployment | On-device gesture recognition reduces latency and privacy exposure without cloud dependency. |
| Smart City Public Display Specification | South Korea's Ministry of Trade, Industry and Energy programs mandate gesture-enabled transit installations. |
Research Methodology
Direct dialogue with semiconductor foundry engineers, streaming platform procurement directors, hospitality technology specifiers, and computer vision algorithm specialists grounded qualitative assessment in operational reality. Secondary validation drew from FCC equipment authorization filings, EU AI Act implementation guidance, SEC 10-K disclosures from display manufacturers, and MIIT GB certification records. Bottom-up and top-down triangulation cross-checked module shipment estimates against television production volumes and streaming service subscriber hardware attachment rates.
Bottom-up modeling segmented volume and value across sensing modalities, integration depths, and procurement channels. The analytical framework incorporated technology type, application use case, product integration level, and end-user category throughout the forecast period. CAGRs derived from historical trajectory analysis and adoption curve positioning across residential smart home penetration curves. Industry-specific inputs included time-of-flight depth array maturation timelines and FCC equipment authorization streamlining impacts on product launch cycles.
Revisions become necessary when interoperability mandates between smart TV platforms and smart home ecosystems materialize, or when raw material constraints in indium phosphide substrates disrupt module supply. Forecasts reflect assumptions about streaming service direct procurement expansion and edge AI neural processing unit integration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific 3D Printing Construction Market
Others
Global Multi Domain Controller Market
Others
Mainframe Market
Others
Europe Air Separation Unit Market
Others
India 3D Printing Construction Market
Others
Triathlon Clothing Market
Others
Military Image Intensifier Market
Others
South America Halal Food and Beverages Market
Others
Liquid Density Meters Market
Others
Couscous Market
Others
Foldable Smartphone Market
Others
North America Orange Market
Others
Wearable Translator Market
Others
Profiling Floats Market
Others
Smart Plug Market
Others
Drum Motor Market