
 Europe Travel Retail Market | 2026-2036
Europe Travel Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Travel Retail Market Analysis
CE marking for consumer goods sold within the European Economic Area is reorganizing competitive access across airport retail concessions. Dufry AG leverages its multi-airport concession portfolio to sustain volume throughput across Schengen hubs. Gebr. Heinemann SE & Co. KG anchors its position through exclusive fragrance and spirits distribution agreements with premium houses. WH Smith PLC competes by dominating convenience-oriented news and travel essentials in high-frequency terminal locations.
Europe travel retail encompasses the sale of goods to international travelers in tax-advantaged or duty-suspended environments, typically operating through bonded warehouse supply chains with real-time passenger eligibility verification at point of sale. The model depends on VAT exemption thresholds, destination-based consumption rules, and secure transit corridors that separate inbound and outbound passenger flows. Cosmetics and perfumes command margin concentration due to brand exclusivity and tester-driven conversion rates in confined terminal spaces. Airports as a distribution channel capture the dominant value share, while cruise ships represent a faster-growing but smaller volume pool as Mediterranean itineraries expand.
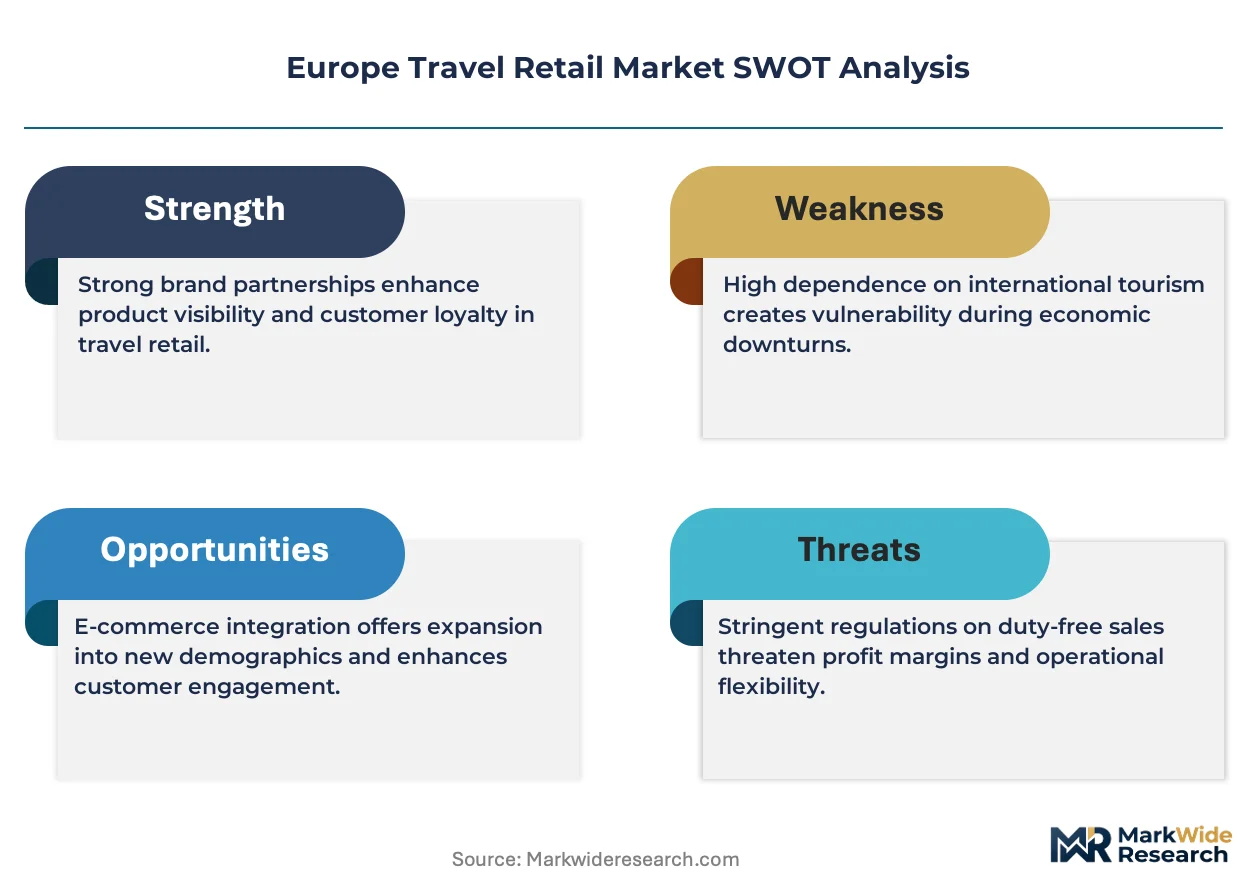
EMA guidelines on cosmetic ingredient safety and REACH chemical registration requirements shape product assortment decisions for beauty and fragrance categories sold across EU airports. The EU AI Act's emerging provisions on automated border processing will influence passenger flow architecture and dwell-time economics in terminal retail zones. Stakeholders must monitor concession renewal cycles alongside evolving digital customs verification systems that could redefine tax-free eligibility mechanics.
Market Dynamics
EU Green Deal packaging waste directives are forcing airport retailers to reengineer bonded warehouse supply chains and eliminate single-use plastics from duty-free operations. The regulatory pressure converges with passenger volume recovery to reshape concession economics across Schengen hubs.
Growth Catalysts
- REACH chemical registration:Harmonized cosmetic ingredient standards simplify cross-border assortment planning for beauty retailers operating in Charles de Gaulle, Heathrow, and Frankfurt terminals.
- Post-pandemic passenger recovery:Mediterranean cruise itineraries are expanding rapidly, creating new duty-suspended retail corridors between Barcelona, Civitavecchia, and Piraeus.
- Digital customs verification:Real-time passenger eligibility systems are reducing transaction friction at point-of-sale terminals in high-volume Schengen airports.
Market Restraints
- Concession renewal concentration:Multi-airport operators face compressed bidding timelines as major European hubs synchronize lease expirations to capture competitive tension.
- Aviation fuel cost pass-through:Carrier ticket pricing volatility directly suppresses discretionary spending power among price-sensitive terminal visitors.
- Biodegradable packaging technical limits:Current barrier properties of compostable materials shorten shelf stability for fragrance and skincare products in climate-variable warehouses.
Strategic Opportunities
- Poland and Romania underpenetration:Warsaw Chopin and Bucharest Henri Coandă offer first-mover concession positioning as Eastern European transit traffic builds.
- EU AI Act border processing:Automated passenger flow architecture will extend dwell times in retail zones, enabling higher conversion rates for impulse categories.
- Refill station integration:Permanent fragrance and cosmetics refill infrastructure aligns with circular economy mandates while capturing repeat terminal visits.
Industry Challenges
- CE marking compliance timelines:Consumer goods certification delays create inventory stranded in bonded warehouses during peak travel seasons.
- Legacy POS integration:Real-time tax-free eligibility verification requires expensive retrofitting of terminal retail systems built on batch-processing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Travel Retail Market |
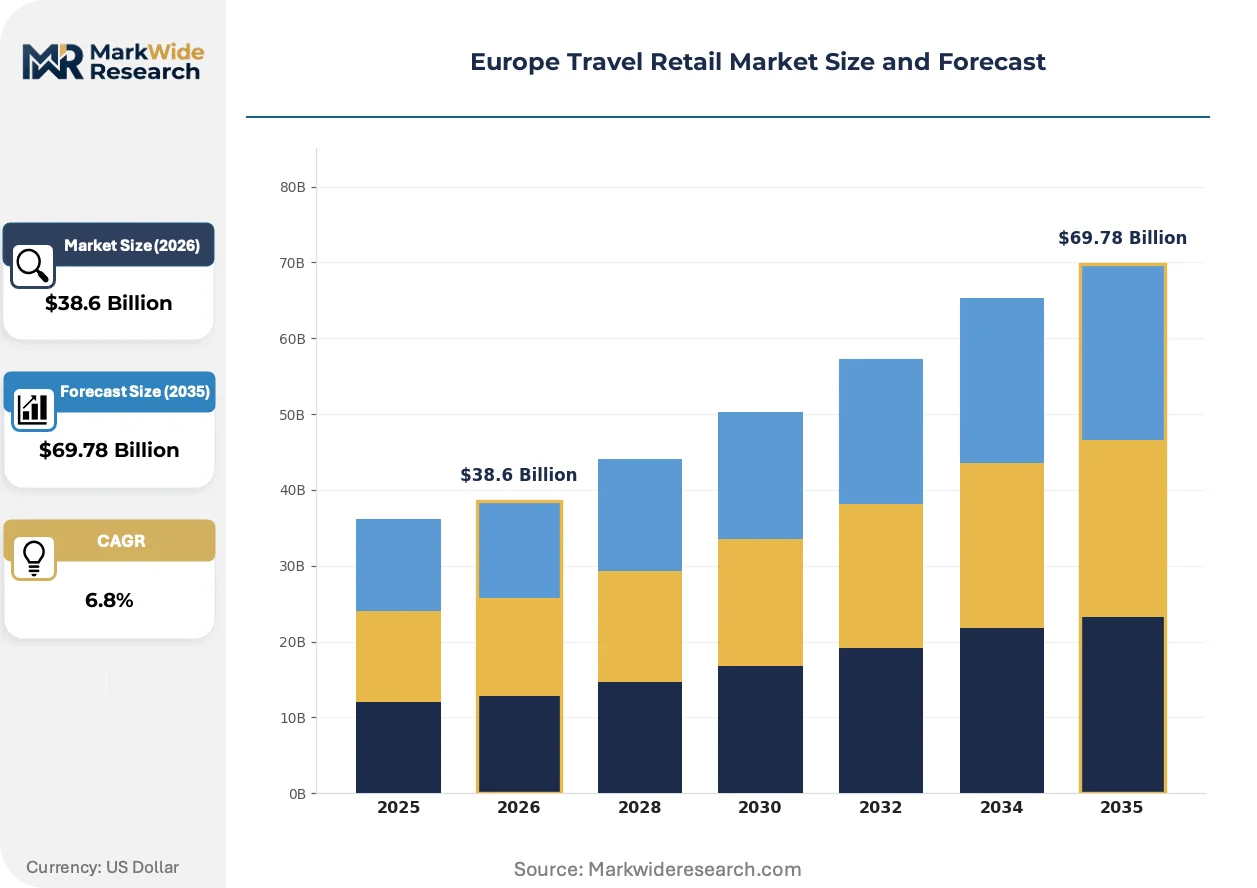
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Cosmetics, Perfumes, Spirits, Confectionery Distribution Channel: Airports, Ferries, Cruise Ships, Train Stations Customer Type: Domestic Travelers, International Tourists, Business Passengers, Holiday Makers Service Type: Duty-Free, Travel Retailers, Specialty Shops, Online Services |
| Companies Covered | Autogrill S.p.A. / World Duty Free, WH Smith PLC, Dufry AG, Avolta AG, Aer Rianta International, Lagardère Travel Retail, LVMH (Moët Hennessy Louis Vuitton), SSP Group PLC, Gebr. Heinemann SE & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Travel Retail Market Emerging Trajectories
Digital passenger verification and sustainable packaging mandates are converging to transform how retailers manage inventory, engage travelers, and structure concession economics across European airports.
Biometric boarding pass integration is bifurcating terminal retail operations. Facial recognition gates at Amsterdam Schiphol and Paris Charles de Gaulle now authenticate tax-free eligibility without document presentation. High-frequency business travelers adopt seamless corridor routing that bypasses traditional duty-free zones entirely. This technology is bifurcating passenger flows into tracked high-value segments and untracked leisure travelers with divergent dwell-time profiles.
EMA guidelines on cosmetic ingredient safety are tightening permissible preservative concentrations in fragrance and skincare formulations sold across EU airports. Retailers must maintain parallel inventory streams for Schengen-compliant and non-Schengen destination passengers. Premium beauty houses are reformulating tester products first, creating temporary assortment gaps in flagship terminal boutiques.
Pre-order and collect-later models are displacing impulse-heavy browsing in confined gate areas. British Airways and Air France-KLM passengers increasingly reserve duty-free items via mobile apps before airport arrival. Mediterranean cruise terminals in Barcelona and Venice show the strongest adoption, where embarkation-day congestion compresses traditional retail windows.
Europe Travel Retail Market Segmentation
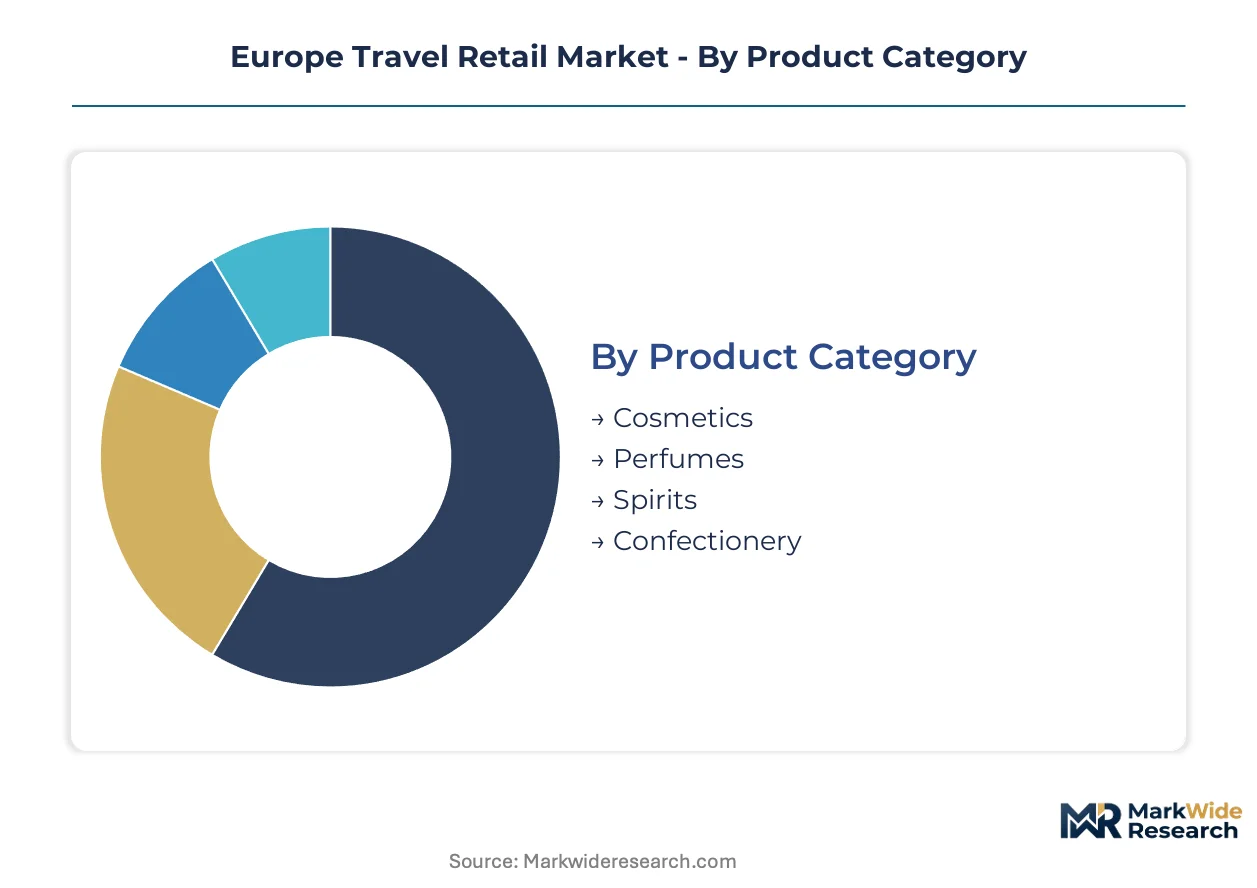
Travel retail segmentation in Europe maps directly onto regulatory boundaries and passenger flow architecture. Each dimension—product, channel, customer, and service type—interacts with Schengen zone rules, VAT exemption thresholds, and concession economics to determine margin capture.
Product Category:
Demand spreads unevenly across domestic Schengen consumption versus long-haul export corridors, with fragrance and spirits dominating extra-EU routes while confectionery captures intra-European impulse purchases.
- Cosmetics:Skincare and color cosmetics formulated under EMA preservative guidelines command premium positioning in flagship terminal boutiques. Heathrow and Charles de Gaulle concentrate demand as Asian and Middle Eastern passengers prioritize tax-advantaged beauty assortments ahead of return flights.
- Perfumes:Tester-driven conversion in confined gate spaces sustains margin concentration for exclusive fragrance houses. Mediterranean cruise terminals from Barcelona to Venice show accelerating adoption of pre-order models that compress traditional browsing windows.
- Spirits:Bonded warehouse supply chains for aged whiskies and regional liqueurs face compressed inventory cycles under EU Green Deal packaging mandates.
- Confectionery:Short shelf-life requirements and climate-variable storage limit premium chocolate distribution to high-turnover Schengen hubs.
Cosmetics holds the largest share; momentum sits with perfumes as reformulation cycles align with circular economy mandates.
Distribution Channel:
Channel economics diverge sharply by dwell-time architecture and passenger eligibility verification complexity, with airports extracting maximum value per square meter while cruise ships expand volume pools.
- Airports:Real-time biometric boarding pass integration at Amsterdam Schiphol and Paris Charles de Gaulle authenticates tax-free eligibility without document presentation, streamlining transaction velocity in high-frequency terminals.
- Cruise Ships:Mediterranean itineraries connecting Barcelona, Civitavecchia, and Piraeus create expanding duty-suspended retail corridors with embarkation-day congestion compressing traditional retail windows.
- Ferries:Cross-channel routes between Dover and Calais maintain steady confectionery and spirits throughput on shorter transit schedules.
- Train Stations:Eurostar terminals at London St Pancras and Paris Gare du Nord capture business passenger convenience spending with limited luxury penetration.
Airports dominate revenue extraction; cruise ships are gaining share fastest as Eastern Mediterranean itineraries multiply.
Customer Type:
Passenger segmentation reflects divergent dwell-time profiles and discretionary spending power, with business travelers bypassing traditional duty-free zones through seamless biometric corridors.
- International Tourists:Long-haul visitors from Asia-Pacific and Gulf Cooperation Council states drive fragrance and premium spirits volume at Heathrow, Charles de Gaulle, and Frankfurt through extended pre-departure dwell times.
- Business Passengers:High-frequency travelers adopting facial recognition gate routing at major Schengen hubs increasingly bypass conventional retail zones entirely, forcing concession operators toward mobile pre-order integration.
- Domestic Travelers:Intra-European passengers face restricted VAT exemption eligibility, concentrating demand on convenience categories in train stations and regional airports.
- Holiday Makers:Seasonal leisure passengers on Mediterranean cruise routes show strongest adoption of reserve-and-collect duty-free models.
International tourists contribute the highest per-passenger spend; business passengers are expanding most quickly through biometric-enabled seamless corridors.
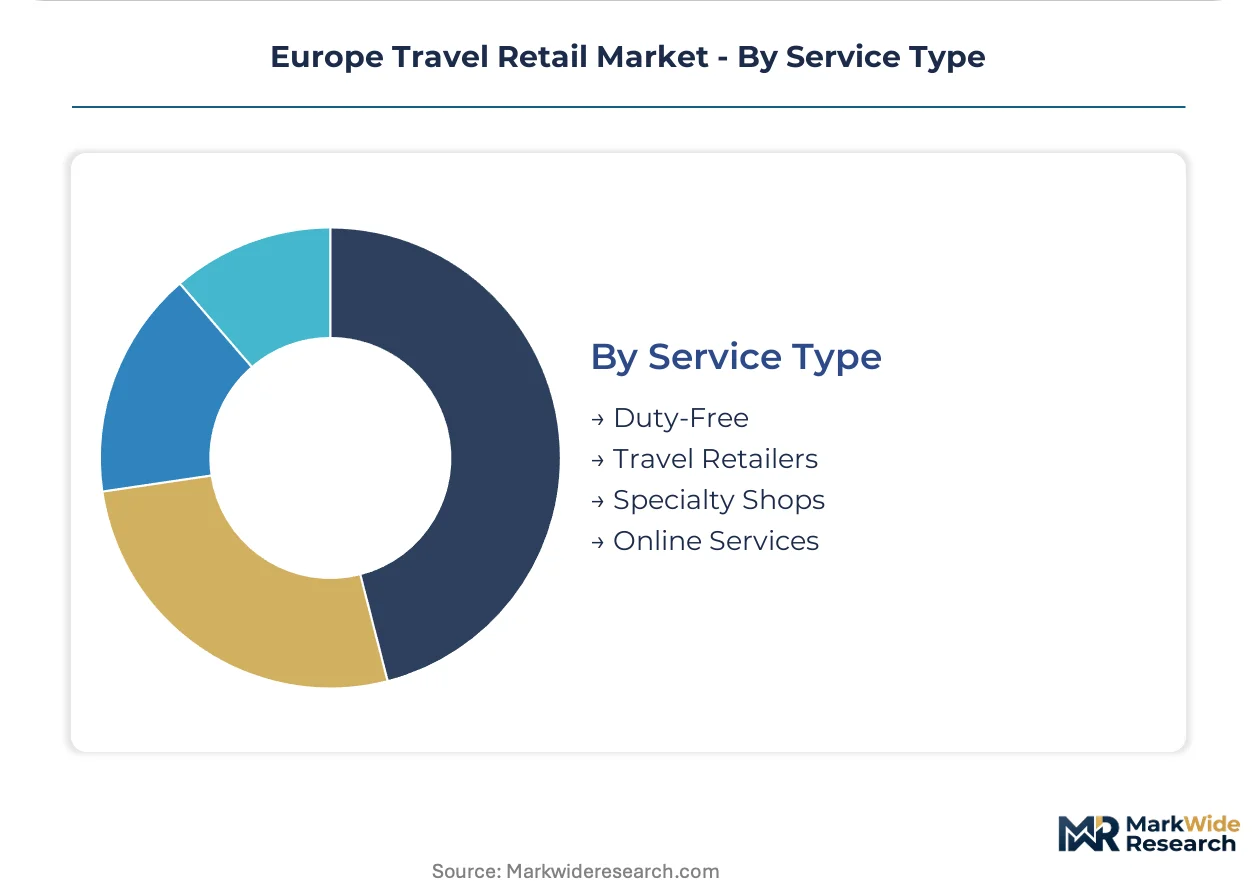
Service Type:
Service model differentiation tracks regulatory compliance burden and inventory risk allocation, with duty-free operations requiring bonded warehouse infrastructure and real-time customs verification systems.
- Duty-Free:VAT-suspended sales contingent on destination-based consumption rules and secure transit corridor separation of inbound and outbound flows demand sophisticated bonded supply chain management at Charles de Gaulle and Heathrow.
- Travel Retailers:Multi-category operators like Dufry AG leverage multi-airport concession portfolios to sustain volume throughput across Schengen hubs through exclusive distribution agreements with premium houses.
- Specialty Shops:Single-brand boutiques in high-frequency terminal locations concentrate on tester-driven conversion for cosmetics and fragrances.
- Online Services:Pre-order and collect-later platforms displace impulse browsing as British Airways and Air France-KLM passengers increasingly reserve items via mobile apps before airport arrival.
Duty-Free captures the dominant value share; online services show the steepest expansion trajectory as mobile reservation penetration climbs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Long-haul passengers from Asia-Pacific and Gulf Cooperation Council states concentrate per-passenger spend at major hub airports. Schengen transit corridors and VAT exemption thresholds determine concession economics across national boundaries. Recovery trajectories diverge between mature Western European hubs and emerging Eastern European transit points.
United Kingdom
Heathrow Terminal 5 and Gatwick North Terminal anchor fragrance and premium spirits volume through extended dwell times for Middle Eastern and Asian passengers. UK Border Force digital customs verification systems streamline tax-free eligibility authentication at point of sale. London's hub concentration faces pressure from post-Brexit regulatory friction on EU passenger flows.
France
Charles de Gaulle Terminal 2E and Orly West Terminal capture luxury beauty demand from Chinese and American tourists through flagship boutique footprints. ANSM cosmetic ingredient guidelines and EMA preservative concentration limits drive parallel inventory streams for Schengen-compliant formulations. Paris hub retail zones extend dwell-time architecture through integrated pre-order mobile platforms.
Germany
Frankfurt Terminal 1 and Munich Lufthansa hubs sustain spirits and confectionery throughput via bonded warehouse efficiency. REACH chemical registration harmonizes cross-border assortment planning for beauty retailers operating across federal state boundaries. Bavaria's Munich Airport clusters premium fragrance distribution agreements with exclusive brand houses.
Spain
Barcelona El Prat and Madrid Barajas terminals serve Mediterranean cruise corridor passengers with compressed embarkation-day retail windows. EU Green Deal packaging waste directives force reengineering of single-use plastics in duty-free operations at Catalan hub facilities. Andalusian coastal terminals from Málaga to Alicante capture seasonal holiday maker volume.
Netherlands
Amsterdam Schiphol facial recognition gates authenticate tax-free eligibility without document presentation, bifurcating passenger flows into tracked and untracked segments. GDPR compliance frameworks shape biometric data handling in automated border processing systems. Randstad hub retail zones leverage seamless corridor routing to capture high-frequency business traveler convenience spending.
Europe Travel Retail Market Vendor Landscape
Player mix skews toward multi-airport concession operators with integrated bonded supply chain capabilities. Market structure concentrates around three to four dominant groups controlling flagship terminal portfolios across Schengen hubs. Strategic archetypes include pan-European concession aggregators, luxury brand captive retail operators, and specialty fragrance distribution houses. Competitive moves center on concession renewal bidding and exclusive brand distribution agreement capture.
Within the multi-airport concession tier, Dufry AG and Avolta AG exemplify scale-driven operators leveraging integrated portfolios across high-frequency terminals. WH Smith PLC occupies a position anchoring convenience-oriented news and travel essentials in business passenger corridors. Gebr. Heinemann SE & Co. KG represents the specialty fragrance and spirits distribution archetype through exclusive premium house relationships. These three structures illustrate how competitive positioning separates volume throughput operators from brand-exclusivity specialists.
| Leading Market Players |
|---|
| Autogrill S.p.A. / World Duty Free |
| WH Smith PLC |
| Dufry AG |
| Avolta AG |
| Aer Rianta International |
| Lagardère Travel Retail |
| LVMH (Moët Hennessy Louis Vuitton) |
| SSP Group PLC |
| Gebr. Heinemann SE & Co. KG |
| Others |
Supply Flow & Price Mechanics
Multi-airport concession portfolios at Dufry AG and Avolta AG generate procurement scale that compresses supplier margins while establishing price floors for exclusive fragrance and spirits distribution. Bonded warehouse utilization rates across Schengen hubs directly determine per-unit logistics costs, with Heathrow and Charles de Gaulle capacity constraints feeding into premium positioning for cosmetics and perfumes.
Pricing Analysis
Cost-plus contracts with indexation to aviation fuel surcharges and bonded storage fees dominate concession economics between operators and airport authorities. Three-tier pricing structure across premium, standard, and economy levels separates exclusive brand boutiques from multi-category travel retailers and convenience-focused newsagents. Pricing pressure stems from synchronized concession renewal cycles at major hubs compressing bidder margins. Price-sensitive holiday makers on Mediterranean cruise routes contrast with least-sensitive international tourists purchasing tax-advantaged luxury beauty ahead of long-haul departures.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg container terminals elevates inbound logistics costs for Asia-sourced cosmetics packaging and fragrance components. Manufacturing concentration in France, Italy, and Switzerland for premium beauty houses draws from specialized glass and aluminum packaging suppliers. Single-source vulnerability sits with exclusive distribution agreements tying Gebr. Heinemann to specific premium fragrance houses. Distribution runs through bonded warehouse networks with real-time customs verification at point-of-sale terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Passenger volume cyclicality tied to long-haul route recovery from Asia-Pacific markets defines this market's recovery trajectory. Concession renewal waves concentrate competitive tension into discrete bidding windows.
For Market Incumbents: Consolidate multi-airport concession portfolios ahead of synchronized lease expirations at Frankfurt and Munich. Deepen exclusive distribution agreements with premium beauty houses to defend against specialty fragrance operators. Vertical integration into bonded warehouse operations at Charles de Gaulle and Heathrow secures capacity during peak summer traffic. For New Entrants and Emerging Players: Differentiate on circular economy compliance by deploying refill station infrastructure aligned with EU Green Deal packaging mandates. Target Warsaw Chopin and Bucharest Henri Coandă as underpenetrated Eastern European transit hubs. Pre-order mobile platform partnerships with Air France-KLM and British Airways offer rapid customer acquisition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among multi-airport concession operators with integrated bonded supply chains and exclusive brand relationships. Long-term viability hinges on digital customs verification infrastructure deployment and biometric passenger flow integration. Monitor concession renewal announcement density as inflection indicator for competitive pricing pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Portfolio Consolidation | Scale advantages intensify bidding power at Heathrow and Charles de Gaulle renewal cycles. |
| Biometric Boarding Pass Integration | Amsterdam Schiphol facial recognition gates authenticate tax-free eligibility without document friction. |
| Refill Station Infrastructure | Permanent fragrance refill aligns with EU Green Deal mandates while capturing repeat terminal visits. |
| Exclusive Brand Distribution Capture | Gebr. Heinemann's premium house relationships demonstrate margin concentration in specialty fragrance. |
| Pre-Order Mobile Platform Launch | British Airways passenger adoption displaces impulse browsing with reserve-and-collect economics. |
Methodological Framework
A spread of perspectives from airport concession directors, bonded warehouse operators, premium beauty house regional managers, and airline ancillary revenue executives converged on the working assumptions. Primary interview insights combined with secondary validation from EU customs administration filings, EMA cosmetic ingredient safety guidelines, airport authority procurement records, and REACH chemical registration databases. Bottom-up passenger traffic modeling and top-down concession revenue estimates underwent triangulation across Schengen hub terminals.
Segmentation dimensions modeled include product category, distribution channel, customer type, and service type across the analysis window. CAGRs derived from passenger volume elasticity to long-haul route restoration and duty-free spend per passenger trajectories. Forecast inputs incorporated EU AI Act border processing implementation timelines and EU Green Deal packaging waste directive compliance costs.
Material uncertainties — aviation fuel cost volatility, concession renewal outcome distributions, and biometric verification adoption rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about passenger recovery pacing and regulatory implementation schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Hypersensitivity Market
Others
China 3D Printing Construction Market
Others
North America IT Device Market
Others
Tobacco Packaging Market
Others
Lychee Market
Others
Digital Mortgage Software Market
Others
Smart Home Solutions Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
Thiamethoxam Market
Others
Underwater Communication System Market
Others
Global Human Augmentation Market
Others
Video-As-A-Service (Vaas) Market
Others
Silicone Molding Machinery Market
Others
Server Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Global Pregnancy Tracker Apps Market