
 Corn Fiber Market | 2026-2036
Corn Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Fiber Market Analysis
Midwestern U.S. ethanol coproduct streams are restructuring how corn fiber isolates reach industrial buyers. Archer Daniels Midland Company leverages its Decatur, Illinois processing complex to sustain wet-milled fiber output for textile spinners. Cargill Inc. anchors North American supply through its Blair, Nebraska facility, where modified starch lines feed adjacent fiber recovery. Roquette Frères competes from its Lestrem plant in France, specializing in pharmaceutical-grade cellulosic fractions.
Corn fiber comprises the pericarp and endosperm cell wall residues separated during wet milling or dry grind ethanol production, typically yielding 60-85% cellulose and hemicellulose with lignin contents below 15%. Its primary industrial purpose centers on replacing petroleum-based feedstocks in spun textiles and thermoplastic composites where biodegradability commands specification premiums. Pulp fiber leads product type volumes due to mature integration with paperboard and molded packaging lines, while textile fiber claims the fastest expansion as denim mills substitute cotton blends. Food packaging applications concentrate margin pools because compostable film substrates require certified fiber purity tiers that command price premiums over standard textile grades.
The U.S. FDA regulates corn fiber intended for food contact under 21 CFR 176.170, while the EPA administers Renewable Fuel Standard coproduct pathways that affect fiber availability from ethanol plants. The EU REACH framework and F-Gas Regulation indirectly shape demand by restricting synthetic alternatives in automotive and packaging applications. Stakeholders must monitor how the EU Green Deal's bioplastics mandates and emerging U.S. state-level extended producer responsibility laws redefine qualification thresholds for corn fiber in certified compostable products.
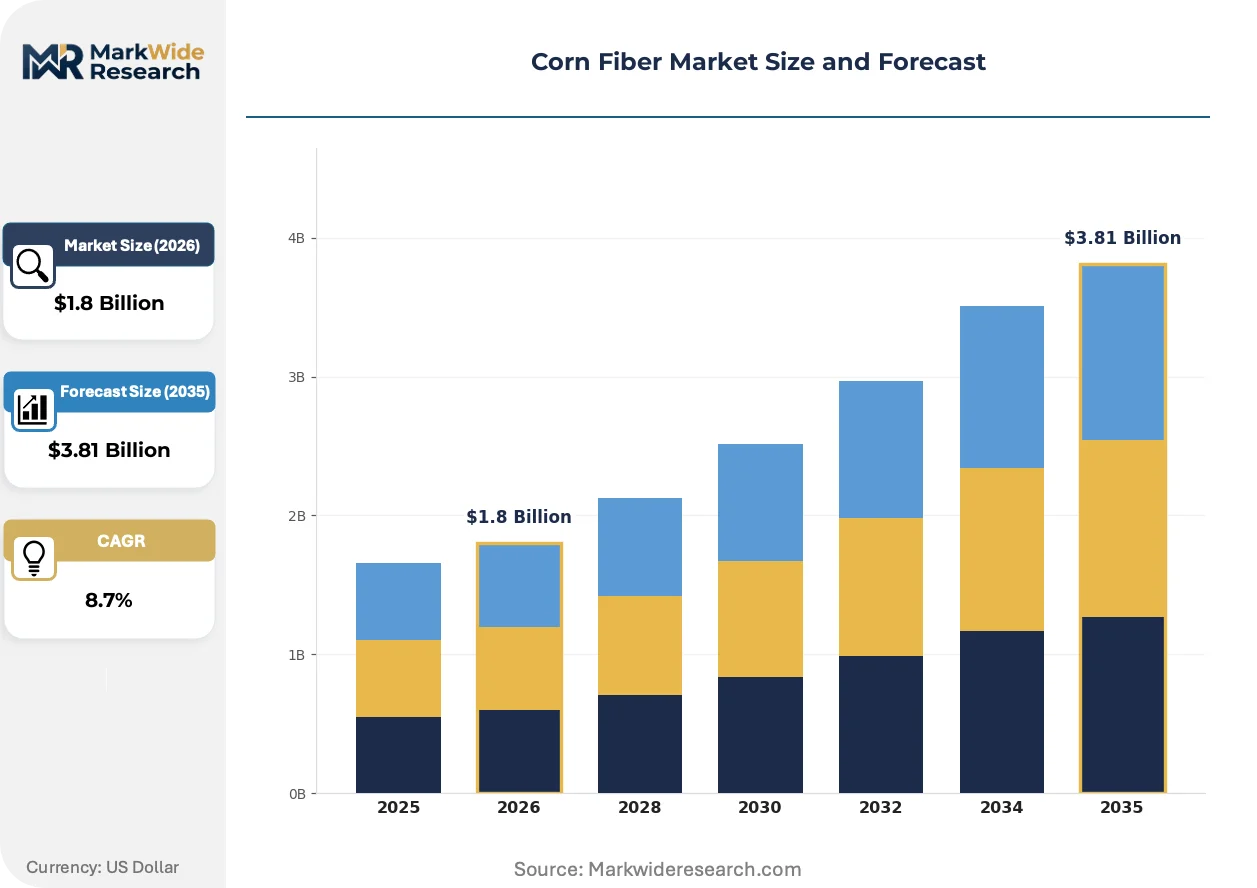
Market Dynamics
Ethanol plant coproduct economics are forcing corn fiber recovery upstream, as dry-grind facilities retrofit fiber separation to offset volatile distillers grain margins and capture premium cellulosic feedstock streams.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Compostable packaging mandates are pulling food-grade corn fiber into film substrates at certified purity tiers.
- Automotive lightweighting specifications:German OEMs now specify natural fiber composites for interior panels, creating dedicated offtake agreements with wet-mill processors.
- Cellulosic ethanol qualification pathways:The EPA's Renewable Fuel Standard coproduct definitions are incentivizing fiber recovery investments at Midwestern biorefineries.
Market Restraints
- Input cost volatility:Corn price swings transmitted through ethanol coproduct contracts compress fiber isolate margins unpredictably.
- Supply concentration risk:North American output clusters around Illinois and Nebraska processing complexes, exposing buyers to regional weather and logistics disruptions.
- Technical limitation:Lignin contents above 12% in dry-grind fiber streams restrict textile-grade spinning compatibility without capital-intensive bleaching.
Strategic Opportunities
- Underpenetrated geography:Brazilian ethanol producers lack fiber separation infrastructure, creating first-mover advantage for equipment-and-offtake joint ventures.
- Emerging application:Mycelium-composite packaging binders represent uncontracted demand for pharmaceutical-grade cellulosic fractions.
- Regulatory tailwind:The EU Green Deal's bioplastics production targets are accelerating compostable certification timelines that favor established corn fiber suppliers.
Industry Challenges
- Certification timeline compression:FDA 21 CFR 176.170 food-contact approvals and BPI compostable certifications now run sequentially, extending qualification cycles.
- Skill gap in fiber refinement:Wet-mill operators lack trained technicians for pharmaceutical-grade cellulosic fractionation, constraining high-margin output expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Fiber Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seed Fiber, Pulp Fiber, Textile Fiber, Non-Woven Fiber Application: Textiles, Bioplastics, Food Packaging, Composite Materials End User: Apparel Manufacturers, Automotive OEMs, Packaging Companies, Furniture Producers Form: Staple Fiber, Continuous Filament, Roving, Yarn |
| Companies Covered | Tate & Lyle PLC, Grain Processing Corporation, Archer Daniels Midland Company, J. Rettenmaier & Söhne GmbH & Co. KG, SunOpta Inc., Cargill Inc., Roquette Frères, Doshi Group, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Fiber Market Emerging Trajectories
Processing technology and regulatory classification are rewriting qualification pathways for corn fiber, compressing the gap between agricultural commodity and engineered material specifications.
Enzymatic fiber liberation is converging with mechanical refining systems to produce textile-grade pulp without chlorine bleaching sequences. Italian denim mills are trialing these semi-chemical pulps in cotton blends at 15-20% substitution rates. This convergence is collapsing the capital barrier between food-packaging and textile fiber production lines.
The EU F-Gas Regulation restrictions on synthetic refrigerants and foams are indirectly mandating bio-based thermal insulation in automotive and appliance applications. Corn fiber-derived binders are qualifying for these segments under REACH substance registration. German automotive suppliers are reformulating door panel cores to capture this regulatory displacement.
Specification-driven procurement now dominates food packaging converter buying, with certified compostable grades commanding dedicated supply contracts separate from standard textile fiber spot markets. Tier-one converters in France and the Netherlands are locking multi-year offtake with wet-mill processors to secure BPI and OK Compost certification continuity. This pattern is most visible in the Benelux cluster where extended producer responsibility laws activate in 2025.
Corn Fiber Market Segmentation
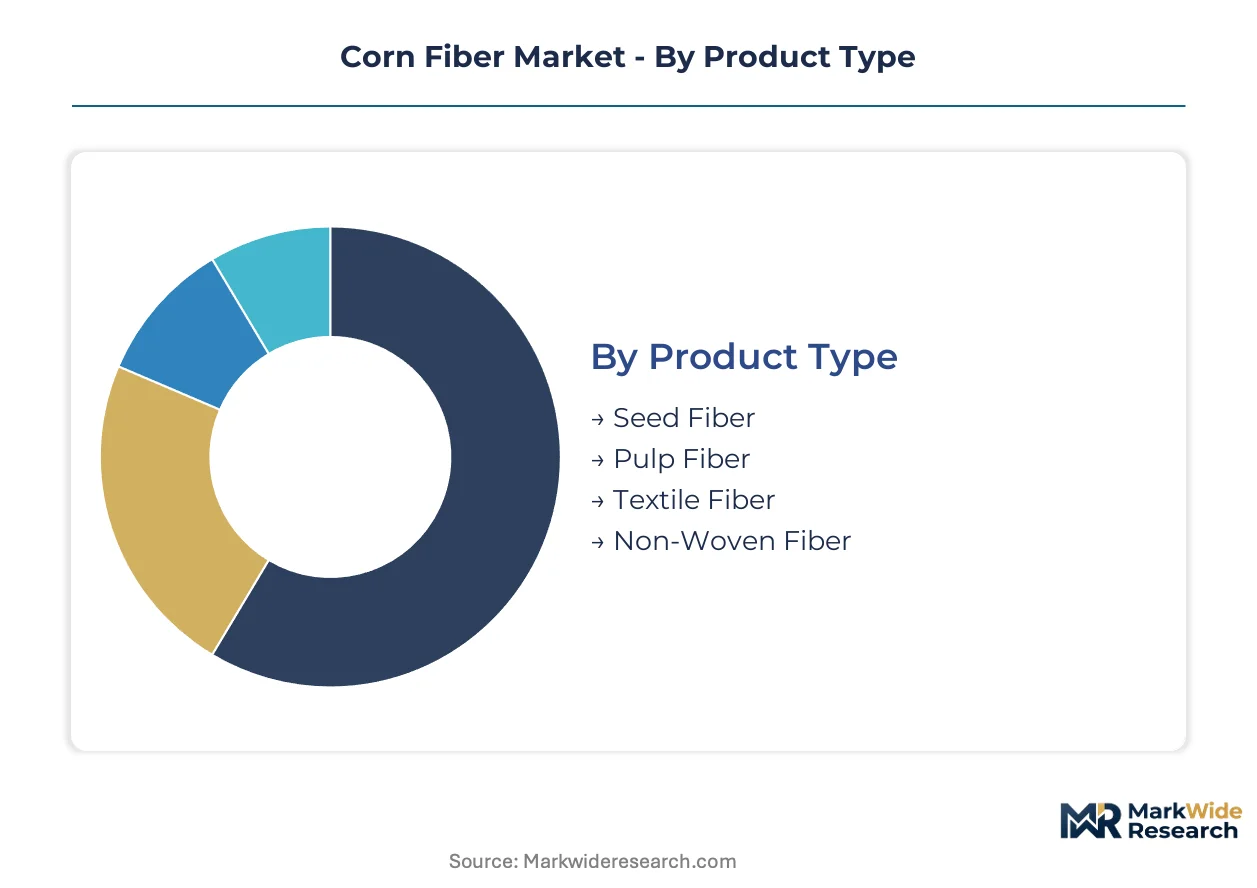
Corn fiber procurement splits sharply between high-volume commodity grades and certified premium tiers. Specification requirements from German automotive suppliers and EU food packaging converters are fragmenting what was once a uniform feedstock market into distinct quality bands with divergent pricing and supply chain structures.
Product Type:
Pulp fiber dominates volume flows while textile fiber captures specification premiums in denim mill trials.
- Pulp Fiber:Pericarp-rich fractions with 60-75% cellulose content integrate directly into paperboard and molded packaging lines without secondary refining. Wet-mill processors in Illinois and Nebraska supply this grade to corrugated converters seeking BPI certification for extended producer responsibility compliance.
- Textile Fiber:Endosperm cell wall isolates with hemicellulose fractions above 25% enable cotton-blend spinning at 15-20% substitution rates. Italian denim mills are trialing enzymatically liberated semi-chemical pulps to bypass chlorine bleaching sequences.
- Seed Fiber:Germ and tip-cap residues with elevated protein content suit animal feed binders and low-grade composite fillers.
- Non-Woven Fiber:Discontinuous staple grades serve automotive interior mat applications where thermal bonding replaces woven structures.
Today's leader: Pulp Fiber. Tomorrow's challenger: Textile Fiber.
Application:
Food packaging concentrates margin pools while composite materials expand through regulatory displacement of synthetics.
- Food Packaging:Certified compostable film substrates demand pharmaceutical-grade cellulosic purity tiers. Benelux converters are locking multi-year offtake agreements to secure OK Compost certification continuity ahead of 2025 extended producer responsibility activation.
- Composite Materials:Natural fiber thermoplastics for automotive door panels and seat backs now specify lignin content below 12%. German OEM procurement teams are rewriting interior specifications to capture EU F-Gas Regulation displacement of synthetic foams.
- Textiles:Cotton substitution in denim and home furnishings drives demand for bleached textile-grade isolates.
- Bioplastics:Cellulosic ethanol coproduct pathways under EPA Renewable Fuel Standard definitions are redirecting fiber streams toward polylactic acid blend feedstocks.
Food packaging commands the steepest premium trajectory. Composite materials are gaining share fastest through automotive lightweighting mandates.
End User:
Automotive OEMs impose the tightest specifications while apparel manufacturers offer the deepest volume absorption.
- Automotive OEMs:German interior suppliers now require natural fiber composites with REACH-registered binders for door panel cores. Tier-one processors are qualifying corn fiber-derived thermal insulation to replace restricted synthetic refrigerant foams.
- Apparel Manufacturers:Denim mills in Italy and Turkey are the primary offtakers for textile-grade fiber, absorbing semi-chemical pulp output at cotton substitution rates that justify dedicated supply contracts.
- Packaging Companies:French and Dutch converters dominate certified compostable film procurement, separating premium-grade spot markets from standard textile fiber contracts.
- Furniture Producers:Upholstery and panel applications represent emerging demand for non-woven fiber grades with lower purity requirements.
Automotive OEMs set the specification ceiling. Apparel Manufacturers provide the volume floor.
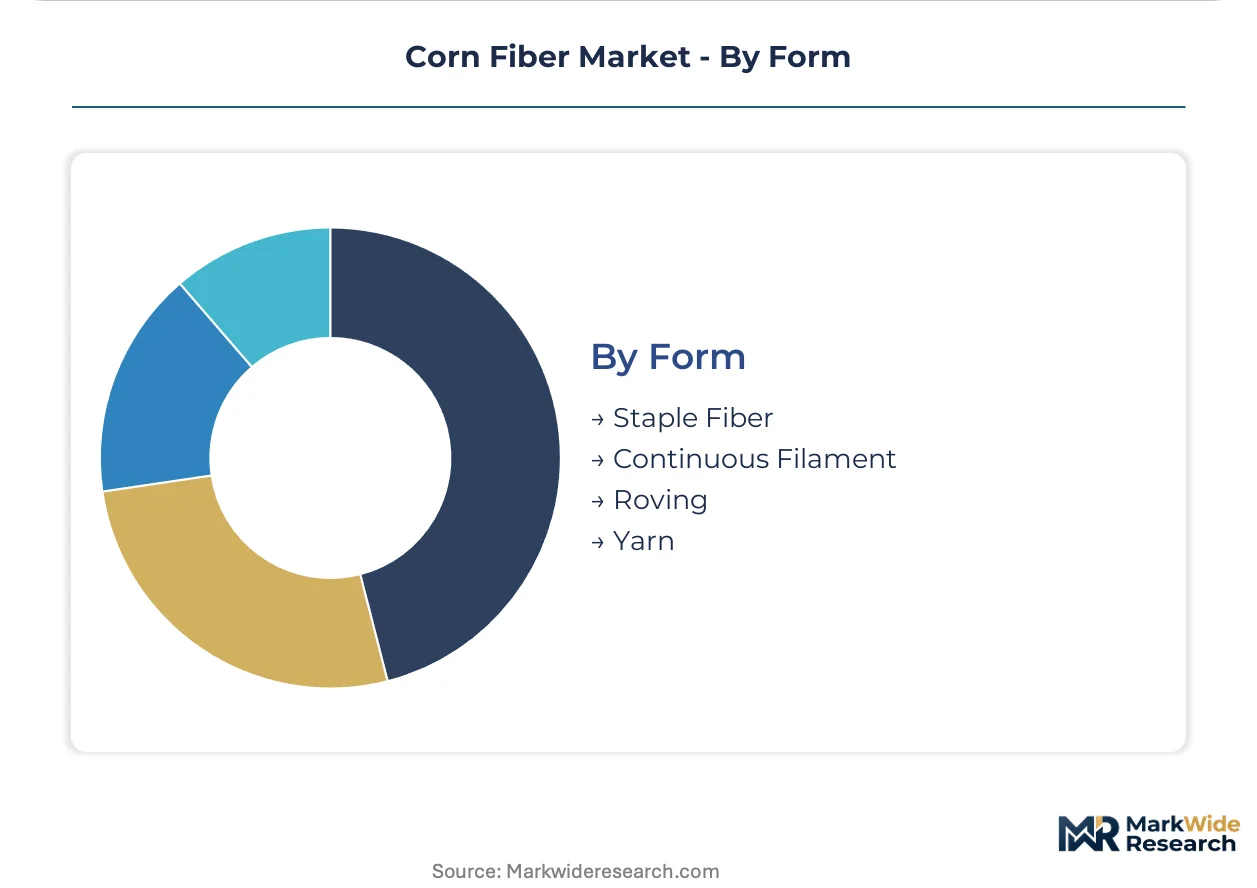
Form:
Staple fiber suits discontinuous processes while continuous filament enables woven textile integration.
- Staple Fiber:Discontinuous 3-6 centimeter lengths feed non-woven mat production and short-fiber thermoplastic compounding for automotive interiors.
- Continuous Filament:Extruded cellulosic streams enable direct yarn spinning for woven textile applications, though capital requirements limit supplier entry.
- Roving:Parallel fiber bundles serve pultrusion processes for structural composite profiles with unidirectional strength requirements.
- Yarn:Spun and finished thread forms reach apparel manufacturers through textile mill intermediaries, adding margin layers to the value chain.
Staple fiber anchors current output. Continuous filament represents the upstream integration target for wet-mill processors seeking margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting corn fiber investment toward jurisdictions where bio-based certification costs and extended producer responsibility timelines create competitive advantage for early movers.
United States
Midwestern ethanol coproduct streams supply textile spinners and packaging converters through Illinois and Nebraska processing clusters. The EPA's Renewable Fuel Standard coproduct definitions incentivize fiber recovery investments at biorefineries. Decatur, Illinois and Blair, Nebraska anchor North American output, with wet-mill processors securing dedicated offtake agreements for food-grade isolates.
Germany
Automotive OEM procurement teams specify natural fiber composites for interior door panels and seat backs, creating premium demand tiers. The EU F-Gas Regulation restricts synthetic foams, mandating bio-based thermal insulation alternatives. Suppliers in Baden-Württemberg and Lower Saxony are reformulating composite cores to capture this regulatory displacement.
France
Roquette Frères operates pharmaceutical-grade cellulosic fractionation from its Lestrem plant, serving European bioplastics and packaging markets. The EU Green Deal's bioplastics production targets accelerate compostable certification timelines. The Hauts-de-France cluster concentrates premium fiber refining capacity for BPI and OK Compost certified grades.
Italy
Denim mills in Lombardy and Veneto trial enzymatically liberated semi-chemical pulps at 15-20% cotton substitution rates. REACH framework restrictions on synthetic alternatives indirectly mandate bio-based textile inputs. Milan-area spinners are locking multi-year supply contracts to secure textile-grade fiber continuity.
Brazil
Ethanol producers lack fiber separation infrastructure despite massive corn processing volumes. ANVISA bio-based substance guidelines are tightening specifications for compostable feedstocks. São Paulo-state mills represent first-mover opportunity for equipment-and-offtake joint ventures targeting pharmaceutical-grade output.
Corn Fiber Market Vendor Landscape
North American processors anchor the volume-driven tier; European specialists hold premium-grade positioning through certification depth. Market structure splits between consolidated wet-mill operators with captive corn supply and fragmented regional refiners serving niche textile and pharmaceutical applications. Three archetypes dominate: integrated agribusiness conglomerates, pharmaceutical-grade cellulosic specialists, and regional ethanol coproduct processors. Competitive intensity centers on backward integration into corn sourcing and multi-year offtake contracting for certified compostable grades.
Among North American agribusiness conglomerates, Archer Daniels Midland Company and Cargill Inc. exemplify the integrated processor archetype with Midwestern wet-milling infrastructure. Roquette Frères occupies a position within the European pharmaceutical-grade specialization tier. These three entities represent distinct geographic and capability anchors: Decatur-based wet-milling at scale, Nebraska modified starch integration, and Lestrem pharmaceutical fractionation respectively.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Grain Processing Corporation |
| Archer Daniels Midland Company |
| J. Rettenmaier & Söhne GmbH & Co. KG |
| SunOpta Inc. |
| Cargill Inc. |
| Roquette Frères |
| Doshi Group |
| Ingredion Incorporated |
| Others |
Supply Flow & Price Mechanics
Captive wet-milling infrastructure in Illinois and Nebraska anchors both supply security and pricing power for North American processors, creating a structural advantage over European competitors who source through merchant corn markets. This backward integration into grain origination buffers fiber isolate margins against commodity volatility while enabling long-term offtake contracting with automotive OEMs and food packaging converters.
Pricing Analysis
Distributor margins on pharmaceutical-grade cellulosic fractions run 15-25 points above standard textile fiber spot markets, reflecting certification overhead and batch-traceability requirements. Three-tier pricing structure across BPI-certified compostable, REACH-registered automotive, and standard industrial grades separates premium tiers by purity specifications and documentation depth. Cost compression in standard pulp fiber is intensifying because dry-grind ethanol plants are flooding commodity channels with unrefined pericarp streams. Food packaging converters in the Benelux region show least price sensitivity, locking multi-year contracts to secure OK Compost certification continuity.
Supply Chain Analysis
Freight costs from Midwestern processing clusters to German automotive plants add 12-18% to delivered fiber isolate costs, favoring European wet-mill operators on landed price despite higher input grain costs. Supply concentrates in the United States, France, and Italy, with North American output anchored in Decatur and Blair processing complexes, European refining centered in Lestrem and Lombardy, and emerging Brazilian capacity projected for São Paulo-state ethanol retrofits. Raw material flows draw from corn wet-milling coproduct streams, modified starch line residuals, and dry-grind ethanol fiber separation retrofits. Single-source vulnerability runs through Illinois-Nebraska logistics corridors where weather disruptions and rail congestion cascade into delivery failures. Distribution runs through direct mill-to-converter contracts for certified grades and merchant spot markets for standard textile fiber.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification premiums widen as German OEMs and EU packaging converters consolidate procurement around certified compostable and REACH-registered grades. The demand shift toward pharmaceutical-grade cellulosic purity tiers rewards processors who invested in enzymatic liberation and chlorine-free bleaching sequences ahead of regulatory deadlines.
For Market Incumbents: Acquire pharmaceutical-grade fractionation assets in the Hauts-de-France cluster to capture EU Green Deal bioplastics procurement before certification timelines compress. Defend margin position by locking multi-year offtake with Benelux converters ahead of extended producer responsibility activation, while retrofitting Nebraska modified starch lines for textile-grade output to offset commodity pulp fiber erosion. The threat of Brazilian ethanol fiber separation infrastructure demands preemptive capacity positioning in South American joint ventures. For New Entrants and Emerging Players: Enzymatic fiber liberation without chlorine sequences offers entry into Italian denim mill supply chains where cotton substitution trials are expanding from 15% to 25% blend rates. White-space targets include mycelium-composite packaging binders for pharmaceutical-grade cellulosic fractions and automotive thermal insulation cores displacing F-Gas-restricted synthetic foams. The most penetrable segment is non-woven staple fiber for furniture upholstery, where purity requirements remain below textile-grade thresholds. A go-to-market angle anchored in REACH-registered binder formulations qualifies new suppliers for German OEM procurement lists without full BPI certification investment. For Investors and Strategic Acquirers: Consolidation pressure builds where wet-mill operators lack trained technicians for pharmaceutical-grade cellulosic fractionation, constraining high-margin output expansion and creating acquisition targets among regional ethanol coproduct processors. Long-term viability over the next decade hinges on backward integration into corn origination and certification depth rather than scale alone. The acquisition target archetype is mid-cap European refiners with OK Compost and BPI certifications but underutilized enzymatic liberation capacity. The signal to watch is German OEM specification releases for natural fiber composites, which trigger cascading contract lock-ins across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Origination | Captive grain supply from Illinois and Nebraska processing clusters secures fiber isolate margin stability against commodity volatility. |
| Pharmaceutical-Grade Fractionation Investment | Enzymatic liberation capacity at Lestrem and Hauts-de-France plants captures EU Green Deal bioplastics procurement premiums. |
| Multi-Year Offtake Contracting | Direct mill-to-converter agreements with Benelux packaging companies lock OK Compost certification continuity ahead of regulatory activation. |
| Brazilian Joint Venture Formation | Equipment-and-offtake partnerships with São Paulo-state ethanol producers establish first-mover position in underpenetrated South American supply. |
| REACH-Registered Binder Development | Automotive thermal insulation formulations qualify for German OEM procurement lists displacing F-Gas-restricted synthetic foams. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with wet-mill operations managers, automotive Tier 1 procurement leads, food packaging converter technical directors, and textile mill sourcing heads with secondary validation from EPA Renewable Fuel Standard filings, EU REACH substance registrations, BPI certification databases, and customs trade data on corn fiber isolate flows. Bottom-up volume estimates from individual processing facility outputs were triangulated against top-down demand projections from end-use industry consumption models.
Historical reference periods anchored the forecast window to pre-pandemic baseline capacity utilization and post-regulatory-shift demand inflection points across the projection horizon. Segmentation dimensions modeled include product type tier, application purity requirement, end-user specification intensity, and regional regulatory cluster. CAGRs were derived from slope analysis of segment-specific adoption curves calibrated to named OEM procurement timelines and converter certification deadlines. Industry-specific forecast inputs incorporated ethanol coproduct economics, enzymatic liberation technology maturation, and EU Packaging and Packaging Waste Regulation implementation pacing.
The model holds under stable corn-ethanol price relationships and continued EU bioplastics mandate enforcement; deviation in grain commodity volatility or regulatory timeline delays would shift fiber isolate margin projections and certification investment returns. Forecasts reflect assumptions about technology adoption rates, specification migration patterns, and trade flow configurations that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
Subtilisin Market
Others
Global Pregnancy Tracker Apps Market
Others
Global on-Demand Laundry Service Market
Others
Composite Copper Foil Production Equipment Market
Others
Nanomedicine for Drug Delivery Market
Others
Technical Films Market
Others
Aircraft Cameras Market
Others
Digital Mortgage Software Market
Others
Tripod Market
Others
Android STB and TV Market
Others
Insoluble Sulfur Market
Others
Hypersensitivity Market
Others
Retail Media Platform Market
Others
Global Military and Aerospace Sensors Market
Others
Global Aircraft Sensors Market