
 Reusable Wine Bags Market | 2026-2036
Reusable Wine Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Wine Bags Market Outlook
Market Context
China's manufacturing belt is reshaping cost structures for reusable wine bag production, with Zhejiang and Guangdong provinces adding specialized textile and packaging capacity. Ampac Holdings leverages vertical integration across film and fabric substrates to sustain margin control in North American distribution. Yiwu Youbai Packing anchors export volumes through Yiwu's consolidated logistics hub, while Wine Box Company Limited differentiates via rigid-board hybrid designs for premium retail channels.
Technical Definition and Segment Structure
Reusable wine bags are durable carriers engineered from laminated textiles or coated fabrics, typically incorporating padded dividers, thermal insulation layers, and reinforced handles to protect glass bottles during transport and storage. The product serves commercial beverage distribution, gift packaging, and consumer resale protection across retail and hospitality channels. Insulated configurations command premium positioning due to temperature-stable construction demanded by restaurant and event planner segments. Canvas and jute materials lead volume production, while customizable design options capture margin pools from corporate gifting and winery branding programs.
Regulatory Environment and Outlook
The European Union's REACH chemicals framework and Single-Use Plastics Directive constrain disposable alternatives while elevating durable textile standards for food-contact applications. California's SB 54 recycling mandates and France's AGEC anti-waste law impose extended producer responsibility on packaging supply chains, redirecting procurement toward certified reusable formats. Stakeholders must monitor evolving state-level packaging legislation and third-party durability certification requirements to secure channel access and avoid compliance-driven margin erosion.
Market Dynamics
The European Union's Single-Use Plastics Directive is compressing demand for disposable carriers while redirecting procurement budgets toward certified reusable formats across food-contact applications.
Growth Catalysts
- REACH textile standards:The EU's chemicals framework elevates durability certification requirements, forcing distributors to stock compliant reusable formats and expanding addressable market for qualified suppliers.
- Winery direct-to-consumer channels:Boutique producers in California and Oregon are expanding branded bag programs as fulfillment standards for wine club subscriptions and tasting room sales.
- Insulated thermal construction:Restaurant and event planner segments are specifying temperature-stable designs for outdoor service and catering logistics, creating premium positioning opportunities.
Market Restraints
- Polyester laminate cost volatility:Feedstock fluctuations for coated textiles compress margins for mid-tier producers lacking captive material supply.
- Yiwu logistics concentration:Export volume dependence on Zhejiang province's consolidated hub creates single-point vulnerability for North American and European replenishment cycles.
- California SB 54 compliance timelines:Extended producer responsibility mandates impose certification delays and testing costs that disadvantage smaller fabricators.
Strategic Opportunities
- Australian urban coastal markets:Sydney and Melbourne procurement offices are specifying reusable formats for municipal event licensing and hospitality procurement frameworks.
- Corporate gifting program expansion:Customizable jute and canvas designs are capturing margin pools from enterprise buyers seeking branded sustainability credentials.
- France AGEC anti-waste enforcement:Retail channel mandates for reusable packaging alternatives are accelerating shelf-space allocation for certified durable carriers.
Industry Challenges
- Durability certification testing:Third-party laboratory validation for wash-cycle performance and food-contact safety extends product launch timelines by four to six months.
- Legacy ERP integration:Winery and hospitality distributors require EDI connectivity for automated replenishment, forcing fabricators to absorb systems upgrade costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Wine Bags Market |
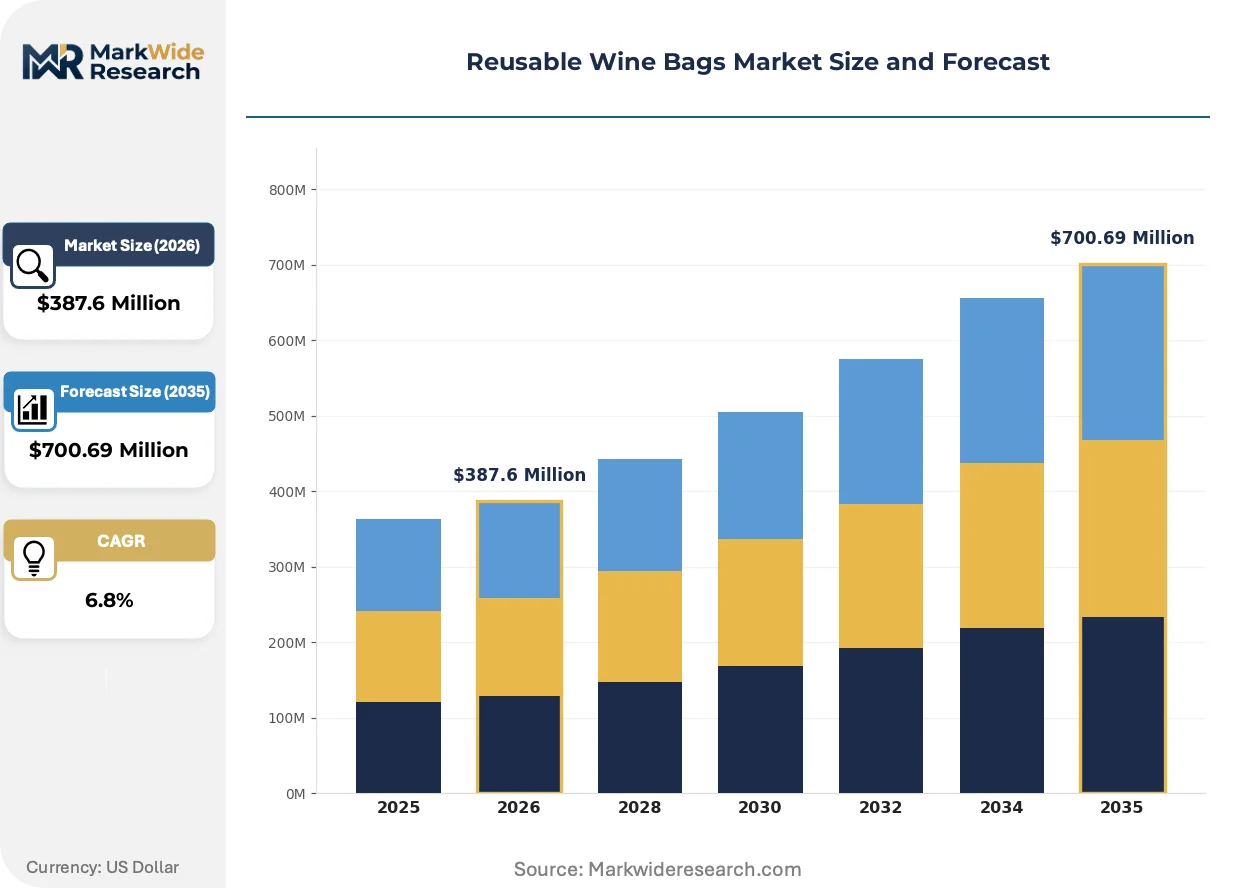
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Bottle, Multi-Bottle, Tote Style, Insulated Material: Canvas, Jute, Polyester, Cotton Design: Classic, Modern, Eco-Friendly, Customizable End User: Retailers, Restaurants, Event Planners, Consumers |
| Companies Covered | Ampac Holdings, LLC, Yiwu Youbai Packing Co., Ltd, Wine Box Company Limited, Acorn Paper Products Company, Initi Bag Manufacturer Co., Ltd, DM Packaging Company, Huizhou Union Packaging Co., Ltd, Dong-Gwang AMT Co., Ltd, Sueco San Prospero Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Wine Bags Market Strategic Shifts
Material science advances and regulatory enforcement timelines are compressing product development cycles while elevating performance specifications for thermal insulation and mechanical durability.
Phase-change material liners are migrating from medical cold-chain applications into wine bag thermal construction. Restaurant supply distributors in France and Australia are specifying these configurations for outdoor dining programs. The technology is migrating from niche pharmaceutical use toward mainstream hospitality procurement, compressing price premiums for basic insulated formats.
France's AGEC anti-waste law and California's SB 54 recycling mandates are imposing extended producer responsibility on packaging supply chains. Durable textile formats now require traceability documentation and end-of-life recovery plans. Boutique wineries in Oregon and direct-to-consumer fulfillment operations face the steepest compliance adjustments, accelerating supplier consolidation toward certified fabricators.
Wine club subscription models are displacing traditional retail replenishment patterns for reusable bag procurement. California and Oregon wineries are integrating branded carriers into membership fulfillment workflows, bypassing wholesale distribution. This channel compression is most visible in urban coastal markets where direct-to-consumer shipment volumes now exceed tasting room walk-in sales for mid-tier producers.
Reusable Wine Bags Market Segmentation
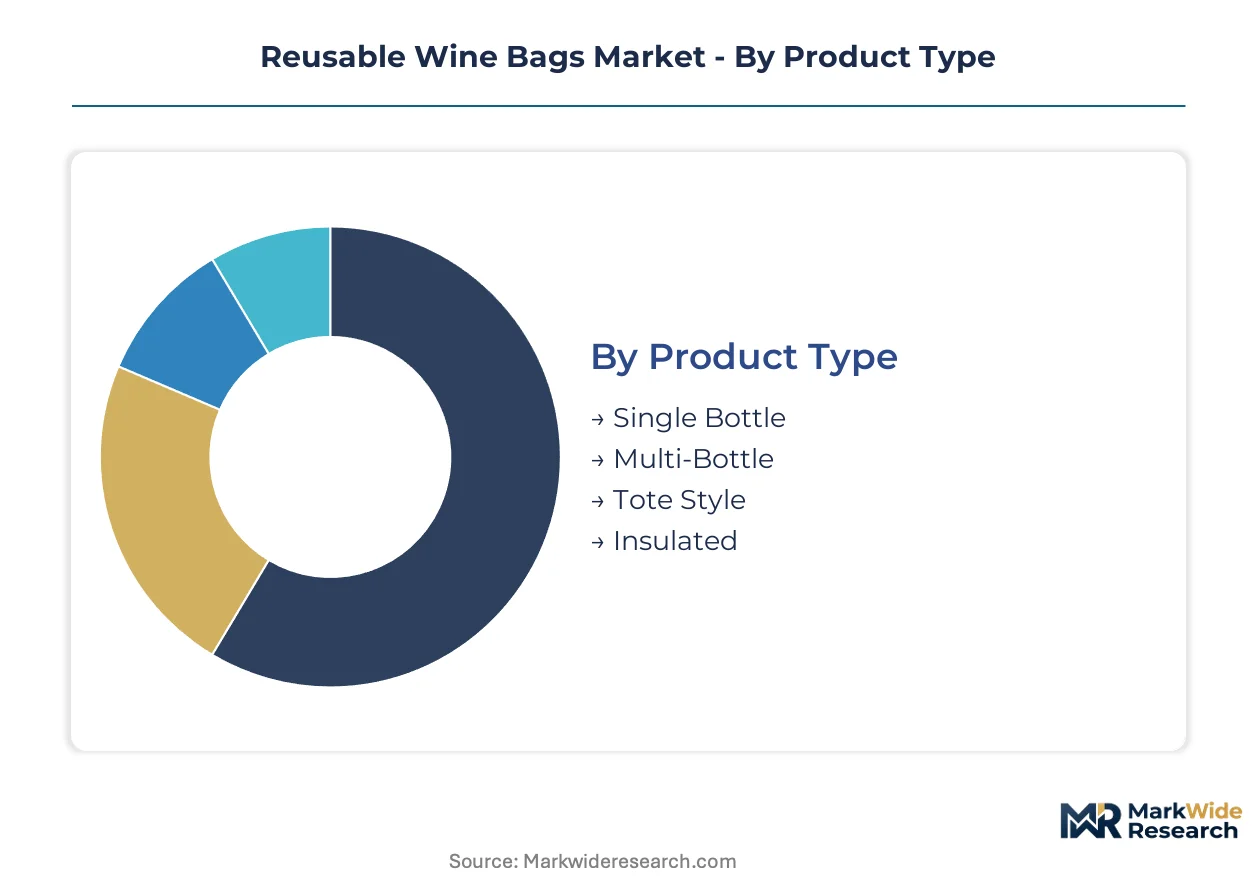
Segmentation in the reusable wine bags market reveals how procurement specifications diverge across temperature requirements, branding priorities, and regulatory compliance obligations. Understanding these divides allows suppliers to align production capacity with the highest-margin demand pools.
Product Type:
After-sales service intensity varies sharply by product type, with insulated formats requiring warranty support for thermal liner degradation while single-bottle units move through transactional retail channels with minimal post-purchase engagement.
- Single Bottle:Compact carriers engineered for individual glass bottle protection using padded dividers and reinforced base panels. Demand concentrates in California tasting room gift shops where walk-in visitors purchase impulse accessories alongside wine releases. Service requirements remain minimal due to simple construction.
- Multi-Bottle:Expanded capacity designs accommodating two to six bottles with modular compartment configurations. Restaurant distributors in France specify these formats for catering logistics and event provisioning, driving premium positioning through volume efficiency. Thermal stability specifications elevate supplier qualification thresholds.
- Tote Style:Open-top configurations prioritizing aesthetic presentation over enclosed protection. Urban consumers in Sydney and Melbourne favor these for casual transport and gift presentation.
- Insulated:Temperature-stable construction incorporating foam cores or phase-change liners for extended thermal protection. Outdoor dining programs in Australia and France mandate these specifications for regulatory compliance and food safety protocols.
Multi-bottle formats hold the largest share; momentum sits with insulated configurations as phase-change material costs decline.
Material:
Cost tier stratification across material categories determines margin architecture, with natural fibers commanding sustainability premiums while synthetic laminates offer volume scalability at compressed price points.
- Canvas:Heavy-duty cotton duck weave providing mechanical durability and printable surface for branding applications. Oregon wineries specify canvas for wine club subscription fulfillment, leveraging natural fiber credentials in direct-to-consumer marketing. REACH textile compliance adds certification overhead.
- Jute:Bast fiber construction offering biodegradability and rustic aesthetic positioning. Corporate gifting programs in France and Australia select jute for sustainability reporting requirements, though moisture sensitivity limits reuse cycles.
- Polyester:Coated synthetic substrates enabling waterproofing and thermal insulation integration. Zhejiang province fabricators dominate volume production through cost-optimized laminate extrusion.
- Cotton:Lightweight natural fiber for basic protection and promotional applications. California SB 54 compliance documentation is accelerating toward certified organic sourcing.
Polyester dominates volume throughput; canvas gains share fastest in premium branded channels.
Design:
Application context dictates design selection, with hospitality procurement frameworks prioritizing functional durability while gift channels emphasize aesthetic differentiation and customization flexibility.
- Classic:Traditional silhouettes with minimal ornamentation and neutral color palettes. Established French retailers stock these for conservative demographic segments resistant to trend-driven alternatives.
- Modern:Contemporary geometric forms and bold color blocking targeting urban professional consumers. Sydney municipal event licensing programs specify modern designs for visual coherence across vendor fleets.
- Eco-Friendly:Unbleached natural fibers, soy-based inks, and minimal packaging positioning for sustainability-certification requirements. AGEC anti-waste law enforcement in France is accelerating shelf-space allocation for these formats.
- Customizable:Modular construction enabling winery logo integration, variable capacity, and seasonal design refreshes. California and Oregon boutique producers leverage these for wine club retention and tasting room differentiation.
Customizable designs capture the highest margin pools; eco-friendly formats are climbing the fastest as extended producer responsibility mandates expand.
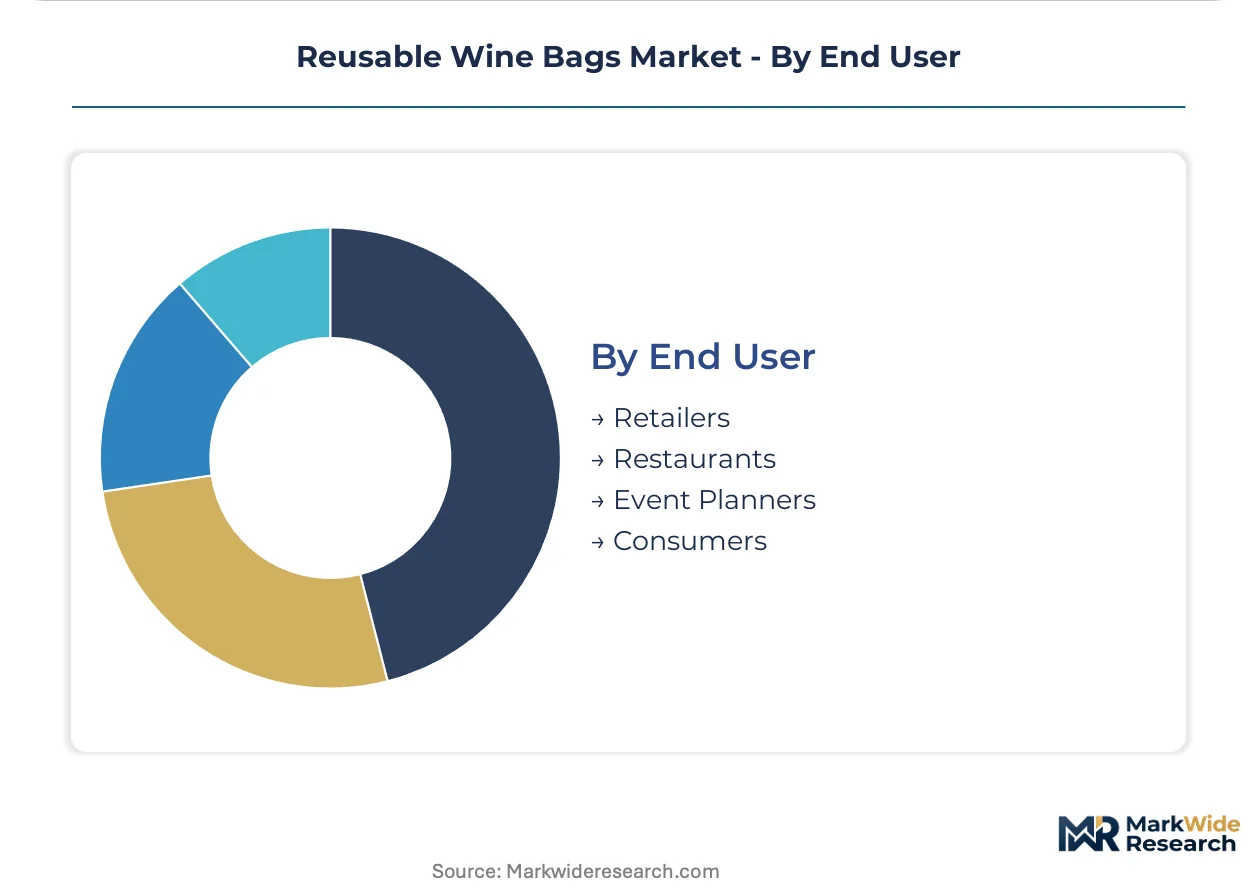
End User:
Customer type segmentation reveals divergent procurement authority structures, with enterprise buyers negotiating annual contracts against specification frameworks while consumer purchases remain price-sensitive and brand-driven.
- Retailers:Multi-format stocking requirements spanning impulse single-bottle units through premium gift sets. French retail channel mandates under AGEC are redirecting procurement toward certified reusable formats with traceability documentation.
- Restaurants:Thermal performance specifications for outdoor service and catering logistics. Melbourne and Sydney hospitality procurement offices specify insulated configurations for municipal event licensing compliance.
- Event Planners:Volume procurement with branding integration and rapid turnaround requirements. Corporate sustainability reporting obligations favor jute and canvas materials for client-facing events.
- Consumers:Individual purchase decisions driven by aesthetic preference, gift occasion, and price accessibility. Direct-to-consumer subscription models in California are displacing traditional retail replenishment patterns.
Retailers maintain the largest procurement volume; restaurants are expanding most quickly as outdoor dining programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang and Guangdong provinces anchor manufacturing capacity for reusable wine bags, while procurement demand concentrates in urban coastal markets across the United States, France, and Australia.
United States
California and Oregon wineries drive branded bag programs for direct-to-consumer subscription fulfillment. EPA and state-level frameworks under California's SB 54 impose extended producer responsibility mandates on packaging supply chains. Los Angeles and San Francisco Bay Area distributors specify certified reusable formats for wine club logistics.
France
Restaurant and hospitality procurement offices in Paris and Lyon mandate insulated thermal configurations for outdoor dining programs. AGEC anti-waste law enforcement redirects retail shelf-space toward durable carriers with traceability documentation. Île-de-France retail channels accelerate certified reusable format allocation under regulatory pressure.
Australia
Sydney and Melbourne municipal event licensing programs specify reusable wine bags for vendor fleet compliance. TGA food-contact safety standards elevate certification requirements for thermal insulation materials. New South Wales and Victoria hospitality procurement frameworks favor temperature-stable designs for catering logistics.
China
Zhejiang province fabricators dominate export volume production through Yiwu's consolidated logistics hub. MIIT industrial standards and dual carbon goals reshape cost structures for textile and packaging capacity expansion. Guangdong manufacturers add specialized coated fabric production for North American and European replenishment cycles.
Germany
REACH textile standards and EU Green Deal implementation elevate durability certification requirements for food-contact applications. Bavaria and North Rhine-Westphalia retail distributors stock compliant reusable formats under chemicals framework enforcement. Frankfurt and Munich procurement offices specify certified carriers for corporate gifting program expansion.
Reusable Wine Bags Market Competitive Environment
Specialized packaging fabricators and diversified material suppliers split the market into distinct capability tiers. The vendor base concentrates around textile lamination expertise and logistics integration rather than brand equity. Three archetypes dominate: vertically integrated substrate producers, export-focused contract manufacturers, and rigid-board hybrid specialists. Competitive moves center on backward integration into film and fabric supply chains and strategic positioning within certified supplier networks for regulated procurement channels.
Within the export-focused contract manufacturer tier, Yiwu Youbai Packing Co., Ltd and Huizhou Union Packaging Co., Ltd represent Zhejiang and Guangdong-based production clusters serving North American and European replenishment demand. Ampac Holdings, LLC occupies a position among North American distributors leveraging substrate control for margin stability. Wine Box Company Limited exemplifies the rigid-board hybrid archetype targeting premium retail channel differentiation. These three anchors illustrate how geographic production concentration and material specialization stratify competitive positioning across compliance-driven and brand-sensitive demand segments.
| Leading Market Players |
|---|
| Ampac Holdings, LLC |
| Yiwu Youbai Packing Co., Ltd |
| Wine Box Company Limited |
| Acorn Paper Products Company |
| Initi Bag Manufacturer Co., Ltd |
| DM Packaging Company |
| Huizhou Union Packaging Co., Ltd |
| Dong-Gwang AMT Co., Ltd |
| Sueco San Prospero Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure on coated textile imports from Zhejiang province determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic distribution of contract manufacturing capacity. Buyers facing landed cost volatility shift procurement toward certified fabricators with captive substrate supply, compressing margin pools for mid-tier distributors lacking backward integration.
Pricing Analysis
California's SB 54 extended producer responsibility mandates dictate the pricing tier structure across insulated, multi-bottle, and single-bottle formats. Certification grade and customization level drive price differentiation, with AGEC-compliant traceability documentation commanding premiums over basic reusable alternatives. Cost compression in polyester laminate feedstocks is intensifying because of petroleum derivative volatility, squeezing standard-tier fabricators most severely. Corporate gifting programs exhibit the least price sensitivity due to sustainability reporting requirements, while impulse retail consumers in tasting rooms remain highly elastic.
Supply Chain Analysis
Yiwu Youbai Packing, Huizhou Union Packaging, and Guangdong-based contract manufacturers hold the dominant export capacity for North American and European replenishment. Production draws from Zhejiang and Guangdong provinces in China, with secondary capacity emerging in Vietnam for basic canvas construction. Raw material dependencies center on coated polyester laminates, phase-change thermal liners, and REACH-certified textile dyes. Single-source vulnerability concentrates in Yiwu's consolidated logistics hub, where customs delays propagate across quarterly replenishment cycles. Distribution runs through winery direct-to-consumer fulfillment networks, hospitality procurement frameworks, and retail channel distributors with certified supplier mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wine club subscription platforms are displacing wholesale distribution, creating interoperability requirements between branded bag fulfillment and membership management systems that reshape competitive moats.
For Market Incumbents: Harden certification investment in REACH textile compliance and AGEC traceability documentation to defend against emerging rigid-board hybrid specialists capturing premium retail shelf-space. Deepen backward integration into coated fabric substrate production to offset polyester laminate cost volatility and sustain margin control across standard-tier volume contracts. For New Entrants and Emerging Players: Australian municipal event licensing programs in Sydney and Melbourne represent the most penetrable white-space, with procurement offices specifying reusable formats for vendor fleet compliance. Target corporate gifting programs in France seeking AGEC-compliant jute and canvas designs with rapid customization turnaround. A direct-to-consumer fulfillment partnership model with Oregon boutique wineries offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: France's AGEC anti-waste enforcement timeline reshapes the acquisition landscape toward certified fabricators with established traceability documentation and end-of-life recovery plans. Long-term viability centers on suppliers positioned for extended producer responsibility expansion across EU member states. The target archetype combines Zhejiang manufacturing scale with European certification infrastructure. Watch insulated format adoption rates in Australian outdoor dining programs as the signal for thermal construction demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment in REACH Compliance | REACH textile standards from ECHA elevate durability requirements for EU channel access. |
| Backward Integration into Coated Fabric Production | Captive substrate supply from Zhejiang extrusion capacity insulates margin from petroleum volatility. |
| Direct-to-Consumer Fulfillment Partnership | Wine club subscription models in California bypass wholesale distribution compression. |
| Phase-Change Thermal Liner Integration | Restaurant procurement in France and Australia mandates temperature-stable construction for outdoor service. |
| Traceability Documentation Infrastructure | AGEC anti-waste law enforcement requires end-of-life recovery plans for retail shelf-space allocation. |
Study Parameters
A spread of perspectives from winery operations directors, hospitality procurement managers, packaging fabricator executives, and retail category buyers converged on the working assumptions for demand segmentation and pricing tier boundaries. Primary fieldwork combined structured interviews with secondary validation against customs trade records, EU regulatory filings from ECHA and national implementation agencies, and SEC disclosures from diversified material suppliers. Bottom-up volume estimates from production capacity utilization triangulated against top-down demand projections from wine club subscription growth and municipal procurement frameworks.
Demand-supply balance modeling across the projection horizon anchored volume forecasts to replenishment cycle patterns and certification adoption curves. Segmentation dimensions included product type, material substrate, design positioning, and end-user procurement authority, with thermal performance tier and regulatory compliance grade as wine-industry-specific overlays. CAGRs derived from fitted growth curves applied to base-year estimates, with cross-checks against historical adoption rates for comparable durable packaging categories. Forecast inputs incorporated phase-change material cost decline trajectories and extended producer responsibility enforcement timelines.
The forecast holds incumbent behavior within observed patterns; aggressive certification acceleration by Zhejiang-based vertically integrated producers or sudden tariff restructuring on coated textile imports would shift outcomes materially. Quarterly review of AGEC enforcement actions, REACH textile standard updates, and wine club subscription growth rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Recruitment and Staffing Market
Others
Global Mobile Gambling Market
Others
UK Real Estate Hospitality Market
Others
Inorganic Tin Chemicals Market
Others
Mobile MRI Services Market
Others
Global on-Demand Laundry Service Market
Others
North America Commercial Vehicles Lubricants Market
Others
Smart Card Market
Others
Electric Pallet Jack Truck Market
Others
Global Hair Loss Treatment Products Market
Others
Spain Feed Additives Market
Others
Global Smart Home Installation Service Market
Others
Safety Critical Software Testing Market
Others
Global Learning Analytics Market
Others
Banknote Printing Machine Market
Others
Remanufacturing-as-a-Service (RaaS) Market