
 Mexico Digital Thermometer Market | 2026-2036
Mexico Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Digital Thermometer Market Insights
Clinical-grade accuracy certification is reorganizing procurement priorities across Mexican healthcare channels. Omron Corporation leverages its longstanding presence in Latin American diagnostics to sustain shelf visibility in major pharmacy chains. Microlife Corporation anchors its position through specialized distribution partnerships with regional medical suppliers. M. Meditech de México competes on localized assembly capabilities that reduce import dependency for public sector tenders.
A digital thermometer is an electronic temperature measurement instrument utilizing thermistors or infrared sensors to convert thermal radiation or contact heat into digital readings, typically displaying precision to 0.1 degrees Celsius for clinical decision-making. The device serves primary temperature screening functions across outpatient, inpatient, and domestic health monitoring environments. Infrared product types dominate hospital procurement due to non-contact speed and reduced cross-contamination risk, while smart technology segments capture expanding margin pools through app-connected fever tracking. Home care end users represent the fastest-growing structural segment as post-pandemic self-monitoring habits persist among Mexican families.
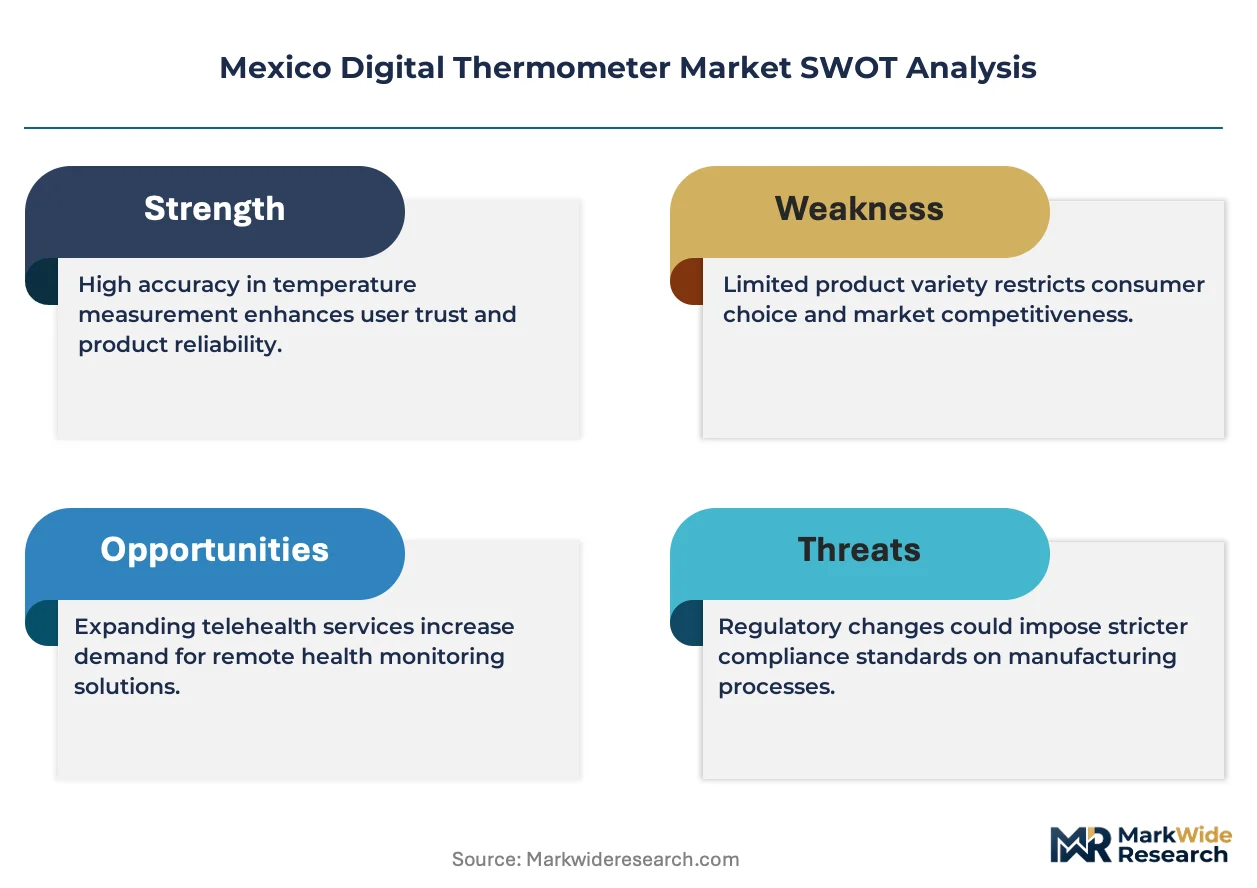
COFEPRIS, Mexico's national health regulator, enforces medical device registration and post-market surveillance that directly determines which imported digital thermometers gain commercial authorization. NOM standards for electrical safety and electromagnetic compatibility create additional compliance layers for manufacturers seeking market access. Stakeholders must monitor evolving COFEPRIS equivalency agreements with foreign regulators to anticipate streamlined approval pathways or new technical barriers.
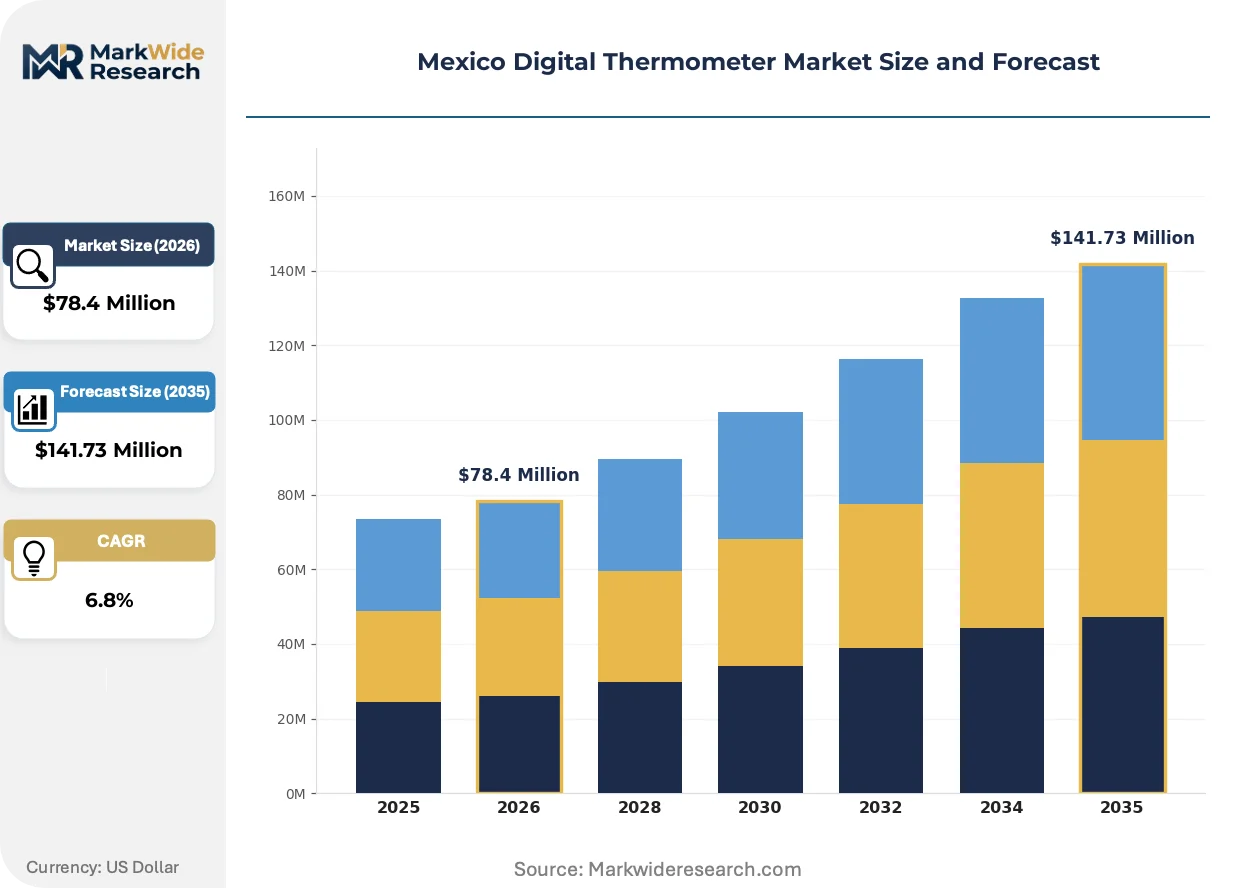
Market Dynamics
COFEPRIS registration requirements are tightening quality thresholds for imported digital thermometers, forcing distributors to prioritize clinical-grade accuracy certification over price competitiveness in procurement negotiations.
Growth Catalysts
- Chronic disease prevalence:Mexican households managing diabetes and cardiovascular conditions drive sustained demand for home-based temperature monitoring.
- NOM electrical safety standards:Compliance with electromagnetic compatibility mandates creates barriers that favor established suppliers with testing infrastructure.
- Post-pandemic habits:Self-monitoring behaviors persist among families in Mexico City and Estado de México corridors.
Market Restraints
- Import dependency:Concentrated sourcing from Asian manufacturing clusters exposes distributors to shipping cost volatility and extended lead times.
- COFEPRIS equivalency uncertainty:Shifting recognition agreements with foreign regulators create unpredictable approval timelines for new product entries.
- Smartphone-based alternatives:Third-party fever-tracking applications reduce willingness to pay for standalone connected devices.
Strategic Opportunities
- Localized assembly:Captive production capabilities in Mexican industrial zones reduce tariff exposure for public sector tenders.
- Telehealth integration:App-connected thermometers that stream data to remote clinicians capture emerging reimbursement pathways.
- Pharmacy channel expansion:Direct-to-retail distribution partnerships bypass traditional medical supplier intermediaries.
Industry Challenges
- COFEPRIS post-market surveillance:Mandatory adverse event reporting systems require dedicated regulatory affairs staffing that strains mid-size importers.
- Legacy system integration:Hospital information systems in public facilities lack standardized APIs for connected device data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Digital Thermometer Market |
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared, Oral, Rectal, Ear End User: Hospitals, Clinics, Home Care, Pharmacies Technology: Bluetooth, Wi-Fi, Manual, Smart Distribution Channel: Online Retail, Medical Suppliers, Drugstores, Supermarkets |
| Companies Covered | Omron Corporation, Terumo Corporation, Microlife Corporation, Exergen Corporation, AMETEK, Inc., Spectris plc, A&D Company, Limited, PCE Holding GmbH, M. Meditech de México, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Digital Thermometer Market Trends and Innovations
Infrared sensing architectures are reshaping competitive positioning across Mexican healthcare procurement channels, with speed and hygiene protocols now outweighing unit cost in tender evaluations.
Thermopile array sensors is supplanting single-point infrared detectors in hospital-grade non-contact thermometers. Major public hospital systems in Mexico City deploy these units for mass triage screening. The technology is supplanting slower contact-based methods in emergency department workflows.
COFEPRIS medical device registration timelines have extended following implementation of enhanced technical documentation requirements. Distributors now front-load quality management system investments to preempt review cycles. Imported infrared units face particular scrutiny under electromagnetic compatibility testing protocols.
Direct sourcing from manufacturers is fragmenting traditional medical supplier relationships. Large pharmacy chains in Guadalajara and Monterrey now negotiate volume contracts bypassing regional distributors. This pattern concentrates procurement leverage among retail buyers with national footprint scale.
Mexico Digital Thermometer Market Segmentation
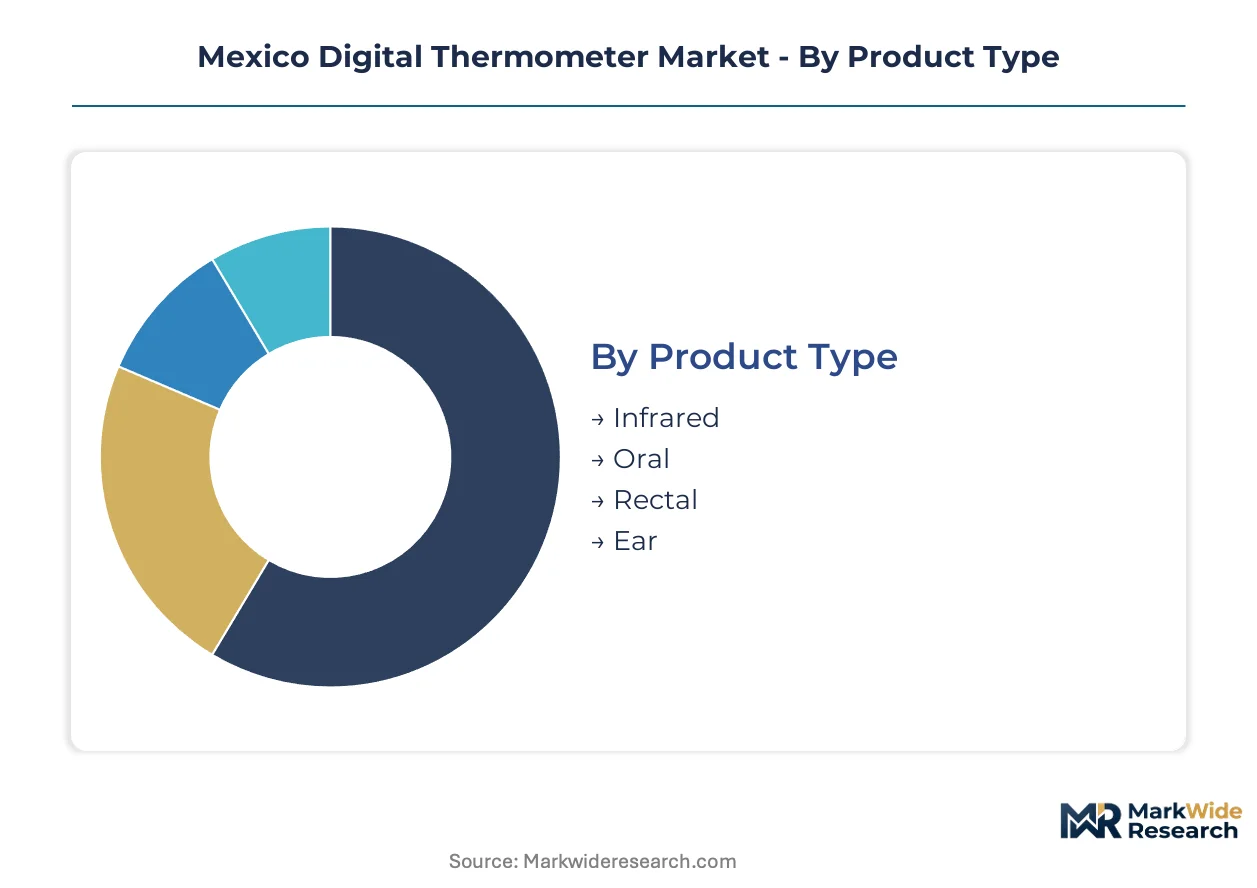
COFEPRIS registration pathways diverge sharply across product architectures, with infrared and connected devices facing electromagnetic compatibility scrutiny that manual units bypass. Procurement officers in Mexican healthcare systems weight these compliance burdens against clinical utility when allocating budgets across thermometer categories.
Product Type:
COFEPRIS electromagnetic compatibility testing protocols impose differentiated certification burdens across contact and non-contact architectures, reshaping import economics for distributors serving Mexican healthcare channels.
- Infrared:Thermopile array sensors capture thermal radiation for non-contact readings in 1-2 seconds. Hospital systems in Mexico City prioritize these units for emergency department triage workflows where speed and reduced cross-contamination risk outweigh unit cost premiums.
- Oral:Thermistor-based contact sensors deliver 0.1-degree precision for routine outpatient monitoring. Clinics in Guadalajara and Monterrey standardize on these units for cost-efficient fever screening in high-volume primary care settings.
- Rectal:Specialized probe designs serve neonatal and critical care applications requiring core temperature accuracy.
- Ear:Tympanic membrane targeting enables rapid pediatric assessment in family practice environments.
Established volume favors oral thermometers; emerging adoption favors infrared.
End User:
Procurement authority concentrates differently across institutional buyers and retail channels, with public sector tenders demanding localized assembly capabilities that private clinics rarely require.
- Hospitals:Large-scale procurement through ISSSTE and IMSS systems mandates NOM electrical safety compliance and extended warranty terms. Public hospital networks in Estado de México corridors specify infrared units for mass screening protocols.
- Home Care:Post-pandemic self-monitoring habits persist among Mexican families managing chronic conditions. Households in Mexico City metropolitan zone drive replacement cycles for app-connected units with fever history logging.
- Clinics:Independent physician practices prioritize unit cost over connectivity features for routine patient intake.
- Pharmacies:Retail health counters serve walk-in temperature screening demand with mid-tier oral and ear models.
Institutional procurement anchors current revenue; direct-to-consumer channels are climbing the fastest.
Technology:
Connectivity premiums fragment across customer segments willing to pay for data integration versus price-sensitive buyers satisfied with standalone functionality.
- Smart:App-connected architectures stream temperature logs to telehealth platforms. Reimbursement experiments by Mexican insurers for remote patient monitoring create tentative demand pull in diabetes management programs.
- Bluetooth:Local device pairing enables family health record consolidation without cloud dependency. Younger households in Monterrey tech corridors show preference for these intermediate connectivity tiers.
- Manual:Battery-powered LCD displays dominate price-sensitive rural pharmacy channels.
- Wi-Fi:Direct cloud upload capabilities serve institutional remote monitoring deployments.
Manual units retain rural penetration; smart connectivity shows steepest expansion trajectory.
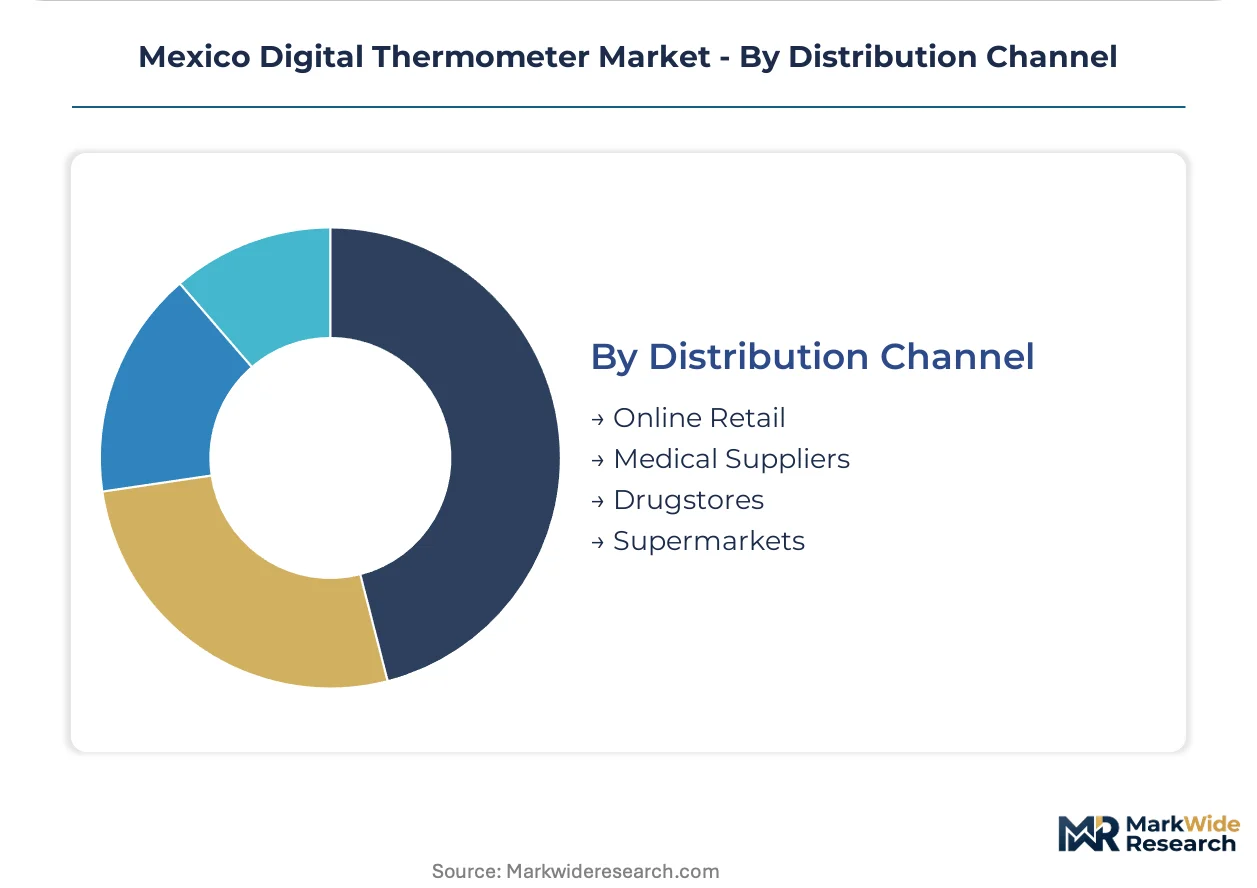
Distribution Channel:
Channel control is shifting as pharmacy chains consolidate procurement leverage and medical supplier intermediaries face disintermediation pressure.
- Medical Suppliers:Traditional regional distributors maintain relationships with public hospital procurement offices. COFEPRIS import documentation support and after-service networks defend their position in institutional channels.
- Online Retail:Marketplace platforms capture comparison-shopping behavior among tech-adopting households. Mercado Libre and Amazon Mexico listings expose price transparency that pressures brick-and-mortar premiums.
- Drugstores:Farmacias Guadalajara and similar chains negotiate direct manufacturer contracts bypassing wholesale tiers.
- Supermarkets:Mass retail placement captures impulse purchases during seasonal illness peaks.
Medical supplier relationships defend institutional share; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity concentrates in Mexican industrial zones serving public health procurement. Regional demand patterns diverge sharply between metropolitan health corridors and rural pharmacy networks. COFEPRIS regulatory harmonization varies across state-level health system implementations.
Mexico City Metro
ISSSTE and IMSS hospital networks anchor institutional thermometer procurement at scale. COFEPRIS headquarters proximity accelerates registration processing for distributors maintaining local regulatory affairs teams. The Estado de México corridor hosts specialized medical device logistics clusters serving the capital's screening protocols.
Nuevo León
Monterrey's manufacturing base supports localized assembly operations reducing import dependency for northern hospital systems. The state's industrial parks attract medical device producers seeking tariff-advantaged production for public tenders. Private hospital chains in the metropolitan zone specify connected thermometer architectures for telehealth integration.
Jalisco
Guadalajara's pharmacy retail density drives consumer-channel volume for mid-tier oral and ear thermometer models. The state's medical supplier distribution networks maintain traditional relationships with independent clinics. Regional COFEPRIS field offices enforce post-market surveillance protocols for imported inventory.
Bajío Region
Querétaro and Guanajuato industrial corridors host contract manufacturing for infrared sensor assemblies. Automotive supplier parks adjacent to medical device production create shared logistics infrastructure. State health ministries in the region prioritize cost-efficient procurement for rural clinic networks.
Northern Border States
Chihuahua and Baja California maquiladora operations capture cross-border supply chain efficiencies for US-market thermometer production. COFEPRIS-FDA equivalency discussions create uncertainty for dual-market product registrations. Tijuana medical device clusters serve export-oriented manufacturing with limited domestic market penetration.
Mexico Digital Thermometer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Mexican healthcare procurement channels. The market structures around three tiers: multinational diagnostic brands with COFEPRIS-established registrations, regional distributors with localized assembly capabilities, and price-focused importers serving rural pharmacy networks. Strategic differentiation concentrates on regulatory compliance speed, public tender eligibility, and pharmacy chain direct contracting. Competitive moves prioritize distribution partnership consolidation and captive production investments in Mexican industrial zones.
Among Japan-based diagnostic specialists, Omron Corporation and Terumo Corporation occupy positions anchored by longstanding Latin American market presence. Microlife Corporation represents the specialized distribution partnership archetype through regional medical supplier relationships. M. Meditech de México exemplifies localized assembly capabilities that reduce import dependency for ISSSTE and IMSS procurement cycles.
| Leading Market Players |
|---|
| Omron Corporation |
| Terumo Corporation |
| Microlife Corporation |
| Exergen Corporation |
| AMETEK, Inc. |
| Spectris plc |
| A&D Company, Limited |
| PCE Holding GmbH |
| M. Meditech de México |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between ISSSTE procurement offices and established distributors lock in both infrared thermometer supply access and price visibility across multi-year public health agreements. COFEPRIS registration timelines and NOM electrical safety compliance costs embed predictably into these arrangements, insulating contracted volumes from spot-market volatility affecting unregistered imports.
Pricing Analysis
COFEPRIS electromagnetic compatibility certification dictates the pricing tier structure across Mexican healthcare procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates hospital-grade infrared units with thermopile arrays from clinic-standard oral models and basic pharmacy-channel manual devices. Cost compression in the economy tier is intensifying because smartphone-based fever-tracking applications reduce willingness to pay for standalone connected devices. Rural pharmacy networks show highest price sensitivity, while ISSSTE hospital systems prioritize clinical-grade accuracy over unit cost.
Supply Chain Analysis
Inventory buffers at Tijuana and Laredo logistics hubs currently stretch to 8-12 weeks for infrared sensor assemblies, reflecting extended lead times from Asian manufacturing clusters. Component sourcing draws from China for thermopile sensors, Taiwan for microcontroller units, and Malaysia for plastic housings. Single-source vulnerability concentrates in thermopile array supply where two dominant producers control hospital-grade specifications. Distribution runs through regional medical suppliers for institutional channels, while pharmacy chains increasingly negotiate direct manufacturer contracts bypassing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
COFEPRIS registration pathway acceleration represents the decisive inflection for market access, transforming compliance speed into sustainable competitive advantage as quality thresholds tighten for imported digital thermometers.
For Market Incumbents: Consolidate distribution partnerships with Farmacias Guadalajara and similar retail chains before pharmacy channel disintermediation accelerates. Deepen captive production investments in Nuevo León industrial parks to reduce tariff exposure for IMSS tenders and defend margin position against emerging local assemblers. For New Entrants and Emerging Players: Lead with telehealth-integrated smart thermometer architectures targeting Monterrey's private hospital chains where reimbursement experiments for remote patient monitoring create tentative demand pull. Bypass saturated Mexico City procurement corridors; instead penetrate Guadalajara's independent clinic networks through specialized distribution partnerships with established regional medical suppliers. For Investors and Strategic Acquirers: COFEPRIS-registered distributors with established ISSSTE relationships and in-house regulatory affairs teams offer the most defensible acquisition profile for long-term viability. Watch for equivalency agreement announcements between COFEPRIS and foreign regulators as the critical signal indicating streamlined approval pathways or new technical barriers reshaping import economics.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Registration Acceleration | Compressed approval timelines unlock institutional procurement eligibility before competitors complete documentation cycles. |
| Localized Assembly Investment | Nuevo León production capacity reduces import dependency for public sector tenders subject to domestic content preferences. |
| Pharmacy Chain Direct Contracting | Bypassing medical supplier intermediaries captures margin pools as retail buyers consolidate national procurement leverage. |
| Telehealth Platform Integration | App-connected architectures align with Mexican insurer reimbursement experiments for remote patient monitoring programs. |
| Thermopile Array Technology Licensing | Hospital-grade sensor access differentiates positioning in ISSSTE emergency department triage procurement. |
Research Methodology
Operator-level perspectives from hospital procurement managers, COFEPRIS regulatory affairs consultants, medical supplier distribution heads, and pharmacy chain category buyers anchored the qualitative base for this study. Primary interview insights combined with secondary validation from COFEPRIS registration databases, IMSS procurement records, NOM standards documentation, and customs import statistics. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, end user, technology, and distribution channel dimensions.
Sensitivity analysis tested forecast robustness across COFEPRIS equivalency agreement scenarios, tariff rate assumptions, and telehealth reimbursement adoption curves over the projection horizon. Segmentation modeling captured product architecture splits, institutional versus retail channel dynamics, connectivity tier penetration, and regional industrial zone production capacity. CAGRs derived from trend extrapolation anchored in chronic disease prevalence trajectories and post-pandemic self-monitoring habit persistence among Mexican households.
The analysis sits within stated boundaries; outcomes outside sustained COFEPRIS regulatory tightening or accelerated telehealth platform adoption would require recalibration. Forecasts reflect documented assumptions regarding import dependency patterns and pharmacy channel consolidation velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Photoelectric Sensor Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
Occupancy Sensor Market
Sensors and Controls
Torque Sensor Market
Sensors and Controls
Meteorological Equipment Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
Global RFID Sensor Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Industrial Wireless Sensor Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Europe Human Machine Interface Market