
 Bio-FET Market | 2026-2036
Bio-FET Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-FET Market Insights
Software-defined calibration layers is repositioning what Bio-FET vendors monetize, shifting revenue from hardware sales to recurring analytical service contracts. Thermo Fisher Scientific leverages its installed base of laboratory automation to bundle Bio-FET modules with cloud-based data interpretation. Samsung Biologics anchors its strategy in captive semiconductor fabrication, integrating sensor wafer production with biologic assay development. Lonza Group specializes in contract manufacturing of custom Bio-FET arrays for pharmaceutical toxicology programs.
A Bio-FET (Bio-Field Effect Transistor) is a solid-state biosensor that transduces biomolecular binding events into measurable electrical signals through gate surface functionalization with receptors such as antibodies, enzymes, or aptamers, typically operating at sub-nanomolar detection limits for proteins and nucleic acids. The device serves industrial and commercial purposes in real-time, label-free molecular detection for drug screening, clinical diagnostics, and environmental surveillance. Si-based platforms dominate current manufacturing volumes due to mature CMOS foundry compatibility and economies of scale in wafer processing. Graphene channels represent the fastest-growing material segment, driven by superior carrier mobility and surface-area-to-volume ratios that enable single-molecule resolution. Diagnostic tools command the largest technology revenue pool, though therapeutic device applications are expanding as closed-loop bioelectronic medicine gains clinical traction.
The FDA regulates Bio-FET devices intended for clinical diagnostics under in vitro diagnostic device pathways, while the EPA sets performance benchmarks for environmental monitoring deployments. The EU MDR and REACH frameworks impose biocompatibility and substance restriction requirements on sensor materials entering European healthcare and environmental markets. Stakeholders must monitor how converging semiconductor export controls and medical device cybersecurity standards reshape supply chain access and product qualification timelines.
Market Dynamics
Semiconductor foundry consolidation near life science clusters is compressing sensor-to-assay development cycles, while software-defined calibration layers are converting hardware vendors into recurring-revenue service providers.
Growth Catalysts
- EU MDR performance validation mandates:Point-of-care biosensor manufacturers must demonstrate clinical equivalence under tightened conformity assessment pathways, accelerating replacement of legacy electrochemical platforms with solid-state architectures.
- Pharmaceutical toxicology programs:Contract research organizations are integrating Bio-FET arrays into high-throughput screening workflows to reduce label-dependent assay costs and enable real-time kinetic monitoring.
- Graphene channel fabrication:Superior carrier mobility and surface-area-to-volume ratios are enabling single-molecule resolution in nucleic acid detection, displacing Si-based platforms in premium diagnostic segments.
Market Restraints
- CMOS foundry capacity allocation:Mature node scarcity at Taiwan and South Korean semiconductor facilities creates 12-18 month wafer allocation queues for custom sensor designs.
- Gate surface functionalization yield:Non-uniform receptor immobilization across wafer-scale production limits manufacturing economics for sub-nanomolar detection thresholds.
- Optical biosensor substitution:Surface plasmon resonance and interferometric platforms retain entrenched positions in pharmaceutical binding kinetics applications where regulatory precedent reduces switching incentives.
Strategic Opportunities
- Closed-loop bioelectronic medicine:Implantable therapeutic Bio-FET devices for real-time metabolite monitoring represent an unpenetrated revenue pool as FDA breakthrough device pathways accelerate neuromodulation approvals.
- Environmental surveillance networks:EPA performance benchmarks for water quality monitoring are mandating continuous contaminant detection, creating deployment pull for field-hardened sensor arrays.
- Cloud-interpretation service bundling:Laboratory automation vendors are converting instrument sales into per-sample analytical contracts, capturing lifetime value through data platform subscriptions.
Industry Challenges
- Cross-disciplinary talent scarcity:Device physics expertise must integrate with bioconjugation chemistry and clinical assay validation, creating recruitment bottlenecks for hybrid R&D teams.
- Cybersecurity compliance timelines:FDA medical device cybersecurity guidance and EU MDR software lifecycle requirements are extending product qualification cycles by 8-14 months for connected diagnostic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-FET Market |
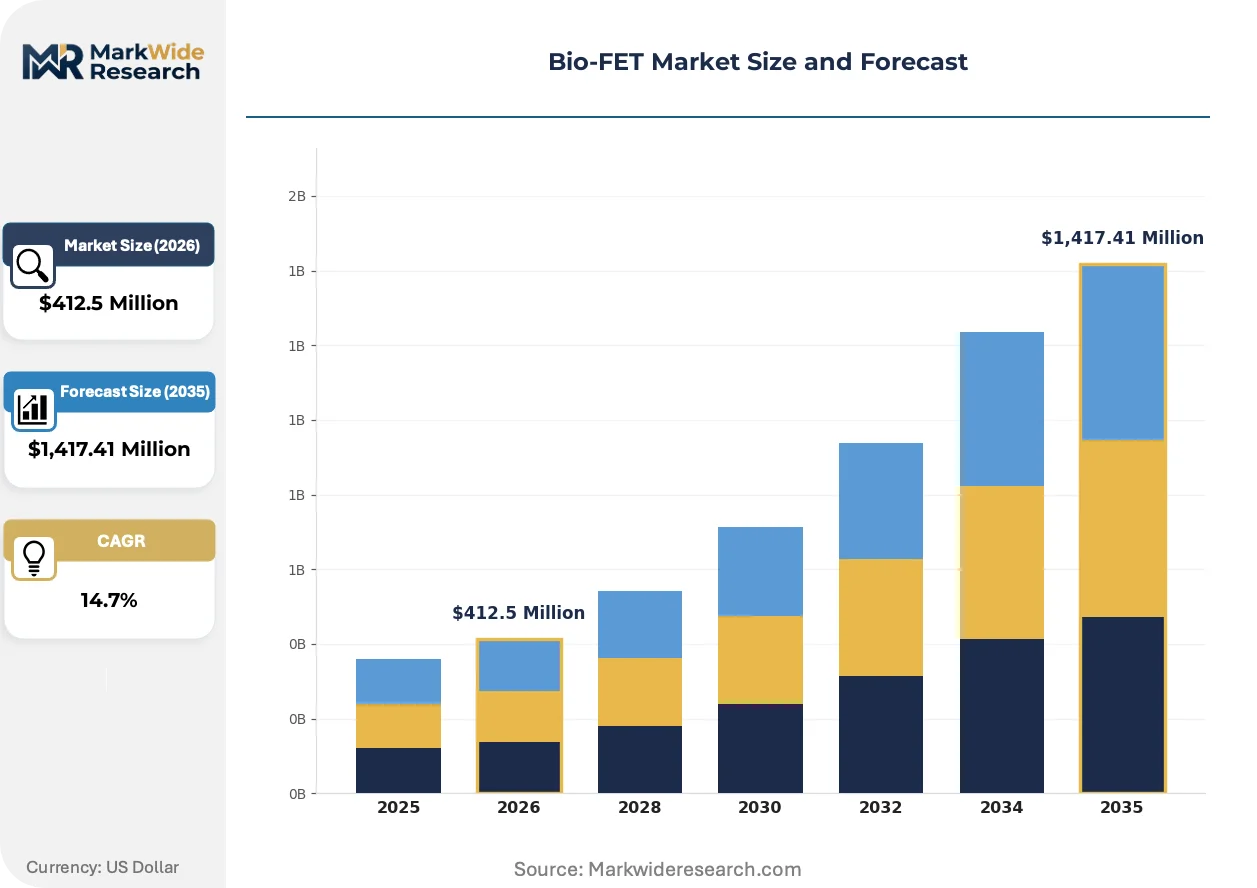
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,417.41 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Si-based, Organic, Graphene, Carbon Nanotube Technology: Biosensors, Bioelectronics, Diagnostic Tools, Therapeutic Devices End User: Pharmaceuticals, Biotechnology, Academic Research, Hospitals Application: Drug Development, Clinical Diagnostics, Environmental Monitoring, Food Safety |
| Companies Covered | Samsung Biologics, WuXi AppTec, Thermo Fisher Scientific, Regeneron Pharmaceuticals, Vertex Pharmaceuticals, Agilent Technologies, Lonza Group, Glyphic Biotechnologies, Illumina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-FET Market Trends and Innovations
Material science breakthroughs and regulatory data requirements are converging to reshape how Bio-FET devices are manufactured, validated, and monetized across diagnostic and therapeutic applications.
Graphene channel technology is expanding into clinical diagnostics through its exceptional electrical sensitivity and biocompatibility profile. Academic medical centers in Germany and South Korea are piloting graphene-based nucleic acid sensors for rapid pathogen identification. This material transition is compressing the competitive moat around incumbent silicon platforms while enabling detection limits previously restricted to laboratory-grade instrumentation.
The EU MDR's tightened performance validation requirements for point-of-care biosensors are forcing sensor manufacturers to generate clinical evidence through notified body-supervised trials. Pharmaceutical toxicology programs now demand documented equivalence to predicate devices under the new conformity assessment pathways. European diagnostic distributors are consolidating supplier relationships to reduce qualification burden, favoring vendors with captive regulatory affairs capabilities.
Service contract unbundling from hardware procurement is restructuring buyer-vendor economics in pharmaceutical screening operations. Large molecule developers are shifting from capital equipment purchases to per-assay analytical service agreements that include cloud-based kinetic interpretation. This consumption model is most visible in United States biotech clusters where venture-funded companies prioritize operational expenditure flexibility over fixed asset ownership.
Bio-FET Market Segmentation
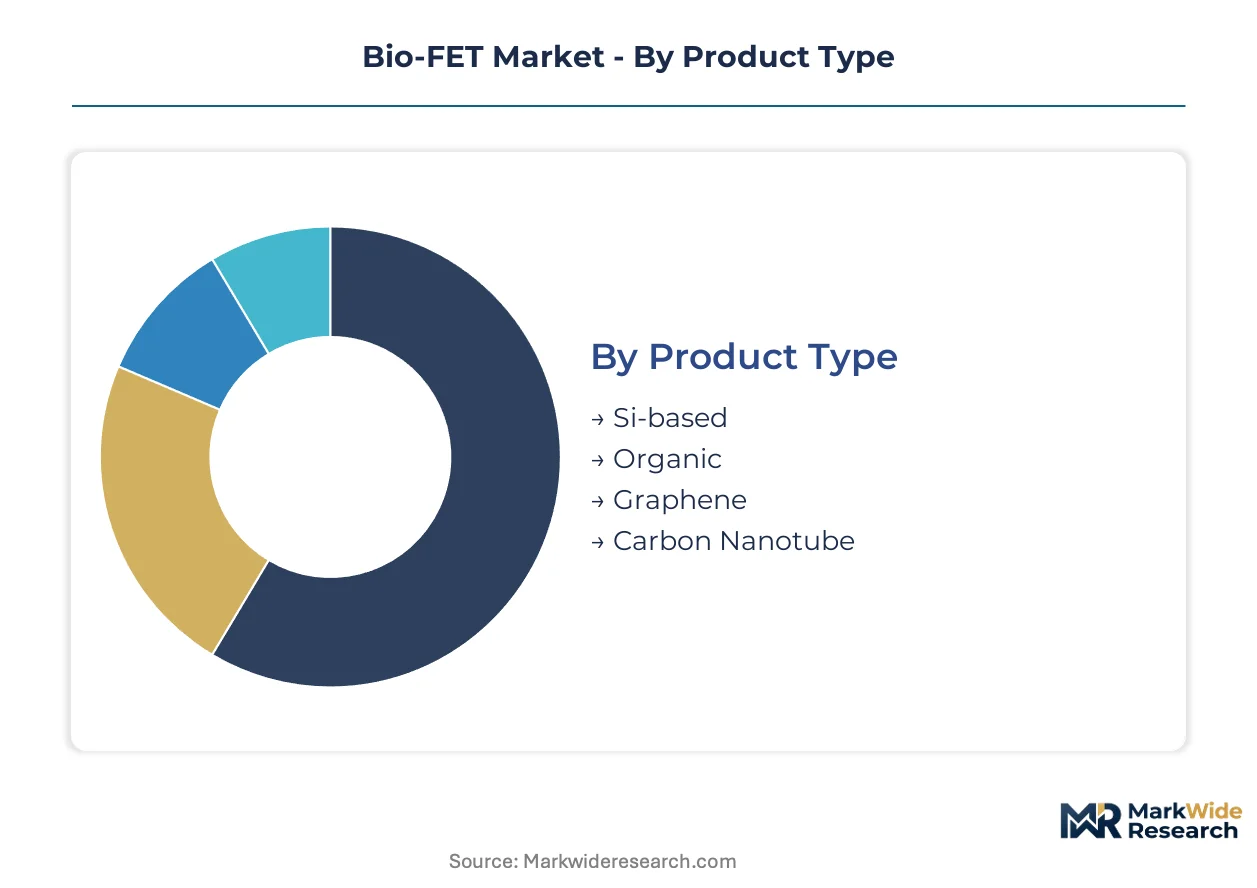
Bio-FET market segmentation reveals divergent capital requirements across material platforms and sharply contrasting regulatory pathways between diagnostic and therapeutic applications. Understanding these structural divisions enables vendors to align R&D spending with segments offering defensible margin profiles.
Product Type:
Capital intensity varies dramatically across material platforms, with semiconductor foundry investments dwarfing organic chemistry infrastructure requirements.
- Si-based:Silicon substrates leverage mature CMOS foundry ecosystems at Taiwan Semiconductor Manufacturing and Samsung Foundry, enabling wafer-scale production with established yield protocols. Pharmaceutical toxicology programs in Germany and the United States dominate procurement, drawn by predictable manufacturing economics and extensive regulatory precedent.
- Graphene:Exceptional carrier mobility and surface-area-to-volume ratios enable single-molecule resolution in nucleic acid detection. South Korean academic medical centers and German research hospitals are piloting clinical deployment, though chemical vapor deposition equipment costs constrain foundry expansion.
- Organic:Solution-processable polymers reduce barrier-to-entry for specialized contract manufacturers serving environmental monitoring networks.
- Carbon Nanotube:Purification and chirality separation costs limit commercial scale despite superior mechanical stability in implantable configurations.
Most installed capacity flows through Si-based platforms. Expansion is steepest in Graphene channels.
Technology:
Revenue model differentiation separates segments pursuing hardware margins from those capturing recurring analytical service contracts.
- Diagnostic Tools:Point-of-care platforms face EU MDR conformity assessment requirements that extend qualification timelines. United States hospital systems and South Korean clinical laboratories represent primary demand concentration.
- Biosensors:Label-free detection architectures dominate pharmaceutical screening workflows, with contract research organizations in Germany and the United States driving volume.
- Bioelectronics:Closed-loop therapeutic systems command premium pricing through FDA breakthrough device pathways.
- Therapeutic Devices:Implantable metabolite monitors for neuromodulation remain pre-commercial, with regulatory precedent still forming at FDA.
Diagnostic Tools concentrate current revenue. Therapeutic Devices are gaining share fastest.
End User:
Procurement sophistication determines vendor access, with pharmaceutical buyers demanding integrated data platforms and academic users prioritizing publication-grade sensitivity specifications.
- Pharmaceuticals:Large molecule developers in the United States biotech clusters are shifting from capital purchases to per-assay service agreements that bundle cloud-based kinetic interpretation.
- Biotechnology:Venture-funded companies prioritize operational expenditure flexibility over fixed asset ownership, favoring consumption-based pricing models.
- Academic Research:German and South Korean university consortia drive graphene channel validation studies.
- Hospitals:Clinical laboratories face EU MDR performance validation mandates that accelerate replacement of legacy electrochemical platforms.
Pharmaceuticals absorb the highest absolute spending. Biotechnology is expanding most quickly.
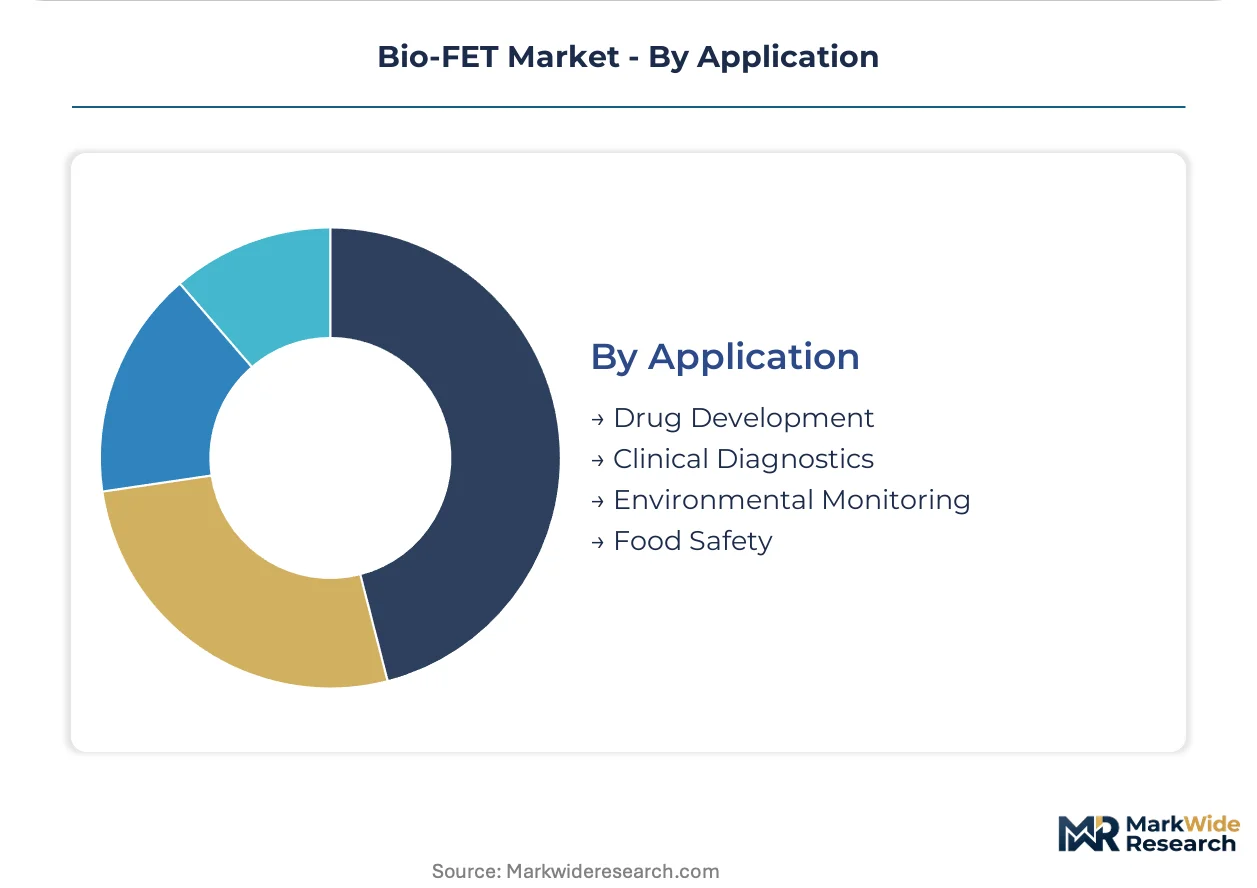
Application:
Regulatory jurisdiction fragmentation shapes go-to-market economics, with environmental and food safety applications facing distinct approval pathways from clinical diagnostics.
- Drug Development:High-throughput screening workflows at contract research organizations demand real-time kinetic monitoring capabilities that displace label-dependent assays.
- Clinical Diagnostics:FDA in vitro diagnostic pathways and EU MDR conformity assessments impose parallel qualification requirements on connected platforms.
- Environmental Monitoring:EPA performance benchmarks for water quality monitoring mandate continuous contaminant detection, creating deployment pull for field-hardened arrays.
- Food Safety:Pathogen detection specifications vary across national regulators, complicating standardization for multinational suppliers.
Drug Development commands the largest revenue pool. Environmental Monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting Bio-FET manufacturing toward jurisdictions with streamlined medical device qualification pathways. South Korea and Germany offer faster notified body engagement than the United States, while Taiwan provides CMOS foundry proximity without REACH substance restrictions.
United States
FDA breakthrough device pathways accelerate neuromodulation approvals for therapeutic Bio-FET applications. The agency's medical device cybersecurity guidance extends qualification timelines for connected diagnostic platforms. Greater Boston biotech clusters absorb per-assay service contracts that bundle cloud-based kinetic interpretation with hardware access.
Germany
Notified body-supervised trials under EU MDR tighten performance validation requirements for point-of-care biosensors. REACH frameworks impose substance restrictions on sensor materials entering healthcare markets. Bavarian academic medical centers pilot graphene-based nucleic acid sensors for rapid pathogen identification.
South Korea
MFDS fast-track approvals for novel diagnostic platforms attract foreign sensor developers seeking earlier market entry. Samsung Foundry provides captive semiconductor fabrication integrated with biologic assay development. Seoul Capital Area research hospitals validate single-molecule resolution in clinical nucleic acid detection.
Taiwan
TSMC mature node allocation queues create 12-18 month wafer delays for custom sensor designs. The absence of EU substance restrictions lowers material compliance costs for export-oriented manufacturers. Hsinchu Science Park clusters semiconductor expertise adjacent to biomedical research institutes.
Switzerland
Swissmedic maintains regulatory alignment with EU MDR without full conformity assessment burdens. Precision manufacturing heritage supports microfabrication of implantable therapeutic devices. Basel pharmaceutical headquarters drive demand for contract-manufactured Bio-FET arrays in toxicology programs.
Bio-FET Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Diagnostic tool vendors capture recurring analytical service contracts while semiconductor foundries monetize wafer-scale sensor production. Three archetypes dominate: laboratory automation integrators bundling cloud interpretation, captive semiconductor fabricators with biologic assay capabilities, and contract research organizations integrating sensor arrays into screening workflows. Competitive moves center on strategic partnerships between foundries and life science clusters, plus portfolio diversification into closed-loop bioelectronic medicine.
Among diversified laboratory technology providers, Thermo Fisher Scientific and Agilent Technologies exemplify the instrumentation-to-service transition. Lonza Group occupies a position within contract manufacturing specialists producing custom sensor arrays for pharmaceutical toxicology. Samsung Biologics anchors the captive fabrication archetype through integrated sensor wafer and biologic development capabilities.
| Leading Market Players |
|---|
| Samsung Biologics |
| WuXi AppTec |
| Thermo Fisher Scientific |
| Regeneron Pharmaceuticals |
| Vertex Pharmaceuticals |
| Agilent Technologies |
| Lonza Group |
| Glyphic Biotechnologies |
| Illumina |
| Others |
Pricing and Supply Chain Analysis
Graphene channel fabrication scaling simultaneously compresses unit economics at premium tiers and concentrates production capacity among South Korean and German facilities with chemical vapor deposition expertise. This material transition restructures cost curves while locking supply relationships to semiconductor foundries with captive biologic assay capabilities.
Pricing Analysis
Distributor margins on diagnostic tool platforms absorb 15-25 point spreads between OEM gate pricing and hospital laboratory procurement. Three-tier pricing structure across premium graphene-based, standard silicon, and economy organic polymer tiers reflects certification grade differentiation under EU MDR and FDA pathways. Pricing pressure stems from CMOS foundry capacity scarcity forcing allocation premiums for custom sensor wafer designs. Biotechnology venture-funded buyers exhibit highest price sensitivity through preference for per-assay service contracts over capital equipment ownership.
Supply Chain Analysis
Direct-to-OEM channels handle pharmaceutical toxicology program demand while distributor networks serve hospital laboratory procurement. Wafer fabrication concentrates in Taiwan, South Korea, and Germany where TSMC, Samsung Foundry, and Bavarian microfabrication facilities anchor production. Supply chains draw from high-purity silicon substrates, graphene chemical vapor deposition precursors, and bioconjugation chemistry reagents. Single-source vulnerability around mature CMOS node allocation creates structural risk for custom Bio-FET designs. Distribution runs through laboratory automation integrators bundling cloud interpretation services with hardware deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
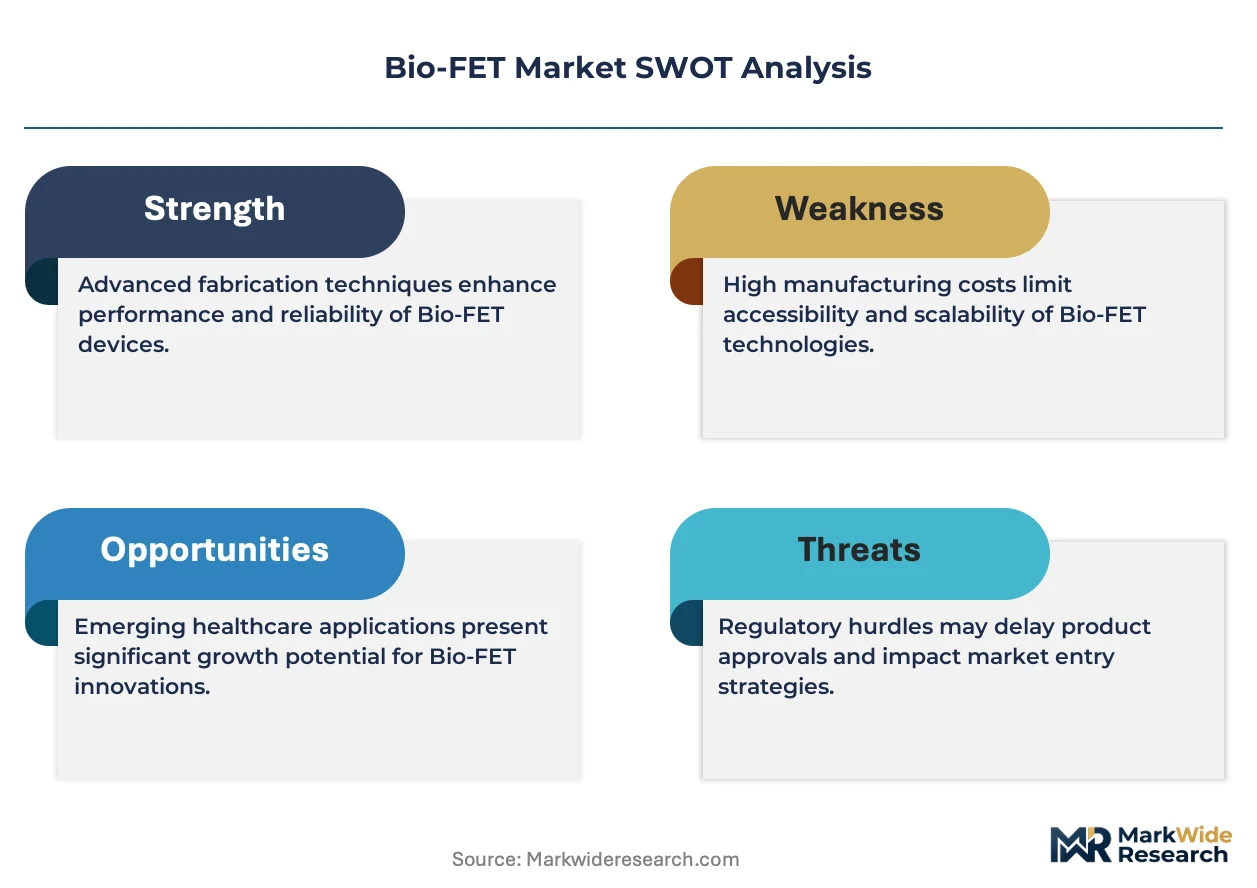
The Bio-FET market functions as a regulatory compounder where EU MDR performance validation mandates and FDA breakthrough device pathways simultaneously expand addressable demand and extend qualification timelines for compliant architectures.
For Market Incumbents: To counter graphene channel displacement of silicon platforms in premium diagnostic segments, incumbents should deepen captive semiconductor fabrication partnerships with Samsung Foundry or TSMC while accelerating FDA breakthrough device pathway submissions for closed-loop therapeutic applications. Certification investment in EU MDR notified body relationships defends market access against qualification timeline extension. For New Entrants and Emerging Players: Launch via contract manufacturing partnerships with Lonza Group or WuXi AppTec to bypass capital-intensive foundry investments. Environmental monitoring networks under EPA performance benchmarks represent the most penetrable white space, with field-hardened sensor arrays for water quality surveillance offering lower regulatory barriers than clinical diagnostics. Direct sales to municipal utilities bypass distributor margin extraction. For Investors and Strategic Acquirers: Valuations sit cheapest among organic polymer platform specialists serving environmental surveillance without clinical certification burdens. Long-term viability over the next decade hinges on successful navigation of FDA cybersecurity guidance and EU MDR software lifecycle requirements. Watch FDA breakthrough device designation velocity as the signal for therapeutic Bio-FET commercialization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Partnership | Accelerates conformity assessment timelines for point-of-care biosensor manufacturers entering German and Swiss markets. |
| Graphene CVD Equipment Investment | Enables single-molecule resolution capabilities that displace silicon platforms in South Korean academic medical center pilots. |
| Cloud Interpretation Platform Launch | Converts Thermo Fisher Scientific instrument sales into recurring per-assay analytical service contracts. |
| FDA Breakthrough Device Submission | Fast-tracks neuromodulation approvals for implantable therapeutic Bio-FET metabolite monitors. |
| Pharmaceutical CRO Integration | Embeds Bio-FET arrays into high-throughput toxicology screening workflows at United States biotech clusters. |
Research Methodology
Bottom-up pharmaceutical toxicology and clinical diagnostics demand modeling reconciled against top-down semiconductor foundry capacity tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs directors at sensor manufacturers combined with secondary validation against FDA 510(k) filings, EU MDR notified body registers, EPA environmental monitoring procurement databases, and SEC 10-K disclosures from laboratory automation providers. Triangulation across these sources ensures segmentation integrity.
Input-output matrices connect wafer fabrication capacity, gate surface functionalization yield rates, and assay development timelines to revenue pool estimates across the projection horizon. Segmentation dimensions include material platform, technology type, end user procurement sophistication, and application regulatory jurisdiction. CAGRs derive from installed base replacement cycles, graphene channel adoption curves, and service contract unbundling velocity. Forecast inputs incorporate EU MDR qualification timeline extensions and FDA cybersecurity guidance implementation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor export control expansion or abrupt REACH substance restriction amendments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Fingerprint Sensor Market
Sensors and Controls
Cryogenic Temperature Controller Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
SCR Dosing Control Modules Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market