
 MEMS Microphones Market | 2026-2036
MEMS Microphones Market Size, Share, and Industry Trends Forecast 2026-2036
MEMS Microphones Market Intelligence
Acoustic engineering talent is rotating from traditional electret microphone lines toward capacitive MEMS design teams, tightening the labor pool for analog heritage manufacturers. Knowles Corporation leverages its Illinois-based R&D campus to sustain deep expertise in precision MEMS fabrication. Infineon Technologies anchors European supply through its Austrian foundry partnerships for wafer-level packaging. Goertek dominates final assembly capacity from its Shandong facilities, competing on unit cost at smartphone OEM scale.
MEMS microphones are miniature acoustic transducers fabricated on silicon substrates using semiconductor lithography, typically measuring under 5 mm in footprint and integrating preamplifier circuits for direct digital output. They convert sound pressure into electrical signals for voice capture, noise cancellation, and acoustic event detection in portable electronics. Digital MEMS microphones are pulling ahead of analog variants as OEMs prioritize beamforming algorithms and multi-mic arrays for spatial audio. The consumer electronics end user segment occupies the dominant volume position, while automotive cabin monitoring applications are extending the fastest growth trajectory due to driver attention systems and in-vehicle voice control mandates.
FCC equipment authorization rules govern RF emissions from wireless-integrated microphone modules in the US market, while REACH and RoHS frameworks in Europe restrict hazardous substances in solder joints and encapsulant materials. CE marking requirements for acoustic safety pressure exposure shape product design thresholds for wearable and in-ear deployments. Stakeholders must monitor how IEC 61000 electromagnetic compatibility standards evolve for microphone-integrated IoT devices, as compliance scope directly determines market access breadth across regulated jurisdictions.
Market Dynamics
Smartphone OEM procurement is consolidating around digital MEMS microphone arrays for spatial audio beamforming, compressing analog supplier margins while concentrating assembly capacity in Shandong and Guangdong provinces.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon propellants in acoustic encapsulants is accelerating migration to silicone-based alternatives, opening specification windows for compliant MEMS designs.
- Automotive cabin monitoring:Driver attention systems and in-vehicle voice control mandates are pulling microphone unit counts per vehicle from single-digit to array configurations.
- Shenzhen-Dongguan cluster:Dense concentration of packaging and testing facilities enables rapid iteration cycles for smartphone OEM qualification programs.
Market Restraints
- Wafer supply concentration:Foundry partnerships for 8-inch MEMS-capable lines concentrate in Austria and Taiwan, creating single-source vulnerability for European supply chains.
- Electret substitution in cost-sensitive segments:Analog electret microphones retain 40-60% cost advantage in basic voice capture applications, limiting MEMS penetration in entry-tier consumer electronics.
- REACH compliance friction:Restrictions on lead-bearing solders and halogenated flame retardants extend qualification timelines for acoustic module redesigns by 8-14 months.
Strategic Opportunities
- Hearing aid and OTC audio device channels:FDA 2022 over-the-counter hearing aid regulations are democratizing access, creating demand for miniaturized microphone arrays in direct-to-consumer form factors.
- Industrial IoT acoustic event detection:Machine health monitoring and predictive maintenance applications are adopting MEMS microphones for vibration-to-acoustic translation in smart manufacturing deployments.
- Beamforming algorithm convergence:Integration of AI-driven noise suppression with MEMS array hardware is enabling differentiated performance tiers for premium smartphone and laptop segments.
Industry Challenges
- Acoustic engineering talent migration:Capacitive MEMS design teams are absorbing engineers from electret heritage lines, leaving analog manufacturers with depleted R&D benches and extended hiring cycles.
- IEC 61000 EMC certification timelines:Electromagnetic compatibility testing for microphone-integrated IoT devices varies across notified bodies, creating unpredictable market access delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEMS Microphones Market |
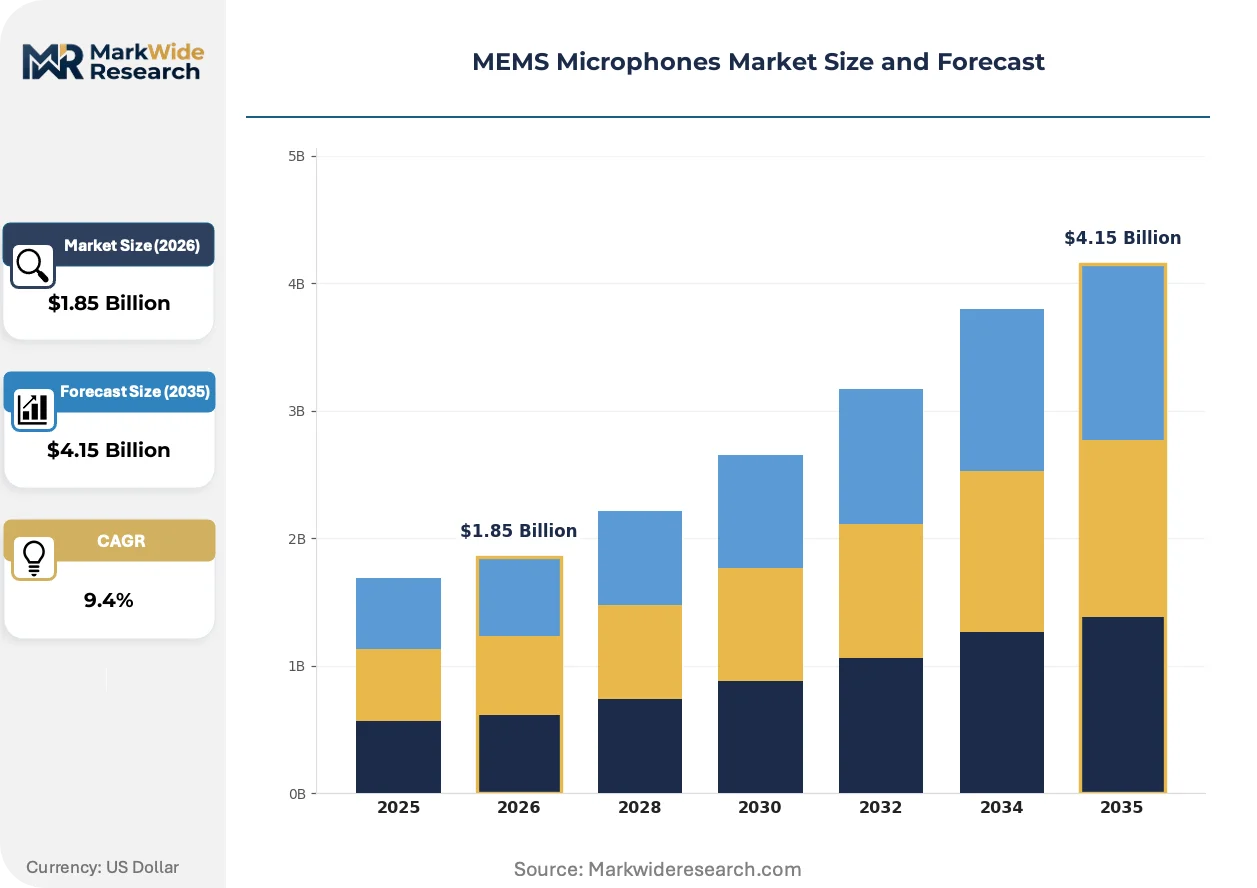
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog MEMS Microphones, Digital MEMS Microphones, Microphone Arrays, MEMS Microphone Modules Application: Smartphones, Tablets, Smart Speakers, Wearable Devices End User: Consumer Electronics, Automotive, Medical Devices, Industrial Equipment Technology: Capacitive, Electret, Piezoelectric, Optical |
| Companies Covered | AAC Technologies, Cirrus Logic, Knowles Corporation, Infineon Technologies, Bosch Sensortec, Goertek, TDK Corporation, Hosiden Corporation, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEMS Microphones Market Strategic Shifts & Innovations
Digital output architectures are overtaking analog interfaces as OEMs prioritize software-defined audio pipelines and multi-microphone synchronization for spatial processing.
Capacitive MEMS transducers with integrated analog-to-digital converters are displacing traditional analog-output designs in smartphone and laptop platforms. Tier-one OEMs now specify digital pulse-density modulation interfaces for beamforming compatibility. This displacement is compressing the addressable market for pure-play analog microphone suppliers and forcing heritage manufacturers to retool fabrication lines.
EU F-Gas Regulation phasedown schedules are accelerating reformulation of acoustic encapsulant materials toward silicone and urethane chemistries. MEMS microphone housings must now demonstrate GWP-compliant thermal stability across -40°C to 85°C operating ranges. Automotive cabin monitoring applications face the steepest compliance curves, with German OEMs driving supplier qualification timelines.
Smartphone OEMs are consolidating microphone procurement under single-source array contracts rather than discrete component sourcing. This consolidation favors suppliers with in-house ASIC design and wafer-level packaging capabilities. The shift is most pronounced in China, where domestic OEMs now specify 4-6 microphone arrays per flagship device with synchronized digital outputs.
MEMS Microphones Market Segmentation
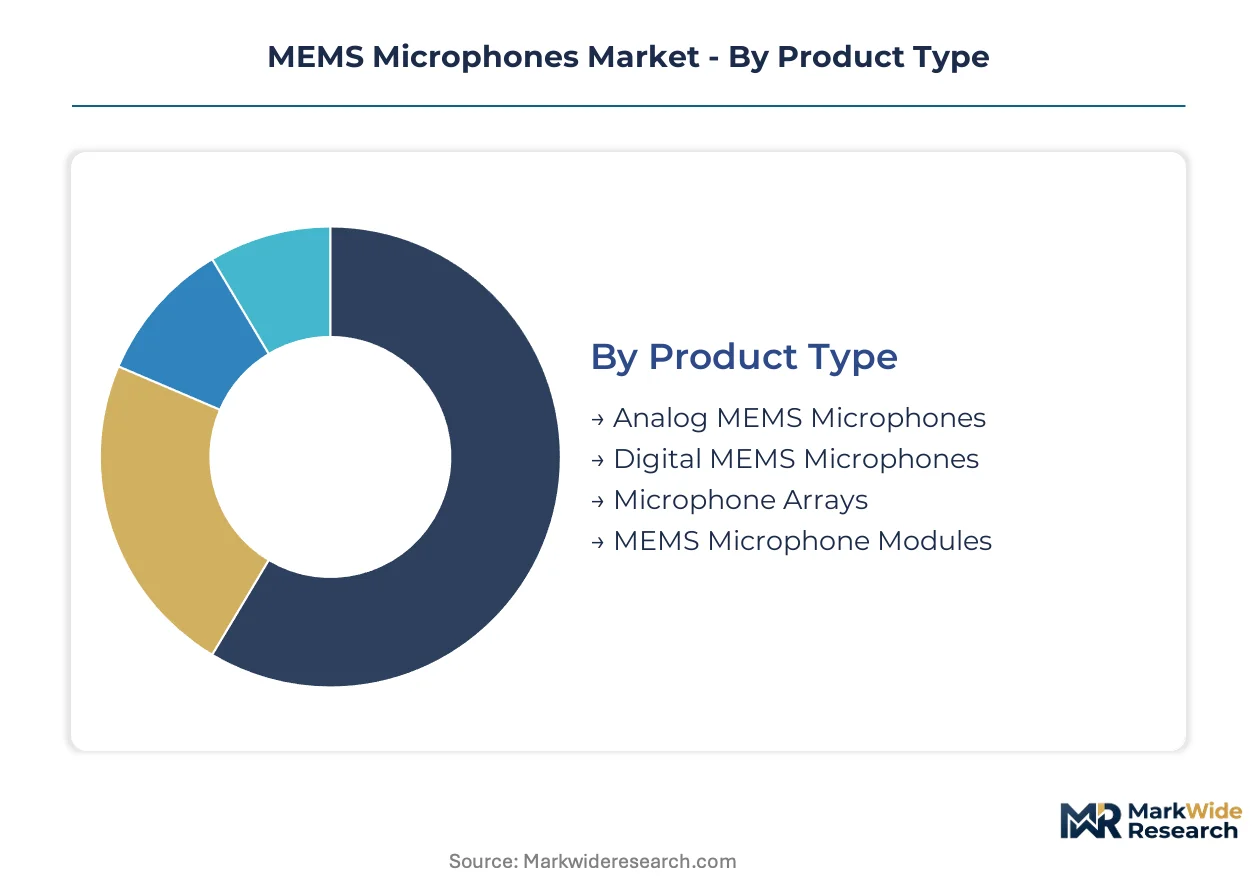
MEMS microphone suppliers must navigate divergent performance requirements across product architectures and end-use environments. Segmentation reveals where digital architectures displace analog heritage and which application tiers resist cost-driven substitution.
Product Type:
Analog designs face the most acute substitution pressure as OEM procurement shifts toward software-defined audio pipelines and synchronized array outputs.
- Digital MEMS Microphones:These integrate analog-to-digital converters directly on the MEMS die, outputting pulse-density modulation streams for beamforming compatibility. Smartphone OEMs in China specify these for 4-6 microphone arrays per flagship device, prioritizing spatial audio algorithms over component cost.
- Analog MEMS Microphones:Continuous voltage output designs retain cost advantage in basic voice capture applications but face margin compression as procurement consolidates around digital suppliers. Entry-tier consumer electronics manufacturers in Southeast Asia still specify these for single-microphone configurations.
- Microphone Arrays:Synchronized multi-microphone modules enable directional pickup and noise suppression through beamforming signal processing. Laptop OEMs increasingly specify these for video conferencing parity with premium smartphone audio performance.
- MEMS Microphone Modules:Pre-integrated acoustic subassemblies combine MEMS transducers with ASICs and housing for direct PCB mounting. White-label electronics assemblers in Dongguan prefer these for reduced qualification overhead and faster time-to-market.
Digital MEMS microphones anchor the volume base while microphone arrays gain share at the steepest rate.
Application:
Cost tier stratification separates flagship specifications from entry-tier tolerance for electret substitution.
- Smartphones:Flagship devices drive the highest unit counts per device, with OEMs specifying synchronized digital arrays for voice-assistant integration and spatial audio recording. Shenzhen-based procurement teams prioritize suppliers with in-house ASIC design capabilities.
- Smart Speakers:Far-field voice recognition demands circular microphone arrays with beamforming DSP, pushing specification toward digital-output MEMS with extended dynamic range. Amazon and Google hardware teams have standardized on 4-7 microphone configurations.
- Tablets:Video conferencing use cases are pulling tablet designs toward dual-microphone noise cancellation, though unit economics still favor analog solutions in education and enterprise fleet deployments.
- Wearable Devices:Miniaturization constraints favor single-microphone configurations with aggressive power budgets, creating specification tension between audio quality and battery life in true wireless earbud designs.
Smartphones anchor the volume base while smart speakers expand most quickly as voice-assistant installation proliferates.
End User:
Margin structure varies sharply across customer types, with automotive and medical commanding qualification premiums over consumer electronics.
- Consumer Electronics:Smartphone, laptop, and audio accessory manufacturers drive aggregate volume but squeeze supplier margins through consolidated procurement and annual cost-down targets. Chinese OEMs dominate global demand concentration.
- Automotive:Driver monitoring systems and cabin voice control are extending microphone counts per vehicle from single-digit to array configurations. German OEMs impose the steepest EU F-Gas compliance curves on encapsulant materials.
- Medical Devices:FDA 2022 over-the-counter hearing aid regulations are democratizing access, creating demand for miniaturized microphone arrays in direct-to-consumer form factors with biocompatibility requirements.
- Industrial Equipment:Machine health monitoring applications adopt MEMS microphones for vibration-to-acoustic translation, though price sensitivity limits penetration versus accelerometer alternatives.
Consumer electronics anchors the volume base while automotive climbs the fastest on regulatory mandates for cabin monitoring.
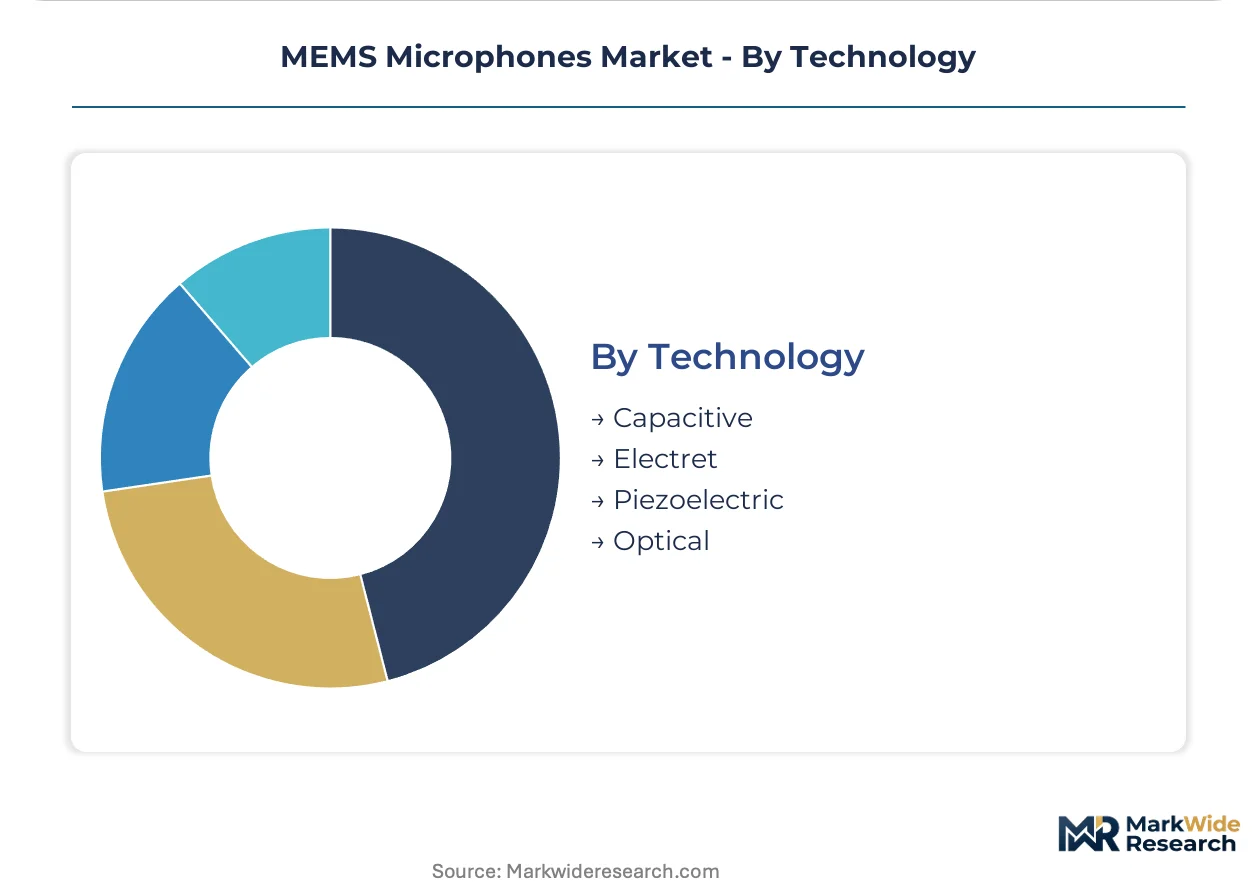
Technology:
Supply concentration for precision fabrication favors capacitive architectures while alternative transduction principles carve niche applications.
- Capacitive:Variable capacitance between a fixed backplate and flexible diaphragm dominates commercial MEMS production, leveraging semiconductor lithography for batch fabrication. Knowles Corporation and Infineon Technologies anchor deep expertise in this architecture.
- Electret:Permanently charged polymer film microphones retain 40-60% cost advantage in basic applications but lack the miniaturization and integration headroom of MEMS alternatives. Analog heritage manufacturers face depleted R&D benches as engineering talent migrates.
- Piezoelectric:Aluminum nitride or PZT thin-film transducers offer intrinsic waterproofing and reduced power consumption, finding traction in wearable and harsh-environment deployments.
- Optical:Laser interferometry detects diaphragm displacement without electrical bias voltage, enabling ultra-low noise floors for professional audio and scientific instrumentation with limited volume scaling.
Capacitive technology anchors the volume base while piezoelectric gains share fastest in power-constrained and ingress-protected applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization rules govern RF emissions from wireless-integrated microphone modules in the United States, while MIIT certification requirements shape product design for Chinese OEMs. Shenzhen and Dongguan host the densest concentration of MEMS microphone packaging and testing facilities worldwide.
China
Smartphone OEM procurement concentrates in Shenzhen and Dongguan, where domestic manufacturers specify 4-6 microphone arrays per flagship device. MIIT enforces GB standards for electromagnetic compatibility in wireless audio peripherals. The Pearl River Delta cluster enables rapid iteration cycles for OEM qualification programs through vertically integrated packaging and testing infrastructure.
United States
Voice-assistant integration in smart speakers and laptops drives demand for beamforming-compatible digital MEMS arrays. FCC Part 15 equipment authorization governs RF emissions from wireless-integrated microphone modules. Illinois hosts precision MEMS fabrication R&D campuses serving defense and medical audio applications.
Germany
Automotive cabin monitoring mandates from KBA are extending microphone counts per vehicle from single-digit to array configurations. EU F-Gas Regulation phasedown schedules impose the steepest compliance curves on encapsulant materials for acoustic modules. Bavaria anchors European supply chain coordination for wafer-level packaging partnerships.
Japan
Wearable device miniaturization demands favor single-microphone configurations with aggressive power budgets in true wireless earbud designs. METI promotes domestic semiconductor resilience through supply chain diversification initiatives. Kanto region fabrication facilities specialize in precision backplate lithography for capacitive MEMS transducers.
South Korea
Consumer electronics manufacturers in the Seoul Capital Area drive consolidated procurement under single-source array contracts. MFDS biocompatibility requirements shape designs for hearing aid and medical audio device channels. Busan-Ulsan industrial corridors support acoustic module assembly for export-oriented smartphone OEMs.
MEMS Microphones Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the MEMS microphone market. The upper tier commands in-house ASIC design and wafer-level packaging capabilities that smartphone OEMs now mandate for array contracts. Below them, pure-play analog suppliers and white-label assemblers compete on unit cost for entry-tier consumer electronics. Two dominant competitive moves are reshaping positioning: backward integration into captive MEMS fabrication capacity, and strategic partnerships with foundries for 8-inch MEMS-capable line access.
Among Asia-Pacific-based fabricators, AAC Technologies and Goertek exemplify the scale-driven archetype with dominant final assembly capacity from Shandong facilities. Knowles Corporation occupies a position within the precision-specialist tier, leveraging Illinois-based R&D campuses for deep expertise in capacitive MEMS fabrication. Infineon Technologies anchors European supply representation through Austrian foundry partnerships for wafer-level packaging.
| Leading Market Players |
|---|
| AAC Technologies |
| Cirrus Logic |
| Knowles Corporation |
| Infineon Technologies |
| Bosch Sensortec |
| Goertek |
| TDK Corporation |
| Hosiden Corporation |
| STMicroelectronics |
| Others |
Cost & Logistics Intelligence
Silicone-based acoustic encapsulants replacing hydrofluorocarbon formulations are redrawing supplier maps toward EU F-Gas-compliant chemistries while compressing margins for legacy compounders locked into phasedown timelines. Smartphone OEM procurement teams in Shenzhen exploit this transition to extract cost concessions from acoustic module vendors facing dual qualification burdens.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-one smartphone OEMs and established MEMS microphone suppliers, locking in volume commitments against annual cost-down schedules. Pricing stratifies across premium, standard, and economy tiers based on ASIC integration depth and automotive qualification status. Cost compression in entry-tier analog segments is intensifying because electret microphones retain 40-60% cost advantage for basic voice capture. White-label assemblers in Dongguan exhibit the highest price sensitivity, while German automotive OEMs accept qualification premiums for F-Gas-compliant encapsulant formulations.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Shenzhen-based smartphone OEMs, though automotive suppliers in Germany maintain strategic stockpiles of qualified encapsulant materials against EU F-Gas phasedown disruptions. Wafer fabrication concentrates in Austria and Taiwan, with final assembly anchored in Shandong and Guangdong provinces. The supply chain draws from 8-inch MEMS-capable foundry lines, silicone-based acoustic encapsulants, and precision lithography equipment. Single-source vulnerability for European supply chains represents the dominant structural risk. Distribution runs through vertically integrated packaging houses in the Pearl River Delta cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as FDA 2022 over-the-counter hearing aid regulations splinter demand across miniaturized microphone arrays, creating niches beyond smartphone consolidation. Specialized medical audio channels now reward biocompatibility expertise that consumer-electronics suppliers lack.
For Market Incumbents: Compound defensive moats through captive 8-inch MEMS fabrication capacity and exclusive foundry partnerships for wafer-level packaging. Electret heritage manufacturers face depleted R&D benches as engineering talent migrates toward capacitive MEMS design teams. Backward integration into ASIC design capabilities secures array contract eligibility against pure-play analog suppliers. For New Entrants and Emerging Players: Anchor in industrial IoT acoustic event detection for predictive maintenance applications, where price sensitivity limits accelerometer alternatives and MEMS microphone penetration remains underdeveloped. Machine health monitoring in smart manufacturing deployments offers the most penetrable white-space target. Pursue qualification partnerships with German automotive OEMs for cabin monitoring arrays as F-Gas compliance curves steepen. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision MEMS fabricators holding Illinois or Austrian R&D campuses but lacking smartphone scale. Long-term viability over a 5-10 year window hinges on beamforming algorithm convergence with hardware differentiation. Watch for inflection when AI-driven noise suppression integration becomes mandatory rather than optional in premium smartphone specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Foundry Capacity | Austrian wafer-level packaging partnerships reduce single-source exposure for European supply chains. |
| Beamforming Algorithm Hardware Integration | AI-driven noise suppression convergence enables premium tier differentiation for laptop OEMs. |
| EU F-Gas Compliance Qualification | German automotive OEMs impose steepest encapsulant reformulation timelines on acoustic module suppliers. |
| OTC Hearing Aid Channel Entry | FDA 2022 regulations democratize access, creating demand for miniaturized microphone arrays with biocompatibility. |
| Industrial IoT Acoustic Event Detection Partnership | Smart manufacturing deployments adopt vibration-to-acoustic translation for predictive maintenance applications. |
Research Approach
A standing panel of MEMS fabrication engineers, smartphone OEM procurement managers, automotive acoustic system architects, and hearing aid device manufacturers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SEC 10-K filings, MIIT certification databases, EU F-Gas Regulation implementation schedules, and FDA 510(k) submission records. Bottom-up unit shipment estimates triangulated against top-down value projections derived from foundry capacity disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product architecture, application tier, end-user industry, and regional regulatory cluster. CAGRs emerged from fitted growth curves applied to smartphone array penetration rates, automotive microphone-per-vehicle trajectories, and industrial IoT adoption patterns. Forecast inputs included Shenzhen OEM procurement consolidation timelines and EU F-Gas phasedown schedules.
Material uncertainties — foundry capacity constraints, REACH compliance timeline extensions, and electret substitution resilience in cost-sensitive segments — sit outside the modeled envelope. Forecasts reflect assumptions regarding beamforming algorithm standardization and automotive cabin monitoring mandate propagation. Revision becomes warranted when smartphone OEM array specifications cross six microphones per flagship device or when EU F-Gas enforcement intensity crosses thresholds affecting encapsulant supplier viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Motion Sensor Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Global RFID Sensor Market
Sensors and Controls
Germany Non-Contact Infrared Thermometer Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
United States Smart Sensors Market