
 Heart Beat Sensor Market | 2026-2036
Heart Beat Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Beat Sensor Market Foresight
Asian semiconductor foundries is decoupling from legacy CMOS image sensor supply, redirecting wafer capacity toward photoplethysmography and bio-impedance chipsets for heart rate applications. Apple leverages its vertical silicon design to sustain proprietary optical engine performance across Watch iterations. Samsung Electronics anchors display-integrated sensor architectures that merge OLED panels with biometric modules. Texas Instruments competes through ultra-low-power analog front-ends purpose-built for wearable ECG signal chains.
A heart beat sensor detects cardiac activity through optical, electrical, acoustic, or ultrasound transduction, typically sampling blood volume changes or myocardial electrical depolarization at rates between 100 Hz and 512 Hz for clinical fidelity. The device converts analog physiological signals into digital waveforms for real-time monitoring, diagnostic screening, or algorithm-driven fitness coaching. Wearable product types now dominate unit volumes, though implantable devices command superior margin pools due to regulatory barriers and long-term cardiac monitoring contracts. Optical technology leads consumer shipments while electrical sensing retains institutional preference in hospital and clinic settings where arrhythmia detection accuracy governs purchasing decisions. Ultrasound-based approaches are gaining traction in telemedicine applications where skin-tone-independent perfusion measurement matters.
FDA 510(k) clearances and the EU MDR framework govern clinical-grade sensor deployment, with FDA's evolving De Novo pathway for consumer ECG devices reshaping market access boundaries. China's NMPA has tightened GB standard compliance for imported wearable medical devices, creating certification friction for non-domestic suppliers. Japan's PMDA maintains distinct pharmaceutical-medical device convergence rules that affect combo-product heart rate drug delivery systems. Stakeholders must monitor how regulatory divergence between FDA's software-as-medical-device guidance and EU MDR technical documentation requirements will fragment go-to-market strategies for multi-region sensor platforms.
Market Dynamics
Semiconductor foundry capacity reallocation toward photoplethysmography chipsets is compressing optical sensor lead times while FDA's De Novo pathway expansion accelerates clinical-grade wearable certification timelines.
Growth Catalysts
- FDA De Novo Pathway:The FDA's streamlined route for novel consumer ECG devices reduces 510(k) submission burdens for pulse oximetry-enabled wearables, expanding regulated home monitoring use cases.
- Germany's DiGA Framework:Germany's Digital Health Applications fast-track reimbursement creates institutional procurement pull for prescription-grade heart rate monitors in chronic cardiac care.
- Photoplethysmography Chipsets:Asian foundries are redirecting wafer capacity from legacy CMOS image sensors toward optical biosensing silicon, resolving prior supply bottlenecks for wearable OEMs.
Market Restraints
- GB Standard Compliance:China's NMPA tightened technical documentation requirements for imported wearable medical devices, extending certification timelines by 8-14 months for non-domestic suppliers.
- Electrode Material Cost Volatility:Silver-silver chloride electrode prices fluctuate with precious metals markets, compressing margins on disposable ECG patch consumables.
- Optical Perfusion Limitations:Skin melanin absorption variability degrades signal quality in darker skin tones, creating accuracy gaps that electrical sensing methods do not exhibit.
Strategic Opportunities
- Telemedicine Ultrasound Integration:Ultrasound-based perfusion measurement bypasses skin-tone dependency, opening cardiac monitoring contracts in dermatologically diverse patient populations.
- Japan's PMDA Convergence Rules:Pharmaceutical-medical device combination product pathways enable heart rate-responsive drug delivery systems for arrhythmia management.
- India's PLI Scheme:Production-linked incentives for electronics manufacturing attract sensor module assembly capacity, reducing landed costs for domestic wearable brands.
Industry Challenges
- Biomedical Signal Processing Talent:Shortage of engineers with combined expertise in analog front-end design and machine learning algorithm development delays product iteration cycles.
- EU MDR Technical Documentation:Clinical evidence requirements for Class IIa heart rate monitors demand expanded post-market surveillance infrastructure that mid-tier manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Beat Sensor Market |
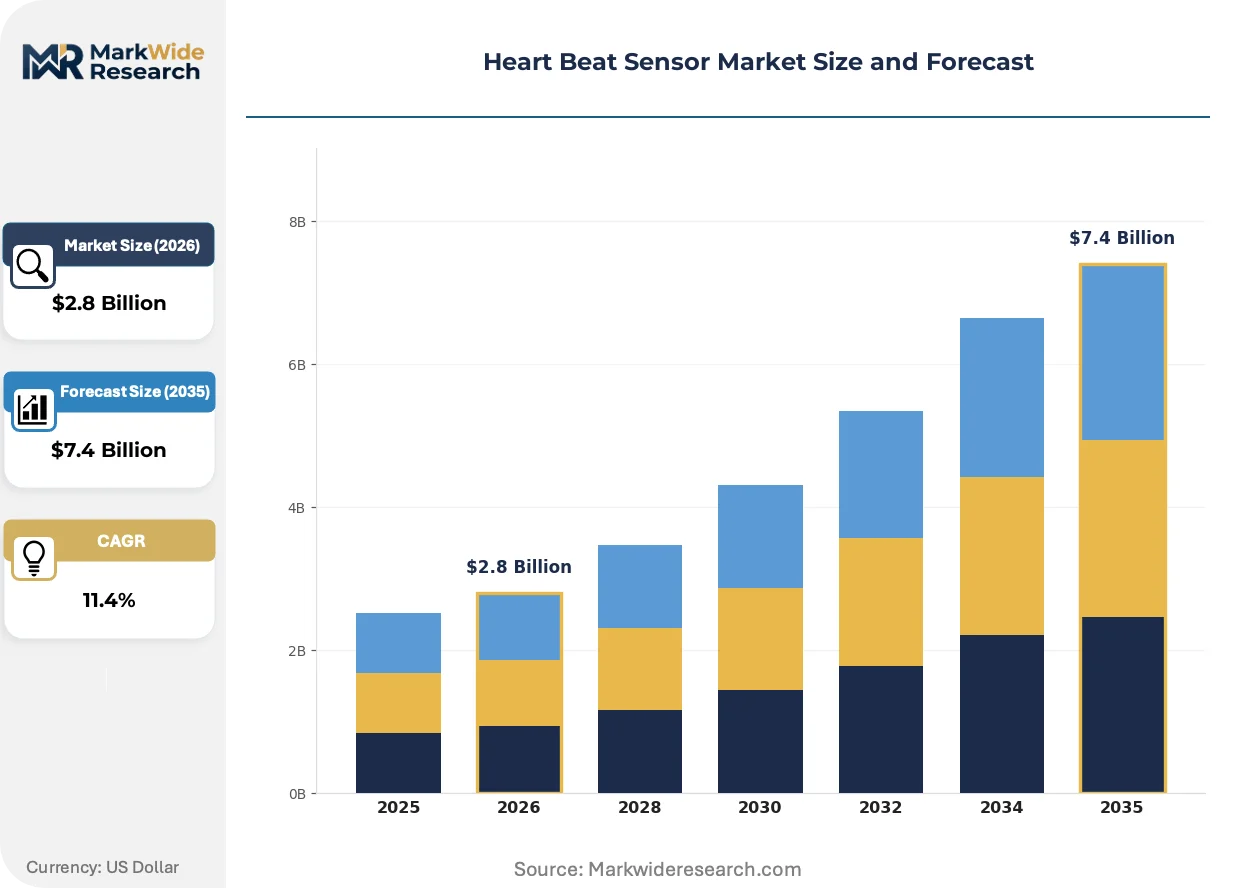
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable, Non-invasive Monitor, Implantable Device, Smartphone Integration End User: Clinics, Hospitals, Home Care, Fitness Centers Technology: Optical, Electrical, Ultrasound, Acoustic Application: Cardiac Monitoring, Fitness Tracking, Telemedicine, Emergency Response |
| Companies Covered | Apple, Samsung Electronics, Garmin, Omron Healthcare, Philips, Medtronic, Texas Instruments, Nihon Kohden, GE HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Beat Sensor Market Shifts & Advancements
Sensor fusion architectures and regulatory pathway evolution are redefining competitive moats in cardiac monitoring hardware, compressing the gap between consumer fitness and clinical diagnostic fidelity.
Multi-wavelength optical engines are integrating green, red, and infrared LEDs with photodiode arrays to isolate arterial blood flow from motion artifacts and ambient light interference. Hospital procurement committees are specifying these configurations for remote patient monitoring contracts previously reserved for electrical Holter monitors. The technology is integrating SpO2 and heart rate variability into single-module designs that reduce bill-of-materials complexity for wearable OEMs.
The EU MDR's 2021 enforcement tightened clinical evaluation requirements for software-driven heart rate algorithms, forcing manufacturers to generate real-world performance data across diverse patient phenotypes. Notified bodies in Germany and the Netherlands are prioritizing technical documentation reviews for devices with embedded artificial intelligence diagnostic functions. Cardiology clinics in France and Switzerland are delaying purchase decisions until CE marking under the new framework is confirmed.
Hospital systems are unbundling cardiac monitoring hardware from long-term service contracts, shifting toward capital-expenditure purchasing with internal biomedical engineering maintenance teams. This procurement model change favors sensor vendors with open API architectures and replaceable component designs over vertically integrated platform providers. The United States and Germany exhibit the fastest adoption of this disaggregated purchasing approach, particularly among academic medical centers with established in-house device management capabilities.
Heart Beat Sensor Market Segmentation
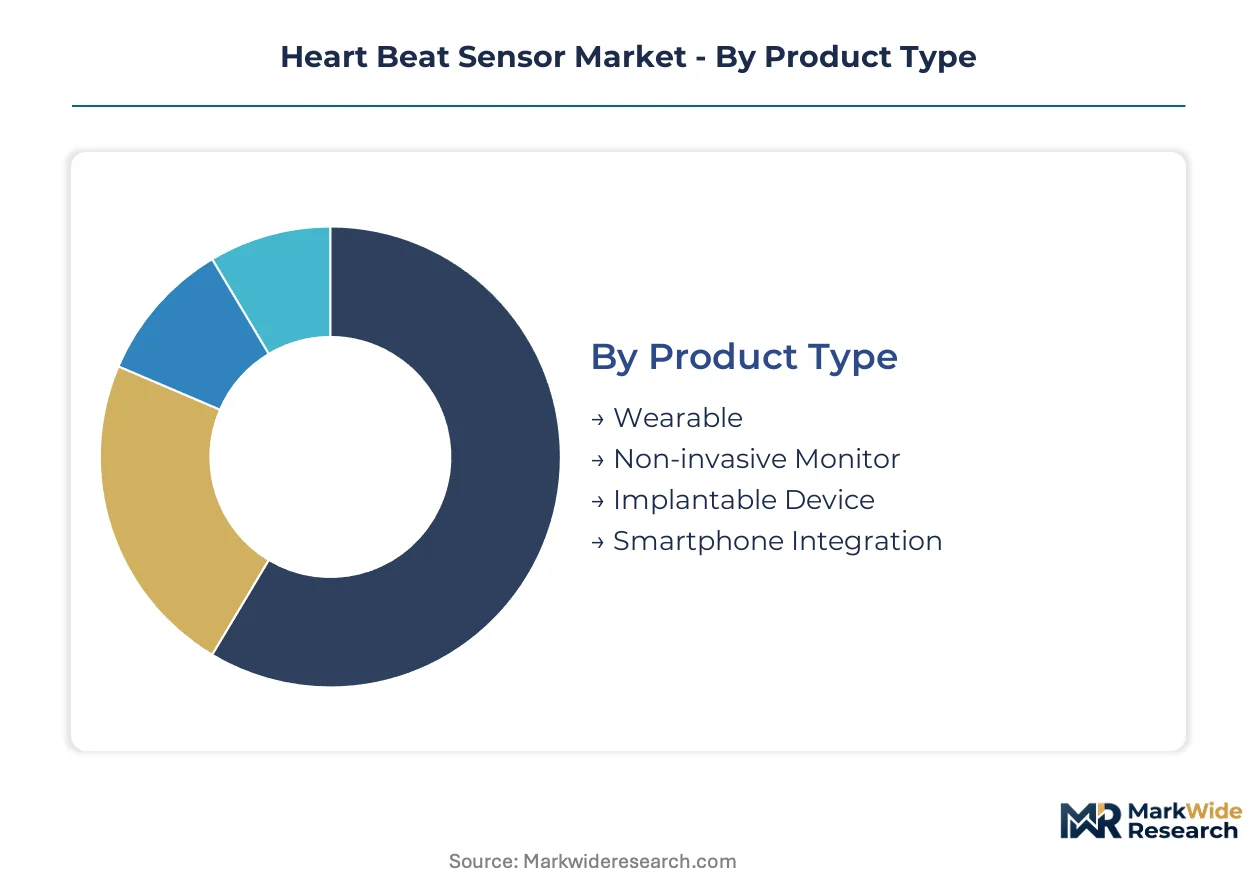
Segmentation in the heart beat sensor market determines regulatory pathway complexity and margin architecture. Product type governs FDA De Novo versus 510(k) submission requirements, while technology choice dictates whether skin-tone-independent accuracy or cost minimization drives procurement decisions.
Product Type:
Wearable devices face streamlined FDA clearance under De Novo pathways for consumer ECG functionality, whereas implantable devices trigger PMA requirements and extended clinical trial obligations.
- Wearable:Wrist-worn and chest-strap configurations integrate photoplethysmography optical engines with accelerometer fusion for motion artifact rejection. Demand concentrates in the United States and Germany where employer wellness subsidies and DiGA reimbursement expand prescription-grade deployment.
- Non-invasive Monitor:Bedside and handheld units employ electrical sensing through disposable Ag/AgCl electrodes for arrhythmia detection in acute care settings. Hospital procurement committees in France and Switzerland specify these for telemetry wards where clinical-grade accuracy governs purchasing.
- Implantable Device:Leadless pacemakers and insertable cardiac monitors command premium pricing through long-term monitoring contracts.
- Smartphone Integration:Camera-based photoplethysmography and accessory dongles leverage existing device penetration for low-cost screening.
Leading the category by volume: Wearable. Expanding most quickly: Smartphone Integration.
End User:
Customer type determines pricing tolerance and certification stringency, with institutional buyers demanding ISO 13485 quality systems and home care channels prioritizing ease-of-use over clinical documentation.
- Clinics:Outpatient cardiology practices specify portable ECG devices with cloud-connected interpretation for same-day arrhythmia screening. Demand clusters in Germany's ambulatory care network where DiGA fast-track reimbursement reduces patient out-of-pocket burden.
- Hospitals:Academic medical centers in the United States unbundle hardware from service contracts, favoring open-API architectures that integrate with Epic and Cerner EMR systems.
- Home Care:Post-discharge remote monitoring programs drive prescription-grade wearable adoption.
- Fitness Centers:Commercial gym chains deploy consumer-grade optical sensors for member retention analytics.
Capturing highest margins: Hospitals. Gaining share fastest: Home Care.
Technology:
Technical approach governs signal fidelity, power consumption, and dermatological compatibility, with electrical methods retaining institutional preference despite optical dominance in unit shipments.
- Optical:Green LED photoplethysmography samples blood volume changes at 100-512 Hz, with multi-wavelength engines adding red and infrared for SpO2 correlation. Asian foundries redirect wafer capacity toward these chipsets, resolving prior supply constraints for wearable OEMs.
- Electrical:Analog front-ends amplify myocardial depolarization signals through skin-contact electrodes, achieving superior arrhythmia detection accuracy that hospital procurement committees specify for diagnostic-grade contracts.
- Ultrasound:Doppler perfusion measurement bypasses melanin absorption variability, opening cardiac monitoring in dermatologically diverse populations.
- Acoustic:Phonocardiography through MEMS microphones captures heart sounds for murmur detection in resource-limited settings.
Dominating unit shipments: Optical. Steepest expansion trajectory: Ultrasound.
Application:
Use case determines algorithm complexity and reimbursement eligibility, with clinical applications requiring FDA-cleared diagnostic claims and fitness applications operating under general wellness exemptions.
- Cardiac Monitoring:Continuous arrhythmia detection and heart failure decompensation预警 drive prescription-grade device adoption. Germany's DiGA framework and United States remote patient monitoring billing codes create institutional procurement pull.
- Fitness Tracking:Calorie estimation and recovery metrics leverage optical heart rate for consumer wellness applications exempt from FDA medical device classification.
- Telemedicine:Asynchronous ECG review and real-time video-integrated monitoring expand rural access.
- Emergency Response:Automated external defibrillator-integrated sensing and first-responder patch monitors enable pre-hospital triage.
Generating largest revenue pool: Cardiac Monitoring. Climbing the fastest: Telemedicine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium arsenide and indium phosphide substrate production in Taiwan anchors optical biosensing wafer supply for wearable heart rate modules. Foundry capacity allocation decisions in Hsinchu Science Park directly determine lead times for photoplethysmography chipsets serving OEMs across consumer and medical device tiers.
United States
Employer wellness subsidies and remote patient monitoring billing codes drive prescription-grade wearable adoption. FDA's De Novo pathway expansion accelerates consumer ECG device clearances. Minneapolis-St. Paul hosts Medtronic's cardiac rhythm management operations alongside a cluster of medical device startups.
Germany
DiGA fast-track reimbursement creates institutional procurement pull for chronic cardiac care monitors. EU MDR technical documentation requirements tighten clinical evidence standards for Class IIa devices. Baden-Württemberg's precision engineering corridor concentrates sensor assembly and testing operations.
China
Domestic wearable brands exploit cost-optimized supply chains for fitness tracker volume production. NMPA tightened GB standard compliance extends certification timelines for imported devices. Shenzhen's electronics manufacturing ecosystem integrates optical module assembly with downstream OEM fulfillment.
Japan
Aging demographics expand home-based cardiac monitoring program enrollment. PMDA pharmaceutical-medical device convergence rules enable heart rate-responsive drug delivery combination products. Tokyo-Osaka corridor houses Nihon Kohden's patient monitoring systems development and manufacturing footprint.
India
Production-linked incentive schemes attract sensor module assembly capacity for domestic wearable brands. CDSCO medical device rules harmonize with ASEAN regulatory frameworks for export-oriented manufacturing. Karnataka's electronics manufacturing clusters near Bangalore expand cleanroom fabrication for biosensing components.
Heart Beat Sensor Market Competitive Landscape
Global majors compete with regional champions across semiconductor design, device manufacturing, and healthcare distribution dimensions. The vendor base organizes into three tiers: vertically integrated technology conglomerates controlling silicon-to-device stacks; specialized medical device manufacturers with institutional sales channels; and component suppliers delivering analog front-ends and optical engines to downstream OEMs. Dominant competitive moves include strategic partnerships between foundries and wearable brands to secure wafer allocation, and geographic expansion of regulatory affairs capabilities to navigate divergent FDA, EU MDR, and NMPA pathways.
Within the integrated technology tier, Apple and Samsung Electronics exemplify captive silicon design strategies that internalize optical engine performance optimization. Texas Instruments occupies a position among analog semiconductor specialists supplying ultra-low-power front-end components across wearable and clinical device OEMs. These three anchors illustrate divergent approaches to value capture: full-stack vertical control versus modular component supply.
| Leading Market Players |
|---|
| Apple |
| Samsung Electronics |
| Garmin |
| Omron Healthcare |
| Philips |
| Medtronic |
| Texas Instruments |
| Nihon Kohden |
| GE HealthCare |
| Others |
Supply & Pricing Matrix
EU MDR technical documentation mandates and RoHS substance restrictions gate qualified supply for premium-tier optical biosensing modules, compressing vendor pools capable of serving institutional procurement channels while sustaining margin premiums for compliant manufacturers.
Pricing Analysis
Service bundling separates capital-expenditure hardware purchases from long-term maintenance contracts, with academic medical centers in the United States and Germany unbundling these components to internalize biomedical engineering capabilities. Pricing stratifies across FDA-cleared diagnostic tiers, CE-marked clinical grades, and general wellness exemptions, with certification level and volume scale driving differentiation. Cost compression in consumer optical sensors intensifies as Asian foundries expand photoplethysmography wafer capacity. Fitness centers and direct-to-consumer channels exhibit highest price sensitivity, while implantable device contracts show lowest elasticity due to regulatory barriers and monitoring service lock-in.
Supply Chain Analysis
Regional distribution centers in Hsinchu Science Park, Shenzhen, and Baden-Württemberg coordinate hub-and-spoke fulfillment for optical biosensing modules and analog front-end components. Taiwan, South Korea, and China anchor gallium arsenide substrate production, photoplethysmography chipset fabrication, and downstream module assembly. The chain draws from silver-silver chloride electrode materials, indium phosphide wafers, and ultra-low-power analog components. Single-source vulnerability concentrates in Taiwan's foundry capacity for optical engines. Distribution runs through medical device distributors, direct OEM contracts, and electronics manufacturing service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity allocation for photoplethysmography silicon sustains supply-constrained pricing power, with wafer reallocation from legacy CMOS image sensors limiting immediate expansion and propping margins for qualified suppliers.
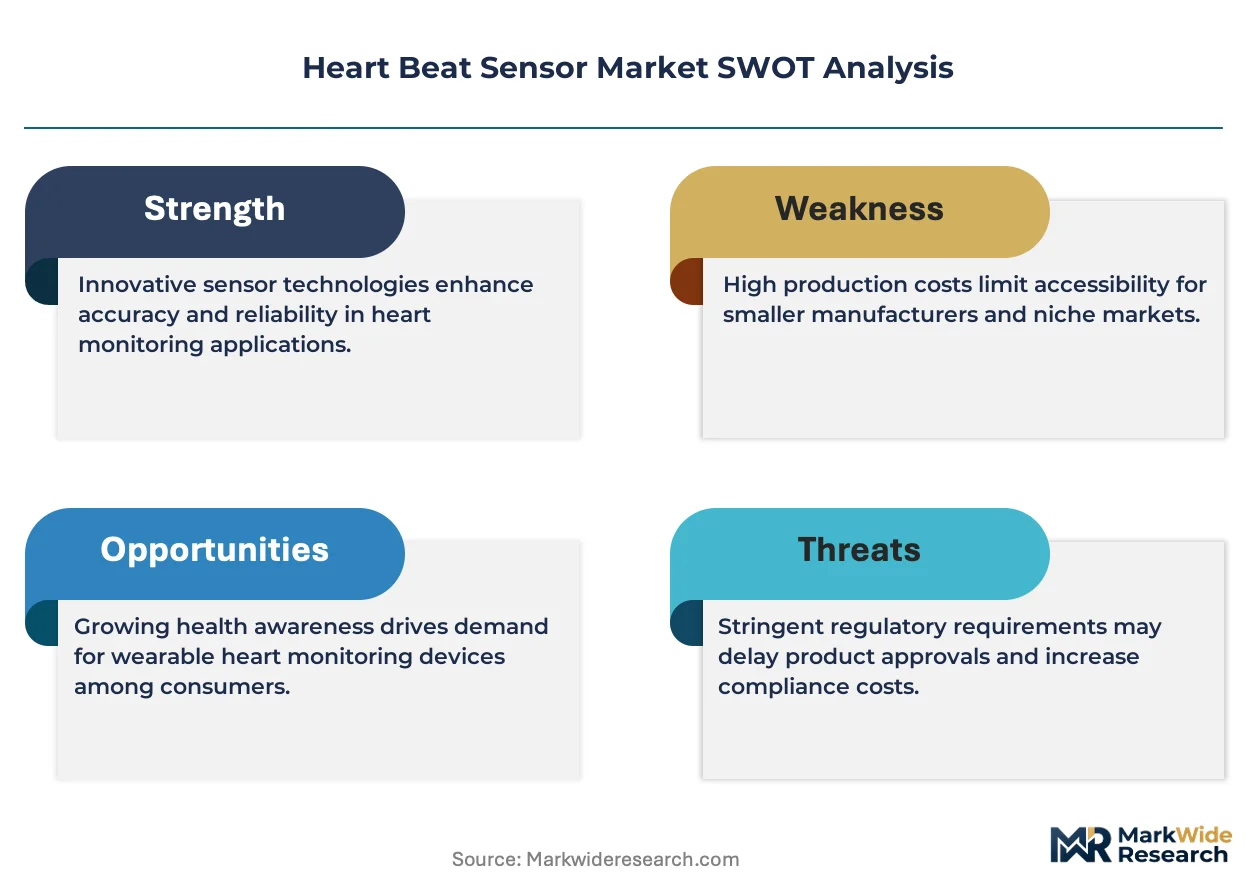
For Market Incumbents: Deepen backward integration into optical engine design to defend against display-integrated sensor architectures from Korean conglomerates. Prioritize certification investment in EU MDR Class IIa technical documentation to maintain hospital procurement access as notified bodies tighten clinical evidence requirements. Lock in long-term wafer allocation agreements with Hsinchu-based foundries before capacity redirects further toward automotive and AI accelerators. For New Entrants and Emerging Players: FDA's De Novo pathway expansion in the United States opens a window for prescription-grade wearable ECG devices targeting remote patient monitoring billing codes. Focus initial penetration on Germany's DiGA fast-track reimbursement framework for chronic cardiac care applications, where institutional procurement pull exceeds saturated consumer fitness channels. Partner with Asian foundries on photoplethysmography chipset co-development to bypass established analog front-end supply relationships. For Investors and Strategic Acquirers: Hospital system unbundling of hardware from service contracts is the leading indicator that open-API architecture capabilities will command acquisition premiums. The five-to-ten year viability window favors targets with embedded AI diagnostic functions and replaceable component designs. Monitor notified body backlog clearance velocities in Germany and the Netherlands as inflection signals for EU MDR market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Wavelength Optical Engine Development | Integrates SpO2 and heart rate variability for reduced bill-of-materials complexity in wearable OEM designs. |
| FDA De Novo Pathway Navigation | Accelerates consumer ECG device clearances for regulated home monitoring use cases in the United States. |
| EU MDR Technical Documentation Investment | Secures CE marking for Class IIa devices under tightened clinical evidence requirements in Germany and the Netherlands. |
| Foundry Wafer Allocation Partnership | Locks in photoplethysmography chipset supply from Hsinchu Science Park capacity reallocation. |
| Telemedicine Ultrasound Integration | Bypasses skin-tone dependency for cardiac monitoring contracts in dermatologically diverse patient populations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across biomedical engineers, hospital purchasing committee members, GPO contracts managers, and wearable OEM product directors. FDA 510(k) and De Novo submission databases, EU MDR notified body technical documentation reviews, and NMPA GB standard compliance records supplemented quantitative sizing. Bottom-up demand modeling triangulated against top-down semiconductor foundry capacity allocation data.
Data-stream reconciliation across shipment volumes, certification timelines, and reimbursement code utilization established the analytical framework. Segmentation dimensions spanned product type, technology modality, end-user channel, and regional regulatory cluster. CAGRs derived from installed base growth, replacement cycles, and penetration rate assumptions. Forecast inputs incorporated photoplethysmography chipset yield rates and EU MDR notified body review velocity.
The model assumes a particular technology adoption path; alternative pathways for ultrasound-based perfusion measurement would alter the outlook if dermatological accuracy concerns accelerate clinical preference shifts. Forecasts reflect documented assumptions regarding foundry capacity reallocation and regulatory pathway evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Ambient Light Sensor Market
Sensors and Controls
Reservoir Monitoring System Market
Sensors and Controls
Magnetic Field Sensor Market
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
Tip Location Devices Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
Global Acoustic Wave Sensor Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
North America Water Detection Sensors Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Taiwan Sensors Market
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
Middle East and Africa Lidar Market
Sensors and Controls
Smart Dust Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market