
 Sensor Based Sorting System Market | 2026-2036
Sensor Based Sorting System Market Size, Share, and Industry Trends Forecast 2026-2036
Sensor Based Sorting System Market Insights
EU Green Deal waste hierarchy mandates are restructuring capital deployment timelines for sorting infrastructure across European material recovery facilities. TOMRA Systems ASA leverages its installed base of optical sorters to sustain aftermarket service revenue in Nordic recycling hubs. Bühler AG anchors its competitive position through integrated food safety platforms that combine optical detection with real-time contamination alerts. Steinert GmbH competes in magnetic and sensor-based metal recovery systems for automotive shredder residue applications.
A sensor based sorting system deploys electromagnetic, optical, or acoustic detection arrays to classify objects by material composition, color, density, or shape at conveyor speeds exceeding three meters per second, generating pneumatic or mechanical ejection signals for automated separation. These systems execute primary industrial functions in waste recovery streams, food safety inspection lines, and mineral beneficiation circuits where manual sorting proves uneconomical or hazardous. Optical sensor configurations currently lead technology procurement in recycling and food processing applications due to mature hyperspectral imaging pipelines and declining CMOS detector costs. Integrated solution packages are expanding fastest among end user categories as manufacturers demand unified hardware-software platforms with predictive maintenance dashboards rather than standalone sorting machines.
EPA Resource Conservation and Recovery Act enforcement in the United States tightens contamination thresholds for recycled commodity exports, compelling domestic MRF operators to upgrade legacy sorting lines with multi-sensor detection arrays. REACH substance restrictions and ECHA persistent organic pollutant listings in Europe force electronics recyclers to deploy X-ray fluorescence and near-infrared sensor combinations for precise hazardous material identification. Stakeholders must evaluate sensor fusion architectures that combine multiple detection modalities against single-technology systems as regulatory precision requirements intensify and commodity purity specifications tighten across export markets.
Market Dynamics
EU Green Deal circular economy mandates are compressing capital deployment timelines for automated sorting infrastructure, forcing material recovery facilities to consolidate multi-sensor detection arrays into unified procurement packages rather than incremental machine additions.
Growth Catalysts
- REACH persistent organic pollutant listings:Electronics recyclers across Europe deploy X-ray fluorescence and near-infrared combinations for hazardous material identification, expanding addressable equipment demand.
- Food processing automation:North American protein and produce packers accelerate hyperspectral imaging adoption to eliminate manual inspection labor and contamination liability exposure.
- Mineral beneficiation circuits:Copper and lithium concentrate producers in Chile and Australia integrate sensor-based ore sorting to reduce downstream energy intensity and tailings volume.
Market Restraints
- CMOS detector supply concentration:Japanese and South Korean semiconductor fabs control critical imaging sensor supply, creating input cost volatility and extended lead times for European and North American OEMs.
- Technical limitation in black plastic identification:Near-infrared spectroscopy fails to distinguish polymer types in carbon-black pigmented packaging, forcing reliance on costly X-ray or robotic alternatives.
- Substitution threat from chemical recycling:Pyrolysis and solvolysis technologies that tolerate mixed feedstocks reduce purity requirements for mechanical recycling streams, dampening optical sorter demand in certain plastic recovery applications.
Strategic Opportunities
- Underpenetrated textile recovery:Post-consumer garment sorting in India and Bangladesh remains manual-intensive, creating whitespace for automated fiber identification systems as extended producer responsibility frameworks expand to apparel.
- Technology convergence:Deep learning inference engines fused with hyperspectral imaging enable real-time material classification at conveyor speeds previously requiring multiple discrete sensor types.
- IRA clean energy manufacturing credits:Domestic battery materials recovery investments in the United States accelerate demand for sensor-based lithium-ion black mass sorting to qualify for domestic content incentives.
Industry Challenges
- Integration complexity with legacy MRF infrastructure:Retrofitting 1990s-era single-stream sorting lines with multi-sensor arrays requires conveyor reconfiguration and compressed air system upgrades that extend commissioning timelines.
- Certification timeline compression:CE marking and FDA food contact safety approvals for new detection algorithms demand validation datasets that slow product release cycles.
- Skill gap in sensor fusion calibration:Maintenance technicians trained on mechanical sorters lack competency in hyperspectral camera alignment and machine learning model retraining protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensor Based Sorting System Market |
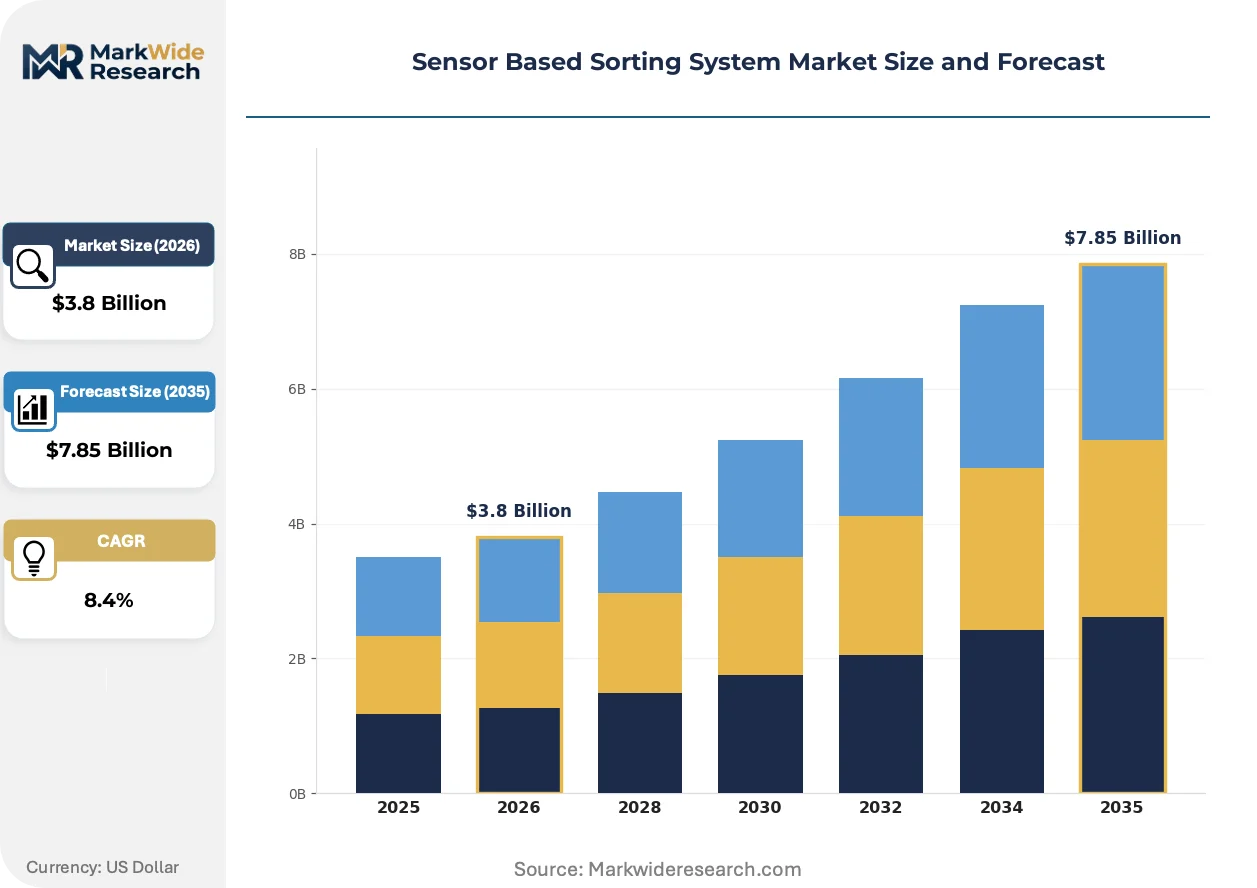
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Optical Sensors, Proximity Sensors, Ultrasonic Sensors, Magnetic Sensors Application: Recycling, Food Processing, Pharmaceutical, E-commerce End User: Manufacturers, Distributors, Waste Management, Retailers Solution: Automated Sorting, Manual Sorting Assistance, Integrated Systems, Real-time Monitoring |
| Companies Covered | TOMRA Systems ASA, Bühler AG, Steinert GmbH, Sesotec GmbH, Key Technology LLC, REDWAVE, Metso, Eriez Manufacturing Co., Satake Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensor Based Sorting System Market Trends and Innovations
Hyperspectral imaging pipelines are maturing from laboratory instruments to production-hardened platforms, compressing the performance gap between research-grade detection and industrial throughput requirements.
Deep learning-enabled material classification is consolidating discrete detection tasks—color, polymer type, contamination identification—into single-pass processing architectures. Food processors and recycling operators adopt these unified platforms to reduce hardware footprint and maintenance complexity. The structural consequence is vendor consolidation as pure-play optical specialists acquire AI software capabilities to defend equipment margins.
EPA Resource Conservation and Recovery Act enforcement tightens contamination thresholds for exported recycled commodities, compelling domestic material recovery facilities to deploy redundant sensor arrays for quality assurance documentation. Operators in California and New York face the steepest compliance gradients and are prioritizing multi-modal detection investments ahead of 2026 inspection cycles.
Equipment-as-a-service contracting is displacing capital purchase models among mid-tier recycling cooperatives and regional food packers. German and Dutch operators lead this transition, negotiating throughput-based pricing with predictive maintenance guarantees that transfer obsolescence risk to OEMs. The financing innovation accelerates technology refresh rates while compressing vendor margins and locking in long-term service relationships.
Sensor Based Sorting System Market Segmentation
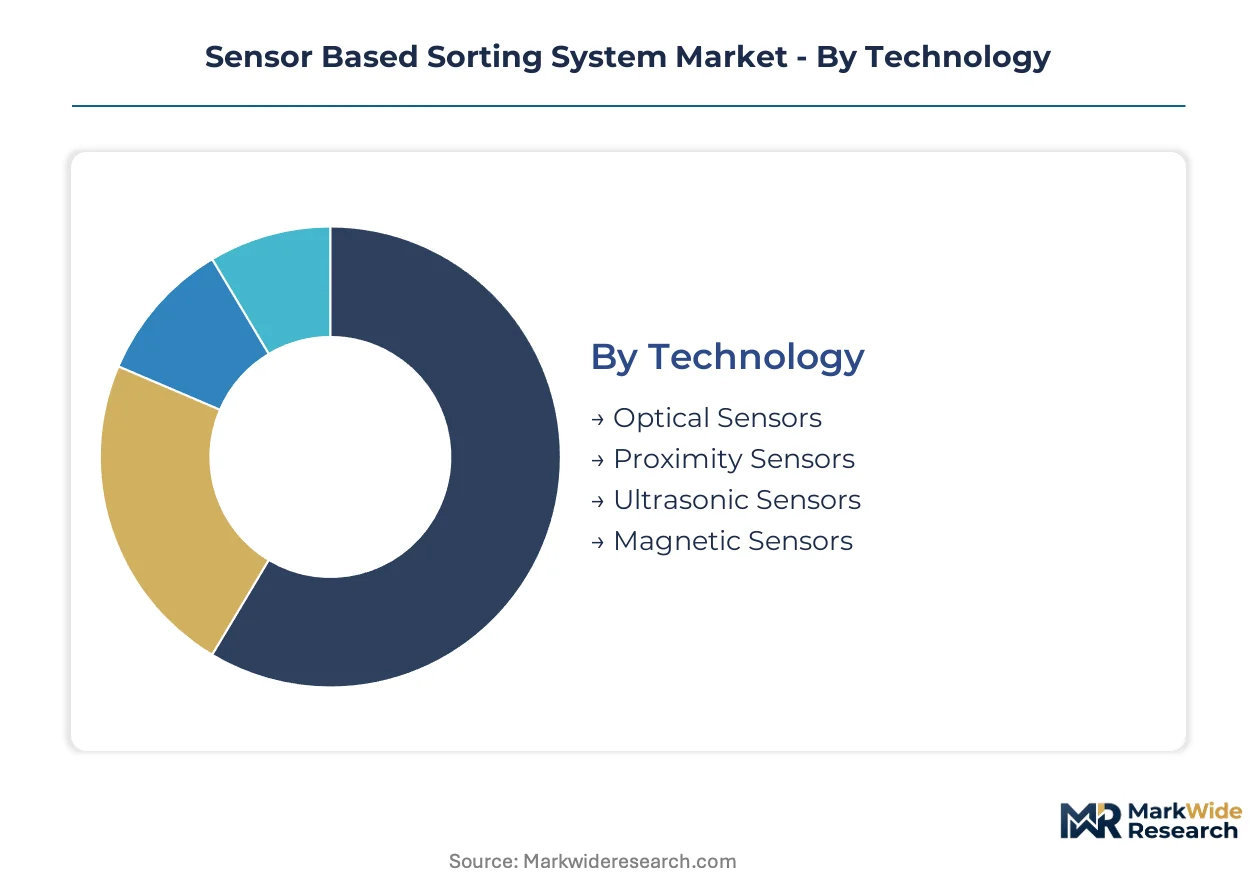
Technology heterogeneity in sensor based sorting creates distinct upgrade cycles across end-use verticals. Procurement decisions fragment by detection modality, integration complexity, and regulatory compliance burden rather than throughput alone.
Technology:
Replacement cycles accelerate as facilities retire single-modality sorters for multi-sensor fusion architectures that satisfy tightening purity specifications.
- Optical Sensors:Hyperspectral imaging and CMOS-based color detection arrays dominate new installations in recycling and food safety lines. German MRF operators and California produce packers drive procurement volume as EPA contamination thresholds and FDA food contact rules harden detection requirements.
- Magnetic Sensors:Eddy current and ferrous detection systems recover non-ferrous and ferrous metals from automotive shredder residue and e-waste streams. Chilean copper concentrators and Nordic electronics recyclers anchor demand as REACH persistent organic pollutant listings force hazardous material identification protocols.
- Proximity Sensors:Inductive and capacitive detection handles ferrous metal proximity sensing in high-speed conveyor applications.
- Ultrasonic Sensors:Acoustic density measurement distinguishes material thickness and internal voids in mineral beneficiation circuits.
Volume placements concentrate in Optical Sensors; the faster expansion belongs to Magnetic Sensors.
Application:
End-use margin structures determine willingness to absorb premium detection technology versus legacy mechanical alternatives.
- Recycling:Material recovery facilities deploy multi-sensor arrays for plastic, paper, and metal stream purification under tightening export contamination limits. EU Green Deal circular economy targets compress capital deployment timelines across German, Dutch, and Belgian sorting hubs.
- Food Processing:Hyperspectral imaging eliminates manual inspection labor in protein, produce, and grain handling lines. North American packers prioritize contamination liability reduction over labor cost savings alone.
- Pharmaceutical:Vision systems verify tablet integrity, packaging correctness, and lot traceability in high-value dosage form manufacturing.
- E-commerce:Automated parcel dimensioning and weight verification accelerates fulfillment center throughput.
Revenue concentration sits with Recycling; steepest expansion trajectory appears in Food Processing.
End User:
Customer scale and technical staffing depth create divergent purchasing patterns between integrated solution demand and standalone equipment procurement.
- Manufacturers:Food, pharmaceutical, and mineral processing producers demand unified hardware-software platforms with predictive maintenance dashboards. Equipment-as-a-service contracting gains traction among mid-tier operators seeking to transfer obsolescence risk.
- Waste Management:Municipal and private MRF operators retrofit legacy single-stream lines with multi-sensor detection arrays. California and New York facilities face the steepest EPA compliance gradients.
- Distributors:Regional equipment resellers serve smaller recycling cooperatives lacking direct OEM relationships.
- Retailers:Reverse logistics centers deploy parcel sorting automation for returns processing.
Procurement volume clusters with Manufacturers; Waste Management shows the fastest technology refresh rates.
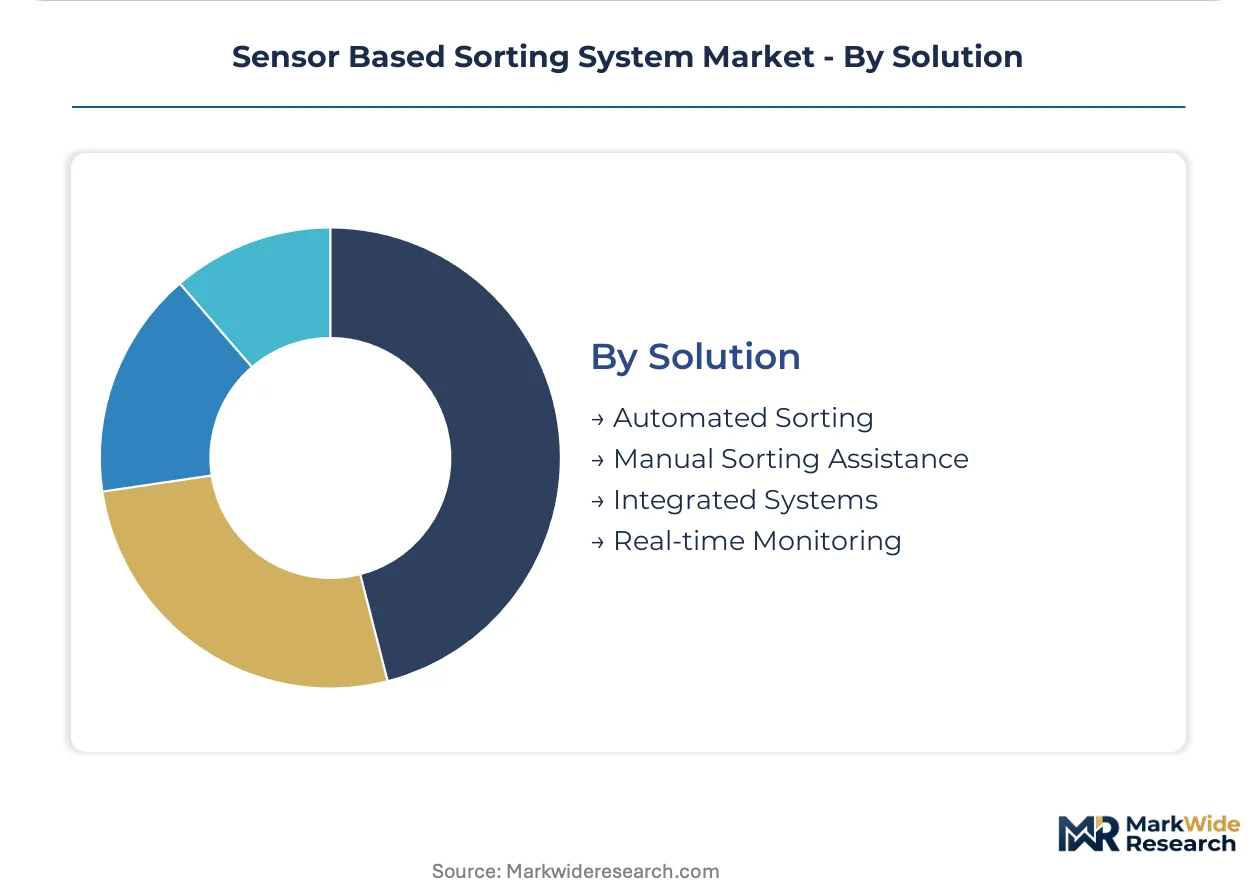
Solution:
Integration depth separates price-competitive hardware sales from recurring revenue service relationships.
- Integrated Systems:Unified detection, ejection, and data analytics platforms consolidate vendor relationships and reduce maintenance complexity. German and Dutch operators lead adoption of throughput-based pricing with predictive maintenance guarantees.
- Real-time Monitoring:Cloud-connected performance dashboards enable remote calibration and model retraining for hyperspectral classification algorithms.
- Automated Sorting:Standalone pneumatic or mechanical ejection systems without integrated analytics.
- Manual Sorting Assistance:Operator guidance systems that augment rather than replace human pickers.
Deployment share concentrates in Integrated Systems; Real-time Monitoring climbs the fastest as connectivity infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the UAE and special economic corridors in Vietnam concentrate new sorting infrastructure investments as manufacturers relocate processing capacity to tariff-advantaged locations.
United States
Domestic battery materials recovery investments accelerate demand for lithium-ion black mass sorting systems. IRA clean energy manufacturing credits require domestic content qualification that sensor-based separation enables. Texas and Arizona processing hubs attract capital for cathode precursor material recovery.
Germany
Material recovery facilities in the Rhine-Ruhr and Bavarian industrial belts consolidate multi-sensor procurement packages under compressed EU Green Deal timelines. REACH persistent organic pollutant enforcement forces electronics recyclers to deploy X-ray fluorescence arrays. Hamburg port logistics operators upgrade containerized waste inspection lines.
China
Dual carbon goals drive copper concentrators in Jiangxi and Yunnan to integrate ore sorting for energy intensity reduction. GB standards for recycled plastics harden detection requirements for domestic mechanical recycling streams. Yangtze River Delta e-waste processors expand automated hazardous material identification capacity.
Chile
Copper concentrate producers in the Atacama and Antofagasta regions deploy sensor-based ore sorting to reduce downstream smelting energy consumption and tailings volume. National mining codes increasingly mandate water-efficient beneficiation technologies. Calama processing clusters anchor technology adoption.
India
Extended producer responsibility frameworks for electronics and plastics expand addressable equipment demand beyond food processing. BIS certification requirements for imported recycling machinery compress vendor qualification timelines. Gujarat and Maharashtra material recovery facilities lead automated infrastructure deployment.
Sensor Based Sorting System Market Competitive Landscape
German and Swiss producers anchor one tier in integrated food safety and recycling platforms; Nordic specialists hold differentiated positions in optical detection for beverage container recovery. The vendor structure consolidates around three strategic archetypes: integrated solution providers bundling hardware-software-analytics, pure-play sensor technology licensors, and regional system integrators serving mid-tier recycling cooperatives. Equipment-as-a-service contracting and AI-enabled detection algorithm development represent the dominant competitive vectors reshaping customer relationships.
Within the integrated solution tier, TOMRA Systems ASA and Bühler AG exemplify platform providers consolidating aftermarket service relationships through predictive maintenance guarantees. Steinert GmbH occupies a position among magnetic and sensor-based metal recovery specialists serving automotive shredder residue applications. These three entities represent contrasting geographic and technological positioning strategies visible across procurement decisions in European and North American material recovery facilities.
| Leading Market Players |
|---|
| TOMRA Systems ASA |
| Bühler AG |
| Steinert GmbH |
| Sesotec GmbH |
| Key Technology LLC |
| REDWAVE |
| Metso |
| Eriez Manufacturing Co. |
| Satake Corporation |
| Others |
Pricing and Supply Chain Analysis
Hyperspectral imaging platform maturation is compressing CMOS detector costs while concentrating procurement power among Japanese and South Korean semiconductor fabs, simultaneously reshaping equipment economics and input supply vulnerability for European and North American OEMs.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations as California MRF operators and German food processors pay 15-25% markups for expedited CMOS sensor delivery. Equipment-as-a-service contracting spreads three-tier pricing structure across premium, standard, and economy levels based on predictive maintenance bundling and algorithm update frequency. Pricing pressure stems from Japanese semiconductor fab capacity constraints extending component lead times. Regional recycling cooperatives exhibit highest price sensitivity; integrated food safety platforms command lowest elasticity due to contamination liability exposure.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and South Korean CMOS detector fabrication, where Sony and Samsung anchor global imaging sensor output. German optical lens assemblies and Chinese pneumatic ejection components complete the bill of materials. Supply chain risk centers on tariff exposure for semiconductor imports into European assembly facilities. Distribution runs through direct OEM sales teams for integrated platforms and regional resellers for standalone sensor modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal circular economy mandates and EPA Resource Conservation and Recovery Act enforcement are elevating compliance costs into a structural barrier-to-entry moat, favoring incumbents with validated CE marking and FDA food contact safety portfolios.
For Market Incumbents: Deepen aftermarket service revenue through predictive maintenance guarantees that lock in multi-year relationships with German and Dutch recycling operators. Expand in-house CMOS detector buffer inventory to offset Japanese semiconductor fab lead time volatility. Cement position against chemical recycling substitution threats by demonstrating mechanical purity thresholds that pyrolysis cannot economically match. For New Entrants and Emerging Players: Launch via equipment-as-a-service contracting to bypass capital-constrained mid-tier recycling cooperatives in India and Bangladesh. Target post-consumer textile recovery in South Asian garment hubs where extended producer responsibility frameworks are expanding addressable demand. Lead with AI-enabled fiber identification algorithms that reduce hardware footprint versus legacy hyperspectral installations. For Investors and Strategic Acquirers: Re-rating potential sits with integrated solution providers given equipment-as-a-service contracting acceleration transferring obsolescence risk to OEMs. Long-term viability favors vendors with captive AI software development capabilities rather than pure-play hardware manufacturers. Monitor CE marking and FDA approval timeline compression as inflection indicator for product release cycle competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Acquisition | Consolidates discrete detection tasks into single-pass architectures that reduce hardware footprint for food processors. |
| CMOS Detector Inventory Expansion | Mitigates Japanese semiconductor fab lead time volatility extending equipment delivery schedules. |
| Equipment-as-a-Service Launch | Transfers obsolescence risk to OEMs while accelerating technology refresh rates among German operators. |
| Textile Recovery Platform Development | Captures whitespace in Indian and Bangladeshi garment sorting as extended producer responsibility expands. |
| Predictive Maintenance Guarantee Rollout | Locks in long-term service relationships with California MRF operators facing EPA compliance gradients. |
Research Methodology
Document review covered SEC filings from TOMRA Systems ASA and Bühler AG, EU Green Deal implementation reports, and EPA enforcement actions, complemented by interviews with MRF operations directors, food safety quality managers, and aftermarket service heads. Secondary validation drew from customs trade data, CE marking notification databases, and semiconductor industry supply disclosures. Bottom-up equipment shipment analysis and top-down end-use market sizing were triangulated against primary fieldwork.
Historical capacity deployment patterns were cross-referenced against panel input from OEM product managers and recycling cooperative procurement leads across the analysis window. Segmentation modeling incorporated technology modality, application vertical, end-user scale, and solution integration depth. CAGRs were derived from regression analysis of capital expenditure cycles and regulatory compliance timeline compression. Forecast inputs included EU REACH persistent organic pollutant listing enforcement schedules and IRA clean energy manufacturing credit qualification requirements.
The model assumes a particular technology adoption path; alternative pathways for chemical recycling feedstock tolerance would alter the outlook for mechanical sorting equipment demand. Forecasts reflect assumptions regarding semiconductor supply normalization and regulatory inspection cycle timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Glucose Sensor Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
Temperature Monitoring Devices Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
Americas Sensor Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Europe Machine Condition Monitoring Market
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Wireless Temperature Sensor Market