
 Induction Cooktops Market | 2026-2036
Induction Cooktops Market Size, Share, and Industry Trends Forecast 2026-2036
Induction Cooktops Market Intelligence
The traditional appliance retail channel is fragmenting as direct-to-consumer online sales and specialized kitchen design showrooms gain share. Bosch leverages its strong brand reputation and engineering focus in the premium built-in segment. Samsung competes on smart features and connectivity, integrating cooktops into its broader smart home ecosystem. Miele sustains its market position through a focus on durability and high-performance commercial-grade technology for residential applications.
An induction cooktop utilizes electromagnetic fields to directly heat ferromagnetic cookware, bypassing the cooktop surface. This method provides rapid, highly efficient, and precise thermal control compared to traditional electric or gas ranges. Built-in models command the residential market, aligning with kitchen renovation trends and new construction specifications. While freestanding units serve the replacement market, portable cooktops represent the fastest-growing product type, driven by their flexibility in both residential and light commercial settings like catering.
Energy efficiency regulations are a primary market shaper, with programs like the US ENERGY STAR certification and the EU's Ecodesign Directive setting stringent performance benchmarks. In China, compliance with GB standards for electrical safety and energy consumption is mandatory for market access. Future competitive advantage will depend on integrating advanced sensor technology for automated cooking and enhanced safety features.
Market Dynamics
The market's primary structural force is the global policy-driven push for residential electrification. This momentum, aimed at decarbonization, is accelerating the displacement of natural gas cooking appliances, creating a direct regulatory tailwind for induction technology adoption in new construction and renovations.
Growth Catalysts
- Government Electrification Mandates:Policies aligned with frameworks like the EU Green Deal phase out gas appliances in residential buildings, creating regulatory-driven demand for induction cooktops as the primary electric alternative.
- Smart Home Integration:The convergence of cooktops with IoT platforms appeals to consumers seeking convenience, integrating the kitchen into a broader connected home ecosystem controlled by mobile apps.
- Rapid Urbanization:Concentrated development in China's metropolitan regions drives demand for modern, energy-efficient kitchen appliances suitable for new high-rise residential construction specifications.
Market Restraints
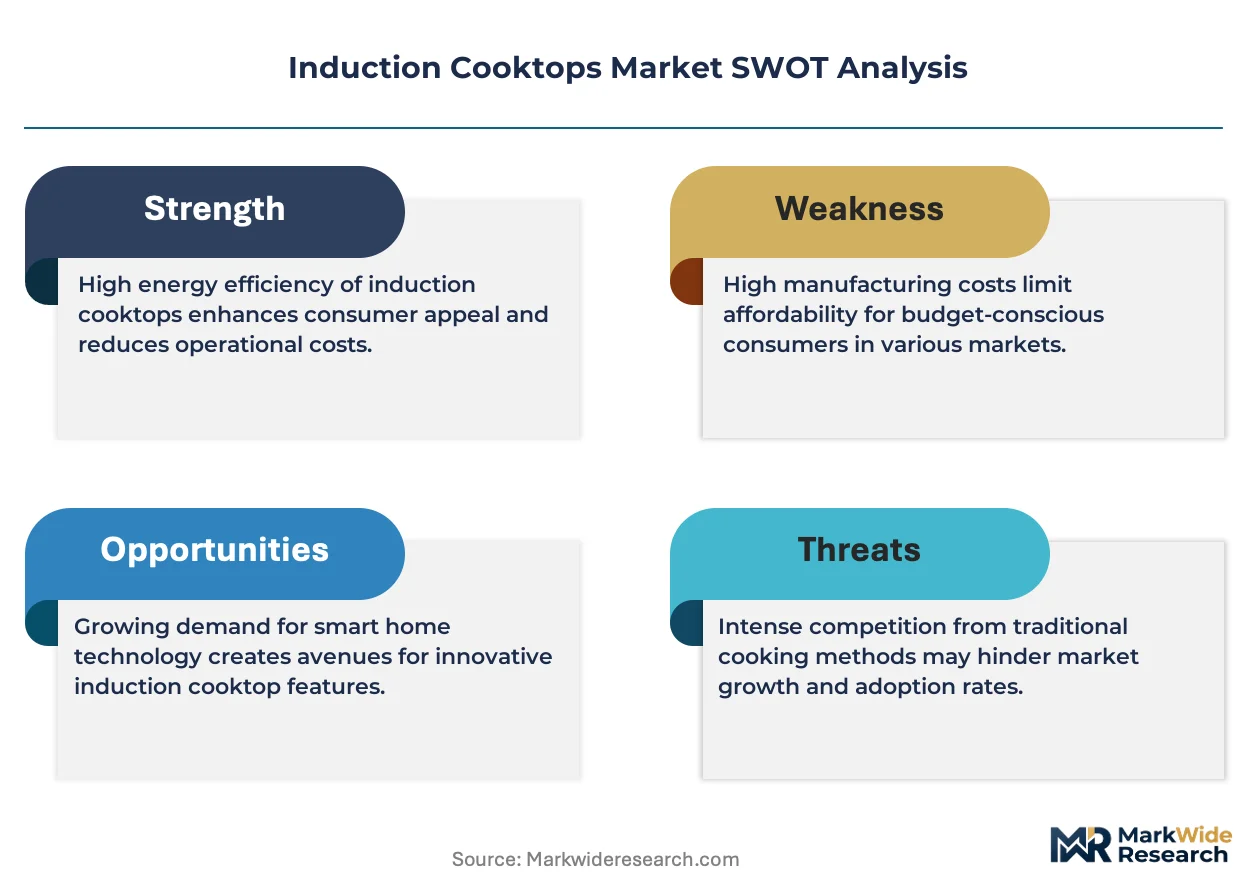
- Higher Initial Cost:The upfront purchase price for induction cooktops remains significantly higher than traditional gas or electric coil counterparts, acting as a primary barrier for budget-conscious consumers.
- Cookware Incompatibility:Induction technology requires ferromagnetic cookware, such as cast iron or magnetic stainless steel, forcing many consumers to invest in new pots and pans, adding to the total cost of adoption.
- Component Supply Concentration:The supply of critical power semiconductors like IGBTs is concentrated among a few manufacturers in Asia, creating vulnerability to geopolitical disruptions and price volatility.
Strategic Opportunities
- Light Commercial Applications:Portable induction units offer a significant growth opportunity in the light commercial sector, including catering, food trucks, and pop-up restaurants, due to their efficiency and safety.
- AI-Powered Automated Cooking:Integrating advanced sensors with AI algorithms to create automated cooking programs and guided recipes represents a key frontier for product differentiation in the premium segment.
- Emerging Market Penetration:Electrification initiatives in countries across Southeast Asia and Latin America create new market entry points for manufacturers as grid infrastructure improves and middle-class purchasing power rises.
Industry Challenges
- Navigating Global Certifications:Manufacturers face complexity and long lead times in securing compliance across multiple mandatory standards, including the EU's Ecodesign Directive, US ENERGY STAR, and China's GB standards.
- Smart Home Ecosystem Fragmentation:Ensuring seamless interoperability with a diverse and fragmented landscape of smart home platforms from different technology companies presents a persistent software integration challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Induction Cooktops Market |
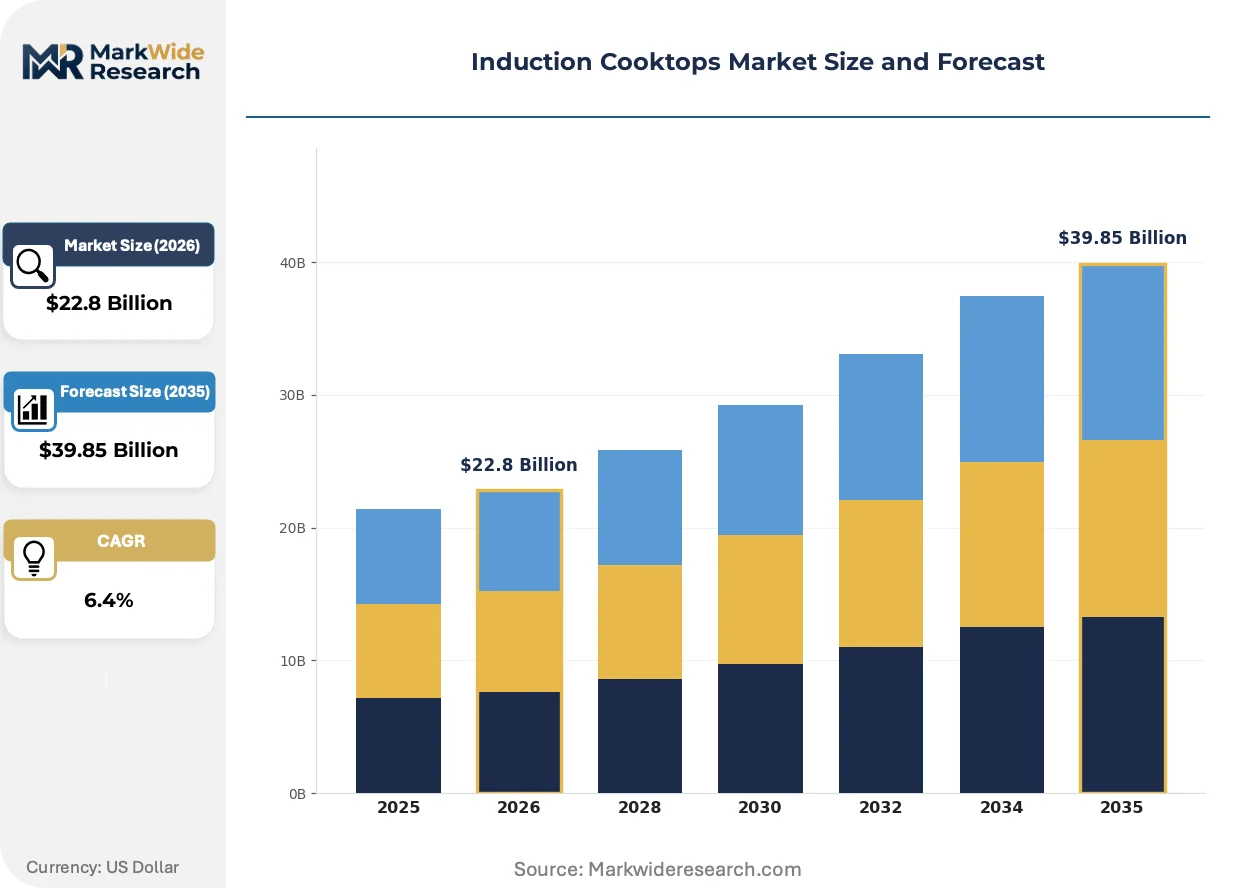
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Built-in, Portable, Commercial Technology: Induction, Convection, Radiant, Dual-Fuel End User: Residential, Restaurants, Catering, Institutions Distribution Channel: Online, Retail Stores, Direct Sales, Wholesalers |
| Companies Covered | Wolf, GE, Fisher & Paykel, Whirlpool, Samsung, LG, Miele, Bosch, SKS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Induction Cooktops Market Strategic Shifts & Innovations
Product evolution is shifting the appliance from a standalone cooking tool to an intelligent, connected kitchen hub. This transformation is defined by the integration of advanced sensor technology and software-driven features that enhance precision, safety, and user interaction.
Advanced sensor arrays provide real-time temperature feedback directly from the cookware. The premium residential segment is rapidly adopting this capability for precise control over delicate cooking processes like simmering and sous-vide. Consequently, user interface design is migrating from simple digital buttons to dynamic, AI-assisted systems that automate temperature adjustments and provide guided cooking experiences.
China's mandatory GB standards for energy consumption and electrical safety are becoming increasingly stringent. These regulations create a high barrier to entry, effectively requiring specific product designs for the Chinese market. As a result, non-compliant models are excluded, forcing global manufacturers to invest heavily in localized R&D to gain or maintain market access.
Consumer purchasing behavior is moving away from reliance on mass-market appliance stores. A significant portion of sales, especially for built-in models, now flows through specialized kitchen design showrooms and direct-to-consumer online channels that offer expert consultation. This channel shift is most pronounced in North American and European metropolitan areas tied to renovation cycles.
Induction Cooktops Market Segmentation
Understanding the distinct segments within the induction cooktops market is crucial for manufacturers to tailor product development, marketing strategies, and distribution channels. Each segment addresses specific consumer needs and operational requirements, influencing competitive positioning and growth opportunities.
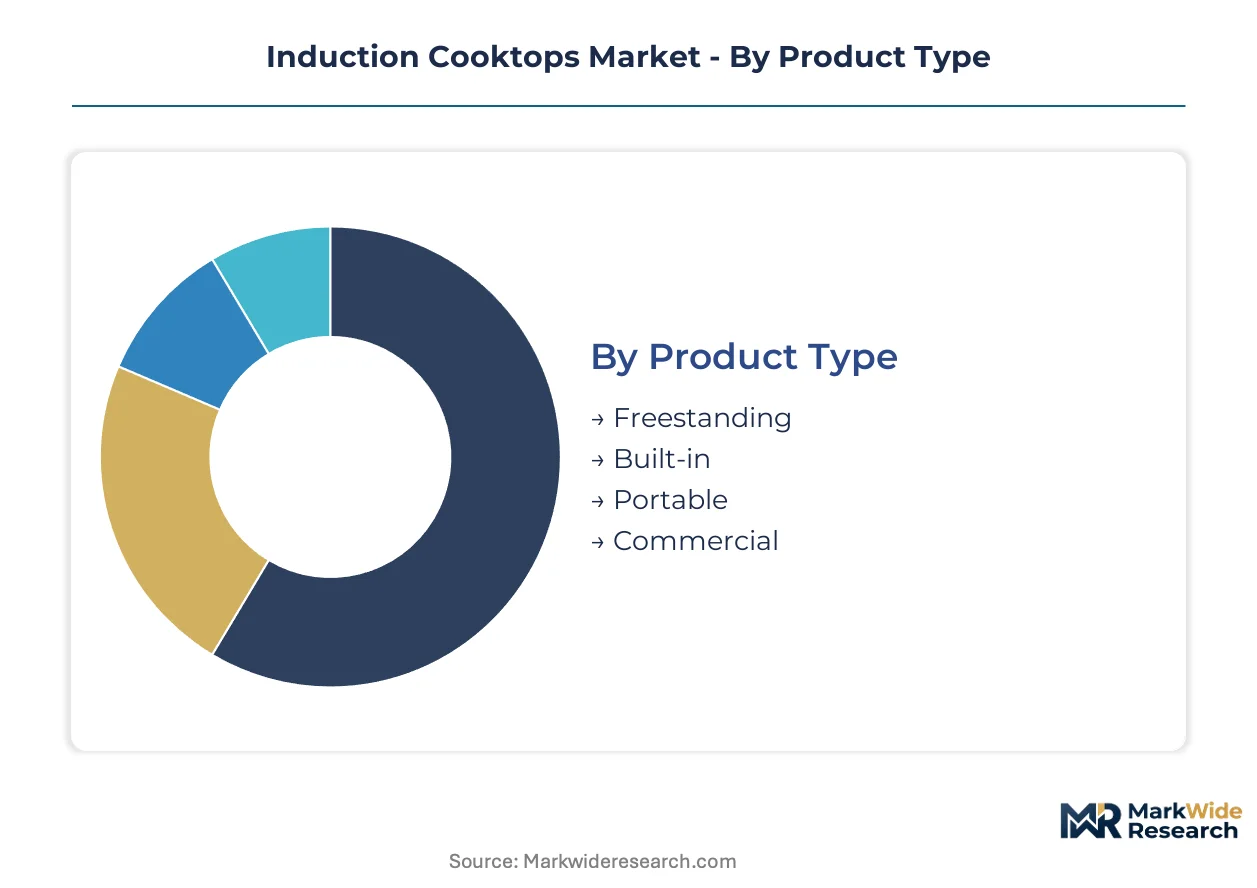
Product Type:
The use-case spectrum for induction cooktops ranges from permanent kitchen installations to flexible, mobile cooking solutions.
- Built-in:These units integrate seamlessly into countertops, offering a sleek aesthetic and aligning with modern kitchen design trends and new construction specifications. Demand concentrates in metropolitan areas across North America and Europe, driven by renovation cycles and premium home aesthetics.
- Portable:Compact and versatile units designed for temporary use or supplementary cooking, requiring minimal installation. This product type represents the fastest-growing trajectory, appealing to consumers in China's rapidly urbanizing regions and light commercial settings like catering due to their flexibility.
- Freestanding:Self-contained cooktop and oven combinations that offer a traditional appliance replacement option for existing kitchens.
- Commercial:Robust, high-performance induction cooktops engineered for heavy-duty use in professional kitchens and food service operations.
The dominant share belongs to Built-in models, while Portable units are closing the gap fastest.
Technology:
Application-specific integration of heating mechanisms defines the technology segment, catering to diverse cooking preferences and energy considerations.
- Induction:This core technology uses electromagnetic fields to directly heat ferromagnetic cookware, offering rapid, precise temperature control and high energy efficiency. This technology is central to residential electrification mandates in the European Union.
- Dual-Fuel:Cooktops that combine induction hobs with traditional gas burners, providing users with the flexibility of both cooking methods. Consumers in the United States often choose this option for versatility in gourmet cooking.
- Convection:While primarily an oven technology, some integrated cooktop systems incorporate convection heating elements for baking and roasting.
- Radiant:These cooktops utilize electric heating elements beneath a glass-ceramic surface, offering a more traditional electric cooking experience without electromagnetic heating.
The market predominantly features Induction technology, with Dual-Fuel options expanding most quickly.
End User:
Customer type differentiation dictates specific product features, performance requirements, and purchasing considerations for induction cooktops.
- Residential:Individual households seeking energy-efficient, modern cooking appliances for daily use, often integrating with smart home ecosystems. This segment accounts for the largest volume, driven by urbanization in China and electrification policies.
- Restaurants:Professional kitchens requiring durable, high-performance cooktops capable of continuous, heavy-duty operation and precise temperature control. Demand for these units is strong in established culinary centers globally.
- Catering:Mobile food service providers and event caterers utilizing portable and efficient cooking solutions for off-site food preparation.
- Institutions:Educational facilities, hospitals, and corporate cafeterias requiring robust and easy-to-clean cooking equipment for large-scale meal preparation.
The largest volume is attributed to Residential users, while Restaurants are gaining share rapidly.
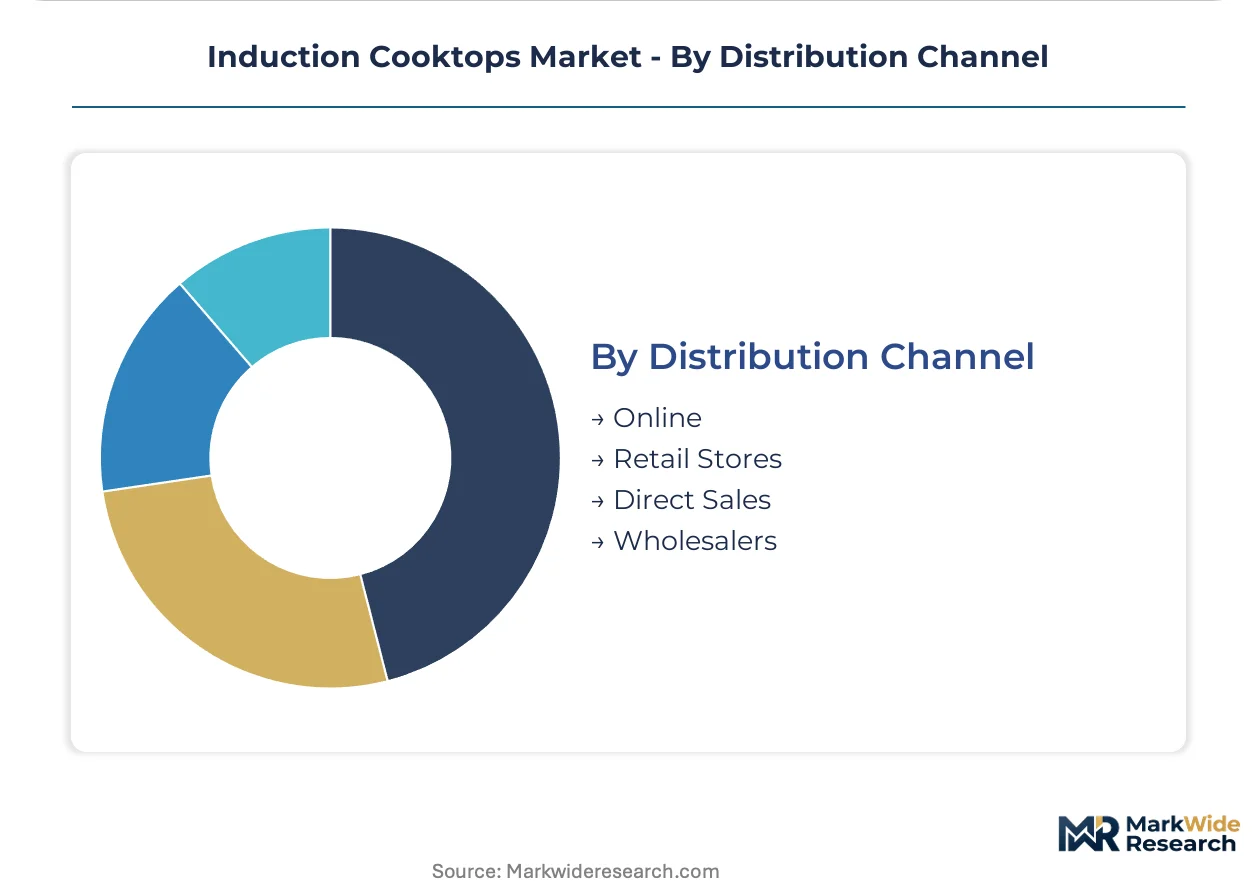
Distribution Channel:
Procurement patterns for induction cooktops are evolving, with traditional retail models being supplemented by specialized and direct-to-consumer options.
- Online:E-commerce platforms and manufacturer websites offer direct-to-consumer sales, providing convenience and a wide selection, particularly for portable models. This channel is experiencing significant growth in North America and Europe.
- Retail Stores:Traditional appliance showrooms and department stores provide physical product inspection and in-person sales assistance for consumers. These stores remain important for premium built-in models.
- Direct Sales:Manufacturers selling directly to large builders, developers, or commercial clients for new construction projects and bulk orders.
- Wholesalers:Intermediaries distributing cooktops to smaller retailers, contractors, and commercial purchasers, facilitating broader market reach.
Sales largely flow through Retail Stores, with Online channels showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for induction cooktops shows asymmetry between China and European markets. China's volume-driven demand contrasts with Europe's premium segment focus. This disparity influences global manufacturing and distribution strategies across key regions.
China
Rapid urbanization and smart home integration drive demand for modern induction cooktops in China. Compliance with GB standards for electrical safety and energy consumption is mandatory for market access. Metropolitan areas like Shanghai and Beijing concentrate demand for advanced, energy-efficient kitchen appliances in new high-rise residential construction.
Germany
Germany's market for induction cooktops benefits from electrification mandates and strong kitchen renovation trends. The EU Ecodesign Directive sets stringent performance benchmarks for these appliances. Cities such as Berlin and Munich show high demand for premium built-in models, aligning with sophisticated architectural and design preferences.
United States
The United States sees demand for induction cooktops from consumers seeking replacement appliances and gourmet cooking capabilities. ENERGY STAR certification programs encourage the adoption of energy-efficient models. High-end kitchen installations in urban centers like New York City and Los Angeles prioritize advanced features and sleek aesthetics.
India
India's market for induction cooktops is expanding due to emerging market penetration and a rising middle-class population. BIS standards ensure product quality and safety for consumers. Bangalore's tech-driven appliance market and Mumbai's urban development areas demonstrate increasing interest in modern kitchen solutions.
France
France experiences a strong push for induction cooktops, propelled by government electrification mandates and the EU Green Deal. These policies accelerate the displacement of natural gas appliances. Paris and Lyon exhibit significant demand for premium built-in induction units, driven by luxury kitchen design showrooms and renovation cycles.
Induction Cooktops Market Key Industry Players
Premium built-in specialists and mass-market appliance manufacturers split the market for induction cooktops. This structure allows for both high-end product differentiation and broad consumer accessibility. Strategic partnerships for smart home ecosystems and capacity expansion in key manufacturing hubs represent dominant competitive moves.
Within the premium built-in tier, Miele and Bosch exemplify engineering focus and brand reputation in the high-end residential segment. Samsung, a major mass-market player, occupies a position emphasizing smart features and connectivity across its broader appliance ecosystem. These companies anchor different segments through distinct product and market approaches.
| Leading Market Players |
|---|
| Wolf |
| GE |
| Fisher & Paykel |
| Whirlpool |
| Samsung |
| LG |
| Miele |
| Bosch |
| SKS |
| Others |
Cost & Logistics Intelligence
Concentration of critical power semiconductors like IGBTs in Asia directly impacts the pricing power and margin pools for premium induction cooktop manufacturers. This supply-side dynamic influences overall cost structures across the residential and commercial segments.
Pricing Analysis
Configured-to-order pricing for premium built-in induction cooktops differentiates from standard unit pricing for mass-market models. Pricing stratifies across premium, standard, and economy tiers, driven by brand reputation, advanced sensor technology, and after-sales service bundles. Pricing pressure stems from the high initial cost barrier for induction technology compared to gas or electric coil alternatives. Residential consumers seeking portable units exhibit the highest price sensitivity, while premium built-in buyers prioritize feature sets over initial cost.
Supply Chain Analysis
Contract manufacturing capacity for induction cooktops primarily centers in China, leveraging established electronics manufacturing infrastructure. The supply chain relies on critical power semiconductors like IGBTs, largely sourced from specialized manufacturers across Asia. Single-source vulnerability for these core components creates a structural risk, susceptible to geopolitical disruptions and price volatility. Distribution runs through a fragmented model, combining traditional retail stores, direct-to-consumer online platforms, and specialized kitchen design showrooms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The induction cooktops market presents a fragmentation opportunity, driven by the shift towards smart home integration and diverse end-user needs. This creates distinct niches for specialized product offerings and tailored market approaches.
For Market Incumbents:
Insulate premium market share by deepening investment in advanced sensor technology and AI-powered cooking features. Secure long-term supply agreements for critical components like IGBTs to mitigate single-source vulnerability. Leverage brand reputation and channel control through specialized kitchen design showrooms to counter pricing pressure from mass-market entrants. Continuous R&D in user interface design will address smart home ecosystem fragmentation.
For New Entrants and Emerging Players:
Establish a beachhead in the portable induction cooktop segment, which represents the fastest-growing product type. Target light commercial applications such as catering and food trucks with robust, efficient units. Penetrate emerging markets in Southeast Asia by offering cost-effective solutions and leveraging online direct-to-consumer channels. Focus on minimizing initial cost to overcome the primary barrier for budget-conscious consumers.
For Investors and Strategic Acquirers:
Secondary-cycle assets sit with specialized component manufacturers and software providers focusing on smart kitchen integration. Long-term viability for the induction cooktops market remains strong, driven by global electrification mandates over the next decade. Target acquisition profiles include niche players with strong intellectual property in advanced sensor technology or established distribution networks in rapidly urbanizing regions. Regulatory policy shifts regarding gas appliance phase-outs serve as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Reduces manufacturing costs for mass-market induction cooktops. |
| IoT Platform Integration | Enhances smart home ecosystem compatibility for Samsung and LG. |
| Advanced Sensor R&D | Improves precision cooking and safety features for premium brands like Miele. |
| Certification Compliance Acceleration | Ensures market access and competitive advantage in China and Europe. |
| Direct-to-Consumer Channel Development | Captures sales from renovation cycles in North American metropolitan areas. |
Research Approach
Findings reconcile primary fieldwork against secondary review of government energy efficiency reports, appliance industry trade publications, smart home technology journals, and national statistical office data. Primary interviews engaged appliance engineers, kitchen designers, retail channel managers, and urban planning officials. This approach ensured bottom-up market insights were validated against top-down industry trends and regulatory frameworks.
Forecast inputs considered historical market performance, projected electrification mandates, and consumer adoption rates across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, end-user, distribution channel, and regional electrification policy. Compound Annual Growth Rates were derived from an assessment of these inputs, alongside residential construction starts and smart home penetration rates.
Macroeconomic conditions sit as an overlay; deviation in global housing starts or energy policy would shift the trajectory of induction cooktop adoption. Forecasts reflect assumptions regarding regulatory stability and technological progression. Quarterly review of component pricing and electrification policy updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
United States Multi-Functional Oven Market
Appliances
Mini Refrigerator Market
Appliances
French Door Refrigerator Market
Appliances
Window Air Conditioners Market
Appliances
Mobile Refrigerators Market
Appliances
UAE Gas Hobs Market
Appliances
Qatar Microwave Ovens Market
Appliances
US Portable Washing Machines Market
Appliances
Egypt Microwave Ovens Market
Appliances
Bathroom Heaters Market
Appliances
Europe Household Electric Grills Market
Appliances
North America Tumble Dryers Market
Appliances
Germany Compact Dishwasher Market
Appliances
Bahrain Microwave Ovens Market
Appliances
Bahrain Dishwashers Market
Appliances
Bhutan and Nepal White Goods Market