
 Europe Induction Hobs Market | 2026-2036
Europe Induction Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Induction Hobs Market Foresight
Italy is fragmenting as a production base for induction hobs, with new assembly lines near Milan and Bologna serving both domestic demand and re-export channels. Bosch leverages its captive inverter supply chain to dominate the premium built-in segment across German-speaking markets. Electrolux sustains cost competitiveness through standardized coil platforms shared across its AEG and Zanussi brand portfolios. SMEG differentiates through design-forward enamel finishes that command shelf space in Italian specialty appliance stores.
Induction hobs are electric cooking surfaces that generate heat through electromagnetic coils beneath a ceramic glass surface, converting ferromagnetic cookware directly into the heating element via eddy currents at frequencies between 20-50 kHz. The technology eliminates open flames, reduces ambient kitchen temperatures, and delivers thermal efficiencies exceeding conventional radiant electric or gas systems. Built-in hobs capture the largest margin pool as kitchen renovation cycles lengthen and consumers prioritize seamless countertop integration. Zone Induction technology leads growth among commercial end users, where flexible cooking surface configurations accommodate variable pan sizes without dedicated coil alignment. Single Coil systems occupy the economy tier, primarily distributed through wholesale channels targeting rental property refurbishment across Southern Europe.
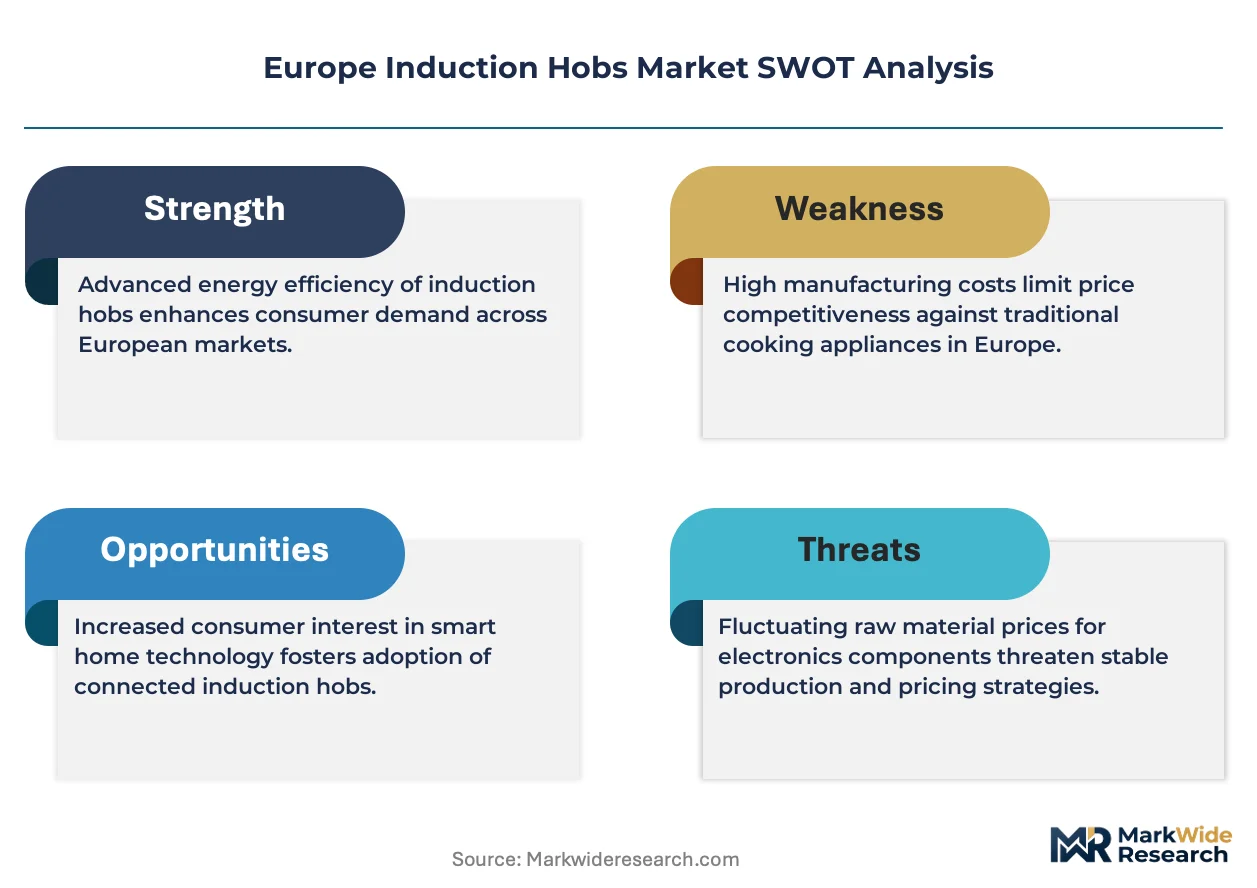
The EU Ecodesign Directive and F-Gas Regulation shape product efficiency benchmarks and refrigerant-linked supply chain compliance for manufacturers operating within the European Economic Area. CE marking requirements enforced by national market surveillance authorities in Germany, France, and Italy determine access conditions for imported coil assemblies and control modules. Stakeholders must monitor pending revisions to the EU Energy Labeling framework, which will likely recalibrate efficiency class thresholds and force component redesign cycles before the next regulatory compliance deadline.
Market Dynamics
The EU Green Deal's building energy codes are compressing replacement cycles for residential cooktops, forcing gas-to-induction conversions across German and French renovation markets while tightening coil efficiency standards for manufacturers.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency thresholds for domestic cooking appliances are eliminating lower-tier radiant electric models from German and French retail channels, redirecting volume toward induction platforms.
- Zone Induction technology:Flexible coil configurations that accommodate variable pan sizes without alignment constraints are capturing specification preference among Italian kitchen renovation contractors seeking faster boil times.
- Residential replacement demand:Building retrofit mandates in Paris and Berlin metropolitan zones are accelerating gas cooktop decommissioning rates among owner-occupied housing stock.
Market Restraints
- Ferrite magnet supply concentration:European coil manufacturers depend on Chinese-processed ferrite cores for inverter assemblies, exposing margin stability to raw material export licensing volatility.
- Ceramic glass substrate costs:Schott AG and EuroKera hold captive positions in high-tempered cooktop glass supply, limiting downstream pricing flexibility for mid-tier assembly operations.
- Electromagnetic compatibility testing:CE marking requirements for electromagnetic interference under RED 2014/53/EU extend certification timelines for new coil control module designs by four to six months.
Strategic Opportunities
- Spanish rental refurbishment channel:Municipal energy efficiency ordinances in Barcelona and Madrid are creating specification pull for economy-tier Single Coil systems through wholesale distributor networks.
- Connected cooking convergence:Integration of induction hobs with IoT-enabled ventilation systems and recipe-guided temperature protocols is opening premium retrofit opportunities in Dutch smart home installations.
- F-Gas Regulation compliance services:Refrigerant-linked supply chain audit requirements are enabling aftermarket revenue streams for coil assembly verification and documentation management.
Industry Challenges
- Inverter firmware specialization:Scarce embedded systems engineering talent in Northern Italy is constraining R&D throughput for Zone Induction control algorithm development.
- Legacy electrical infrastructure:Pre-1990s residential wiring standards in Southern European apartment stock limit power draw capacity for high-wattage induction installations without panel upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Induction Hobs Market |
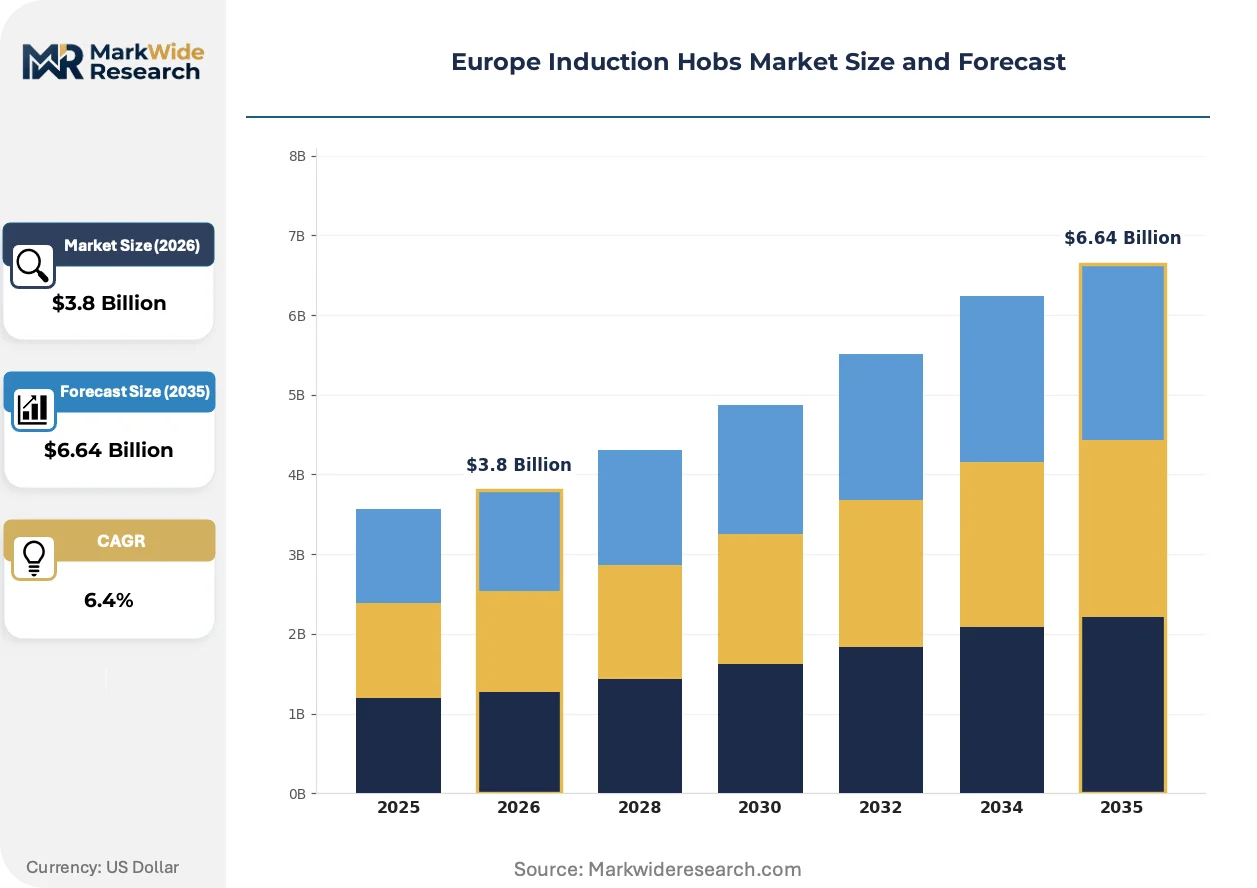
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in Hobs, Freestanding Hobs, Portable Hobs, Integrated Hobs Technology: Single Coil, Multi Coil, Zone Induction, Hybrid Induction End User: Households, Commercial Kitchens, Restaurants, Catering Services Distribution Channel: Online Retail, Home Improvement Stores, Specialty Appliance Stores, Wholesale Distributors |
| Companies Covered | Bosch, Electrolux, Siemens, Miele, Whirlpool, Haier, SMEG, AEG, Philips, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Induction Hobs Market Shifts & Advancements
Induction hob architecture is pivoting toward modular coil platforms and embedded connectivity, compressing development cycles while fragmenting competitive advantage between semiconductor control specialists and glass-ceramic substrate suppliers.
Power modulation technology is migrating from fixed-frequency inverters toward resonant switching architectures that adjust coil excitation in real time based on ferromagnetic load detection. Premium German kitchen studios are specifying these systems for precision sous-vide applications. The shift is compressing differentiation timelines for coil control firmware as a competitive moat.
Pending revisions to the EU Energy Labeling framework will recalibrate efficiency class thresholds for domestic cooking appliances, forcing coil redesign cycles before the next compliance deadline. Manufacturers with captive testing facilities in France and Germany are accelerating pre-certification validation to secure shelf positioning. The regulatory pressure is concentrating procurement authority among suppliers with established notified body relationships.
Builder-merchant procurement patterns are fragmenting as large French and German construction groups consolidate appliance specification authority at the holding-company level, bypassing traditional regional distributor relationships. Direct vendor accreditation programs are displacing wholesale channel intermediaries for mid-rise residential developments. The consolidation is most visible in Paris and Frankfurt metropolitan new-build segments.
Europe Induction Hobs Market Segmentation
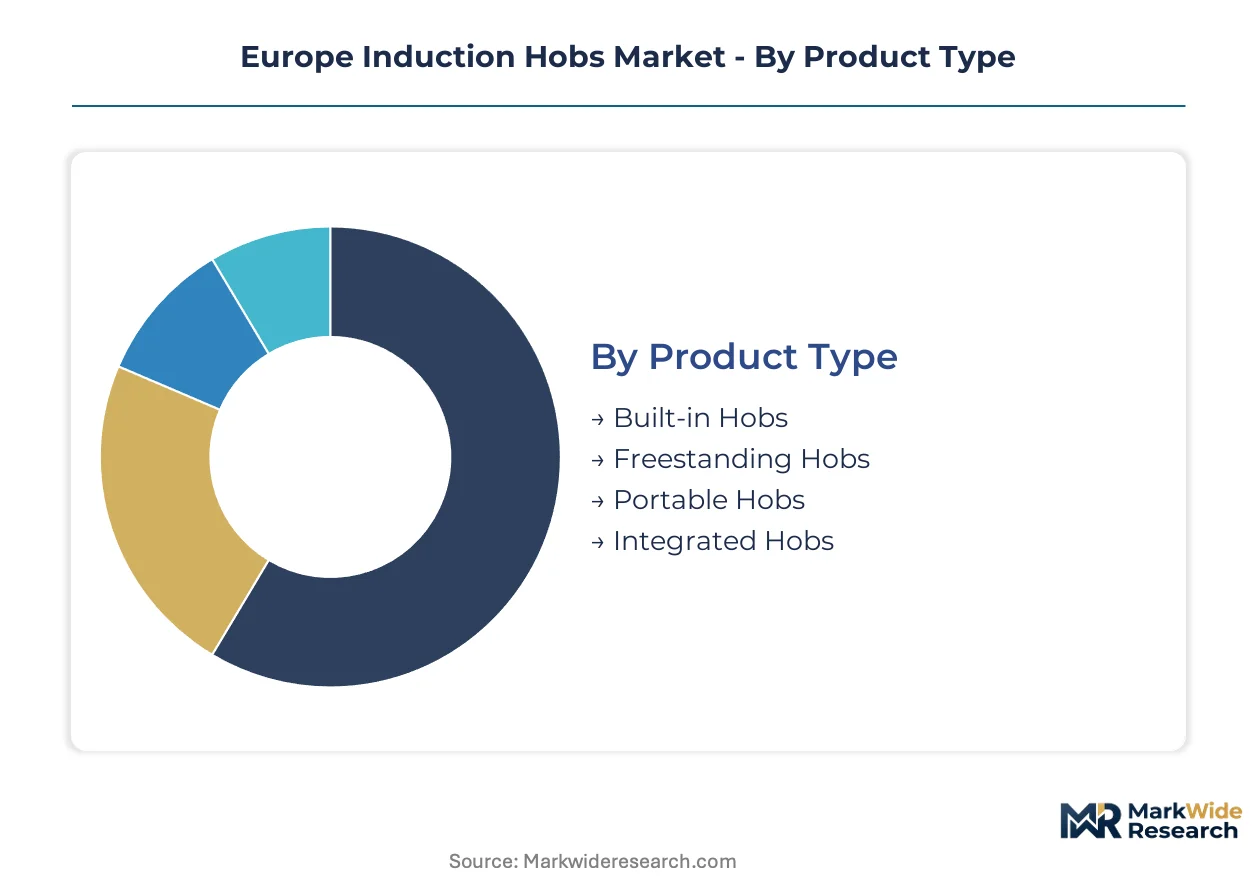
Induction hob segmentation in Europe reflects divergent service intensity requirements across installation types and distribution channels. After-sales support complexity varies sharply between built-in renovations and portable replacements, shaping margin structures and channel economics for manufacturers.
Product Type:
After-sales-service intensity escalates with installation permanence, creating tiered support obligations that separate premium built-in providers from economy portable suppliers.
- Built-in Hobs:Permanent countertop integration requires certified electrical installation and dedicated warranty support networks. German kitchen studios and French renovation contractors specify these units for owner-occupied housing retrofits under tightened EU Green Deal energy codes.
- Freestanding Hobs:Modular units with independent cabinetry appeal to rental property managers seeking appliance flexibility without structural modification. Spanish and Italian landlords favor this format for short-lease furnished apartments.
- Portable Hobs:Single-unit countertop appliances with plug-and-play operation target temporary cooking needs and outdoor applications. Limited service requirements concentrate distribution through online retail and discount channels.
- Integrated Hobs:Downdraft-ventilation combined systems eliminate overhead extraction in open-plan kitchen designs. Dutch and Belgian smart home installers specify these for compact urban dwellings.
Built-in hobs hold the largest share; momentum sits with integrated ventilation combinations.
Technology:
Coil architecture determines thermal response precision and installation power requirements, segmenting procurement between renovation contractors and new-build developers.
- Single Coil:Fixed-position ferrite core assemblies deliver basic induction functionality at minimal component cost. Wholesale distributors across Southern Europe stock these for economy-tier rental refurbishments.
- Multi Coil:Multiple discrete heating zones accommodate simultaneous cookware placement with independent temperature control. Italian kitchen renovation contractors specify these for family residential projects.
- Zone Induction:Flexible surface arrays detect and energize ferromagnetic cookware anywhere across the cooking zone without alignment constraints. German premium kitchen studios favor this technology for precision sous-vide and rapid boiling applications.
- Hybrid Induction:Combined induction and radiant electric zones bridge power infrastructure limitations in older Southern European buildings. Spanish and Portuguese electrical contractors recommend these where panel upgrades are prohibitively expensive.
Zone Induction commands premium positioning; Hybrid Induction is expanding most quickly in retrofit-constrained markets.
End User:
Usage intensity and duty cycle requirements separate domestic replacement demand from commercial specification criteria.
- Households:Residential owner-occupiers and tenants drive replacement cycles linked to building energy efficiency mandates. Paris and Berlin metropolitan zones exhibit accelerated gas-to-induction conversion rates.
- Commercial Kitchens:High-throughput institutional foodservice operations demand reinforced glass-ceramic substrates and extended daily duty ratings. Hospital and corporate cafeteria procurement in France and Germany specifies Zone Induction for variable pan configurations.
- Restaurants:Independent dining establishments prioritize rapid thermal response and surface durability for à la carte service. Michelin-tier kitchens in Northern Italy source premium built-in systems through specialty appliance channels.
- Catering Services:Mobile and event-based food operators require portable or rapidly deployable induction equipment with generator compatibility. Festival and wedding caterers across the UK and Germany favor high-wattage portable units.
Households dominate volume; Commercial Kitchens deliver the steepest expansion trajectory as EU Ecodesign thresholds eliminate gas alternatives.
Distribution Channel:
Channel selection determines installation support depth and regulatory documentation access for CE marking compliance.
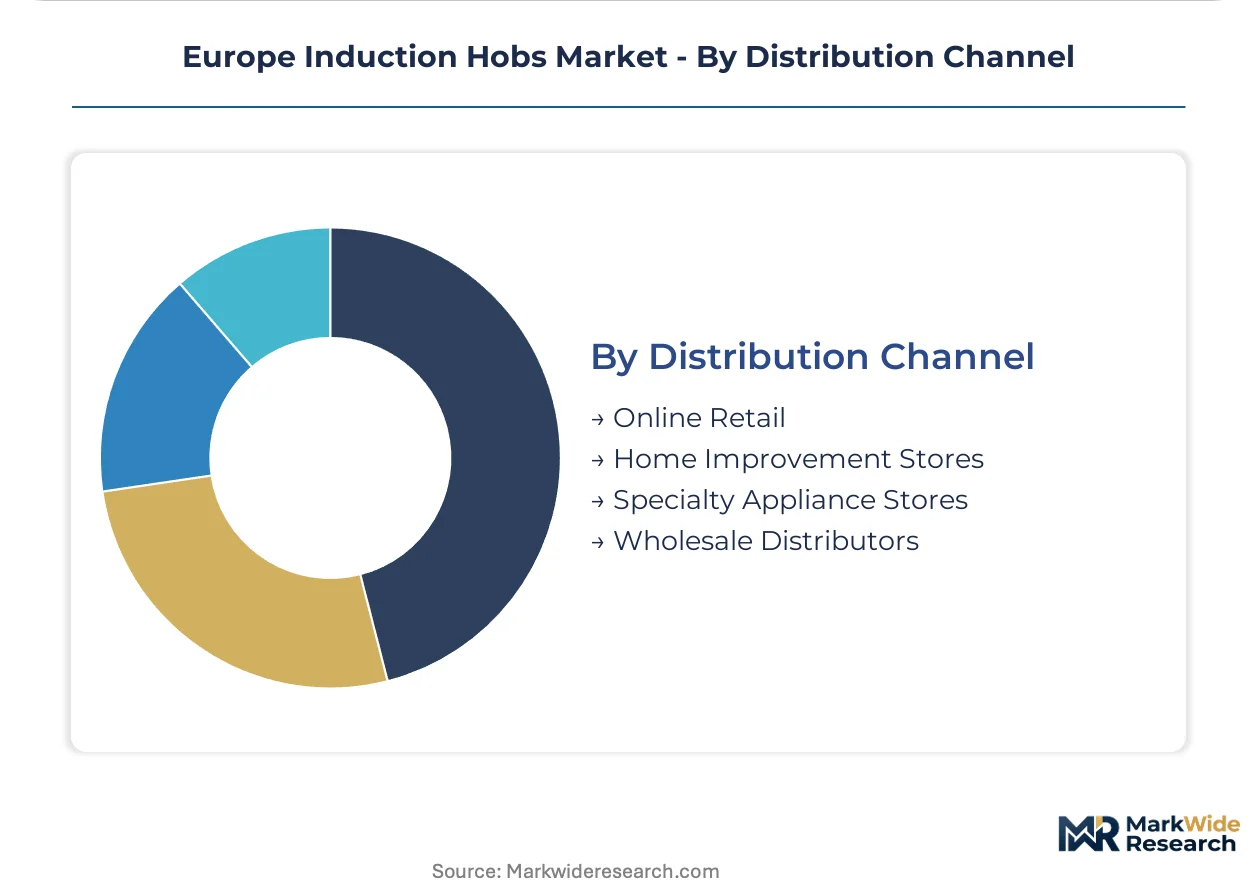
- Online Retail:Direct-to-consumer platforms with standardized product data sheets serve informed replacement purchasers. German and Dutch consumers utilize these channels for portable and economy built-in selections.
- Home Improvement Stores:Big-box retailers with in-house installation services capture renovation-project bundling. French and UK chains like Leroy Merlin and B&Q dominate mid-tier built-in volume.
- Specialty Appliance Stores:Independent dealers with certified technician networks provide pre-installation site surveys and warranty administration. Italian design-forward showrooms in Milan and Bologna concentrate premium specification authority.
- Wholesale Distributors:Builder-merchant networks supply volume contracts for multi-unit residential developments. Consolidated French and German construction groups are bypassing traditional regional distributors through direct vendor accreditation.
Home Improvement Stores capture the largest transaction volume; Specialty Appliance Stores are gaining specification influence in premium kitchen renovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European induction hob manufacturing concentrates in Northern Italy and Western Germany, where captive coil assembly and glass-ceramic processing capabilities have created contiguous supplier ecosystems. This geographic clustering shapes competitive dynamics across the continent.
Germany
Kitchen renovation contractors in Berlin and Munich metropolitan zones specify premium built-in induction systems under tightened EU Green Deal building energy codes. The KBA enforces electromagnetic compatibility standards for imported control modules. Bosch and Siemens anchor production in Baden-Württemberg and Bavaria, leveraging captive inverter supply chains.
France
Paris and Lyon owner-occupied housing stock drives accelerated gas-to-induction replacement cycles mandated by municipal retrofit ordinances. ANSM market surveillance authorities administer CE marking compliance for coil assemblies entering through French ports. Electrolux maintains specification relationships with consolidated construction groups specifying at holding-company level.
Italy
Milan and Bologna kitchen renovation contractors favor Zone Induction technology for precision temperature control in design-forward residential projects. The EU Ecodesign Directive eliminates lower-tier radiant electric models from retail channels. SMEG and specialist enamel finishers concentrate manufacturing in Emilia-Romagna, serving both domestic demand and re-export channels.
Spain
Barcelona and Madrid municipal energy efficiency ordinances create specification pull for economy-tier Single Coil systems in rental property refurbishment. Wholesale distributor networks supply volume contracts through builder-merchant channels. Spanish landlords favor freestanding formats for short-lease furnished apartments to avoid structural modifications.
Netherlands
Dutch smart home installers specify integrated downdraft-ventilation induction systems for compact urban dwellings in Amsterdam and Rotterdam. IoT-enabled ventilation convergence opens premium retrofit opportunities. Connected cooking protocols are gaining traction among residential consumers prioritizing seamless countertop integration.
Europe Induction Hobs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in coil control and glass-ceramic substrates. The European induction hob market exhibits tiered concentration, with German and Italian groups holding premium positioning through captive manufacturing while Asian-origin players compete on cost-standardization. Three archetypes dominate: vertically integrated appliance conglomerates with inverter supply chain control; design-forward specialists commanding specialty retail shelf space; and volume-oriented assemblers leveraging standardized coil platforms across brand portfolios. Competitive moves center on direct vendor accreditation programs displacing wholesale intermediaries, and pre-certification validation investments to secure positioning ahead of EU Energy Labeling revisions.
Among German-based platform integrators, Bosch and Siemens exemplify the captive supply chain archetype, while Electrolux represents portfolio-standardization competitive positioning across multiple brand tiers.
| Leading Market Players |
|---|
| Bosch |
| Electrolux |
| Siemens |
| Miele |
| Whirlpool |
| Haier |
| SMEG |
| AEG |
| Philips |
| Others |
Supply & Pricing Matrix
Chinese-processed ferrite cores anchor inverter assembly costs, concentrating margin capture with coil manufacturers in Northern Italy and Western Germany who command premium positioning through captive magnet supply relationships.
Pricing Analysis
The EU Ecodesign Directive dictates the pricing tier structure by eliminating sub-threshold radiant electric models from German and French retail channels. Three-tier pricing structure across premium, standard, and economy levels separates Zone Induction systems with resonant switching architectures from Single Coil economy units. Cost compression in the mid-tier is intensifying because wholesale distributors in Southern Europe face consolidated construction group procurement authority. Rental property refurbishment channels exhibit highest price sensitivity, while Dutch smart home installers show lowest sensitivity for integrated ventilation combinations.
Supply Chain Analysis
Ferrite magnet feedstock draws from Chinese processing facilities, with European coil assembly concentrated in Italy and Germany. Ceramic glass substrates hinge on Schott AG and EuroKera supply positions. Single-source vulnerability in high-tempered cooktop glass limits downstream pricing flexibility for mid-tier assemblers. Distribution runs through builder-merchant networks for volume contracts, while specialty appliance stores capture premium specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation service bundling and extended warranty programs represent faster-expanding revenue layers than hardware sales alone, as kitchen renovation cycles lengthen and certified electrical installation becomes mandatory across EU Green Deal compliance zones.
For Market Incumbents: Build certification moats through pre-validation investments at French and German notified body facilities ahead of EU Energy Labeling revisions. Secure direct vendor accreditation with consolidated Paris and Frankfurt construction groups to bypass wholesale intermediaries. Defensive consolidation should target coil control firmware specialists in Northern Italy where embedded systems engineering talent scarcity constrains R&D throughput. For New Entrants and Emerging Players: Spanish rental refurbishment channels offer underpenetrated white-space for economy-tier Single Coil systems under Barcelona and Madrid municipal energy efficiency ordinances. Target hybrid induction formats for Portuguese and Southern Italian retrofit markets constrained by pre-1990s electrical infrastructure. Go-to-market execution should prioritize wholesale distributor relationships with established builder-merchant networks over direct retail presence. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across Zone Induction control module development as resonant switching architectures commoditize coil excitation algorithms. Long-term viability favors platform integrators with captive inverter supply chains over pure-play assemblers. Acquisition targets should display established notified body relationships and direct vendor accreditation with consolidated construction groups. Monitor F-Gas Regulation compliance service revenue as inflection indicator for aftermarket documentation management opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Core Supply | Reduces exposure to Chinese export licensing volatility for European coil manufacturers. |
| Pre-Certification Validation Investment | Secures shelf positioning ahead of EU Energy Labeling threshold revisions at notified bodies. |
| Direct Vendor Accreditation Programs | Bypasses wholesale intermediaries for Paris and Frankfurt metropolitan new-build segments. |
| Connected Cooking Platform Integration | Captures premium retrofit opportunities in Dutch smart home installations with IoT ventilation. |
| F-Gas Compliance Service Expansion | Opens aftermarket revenue streams for coil assembly verification and documentation management. |
Research Methodology
The analysis maps built-in, freestanding, portable, and integrated ventilation hob configurations, each validated through kitchen renovation contractors, appliance procurement managers at consolidated construction groups, certified electrical installation technicians, and specialty appliance store owners. Primary fieldwork combined with secondary validation from EU Ecodesign Directive regulatory filings, CE marking surveillance authority databases, customs trade records for ferrite core imports, and glass-ceramic substrate supplier disclosures. Bottom-up volume triangulation across distribution channels and top-down value validation against construction sector appliance spend data ensured cross-verification.
Assumptions held fixed include EU Green Deal building energy code enforcement timelines and F-Gas Regulation compliance requirements, while coil efficiency trajectories and resonant switching adoption rates were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product installation type, coil architecture technology, end-user duty cycle intensity, and distribution channel service depth. CAGRs were derived from installed base replacement cycle analysis and new-build penetration curve fitting. Industry-specific inputs included kitchen renovation permit data from Paris and Berlin metropolitan zones and municipal energy efficiency ordinance implementation schedules.
Practitioners should monitor ferrite magnet export licensing volatility, EU Energy Labeling revision timing, and consolidated construction group procurement consolidation for early signals of forecast deviation. Cross-checking against Euroconstruct building renovation spend benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Built-In Large Cooking Appliance Market
Appliances
APAC White Goods Market
Appliances
United States Microwave Oven Market
Appliances
Smart Connected Washing Machine Market
Appliances
India Washing Machine Market
Appliances
Fully Automatic Dishwasher Market
Appliances
Mexico Washing Machine Market
Appliances
Clothing Iron Market
Appliances
Electric Kettle Market
Appliances
Laundry Appliances Market
Appliances
Domestic Food Preparation Appliances Market
Appliances
Portable Dishwasher Market
Appliances
Global Electric Water Heaters Market
Appliances
Mexico Laundry Appliances Market
Appliances
South Africa Laundry Appliances Market
Appliances
Dishwasher Market