
 Electric Brooms Market | 2026-2036
Electric Brooms Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Brooms Market Analysis
China is rewriting capacity dynamics for electric broom manufacturing as Guangdong and Zhejiang provinces expand motor and battery assembly lines. Karcher leverages its German engineering heritage to sustain premium positioning across European specialty retail channels. Bissell anchors North American distribution through deep penetration of big-box home improvement networks. Dyson competes on brushless motor R&D intensity, while Sinbo dominates value-tier exports from its Ningbo production base.
An electric broom is a motorized, handheld or stick-form cleaning device combining rotary brush agitation with suction airflow, typically operating on AC mains power or rechargeable DC battery packs between 18V and 40V, designed for rapid debris collection on hard floors and low-pile surfaces. Cordless configurations now lead volume shipments as lithium-ion cell costs compress and runtime extends past thirty minutes per charge. HEPA filtration segments command margin premiums in residential and educational end-use settings where allergen containment shapes procurement criteria. Brushless motor technology is displacing brushed commutator designs across mid-tier and premium price bands due to efficiency gains and reduced acoustic output.
China's GB standards for appliance safety and electromagnetic compatibility constrain export-ready product designs, while the EU F-Gas Regulation and REACH compliance requirements shape material selection for seals and housings sold into European markets. The US EPA Energy Star program and FCC Part 15 emissions rules further segment certification burdens by destination geography. Stakeholders must monitor battery chemistry substitution timelines and recycling mandate trajectories as regulatory pressure on circularity intensifies across major destination markets.
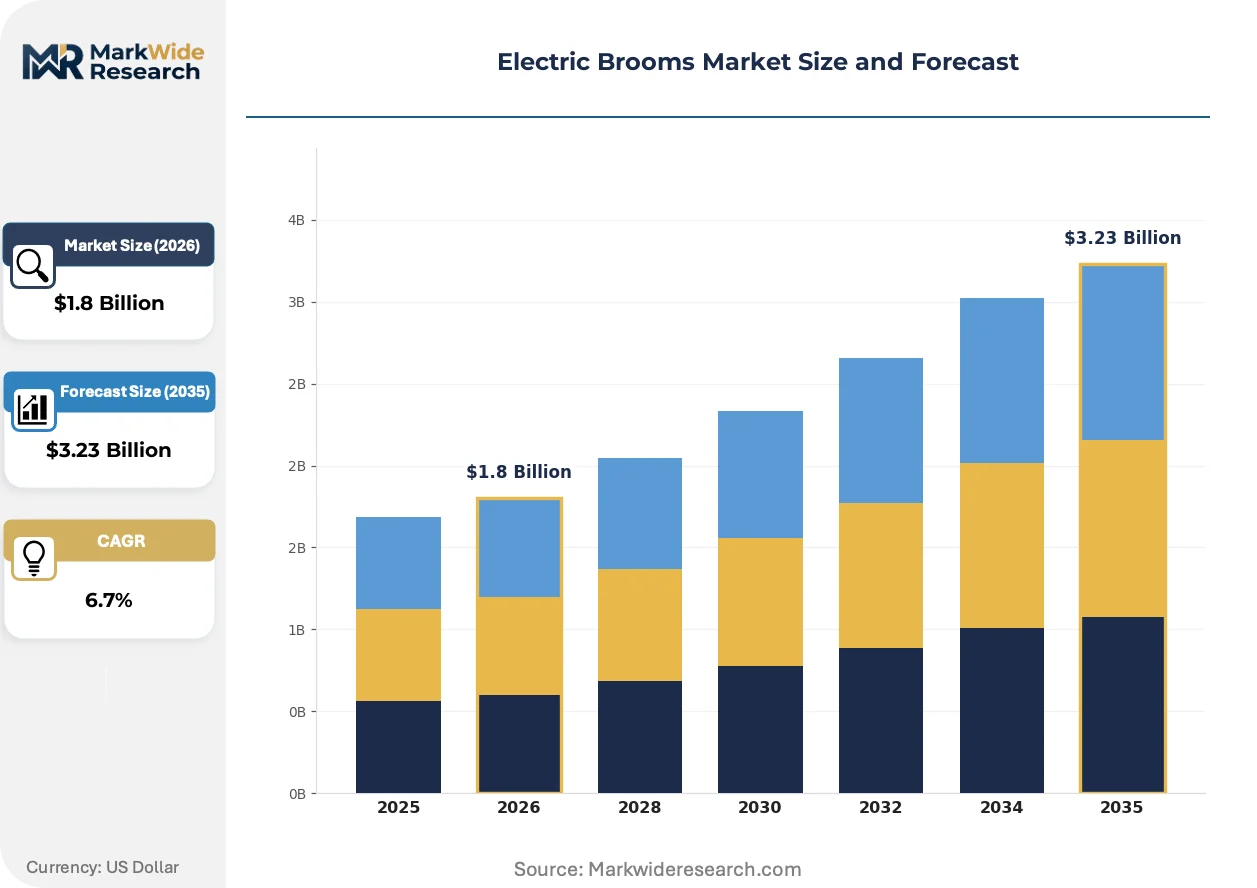
Market Dynamics
Lithium-ion energy density improvements above 250 Wh/kg are compressing battery pack footprints while extending runtime thresholds, enabling cordless configurations to capture volume leadership from corded alternatives across residential and light commercial segments.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon propellants in aerosol cleaning products is redirecting procurement budgets toward electric mechanical alternatives for hard-floor maintenance in German and French educational facilities.
- Brushless motor topology:Permanent magnet synchronous designs are eliminating carbon brush maintenance cycles and reducing acoustic output below 65 dB, satisfying noise ordinances in Japanese multi-unit residential complexes.
- Guangdong manufacturing clusters:Vertical integration of motor winding, PCB assembly, and lithium-ion pack production within 150-kilometer radii is compressing landed costs for export-bound cordless units.
Market Restraints
- Cobalt and lithium carbonate volatility:Cathode material spot price swings above 40 percent annually are compressing gross margins for battery pack assemblers unable to secure long-term offtake agreements.
- Ningbo-Shenzhen supply corridor concentration:Over 70 percent of global motor and battery assembly capacity resides within two Chinese provinces, exposing procurement timelines to regional logistics disruptions and customs processing variability.
- Runtime ceiling for 18V-22V platforms:Physics-limited energy density in cylindrical 18650 and 21700 cell formats constrains cordless runtime below 35 minutes for high-suction brush motor configurations.
Strategic Opportunities
- India BIS certification pathway:Mandatory ISI marking for household electrical appliances creates first-mover advantage for brands establishing local testing partnerships ahead of full enforcement timelines.
- HEPA filtration convergence with asthma management:Allergen containment specifications exceeding 99.97 percent particle capture at 0.3 microns are penetrating pediatric clinic and early childhood education procurement criteria.
- Direct-to-installer channel development:Bypassing traditional retail markup structures through contractor loyalty programs and fleet pricing for multi-unit property management accounts.
Industry Challenges
- Multi-jurisdiction certification sequencing:Simultaneous UL, CE, and GB standard compliance requires 14-18 month pre-market timelines, delaying revenue recognition for platform refreshes.
- Brushless motor controller firmware IP:Field-oriented control algorithms and sensorless commutation methods are subject to patent thickets held by industrial automation incumbents, complicating in-house development or licensing negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Brooms Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded, Cordless, Multi-Surface, Robotic Technology: Brushless Motor, Vacuum Technology, Smart Sensors, HEPA Filtration End User: Residential, Commercial, Industrial, Educational Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Swivel Sweeper, Sinbo, Karcher, Eureka, Bissell, Kitfort, Twister Sweeper, Dyson, Vileda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Brooms Market Emerging Trajectories
Solid-state battery prototyping and wide-bandgap semiconductor integration are converging to redefine power-to-weight ratios, while regulatory pressure on circularity is forcing redesign of pack architectures for end-of-life disassembly.
Silicon-anode lithium-ion cells with pre-lithiated graphite substrates are rendering obsolete nickel-cobalt-manganese cathode systems in premium cordless platforms. German and Japanese appliance engineers are validating 400-cycle retention rates above 90 percent. The technology is rendering obsolete the 20-minute runtime ceiling that previously constrained cordless adoption in commercial cleaning contracts.
China's GB 4706.7-2014 safety standard revision incorporating battery thermal runaway containment protocols is mandating redundant cell-level fusing and venting chamber designs. Domestic manufacturers in Guangdong and Jiangsu provinces are absorbing 8-12 percent BOM cost increases for compliant pack architectures. Export-oriented suppliers targeting European markets are dual-certifying against both GB and IEC 60335-2-2 to maintain single-SKU inventory efficiency.
Facility managers in US healthcare and education verticals are consolidating vendor relationships through multi-site service contracts bundling equipment, consumables, and preventive maintenance. Traditional distributor networks with 25-30 point markups are losing share to manufacturer-direct field service organizations. The shift is most visible in California and Texas metropolitan markets where procurement autonomy has devolved to regional facility directors.
Electric Brooms Market Segmentation
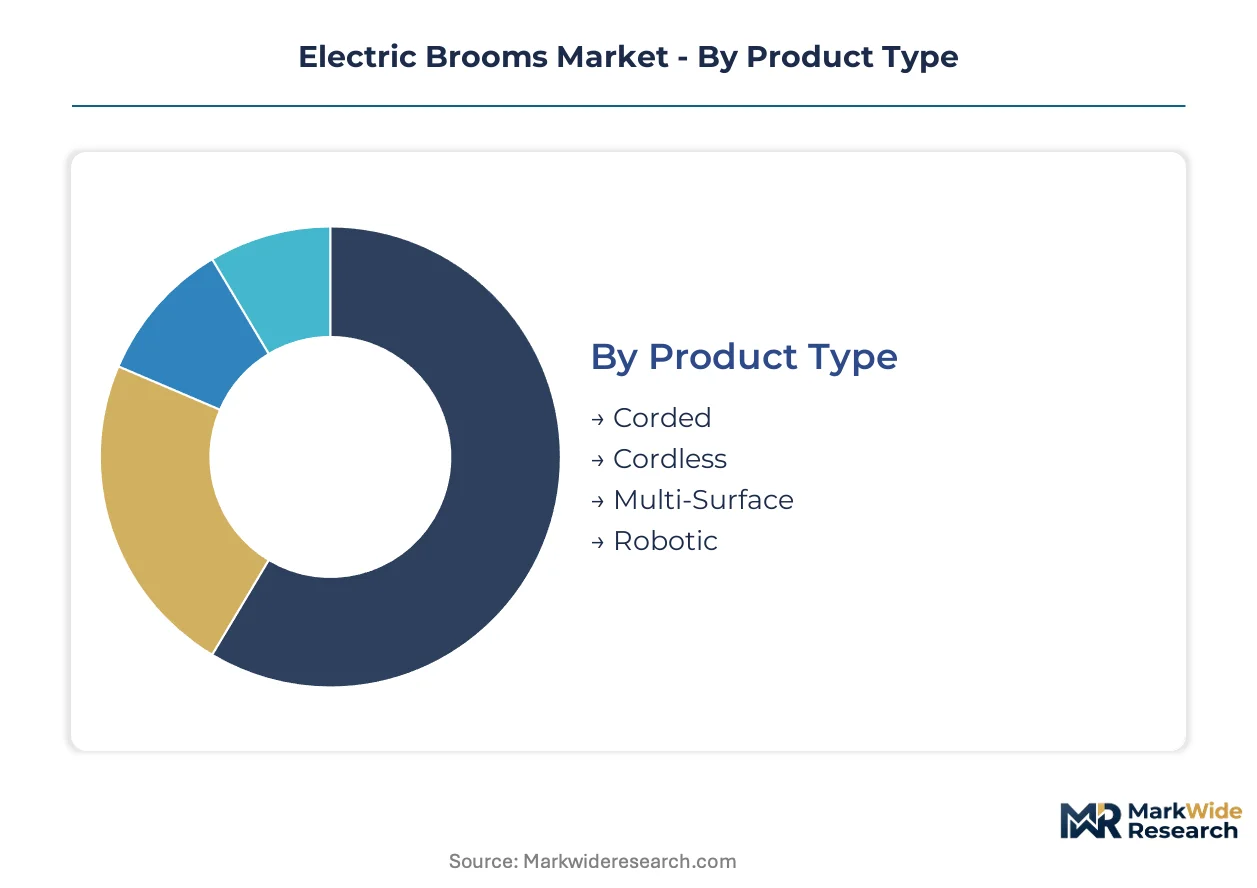
Electric broom segmentation reveals divergent replacement cycles across product architectures. Cordless platforms refresh every 4-6 years as battery degradation accelerates trade-ins, while corded units persist for 8-12 years in commercial custodial fleets.
Product Type:
Corded units turn over slowest in institutional settings; robotic systems refresh fastest as firmware and mapping capabilities obsolete hardware within 24-36 months.
- Corded:AC mains-powered designs with unlimited runtime dominate school districts and hospital maintenance departments where continuous duty cycles outweigh mobility constraints. Procurement concentrates in German municipal facilities prioritizing total cost of ownership over convenience.
- Cordless:Rechargeable lithium-ion packs between 18V and 40V now lead residential volume as Guangdong battery assembly clusters compress unit costs. Japanese apartment complexes drive demand for sub-65 dB acoustic profiles mandated by building ordinances.
- Multi-Surface:Interchangeable brush rolls and suction modulation adapt to hardwood, tile, and low-pile carpet transitions.
- Robotic:Autonomous navigation with LiDAR or visual SLAM mapping targets tech-forward households in Seoul and Singapore.
Corded dominates installed base in institutional verticals. Cordless is where expansion concentrates in residential channels.
Technology:
Cost tiers separate filtration and motor architectures. HEPA systems command 40-60 percent premiums over standard filtration; brushless motors sit 25-35 percent above brushed commutator alternatives.
- Brushless Motor:Permanent magnet synchronous designs eliminate carbon brush maintenance and reduce acoustic output below 65 dB. Demand clusters in Japanese multi-unit residential complexes enforcing strict noise ordinances.
- HEPA Filtration:99.97 percent particle capture at 0.3 microns serves pediatric clinics and early childhood education facilities managing asthma triggers. EU F-Gas Regulation redirects aerosol cleaning budgets toward certified mechanical alternatives.
- Vacuum Technology:Cyclonic separation and direct-airflow configurations reduce filter maintenance frequency.
- Smart Sensors:Surface detection and load-balancing algorithms optimize power draw across debris types.
Vacuum Technology anchors volume shipments. HEPA Filtration is climbing the fastest as allergen containment penetrates healthcare procurement.
End User:
Application context dictates performance specifications and replacement urgency. Educational facilities prioritize runtime and durability; residential buyers emphasize storage footprint and aesthetic integration.
- Residential:Compact stick-form designs with wall-mounted docking stations dominate urban apartments in Shanghai and Tokyo. Lithium-ion energy density improvements above 250 Wh/kg enable 30-plus minute runtime thresholds.
- Commercial:Fleet procurement through multi-site service contracts bundles equipment, consumables, and preventive maintenance. California and Texas facility directors increasingly bypass traditional distributor markups.
- Industrial:Heavy-duty debris handling with reinforced housings and thermal overload protection.
- Educational:EU F-Gas Regulation compliance redirects German and French school district budgets toward electric mechanical floor maintenance.
Residential holds the largest unit volume. Commercial is gaining share fastest through consolidated vendor relationships.
Distribution Channel:
Supply concentration shapes channel economics. Guangdong manufacturing clusters feed online retailers and direct sales with compressed landed costs; specialty stores absorb higher markups for demonstration and service attach.
- Online Retailers:Cross-border e-commerce platforms connect Ningbo production bases directly to European and North American consumers. FCC Part 15 and CE marking compliance enable single-SKU inventory efficiency.
- Specialty Stores:German and Austrian appliance retailers sustain premium positioning through in-store demonstration and extended warranty programs.
- Supermarkets:Mass merchandisers in China and India drive value-tier volume with limited assortment and price-focused merchandising.
- Direct Sales:Manufacturer field service organizations target US healthcare and education verticals with multi-site contracts.
Online Retailers dominate unit velocity. Direct Sales is expanding most quickly in commercial fleet accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GB standards from China's SAMR constrain product designs for the dominant manufacturing geography, while FCC Part 15 and EU F-Gas Regulation shape certification burdens for export-bound units. Procurement patterns diverge sharply between German municipal facilities prioritizing total cost of ownership and Japanese apartment complexes enforcing sub-65 dB noise ordinances.
China
Guangdong and Zhejiang provinces concentrate over 70 percent of global motor and battery assembly capacity within 150-kilometer radii. GB 4706.7-2014 revisions mandate redundant cell-level fusing and venting chamber designs, absorbing 8-12 percent BOM cost increases for compliant pack architectures. Ningbo production bases feed cross-border e-commerce platforms with single-SKU inventory efficiency.
Germany
Municipal facilities prioritize total cost of ownership over convenience specifications for institutional procurement. EU F-Gas Regulation phasedown redirects aerosol cleaning budgets toward electric mechanical alternatives in educational facilities. Karcher leverages German engineering heritage through specialty retail channels with extended warranty programs.
United States
California and Texas facility directors increasingly bypass traditional distributor markups through manufacturer-direct field service organizations. EPA Energy Star program requirements segment certification timelines alongside FCC Part 15 emissions rules. Multi-site service contracts bundle equipment, consumables, and preventive maintenance for healthcare and education verticals.
Japan
METI noise ordinances in multi-unit residential complexes drive demand for brushless motor configurations below 65 dB acoustic output. Tokyo apartment dwellers prioritize compact stick-form designs with wall-mounted docking stations. Osaka-based procurement channels emphasize runtime thresholds exceeding 30 minutes per charge.
India
BIS mandatory ISI marking for household electrical appliances creates first-mover advantage for brands establishing local testing partnerships. Maharashtra and Gujarat urban households drive residential adoption of compact cleaning tools. Supermarket mass merchandisers push value-tier volume with price-focused merchandising strategies.
Electric Brooms Market Vendor Landscape
Premium engineering heritage and value-tier export specialization split the market into distinct strategic territories. The vendor base organizes around three archetypes: German-engineered premium specialists, Chinese-scale export manufacturers, and North American distribution-anchored brands. Capacity expansion and direct-to-installer channel development represent the dominant competitive moves as traditional retail markups erode.
Among German-engineered specialists, Karcher occupies a position exemplifying premium positioning through European specialty retail. Sinbo anchors the value-tier export archetype from its Ningbo production base. Dyson sits within the R&D-intensive tier, representing brushless motor topology advancement. These three companies illustrate the geographic and strategic segmentation structuring competitive dynamics.
| Leading Market Players |
|---|
| Swivel Sweeper |
| Sinbo |
| Karcher |
| Eureka |
| Bissell |
| Kitfort |
| Twister Sweeper |
| Dyson |
| Vileda |
| Others |
Supply Flow & Price Mechanics
Ningbo-Shenzhen freight corridors absorb 12-18 percent landed cost differentials between Guangdong manufacturing clusters and European distribution hubs, concentrating pricing power among exporters with captive logistics contracts while forcing value-tier assemblers into thinner margins. This corridor dynamic amplifies downstream price stratification as battery chemistry grades and motor certification tiers separate premium German-engineered units from mass-market Chinese exports.
Pricing Analysis
China-to-Germany unit price spreads exceed 3x for comparable cordless platforms, with HEPA-certified brushless motor configurations commanding premiums over standard filtration brushed alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects battery cell grade, GB/IEC dual certification status, and after-sales service bundling. Cost compression in the 18V-22V cordless tier is intensifying because lithium carbonate spot volatility transfers directly to pack assemblers without long-term offtake agreements. Residential buyers in India and Southeast Asia exhibit highest price sensitivity, while German municipal procurement prioritizes total cost of ownership over upfront unit cost.
Supply Chain Analysis
EU F-Gas Regulation and REACH compliance requirements restrict fluoropolymer seal imports for European-bound units, forcing redesign of housing materials and venting chamber architectures. Motor winding, PCB assembly, and lithium-ion pack production concentrate in Guangdong and Zhejiang provinces, with cathode active materials drawing from South Korean and Japanese chemical suppliers. Single-source vulnerability in the Ningbo-Shenzhen corridor exposes procurement timelines to regional logistics disruptions and customs processing variability. Distribution runs through cross-border e-commerce platforms and manufacturer-direct field service organizations, bypassing traditional 25-30 point distributor markups in North American healthcare and education verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric brooms market functions as a regulatory entrenchment story where multi-jurisdiction certification sequencing creates 14-18 month pre-market barriers that protect incumbents with established UL, CE, and GB compliance infrastructure.
For Market Incumbents: Build certification moats by accelerating dual-GB/IEC pack architecture development ahead of China's battery thermal runaway containment mandate enforcement. Secure long-term lithium carbonate offtake agreements to neutralize cathode material spot price swings above 40 percent annually. Expand Ningbo and Guangdong motor assembly capacity to capture value-tier export volume before BIS ISI marking requirements fully mature in India. For New Entrants and Emerging Players: Build out direct-to-installer channel capabilities targeting California and Texas facility directors with multi-site service contracts bundling equipment, consumables, and preventive maintenance. Penetrate the Indian residential segment through supermarket mass merchandiser partnerships ahead of mandatory BIS certification enforcement. Anchor go-to-market positioning on sub-65 dB brushless motor configurations for Japanese multi-unit residential complexes. For Investors and Strategic Acquirers: Component-specialist suppliers with captive brushless motor controller firmware IP represent priority acquisition targets amid patent thicket complications around field-oriented control algorithms. Long-term viability hinges on solid-state battery prototyping timelines and wide-bandgap semiconductor integration trajectories across the projection horizon. Watch silicon-anode lithium-ion cell cycle retention validation rates as the inflection signal for cordless runtime ceiling breakthroughs.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Pack Architecture Development | GB 4706.7-2014 and IEC 60335-2-2 compliance enables single-SKU inventory efficiency for export-oriented suppliers. |
| Long-Term Cathode Material Offtake Agreements | Cobalt and lithium carbonate price hedging stabilizes gross margins for battery pack assemblers exposed to spot volatility. |
| Direct-to-Installer Channel Expansion | Manufacturer field service organizations capture California and Texas healthcare procurement autonomy devolving to regional facility directors. |
| Brushless Motor Controller Firmware Licensing | Patent navigation around industrial automation incumbent IP thickets accelerates in-house development timelines for premium cordless platforms. |
| Solid-State Battery Prototyping Partnerships | German and Japanese appliance engineering collaborations validate 400-cycle retention rates above 90 percent for next-generation cordless runtime thresholds. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs export records, SAMR GB standard filings, and EU F-Gas Regulation implementation guidance. Primary interviews engaged product development directors at Guangdong manufacturing clusters, procurement managers at German municipal facilities, and category buyers at North American big-box retailers. Secondary validation drew from battery chemistry patent databases, IEC certification registries, and cross-border e-commerce trade flow analytics. Bottom-up unit shipment estimates triangulate against top-down category spending data from facility management verticals.
Forecast inputs include cordless versus corded platform replacement cycles, lithium-ion energy density improvement trajectories, and regulatory compliance cost absorption rates. Segmentation dimensions span product architecture, motor technology tier, filtration certification grade, end-use vertical, and distribution channel structure. CAGRs derive from installed base turnover modeling and procurement budget reallocation patterns across residential, commercial, and educational settings. Industry-specific inputs incorporate brushless motor adoption curves and HEPA filtration penetration rates in healthcare procurement criteria.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by export-oriented Chinese manufacturers or accelerated solid-state battery commercialization would shift outcomes. Material shifts in EU F-Gas Regulation enforcement timelines, BIS ISI marking mandate acceleration, or cobalt supply chain disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Bottle Openers Market
Household Items
Handheld Fans Market
Household Items
Liquid Hand Soap Market
Household Items
Dry Cleaning and Laundry Market
Household Items
Ironing Boards Market
Household Items
Germany Digital Showers Market
Household Items
Global Electric Scissors Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Mirror Holder Market
Household Items
Electric Mop Market
Household Items
Hydralight Lanterns Market
Household Items
Pocket Tissues Market
Household Items
Europe Heated Mattress Pads Market
Household Items
Alarm Clocks Market
Household Items
Towel Warmers Market
Household Items
Folded Tissues Market