
 French Door Refrigerator Market | 2026-2036
French Door Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
French Door Refrigerator Market Foresight
The gap between premium and commodity tiers is consolidating around compressor architecture and smart connectivity. Haier leverages its global manufacturing footprint to anchor volume in standard and counter-depth configurations. Samsung differentiates through in-house production of inverter compressor systems and AI-driven energy management. Whirlpool Corporation sustains brand strength in North American big-box retail channels while navigating margin pressure from regulatory efficiency mandates.
A French door refrigerator positions two side-by-side doors for fresh food above a pull-out freezer drawer, typically spanning 30 to 36 inches in width with internal volumes between 20 and 28 cubic feet. The dual evaporator segment leads margin capture by isolating humidity zones between refrigerator and freezer compartments. Counter-depth configurations command premium positioning in residential kitchens where built-in aesthetics drive purchase decisions. Smart connectivity features, including Wi-Fi-enabled temperature monitoring and inventory tracking, represent the fastest-expanding technology category despite lingering interoperability fragmentation.
The U.S. Department of Energy and the EPA's ENERGY STAR program shape product efficiency baselines and retail access across North America. The EU Ecodesign Directive and F-Gas Regulation constrain refrigerant choices and insulation material specifications for European market entry. China's GB standards and MIIT circular economy mandates impose parallel efficiency and recyclability requirements. Stakeholders must monitor regulatory divergence on refrigerant transitions as this determines which compressor platforms justify sustained R&D allocation.
Market Dynamics
Compressor architecture transitions and regulatory efficiency mandates are compressing margins while forcing R&D reallocation toward dual-evaporator and inverter-based systems across all price tiers.
Growth Catalysts
- Residential renovation spending:Private households in China's tier-one cities are accelerating replacement cycles through premium kitchen upgrades in new housing completions.
- EPA ENERGY STAR alignment:Retail access across the United States now requires baseline efficiency certification, pulling manufacturers toward compliant inverter platforms.
- Smart connectivity integration:Wi-Fi-enabled inventory tracking and temperature monitoring are expanding addressable premium segments despite interoperability fragmentation.
Market Restraints
- Copper and rare-earth input volatility:Compressor manufacturing faces margin compression from commodity price swings in permanent magnet materials.
- Refrigerant transition friction:The EU F-Gas Regulation constrains R-134a and R-404A availability, forcing costly retooling for hydrocarbon or HFO alternatives.
- Technical limitation in dual-evaporator sealing:Humidity isolation between compartments requires precision manufacturing that constrains volume scaling.
Strategic Opportunities
- Underpenetrated Indian urban markets:Metro kitchen upgrades in Mumbai and Delhi present white space for counter-depth configurations.
- Channel innovation via direct-to-builder:New housing developers in the United States are consolidating appliance procurement outside traditional retail.
- Technology convergence:AI-driven energy management is converging with inverter compressor systems to create predictive load-balancing features.
Industry Challenges
- Refrigerant certification timelines:UL and CSA safety approvals for flammable hydrocarbon systems extend product launch windows by 8-14 months.
- Integration complexity with legacy home automation:Smart refrigerator APIs face fragmentation across Amazon Alexa, Google Home, and proprietary builder platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | French Door Refrigerator Market |
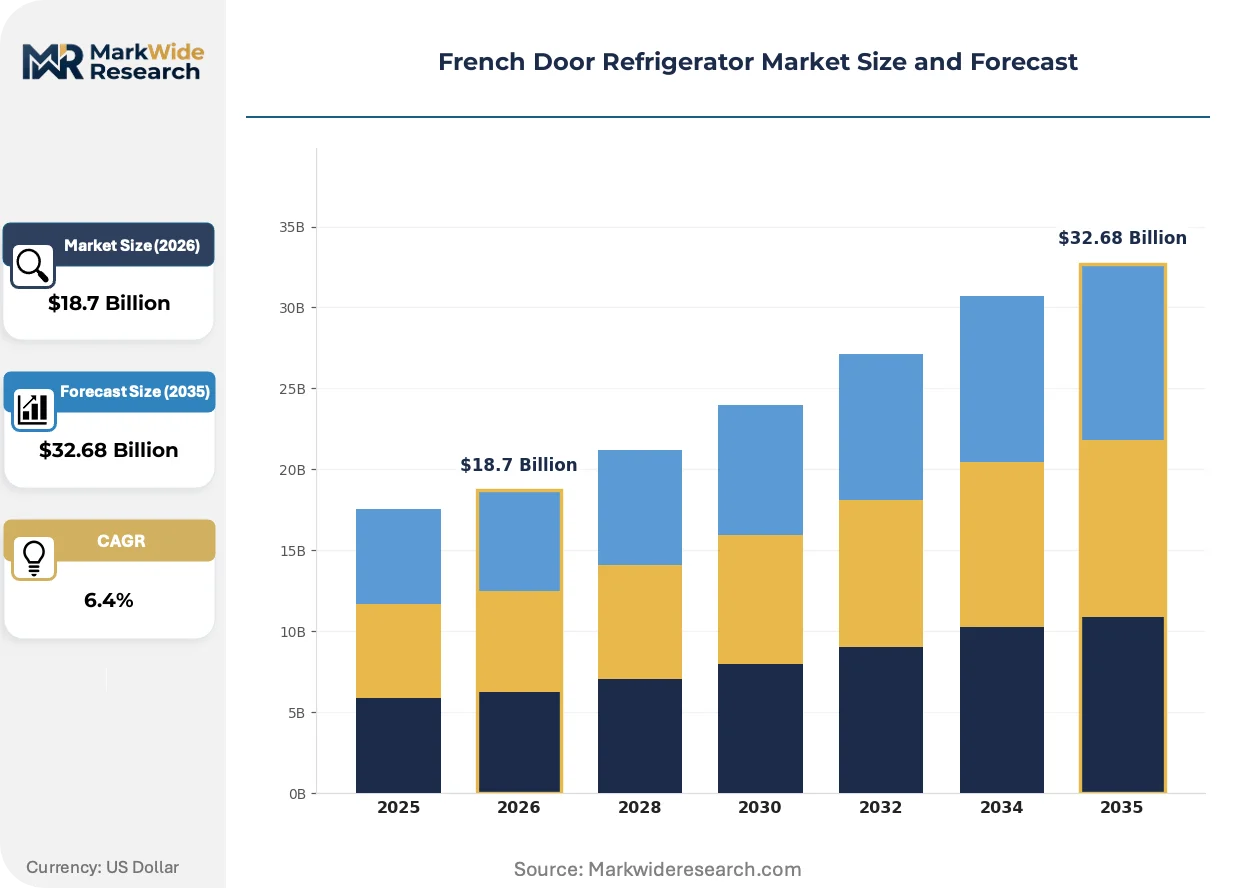
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard French Door, Counter-Depth, Built-In, Smart, Compact Technology: Inverter Compressor, Dual Evaporator, Door-in-Door, Ice & Water Dispenser, LED Lighting Application: Residential Kitchens, Gourmet Restaurants, Catering Services, Hospitality Sector, Food Storage Units End User: Private Households, Commercial Kitchens, Culinary Schools, Luxury Hotels, Foodservice Providers |
| Companies Covered | Haier, Whirlpool Corporation, LG, Samsung, Electrolux, Bosch, Midea, GE Appliances, Panasonic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
French Door Refrigerator Market Shifts & Advancements
Active reshaping in this market centers on three vectors: hardware efficiency architecture, regulatory compliance timelines, and procurement channel migration. Each trend carries distinct investment and competitive implications for manufacturer positioning.
Inverter compressor systems with variable-speed drives are replacing fixed-speed reciprocating architectures in premium and mid-tier units. Residential buyers in the United States and China are specifying these platforms for ENERGY STAR compliance and utility rebate eligibility. Variable-speed control is converging with dual-evaporator humidity management to enable precise compartment-level climate control.
The U.S. Department of Energy's amended appliance efficiency standards are tightening minimum coefficient of performance thresholds for residential refrigeration. Manufacturers must redesign insulation density and compressor mapping to maintain retail access. The standard-depth segment faces the steepest compliance cost absorption, accelerating its consolidation toward inverter platforms.
Builder-direct procurement is displacing big-box retail for new construction appliance packages in the United States. Tract home developers in Texas and Florida are consolidating volume commitments with manufacturers for counter-depth French door configurations. This channel shift compresses brand marketing spend while demanding customized finish and handle options.
French Door Refrigerator Market Segmentation
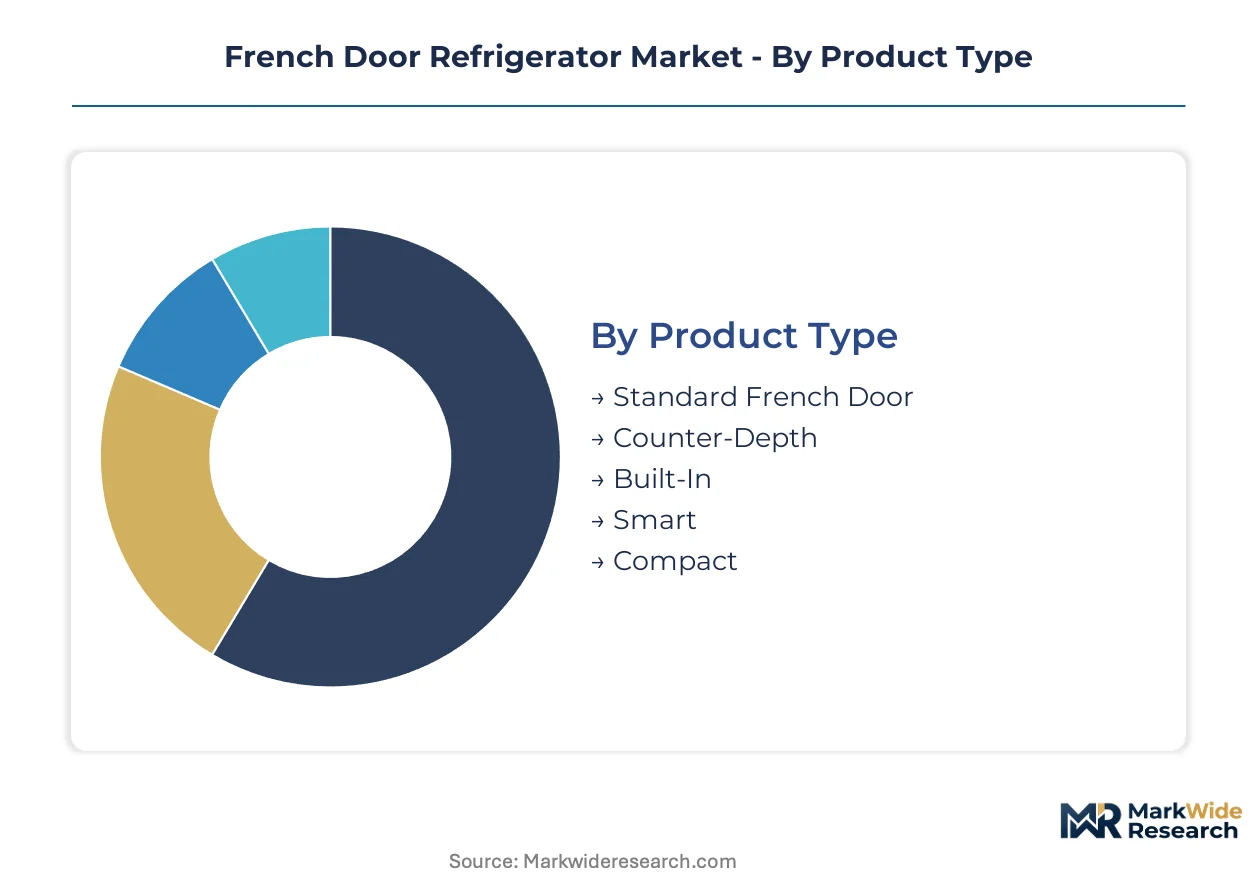
French door refrigerator segmentation reveals divergent margin structures across installation types and compressor architectures. Manufacturers allocate R&D budgets based on which segments justify platform-specific tooling investments versus shared component strategies.
Product Type:
Volume concentrates in standard configurations while premium capture shifts toward built-in and smart variants.
- Standard French Door:Fixed-depth units spanning 30 to 36 inches dominate replacement cycles in suburban single-family housing. Demand clusters in Texas and Florida where new construction tract homes specify these configurations for cost-controlled appliance packages.
- Counter-Depth:Shallower profiles align with cabinetry lines for built-in aesthetics without custom installation costs. Residential kitchen renovations in China's tier-one cities specify these units for premium housing completions where visual integration drives purchase decisions.
- Built-In:Panel-ready designs integrate with custom millwork for ultra-premium residential applications.
- Smart:Wi-Fi-enabled inventory tracking and AI-driven energy management represent the steepest expansion trajectory despite interoperability fragmentation.
- Compact:Reduced-width units target urban apartments and secondary kitchen installations.
Today's leader: Standard French Door. Tomorrow's challenger: Smart.
Technology:
Regulatory efficiency mandates are resegmenting the market by compressor architecture and humidity management capabilities.
- Inverter Compressor:Variable-speed drives modulate cooling load against ambient conditions and door-opening frequency. U.S. Department of Energy efficiency standards and EPA ENERGY STAR rebate eligibility are pulling manufacturers toward these platforms across all price tiers.
- Dual Evaporator:Separate cooling circuits isolate humidity between refrigerator and freezer compartments, extending produce shelf life. Precision sealing requirements constrain volume scaling and concentrate production among specialized component suppliers.
- Door-in-Door:Secondary access panels reduce cold air loss for frequently retrieved items.
- Ice & Water Dispenser:External dispensing systems require additional filtration infrastructure and consume freezer compartment volume.
- LED Lighting:Solid-state illumination reduces heat load and energy consumption versus incandescent alternatives.
Inverter compressors anchor current volume. Dual evaporators define tomorrow's premium differentiation.
Application:
End-use diversification stretches from mass residential replacement to specialized foodservice requirements.
- Residential Kitchens:Private household renovation spending accelerates replacement cycles, with ENERGY STAR compliance now baseline for retail access in the United States.
- Gourmet Restaurants:Chef-driven establishments specify dual-evaporator units for ingredient preservation quality.
- Catering Services:Mobile and event-based food operations require durability-focused configurations.
- Hospitality Sector:Luxury hotels balance aesthetic requirements with operational reliability for 24/7 service.
- Food Storage Units:Dedicated cold storage facilities prioritize capacity density over feature integration.
Residential kitchens command current volume. Gourmet restaurants represent the fastest-climbing premium niche.
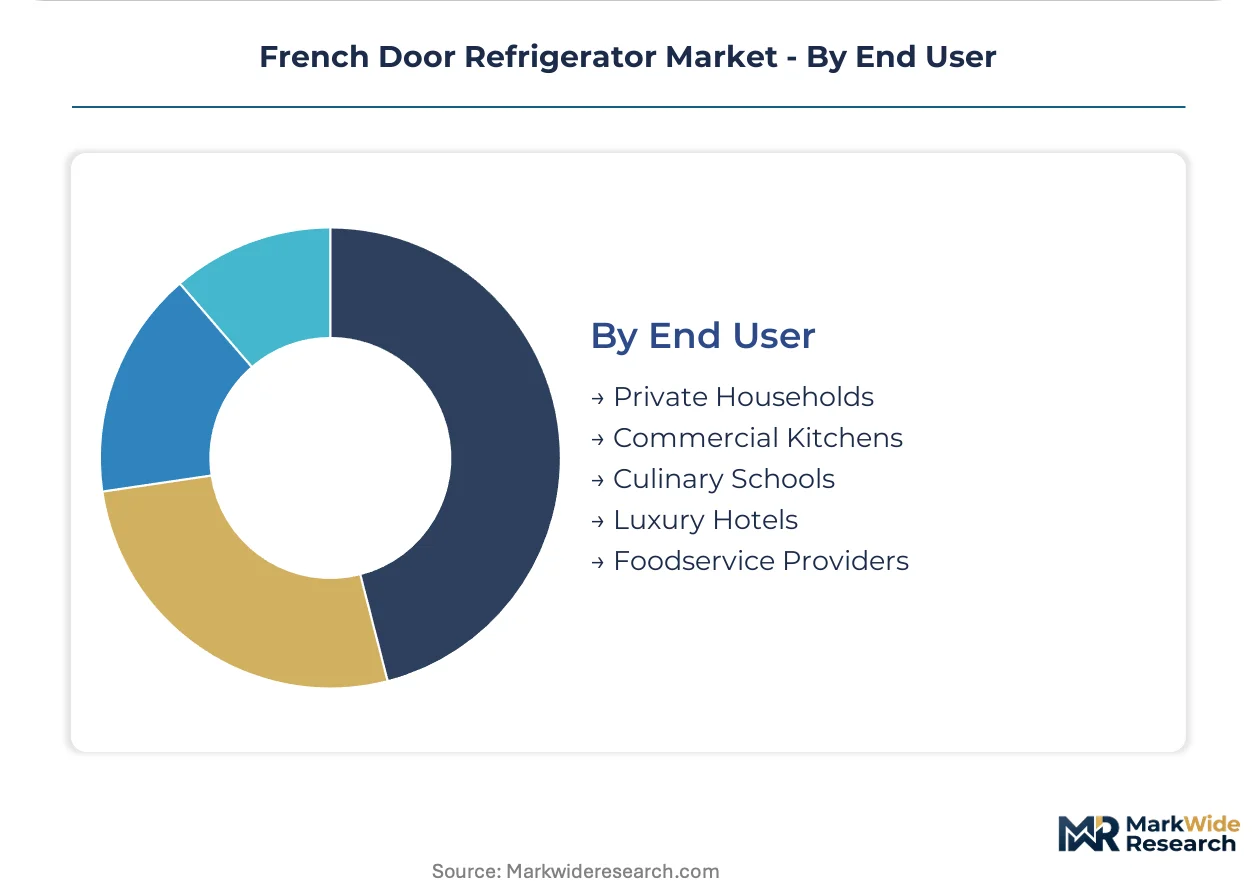
End User:
Procurement authority separates consumer-driven replacement from institutional specification processes.
- Private Households:Individual purchasers respond to utility rebate programs and retail promotional cycles, with builder-direct procurement displacing big-box channels for new construction.
- Commercial Kitchens:Foodservice operators prioritize total cost of ownership and service network density over upfront acquisition cost.
- Culinary Schools:Training institutions require transparent-door demonstration units and standardized configurations for curriculum consistency.
- Luxury Hotels:Brand standards dictate panel-ready aesthetics and silent operation for guest floor installations.
- Foodservice Providers:Contract management companies centralize procurement across multi-site operations.
Private households dominate transaction volume. Commercial kitchens offer contract-based revenue stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities generate premium upgrade velocity that outpaces replacement demand in mature Western markets. The United States maintains volume leadership through builder-direct procurement channels, while regulatory efficiency mandates reshape competitive positioning across both geographies.
United States
Residential kitchen renovations in Texas and Florida accelerate replacement cycles for standard-depth configurations. The EPA's ENERGY STAR program now mandates baseline efficiency certification for retail access, compressing margins on conventional compressor platforms. Builder-direct procurement in Sun Belt metro areas consolidates volume commitments outside traditional big-box channels.
China
Premium housing completions in Shanghai, Beijing, and Shenzhen concentrate demand for counter-depth aesthetics. MIIT circular economy mandates impose parallel efficiency and recyclability requirements on domestic manufacturers. The Yangtze River Delta manufacturing cluster anchors inverter compressor production for both domestic consumption and export markets.
Germany
High-end residential renovations specify panel-ready built-in configurations for kitchen integration. The EU F-Gas Regulation constrains R-134a and R-404A refrigerant availability, forcing costly retooling for hydrocarbon alternatives. Industrial concentration in Baden-Württemberg supports precision sealing component supply for dual-evaporator systems.
India
Metro kitchen upgrades in Mumbai and Delhi present white space for counter-depth configurations previously underpenetrated. BIS efficiency labeling requirements establish minimum performance thresholds for market entry. The Maharashtra-Gujarat industrial corridor hosts emerging component fabrication for inverter compressor assembly.
Japan
Space-constrained urban housing drives compact French door adoption in Tokyo and Osaka metro areas. METI energy conservation standards enforce stringent coefficient of performance thresholds for residential appliances. The Kanto region maintains specialized production capacity for precision humidity control systems.
French Door Refrigerator Market Competitive Landscape
Top-tier vendors anchor premium and mid-tier positioning, while regional specialists and private-label fabricators occupy volume-driven segments. The vendor base stratifies across three strategic archetypes: diversified appliance conglomerates with captive compressor production, mid-scale specialists leveraging OEM partnerships, and emerging Asian manufacturers competing on cost-engineered platforms. Competitive intensity centers on dual-evaporator technology licensing and builder-direct channel consolidation.
Within the diversified conglomerate tier, Haier and Samsung exemplify contrasting strategic postures. Haier leverages its Qingdao-based manufacturing footprint to anchor volume across standard and counter-depth configurations. Samsung occupies a position emphasizing in-house inverter compressor production and AI-driven energy management integration. Whirlpool Corporation sits within the North American retail-anchored archetype, navigating margin pressure from regulatory efficiency mandates while sustaining brand strength in big-box distribution channels.
| Leading Market Players |
|---|
| Haier |
| Whirlpool Corporation |
| LG |
| Samsung |
| Electrolux |
| Bosch |
| Midea |
| GE Appliances |
| Panasonic |
| Others |
Supply & Pricing Matrix
Specialized compressor manufacturing labor pools in the Yangtze River Delta and northern Mexico create tiered labor-cost differentials that widen pricing spreads between premium inverter systems and fixed-speed commodity platforms. These workforce concentrations allow manufacturers to anchor economy-tier production in lower-wage zones while reserving precision dual-evaporator assembly for higher-cost skilled labor markets.
Pricing Analysis
Installation and haul-away service bundling versus unbundled transactional pricing separates big-box retail from builder-direct procurement channels. Three-tier pricing structure across premium, standard, and economy levels tracks compressor architecture complexity and smart connectivity integration. Cost compression in standard-depth configurations is intensifying because U.S. Department of Energy efficiency standards mandate inverter platform adoption. Builder-direct buyers exhibit lowest price sensitivity due to consolidated volume commitments, while individual replacement purchasers in suburban markets demonstrate highest sensitivity to promotional cycles.
Supply Chain Analysis
Workforce availability for precision sealing and inverter controller assembly concentrates in China's Jiangsu province, South Korea's Gyeonggi region, and Mexico's Nuevo León corridor. Permanent magnet materials for compressor motors draw from rare-earth processing in China and magnet fabrication in Japan and Germany. Single-source vulnerability in rare-earth oxide supply creates exposure to export quota disruptions. Distribution runs through manufacturer-direct builder procurement, big-box retail fulfillment centers, and regional appliance distributor networks serving independent dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The French door refrigerator market functions as a stable compounder anchored by residential renovation spending that accelerates replacement cycles regardless of cyclical construction volatility.
For Market Incumbents: To counter margin compression from U.S. Department of Energy efficiency mandates, redirect R&D allocation toward captive inverter compressor production and dual-evaporator platform standardization. Secure builder-direct channel control through customized finish options and volume commitment pricing for Sun Belt tract home developers. For New Entrants and Emerging Players: Capture underpenetrated counter-depth demand in Indian metro markets by establishing local assembly partnerships in the Maharashtra-Gujarat industrial corridor. Lead with BIS efficiency certification compliance and after-sales service network density as primary go-to-market differentiation against established import brands. For Investors and Strategic Acquirers: Diversified appliance conglomerates with captive compressor production are the most active acquirer in this space, seeking dual-evaporator technology licensing and regional manufacturing footprint. Long-term viability centers on regulatory compliance platform consolidation rather than brand arbitrage. Watch refrigerant certification timeline extensions at UL and CSA as the inflection signal for product launch risk and stranded inventory exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Compressor Platform Standardization | Captures U.S. Department of Energy rebate eligibility and ENERGY STAR retail access mandates. |
| Dual-Evaporator Technology Licensing | Isolates humidity zones to extend produce shelf life for premium residential and gourmet restaurant segments. |
| Builder-Direct Channel Expansion | Bypasses big-box retail marketing spend while securing multi-year volume commitments from tract home developers. |
| Refrigerant Transition Compliance Investment | Enables EU F-Gas Regulation market access through hydrocarbon or HFO alternative certification. |
| Smart Connectivity API Development | Addresses interoperability fragmentation across Amazon Alexa, Google Home, and proprietary builder home automation platforms. |
Research Methodology
Multiple input streams — executive interviews with appliance manufacturer product planning directors, procurement managers at national homebuilders, and component supplier sales engineers; secondary validation through U.S. Department of Energy appliance standard filings, EPA ENERGY STAR certification databases, and MIIT circular economy policy circulars; plus customs trade data for compressor and refrigeration component flows — were reconciled through bottom-up unit shipment modeling and top-down market value triangulation.
Data-stream reconciliation applied across the projection horizon segmented volume and value by installation type, compressor architecture, smart connectivity tier, and regional regulatory cluster. CAGRs were derived from regression analysis against residential renovation spending indices and new housing completion trajectories. Forecast inputs incorporated ENERGY STAR rebate program participation rates and builder-direct procurement channel migration patterns.
Refrigerant certification timeline delays, rare-earth export quota disruptions, and ENERGY STAR program eligibility threshold revisions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding efficiency standard implementation schedules and replacement cycle acceleration factors. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Colombia Appliances and Electronics Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Microwave Market
Appliances
Small Electric Kettles Market
Appliances
Smart Microwave Oven Market
Appliances
Mobile Refrigerators Market
Appliances
Commercial Microwave Ovens Market
Appliances
Glass Ceramic Cooktop Market
Appliances
United States Washing Machine Market
Appliances
Conveyor Dishwasher Market
Appliances
Mexico Laundry Appliances Market
Appliances
Dishwasher Market
Appliances
US Portable Washing Machines Market
Appliances
North America Compact Dishwasher Market
Appliances
Kuwait Dishwasher Market
Appliances
Built-In Large Cooking Appliance Market