
 Mini Refrigerator Market | 2026-2036
Mini Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Refrigerator Market Foresight
DC compressor technology is rewriting the engineering economics of mini refrigerator production, enabling thinner wall insulation and lighter cabinet designs without sacrificing cooling performance. Haier Smart Home leverages its captive compressor manufacturing in Qingdao to control component costs across the compact and single door lines. Midea Group sustains export volume leadership through dedicated OEM channels serving North American and European retail brands. Panasonic Corporation differentiates in the beverage cooler segment with precision temperature control systems targeting wine storage applications.
A mini refrigerator is a self-contained, electrically powered cooling appliance with internal volume typically below eight cubic feet, utilizing vapor-compression or thermoelectric refrigeration cycles to maintain temperatures between 34°F and 50°F for food preservation or beverage chilling. The primary commercial purpose centers on space-constrained environments where full-size refrigeration proves impractical or energy-prohibitive. Single door and compact units anchor volume shipments in residential dormitories and small apartments where footprint constraints override capacity needs. Beverage coolers command premium positioning in hotels and office break rooms where glass-door aesthetics and precise temperature zoning justify higher price points. Double door configurations remain a niche within the mini refrigerator category, concentrated in upscale short-term rental properties seeking kitchenette functionality.
The US Department of Energy enforces minimum energy conservation standards under 10 CFR 430 that compel manufacturers to redesign insulation packages and compressor efficiency maps. China's GB standards for household refrigerating appliances, administered by SAMR, mandate refrigerant transitions and labeling protocols that affect export eligibility. The EU F-Gas Regulation progressively restricts hydrofluorocarbon refrigerants, pushing European-market suppliers toward hydrocarbon or natural refrigerant alternatives. Stakeholders must monitor regulatory divergence across these three jurisdictions to avoid stranded inventory and compliance-driven redesign cycles.
Market Dynamics
DC compressor miniaturization is compressing cabinet depths and enabling new placement geometries in space-constrained environments. This technology shift is redrawing competitive boundaries between thermoelectric and vapor-compression architectures.
Growth Catalysts
- Student housing expansion:University towns across the United States are retrofitting dormitories with compact refrigeration units. Procurement volumes from institutional housing operators are accelerating replacement cycles.
- 10 CFR 430 efficiency mandates:The US Department of Energy's updated appliance standards are forcing insulation and compressor redesigns. Compliance investments are creating technical barriers that favor scaled manufacturers.
- Qingdao-OEM cluster concentration:Coastal China's captive compressor and cabinet assembly ecosystems are shortening lead times for export orders. Vertical control over refrigeration subsystems is compressing landed costs for North American and European retail brands.
Market Restraints
- Copper and steel input volatility:Condenser coil and cabinet shell materials face commodity price swings. Margin pressure from raw material exposure limits pricing flexibility for mid-tier suppliers.
- Refrigerant transition friction:The EU F-Gas Regulation is phasing down hydrofluorocarbon availability. European-market inventory is splitting between legacy and hydrocarbon-compatible service networks.
- Thermoelectric performance ceiling:Peltier-based units cannot achieve the temperature deltas required for food preservation. Beverage-only applications cap addressable market share for solid-state cooling architectures.
Strategic Opportunities
- Short-term rental kitchenettes:Airbnb hosts and boutique hospitality operators are specifying double-door mini refrigerators. This application commands premium positioning through integrated freezer compartments.
- India BIS energy labeling:The Bureau of Indian Standards' mandatory star-rating program is creating tiered market segmentation. Early compliance investments open access to organized retail channels in tier-2 cities.
- IoT-enabled inventory management:Connected compressors and door sensors are converging with property management software. Hotels and co-living operators are piloting predictive maintenance and consumption tracking.
Industry Challenges
- Hydrocarbon refrigerant technician certification:R600a and R290 handling requires specialized training and equipment. Service network expansion is lagging product rollout timelines in regulated markets.
- Cross-jurisdiction labeling complexity:Simultaneous compliance with US EnergyGuide, EU energy labels, and China GB marking is fragmenting packaging and documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Refrigerator Market |
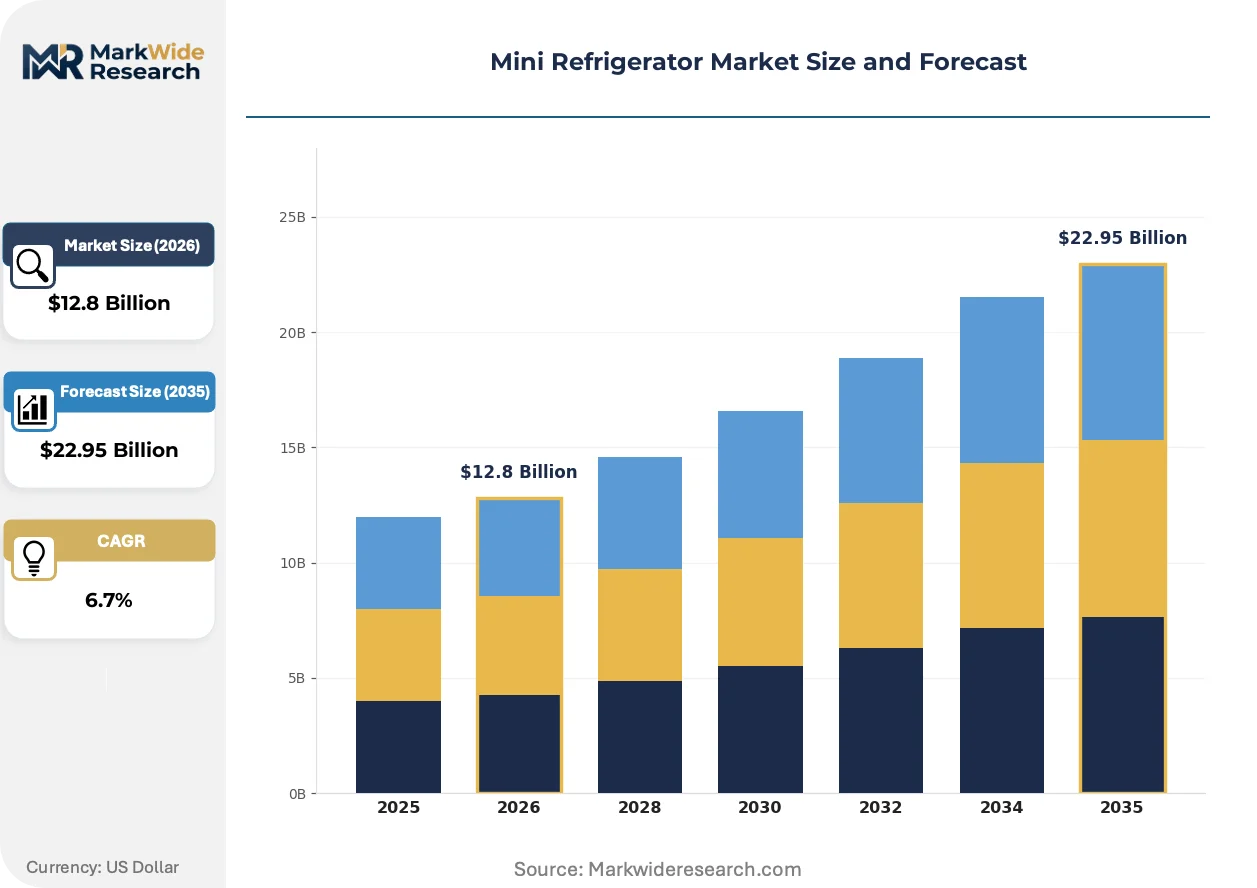
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Door, Double Door, Compact, Beverage Cooler Application: Residential, Commercial, Office, Hotels Size: 2-3 Cu Ft, 4-5 Cu Ft, 6-7 Cu Ft, 8+ Cu Ft Power Rating: 50W-100W, 100W-150W, 150W-200W, 200W+ |
| Companies Covered | Haier Smart Home, Midea Group, Whirlpool Corporation, LG Electronics, Samsung Electronics, Danby, Dometic Group AB, Panasonic Corporation, Electrolux AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Refrigerator Market Shifts & Advancements
Refrigeration subsystem integration is accelerating product architecture convergence. Compressor-electronics-insulation packages are being redesigned as unified modules rather than discrete components.
Variable-speed DC compressor technology is digitizing temperature control precision. Wine storage applications in hotels and residential cellars are adopting these systems for ±1°F stability. The elimination of mechanical thermostats is compressing failure rates and enabling remote diagnostics through integrated motor controllers.
The EU F-Gas Regulation is forcing refrigerant chemistry transitions. Hydrocarbon alternatives are penetrating European-market production lines ahead of quota phase-down deadlines. Beverage cooler segments are most affected, with glass-door SKUs requiring complete refrigeration circuit redesigns to maintain safety certifications.
Direct-to-property-manager procurement is consolidating channel influence. Institutional buyers in student housing and extended-stay hospitality are bypassing traditional retail distribution. This pattern is most visible in US university towns, where housing operators negotiate fleet pricing for standardized unit specifications.
Mini Refrigerator Market Segmentation
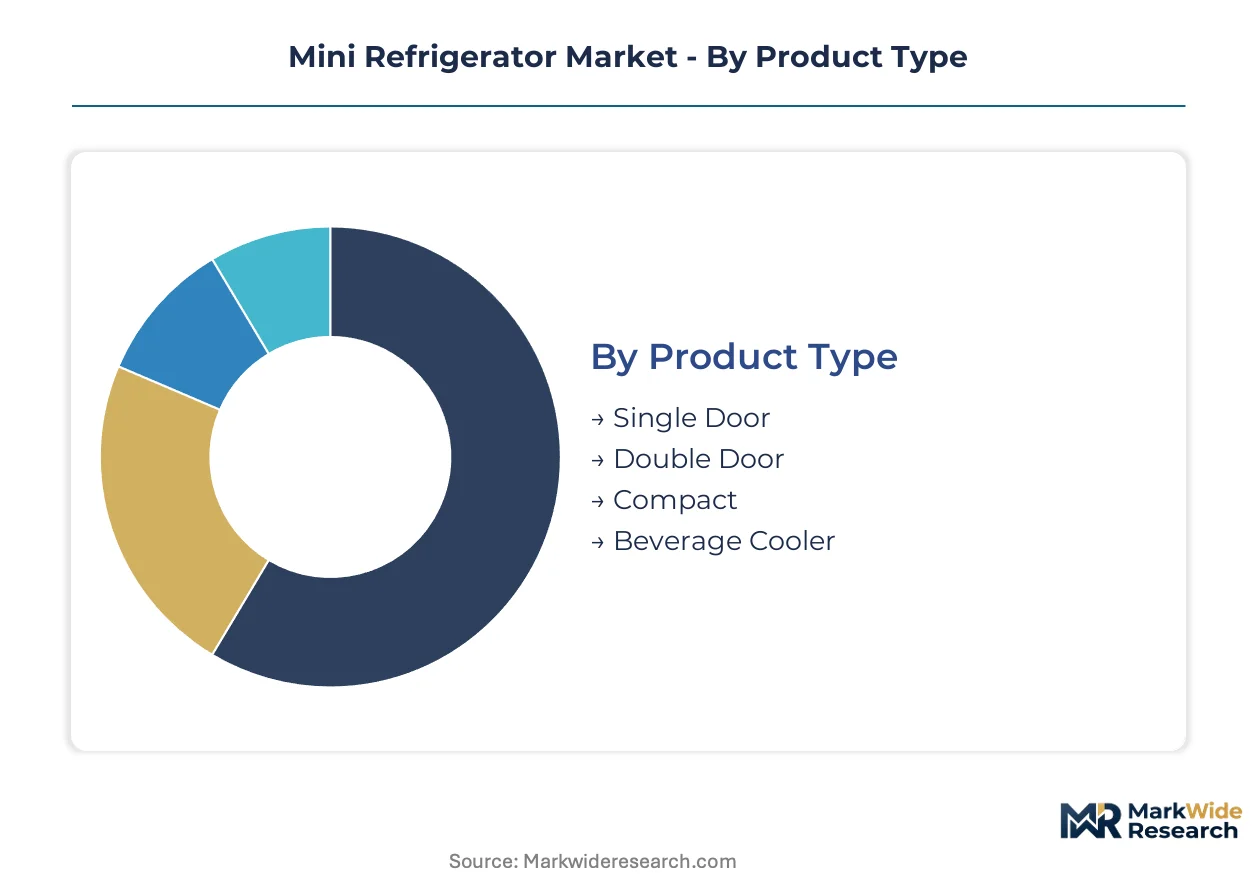
Mini refrigerator segmentation reveals divergent service intensity and margin profiles across product architectures. Understanding these divides allows manufacturers to align production capacity with channel-specific warranty obligations and replacement cycle expectations.
Product Type:
After-sales service intensity varies sharply across cooling architectures, with compressor-based units requiring qualified technician networks versus thermoelectric models suited to swap-out replacement programs.
- Single Door:Vapor-compression units with integrated freezer compartments dominate dormitory and small apartment installations. Procurement from US student housing operators is compressing replacement cycles to 4-6 years as institutional fleet agreements standardize on uniform specifications.
- Beverage Cooler:Glass-door display units with precision temperature zoning target hotel minibars and residential wine storage. EU F-Gas Regulation compliance is forcing hydrocarbon refrigerant transitions that extend redesign timelines and elevate certification requirements for field service networks.
- Double Door:Separate refrigerator-freezer compartments serve Airbnb kitchenettes and extended-stay suites. Premium positioning supports longer warranty terms and white-glove installation services.
- Compact:Sub-4 cubic foot thermoelectric or absorption units address countertop and RV applications. Limited cooling capacity restricts addressable use cases to beverage chilling and medication storage.
Single Door holds the largest share; momentum sits with Beverage Cooler as hospitality operators upgrade minibars with connected inventory systems.
Application:
Cost tier stratification separates residential discretionary purchases from commercial fleet procurement with negotiated service level agreements and volume pricing mechanisms.
- Residential:Individual consumers purchasing through retail channels prioritize footprint constraints and EnergyGuide ratings over extended warranties. Replacement decisions correlate with household relocation patterns rather than product failure.
- Commercial:Restaurants and foodservice operators demand NSF-certified units with rapid-response service contracts. Downtime costs justify premium pricing for same-day technician dispatch.
- Office:Corporate break room installations emphasize glass-door aesthetics and quiet operation. Procurement through facilities management vendors concentrates volume with national service network providers.
- Hotels:Minibar and guest room specifications prioritize silent operation and lockable compartments. Direct-to-brand procurement is displacing traditional distribution as chains standardize fleet-wide configurations.
Residential captures the highest unit volumes; Hotels represent the steepest expansion trajectory as branded hospitality chains accelerate property renovation cycles.
Size:
Volume concentration in mid-size brackets reflects trade-offs between footprint constraints and functional utility across residential and commercial use cases.
- 4-5 Cu Ft:The dimensional sweet spot for US dormitory specifications and European apartment kitchenettes. China's OEM clusters optimize cabinet stamping dies around this capacity band to maximize production efficiency.
- 6-7 Cu Ft:Double-door configurations serving short-term rental kitchenettes and extended-stay suites. Integrated freezer compartments justify premium positioning through enhanced functionality.
- 2-3 Cu Ft:Countertop and personal storage units for medication and cosmetics. Thermoelectric architectures dominate this bracket due to weight and portability requirements.
- 8+ Cu Ft:Niche segment approaching full-size refrigerator thresholds. Limited differentiation from standard compact refrigerators constrains growth.
4-5 Cu Ft commands the largest installed base; 6-7 Cu Ft is gaining share fastest as hospitality operators specify kitchenette functionality.
Power Rating:
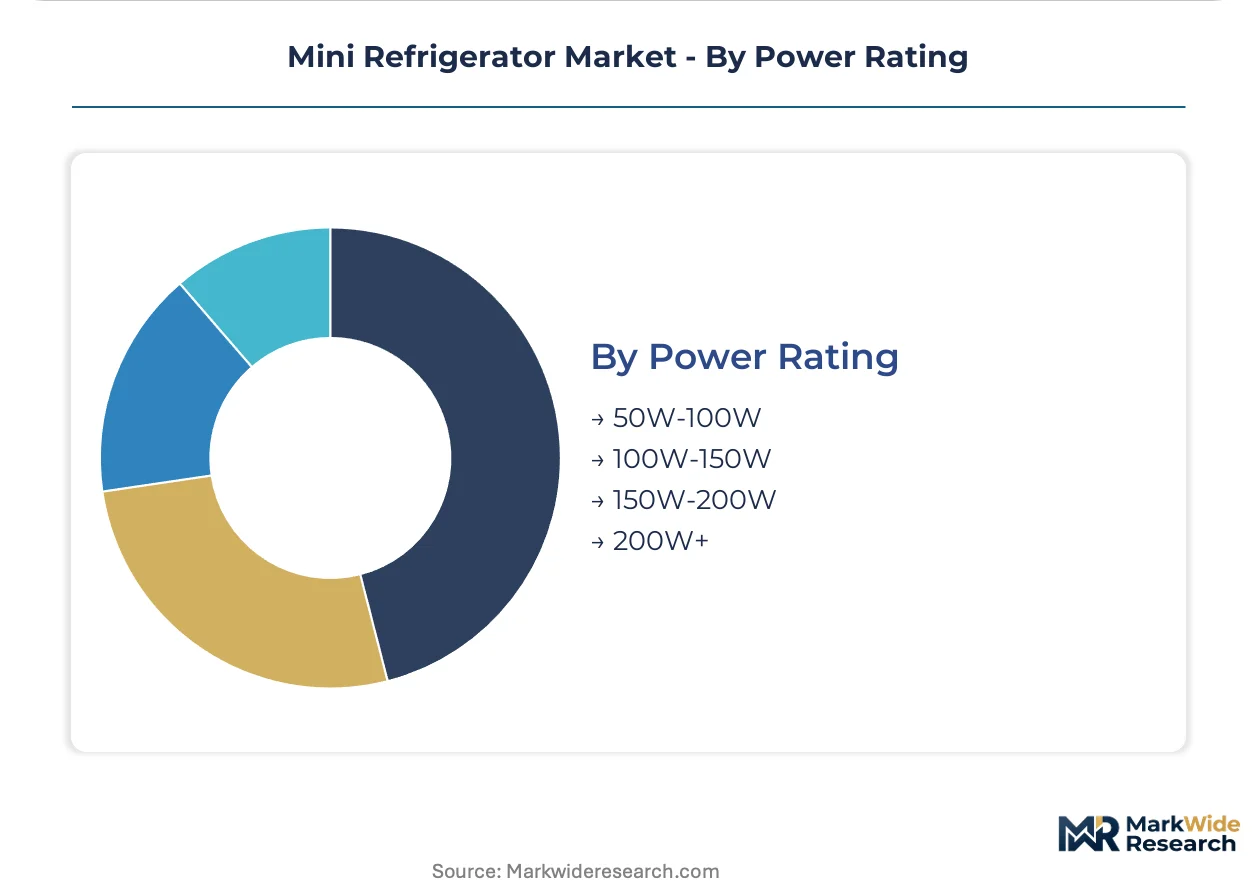
Margin structure tightens at higher wattage bands as 10 CFR 430 efficiency mandates force costly compressor and insulation redesigns to maintain performance within constrained consumption envelopes.
- 50W-100W:Thermoelectric and advanced DC compressor units achieving compliance with stringent efficiency standards. China's coastal manufacturing provinces concentrate production of these low-draw architectures for export markets.
- 100W-150W:Standard vapor-compression workhorses balancing cooling capacity against operating cost. The US Department of Energy's updated standards are compressing allowable consumption bands in this range.
- 150W-200W:Larger single-door and compact double-door units facing redesign pressure. Margin compression from compliance investments favors scaled manufacturers with captive compressor production.
- 200W+:Beverage coolers with glass-door thermal loads and precision control systems. Premium pricing absorbs efficiency-driven cost increases.
100W-150W represents the largest volume band; 50W-100W is climbing the fastest as DC compressor miniaturization enables thinner insulation packages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese coastal manufacturing provinces export compressor and cabinet assemblies to North American student housing operators and European hospitality chains. This trade corridor channels OEM production through Qingdao and Guangdong clusters toward institutional procurement programs in the United States and Germany.
United States
University towns from Austin to Ann Arbor are expanding dormitory refrigeration fleets through direct procurement contracts with housing operators. The US Department of Energy enforces 10 CFR 430 efficiency standards that compel insulation and compressor redesigns. Appliance assembly for the domestic market concentrates in Midwest industrial corridors where logistics networks serve institutional buyers.
China
Qingdao's captive compressor manufacturing ecosystem supplies DC miniaturized units for export markets demanding thinner cabinet profiles. SAMR administers GB standards for household refrigerating appliances that mandate refrigerant transitions and labeling protocols. Guangdong province's Pearl River Delta hosts cabinet stamping and final assembly operations optimized for North American and European retail brand orders.
Germany
Extended-stay hospitality operators in Berlin and Munich are specifying double-door kitchenette units for Airbnb-serviced apartments. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, forcing hydrocarbon-compatible production line conversions. Bavaria's industrial regions host precision temperature control engineering for beverage cooler applications targeting hotel minibars.
India
Tier-2 city retail channels in Pune and Hyderabad are opening to organized appliance distribution as BIS energy labeling creates tiered market segmentation. The Bureau of Indian Standards mandates star-rating compliance for access to formal retail networks. Tamil Nadu's manufacturing corridors are attracting component suppliers serving domestic assembly operations.
Japan
Residential wine storage applications in Tokyo and Osaka metropolitan areas are adopting precision temperature control systems. METI oversees industrial efficiency guidelines that influence compressor technology adoption timelines. Chubu region's Nagoya industrial cluster maintains specialized engineering capabilities for variable-speed DC refrigeration subsystems.
Mini Refrigerator Market Competitive Landscape
Channel-controlling players compete with product-specialist players across institutional procurement and retail distribution vectors. The market structure tiered between scaled OEM suppliers and branded finished goods manufacturers. Three archetypes dominate: captive compressor producers with backward integration into cabinet assembly, retail brand licensors sourcing from Chinese OEM clusters, and precision temperature specialists serving hospitality applications. Competitive moves concentrate on vertical integration into refrigeration subsystems and direct-to-property-manager channel bypass strategies.
Among Chinese appliance conglomerates, Haier Smart Home and Midea Group exemplify the captive-manufacturing archetype through Qingdao-based compressor production and Guangdong OEM channel dominance. Panasonic Corporation occupies a position within the precision-control specialist tier. These three anchors illustrate how geographic concentration of refrigeration subsystem production aligns with divergent go-to-market strategies across institutional and retail channels.
| Leading Market Players |
|---|
| Haier Smart Home |
| Midea Group |
| Whirlpool Corporation |
| LG Electronics |
| Samsung Electronics |
| Danby |
| Dometic Group AB |
| Panasonic Corporation |
| Electrolux AB |
| Others |
Supply & Pricing Matrix
Copper and steel input volatility compresses margin buffers across the mini refrigerator supply chain, forcing manufacturers to segment pricing tiers by compressor technology generation while concentrating production in coastal Chinese provinces with captive component ecosystems. This commodity exposure simultaneously widens spreads between DC compressor premium units and legacy thermoelectric economy models, and locks supply chain geography around Qingdao compressor foundries and Guangdong cabinet stamping clusters.
Pricing Analysis
The technology-generation pricing gap separates variable-speed DC compressor units commanding premium positioning from fixed-speed legacy models and thermoelectric economy tiers. Three-tier pricing structure across premium, standard, and economy levels aligns with 10 CFR 430 efficiency certification tiers, where star-rated compliance opens organized retail channels. Pricing pressure stems from raw material swings in condenser coil copper and cabinet shell steel. Student housing procurement teams exhibit highest price sensitivity, while hospitality operators purchasing connected minibars absorb premiums for inventory integration.
Supply Chain Analysis
Export-control restrictions on advanced compressor motor controllers and variable-speed drive electronics limit technology transfer to Chinese manufacturing clusters. Geographic supply concentration centers on China, South Korea, and Mexico, with Qingdao captive compressor production feeding Guangdong final assembly. Raw material dependencies include copper for condenser coils, cold-rolled steel for cabinet shells, and hydrocarbon refrigerants for EU-compliant production lines. Single-source vulnerability concentrates in DC compressor miniaturization IP held by limited engineering houses. Distribution runs through direct-to-property-manager channels for institutional buyers and retail brand licensing for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mini refrigerator market sits in a cyclical recovery phase as university housing expansion and hospitality renovation cycles drive replacement demand. Institutional procurement patterns normalize following pandemic-disrupted fleet purchasing.
For Market Incumbents: Build captive compressor manufacturing moats through backward integration into DC miniaturization technology. Haier Smart Home's Qingdao foundry model demonstrates how in-house production of refrigeration subsystems insulates margin structures from commodity swings. Defend position by accelerating hydrocarbon refrigerant service network certification ahead of EU F-Gas quota deadlines. Channel control through direct procurement contracts with US student housing operators locks replacement cycle visibility.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 city organized retail channels by securing BIS star-rating compliance ahead of distribution expansion. The 6-7 cubic foot double-door segment serving Airbnb kitchenettes offers white-space penetration with lower incumbent saturation than dormitory single-door markets. Target hospitality technology integrators as go-to-market partners for IoT-enabled inventory management pilots.
For Investors and Strategic Acquirers: The EU F-Gas Regulation's hydrocarbon transition deadline reshapes the acquisition landscape by stranding legacy refrigerant inventory and elevating certified service network value. Long-term viability favors targets with variable-speed DC engineering capabilities and hospitality channel relationships over pure-play thermoelectric assemblers. Watch technician certification velocity in European markets as the inflection signal for competitive positioning durability.
| Strategic Initiative | Industry Significance |
|---|---|
| DC Compressor Miniaturization Investment | Captive production of variable-speed drives enables thinner cabinet profiles without efficiency sacrifice. |
| Hydrocarbon Refrigerant Transition | R600a and R290 conversion maintains EU market access under F-Gas quota phase-down schedules. |
| Direct-to-Property-Manager Channel Development | Bypassing retail distribution captures institutional procurement volumes in student housing and extended-stay hospitality. |
| IoT Inventory Integration Partnership | Connected compressor diagnostics converge with property management software for predictive maintenance revenue streams. |
| India BIS Star-Rating Early Compliance | Mandatory energy labeling opens organized retail access in Pune, Hyderabad, and other tier-2 expansion markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with procurement directors at US student housing operators, hospitality technology integrators, and OEM sourcing managers at Chinese coastal manufacturing clusters. Secondary validation drew from US Department of Energy 10 CFR 430 filings, EU F-Gas Regulation implementation reports, China SAMR GB standard documentation, and India BIS energy labeling databases. Bottom-up unit shipment estimates by product architecture and application were triangulated against top-down value projections across the analysis window.
Calibration approaches anchored volume forecasts to replacement cycle dynamics in institutional housing and renovation patterns in hospitality. Segmentation dimensions modeled include cooling architecture, product type, application sector, capacity band, and power rating tier. CAGRs were derived from slope analysis of historical procurement trajectories and elasticity-adjusted projections. Industry-specific inputs incorporated compressor technology adoption curves and regulatory compliance cost pass-through assumptions.
Macroeconomic conditions sit as an overlay; deviation in copper and steel commodity indices, freight rate volatility, or cross-border tariff regimes would shift the trajectory. Forecasts reflect assumptions around efficiency standard implementation timelines and refrigerant transition schedules. Material shifts in US student housing construction starts or EU hydrocarbon technician certification velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Triple Barrel Waver Market
Appliances
Residential Space Heater Market
Appliances
Induction Cooktops Market
Appliances
Electric Yogurt Maker Market
Appliances
Oman Microwave Ovens Market
Appliances
Household Side by Side Refrigerator Market
Appliances
Window Air Conditioners Market
Appliances
Clothing Iron Market
Appliances
Refrigerated Cabinet Market
Appliances
Cordless Vacuum Cleaner Market
Appliances
Personal Care Appliances Market
Appliances
North America Microwave Oven Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
France Household Electric Grills Market
Appliances
Household Beauty Appliances Market
Appliances
Qatar Dishwashers Market