
 Egypt Microwave Ovens Market | 2026-2036
Egypt Microwave Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Microwave Ovens Market Foresight
Premium-tier convection and grill functionality is rotating through the Egyptian microwave category as consumers trade up from basic solo units. Samsung leverages its inverter technology portfolio to anchor the upper-mid segment in Cairo and Alexandria retail channels. LG Electronics sustains competitive pressure through localized assembly and extended warranty programs. Whirlpool Corporation differentiates via built-in microwave configurations targeting new residential developments along the New Administrative Capital corridor.
A microwave oven is an electric kitchen appliance utilizing magnetron-generated electromagnetic radiation at approximately 2.45 GHz to heat polar molecules in food, with cavity capacities typically spanning 20–42 liters and power ratings from 700–1200 watts for domestic Egyptian voltage standards. The primary purpose is rapid thermal processing for defrosting, reheating, and full meal preparation across residential and foodservice environments. Solo microwave units occupy the volume base but carry thin margins, while convection microwaves command premium positioning through combined radiant and forced-air cooking. Grill microwaves are gaining traction among Egyptian households seeking browning capability without full oven investment. Sensor cooking technology is concentrating in the commercial catering segment where consistency and labor reduction justify higher equipment outlays.
The Egyptian Organization for Standardization and Quality enforces mandatory energy-efficiency labeling and electrical safety certification for imported and domestically assembled microwave ovens, directly shaping product eligibility for government-procured institutional canteen contracts. Customs tariff structures administered by the Ministry of Finance and Trade influence landed costs for fully assembled versus knocked-down kits, affecting manufacturer localization decisions. Stakeholders must monitor evolving local-content requirements and electricity tariff reforms that could alter total-cost-of-ownership calculations for energy-intensive cooking appliances across Egyptian residential and commercial buyer segments.
Market Dynamics
The Egyptian microwave category is compressing around energy-efficiency mandates from the Egyptian Organization for Standardization and Quality, which now gate institutional procurement and reshape manufacturer localization calculus.
Growth Catalysts
- New Administrative Capital construction:Residential tower developments along the corridor are specifying built-in microwave configurations as standard kitchen fitments, creating captive demand for appliance vendors with developer relationships.
- Energy-efficiency labeling:Mandatory Egyptian Organization for Standardization and Quality certification for government canteen contracts is filtering substandard imports and rewarding localized assembly operations.
- Convection functionality:Middle-class households in Greater Cairo are upgrading from solo units to multi-function models capable of baking and grilling without full oven investment.
Market Restraints
- Import tariff volatility:Ministry of Finance and Trade administered customs structures create landed cost uncertainty for fully assembled versus knocked-down kit configurations.
- Electricity tariff exposure:Egypt's ongoing electricity subsidy reforms alter total-cost-of-ownership calculations for high-wattage cooking appliances across price-sensitive buyer segments.
- Magnetron supply concentration:Core component sourcing remains concentrated among East Asian suppliers, exposing Egyptian assemblers to freight cost spikes and currency mismatch risks.
Strategic Opportunities
- Alexandria secondary-city penetration:Appliance upgrade cycles in Egypt's second metropolitan center lag Cairo by several years, offering volume expansion for mid-tier convection models.
- Foodservice sensor integration:Commercial catering operators are adopting humidity-sensing and weight-based cooking automation to reduce labor dependency and portion inconsistency.
- Local-content incentives:Evolving domestic assembly requirements create first-mover advantage for manufacturers establishing knocked-down kit operations ahead of tariff preference thresholds.
Industry Challenges
- Certification timeline compression:Egyptian Organization for Standardization and Quality electrical safety testing queues are extending lead times for new model introductions during peak procurement windows.
- Technical service network gaps:Inverter technology and sensor-equipped units require specialized repair capabilities that remain scarce outside Greater Cairo and Alexandria.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Microwave Ovens Market |
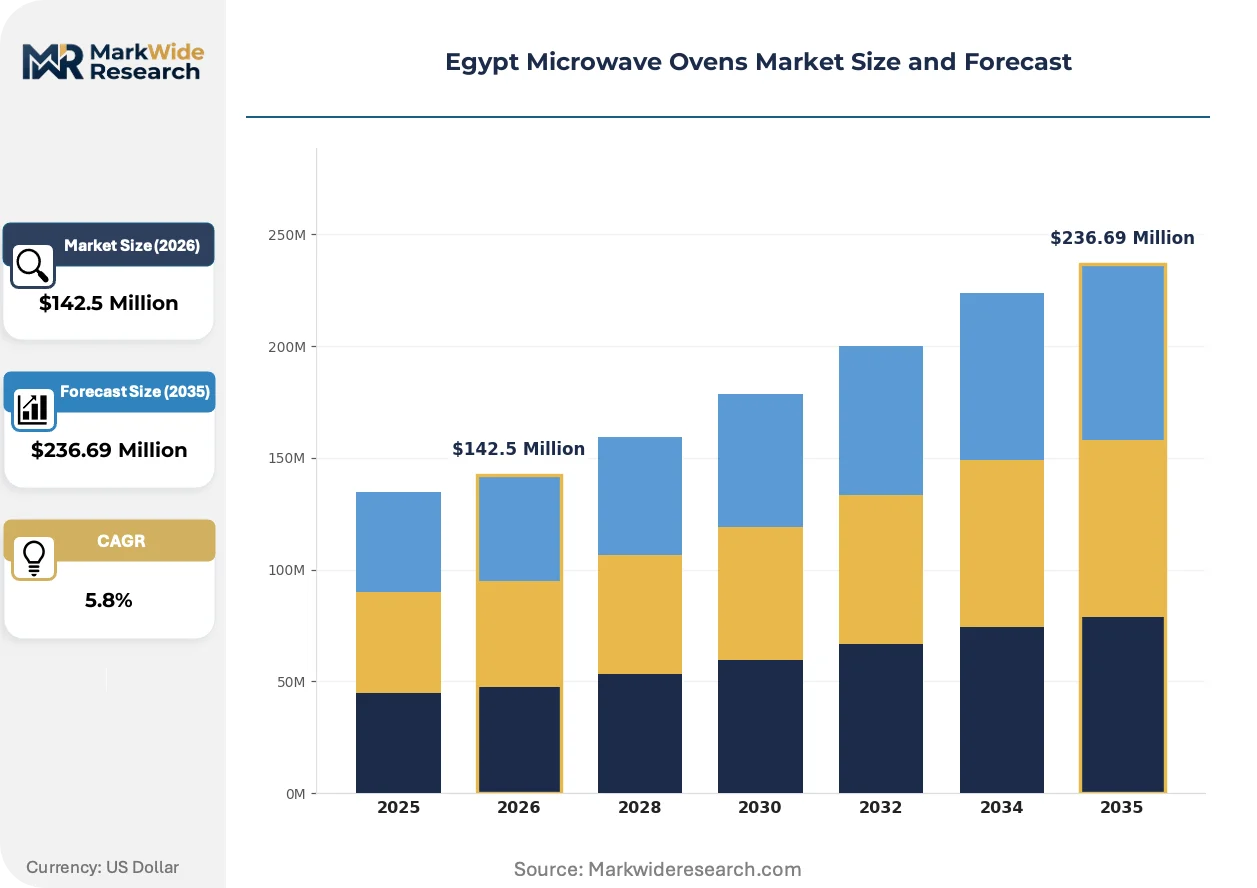
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solo Microwave, Grill Microwave, Convection Microwave, Over-the-Range Microwave, Built-in Microwave Technology: Inverter Technology, Steam Technology, Sensor Cooking, Turbo Defrost, Charcoal Heating Application: Residential Kitchens, Commercial Catering, Institutional Canteens, Food Trucks, Bakery Outlets Distribution Channel: Specialty Stores, E-Commerce Platforms, Electronics Retailers, Hypermarkets, Direct Sales |
| Companies Covered | Toshiba, Castle, Samsung, Panasonic Corporation, Ariston, LG Electronics, Hoover, Whirlpool Corporation, Sharp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Microwave Ovens Market Shifts & Advancements
Technology trajectories in the Egyptian microwave market are diverging between premium feature integration and cost-engineered simplification. Regulatory pressure and buyer sophistication are accelerating this split.
Inverter power delivery systems are replacing traditional transformer-based architectures in upper-mid segment offerings. Cairo and Alexandria residential buyers are specifying these units for precise temperature control and reduced energy waste. The technology is bifurcating the category into precision-cooking premium tiers and basic reheating economy tiers.
Egyptian Organization for Standardization and Quality mandatory energy-efficiency labeling now governs both imported and domestically assembled units. The framework is compressing eligibility for government-procured institutional canteen contracts toward certified suppliers. Manufacturers are responding by accelerating local assembly investments to maintain public-sector access.
Foodservice operators are unbundling after-sales service from equipment purchase, contracting independent technical providers for maintenance coverage. This procurement model is displacing manufacturer-captive service agreements in Alexandria hotel and catering chains. The shift is most visible in commercial segments where uptime guarantees outweigh brand loyalty.
Egypt Microwave Ovens Market Segmentation
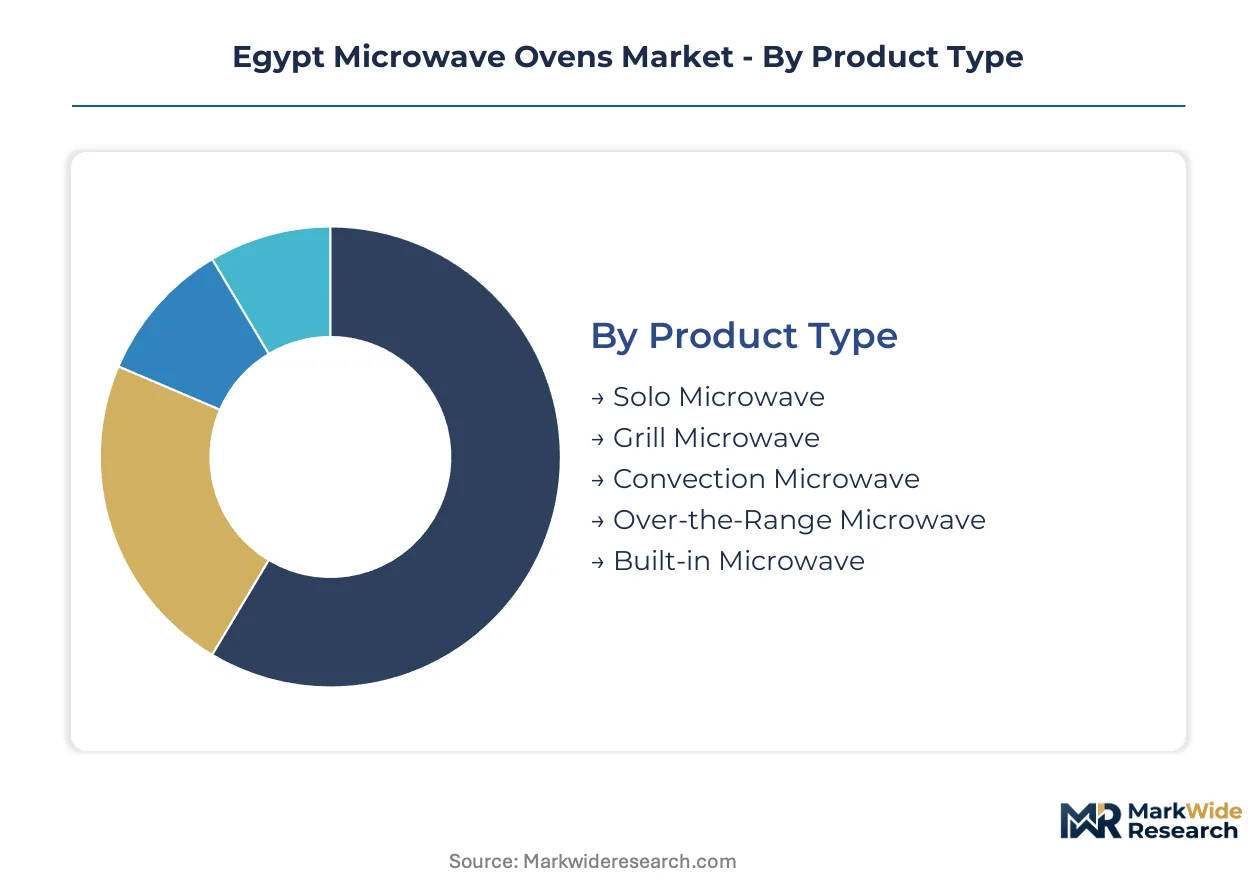
Microwave oven segmentation in Egypt tracks divergent upgrade paths across Greater Cairo's middle-class households and Alexandria's lagging replacement cycles. Channel specialization and regulatory certification requirements fragment procurement patterns between retail-driven residential demand and institutional tender processes.
Product Type:
Channel flows split sharply: built-in and over-the-range units move through developer-direct procurement for New Administrative Capital residential towers, while solo and grill models dominate electronics retailers and hypermarkets serving replacement demand.
- Convection Microwave:Combines radiant heating with forced-air circulation for baking and roasting functions in a single cavity. Demand concentrates in Greater Cairo middle-class households upgrading from basic solo units amid space constraints in urban apartments. The Egyptian Organization for Standardization and Quality energy-efficiency labeling rewards inverter-equipped convection models with preferred procurement status for government canteen contracts.
- Built-in Microwave:Designed for seamless integration into kitchen cabinetry with standardized trim kits and ventilation interfaces. Developer relationships along the New Administrative Capital corridor specify these as standard fitments in residential tower deliveries, creating captive volume for vendors with construction-channel presence. Alexandria's secondary market lags this transition by several upgrade cycles.
- Solo Microwave:Basic magnetron-based units limited to reheating and simple defrosting functions.
- Grill Microwave:Adds quartz or metal-sheath heating elements for surface browning without full oven investment.
- Over-the-Range Microwave:Combines cooking cavity with integrated ventilation hood for space-constrained kitchen layouts.
By volume, Solo Microwave leads. By growth pace, Built-in Microwave is climbing the fastest.
Technology:
Cost tier stratification separates precision-engineered inverter and sensor systems commanding premium positioning from simplified turbo defrost and charcoal heating architectures targeting price-sensitive segments.
- Inverter Technology:Replaces conventional transformer power delivery with continuous variable-output magnetron control. Samsung anchors this tier in Cairo and Alexandria retail channels where precise temperature modulation justifies price premiums. The technology bifurcates procurement between precision-cooking residential buyers and basic reheating economy segments.
- Sensor Cooking:Deploys humidity and weight detection algorithms to automate power adjustment and timing termination. Commercial catering operators in Alexandria hotel chains adopt these units to reduce labor dependency and standardize portion consistency across high-volume service windows.
- Steam Technology:Integrates water reservoir and vapor injection for moisture-retentive reheating.
- Turbo Defrost:Accelerates thawing cycles through pulsed low-power delivery sequences.
- Charcoal Heating:Utilizes porous ceramic elements for radiant browning in grill-configured units.
By installed base, Turbo Defrost dominates. By adoption velocity, Sensor Cooking is expanding most quickly.
Application:
Volume concentration sits with residential kitchens, while margin extraction concentrates in commercial catering where uptime guarantees and service unbundling reshape procurement economics.
- Residential Kitchens:Urban households in Greater Cairo and Alexandria drive replacement cycles from solo to multi-function units. Space constraints in high-rise apartments favor convection and grill configurations that eliminate separate oven requirements.
- Commercial Catering:Hotel and restaurant chains in Alexandria are unbundling after-sales service from equipment purchase, contracting independent technical providers for maintenance coverage. This procurement model displaces manufacturer-captive service agreements where uptime guarantees outweigh brand loyalty.
- Institutional Canteens:Government-procured facilities requiring Egyptian Organization for Standardization and Quality certification for contract eligibility.
- Food Trucks:Mobile operators prioritizing compact footprint and generator-compatible power draw.
- Bakery Outlets:Small-format operations supplementing primary oven capacity with convection microwave backup.
By unit shipments, Residential Kitchens leads. By margin expansion, Commercial Catering is gaining share fastest.
Distribution Channel:
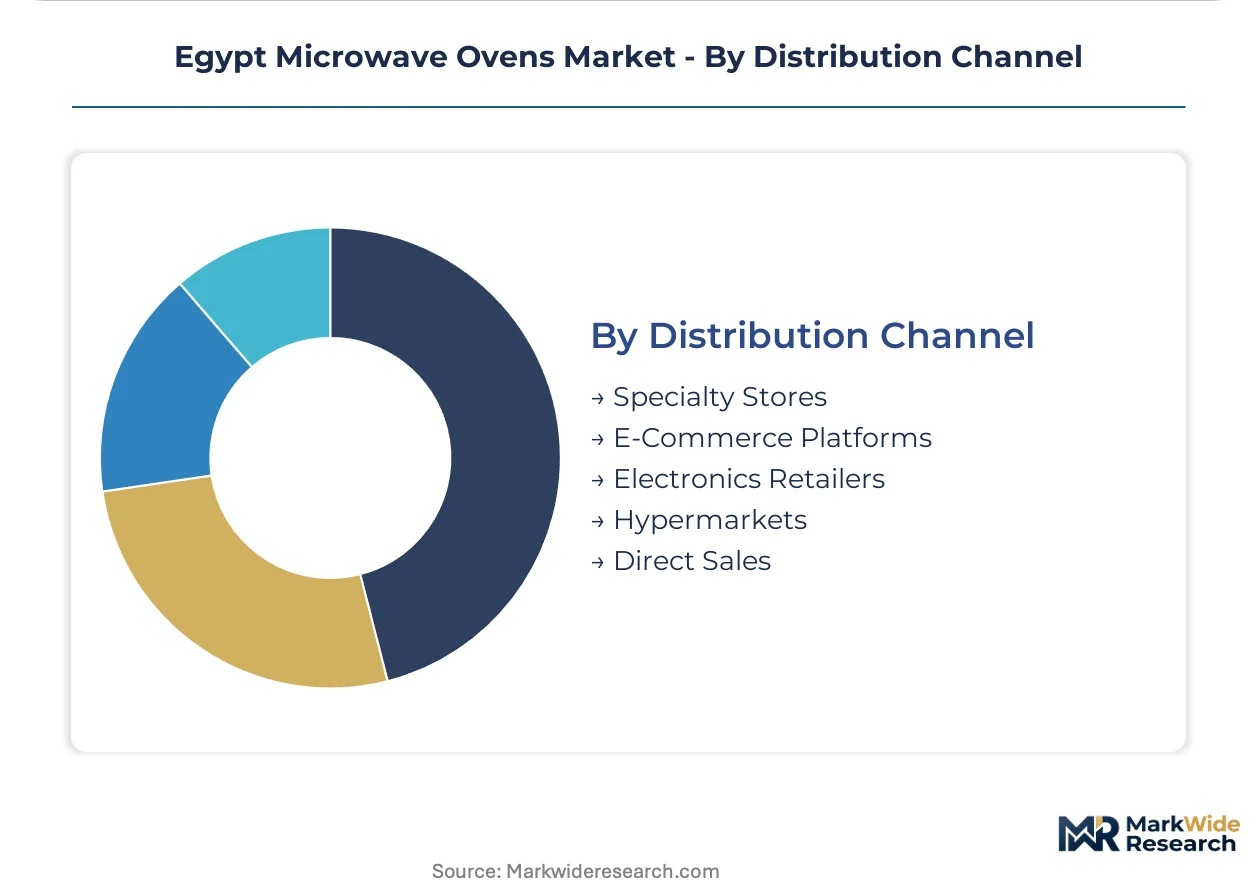
Geography determines channel dominance: electronics retailers and hypermarkets capture Cairo's dense urban foot traffic, while e-commerce platforms penetrate Alexandria's dispersed secondary market with delivery logistics.
- Electronics Retailers:Multi-brand storefronts in Greater Cairo shopping districts facilitate hands-on comparison of inverter technology demonstrations. Samsung and LG maintain dedicated display allocations for upper-mid segment convection models.
- E-Commerce Platforms:Digital procurement accelerates in Alexandria where physical specialty store presence remains thinner. Extended warranty programs and localized assembly claims differentiate online listings.
- Specialty Stores:Single-brand flagship locations emphasizing premium built-in configurations.
- Hypermarkets:High-volume solo and grill unit sales through Carrefour and Spinneys networks.
- Direct Sales:Developer-channel procurement for New Administrative Capital residential fitments.
By transaction volume, Electronics Retailers leads. By channel growth, E-Commerce Platforms shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's microwave oven trade flows reflect a heavy import dependency with limited domestic assembly capacity concentrated in Greater Cairo industrial zones. The country's customs tariff administration shapes landed cost structures for fully assembled versus knocked-down kit configurations.
Greater Cairo
Urban households in Nasr City and New Cairo drive convection microwave upgrades amid space-constrained apartment layouts. The Egyptian Organization for Standardization and Quality enforces mandatory energy-efficiency labeling that gates government canteen contract eligibility. Industrial assembly operations in 10th of Ramadan City and Obour City process knocked-down kits for localized production.
Alexandria
Secondary-city replacement cycles lag Cairo by several years, creating volume expansion potential for mid-tier grill and convection models. Alexandria's port infrastructure handles bulk import arrivals for redistribution to Delta region retail networks. The city's hotel and catering chains are unbundling after-sales service from equipment procurement, contracting independent technical providers.
New Administrative Capital
Residential tower developments along the corridor specify built-in microwave configurations as standard kitchen fitments, generating captive demand for appliance vendors with construction-channel relationships. Developer-direct procurement bypasses traditional retail channels. The area's master-planned infrastructure accommodates integrated appliance specifications from project inception.
Suez Canal Economic Zone
Logistics advantages attract regional distribution hub operations for multinational appliance brands serving Middle East and African markets. Customs facilitation within the zone reduces clearance timelines for imported component shipments. Assembly facilities in Ismailia and Port Said leverage proximity to container terminals for re-export configurations.
Upper Egypt
Price-sensitive demand concentrates in basic solo microwave units through hypermarket networks in Assiut and Sohag. Electricity tariff exposure alters total-cost-of-ownership calculations for high-wattage appliances across lower-income buyer segments. Retail penetration remains thinner than northern governorates, with e-commerce platforms filling distribution gaps.
Egypt Microwave Ovens Market Competitive Landscape
Listed leaders compete with private specialists across brand recognition and distribution depth in Egypt's microwave oven category. Samsung and LG Electronics anchor the upper-mid segment through electronics retailer presence, while Whirlpool Corporation pursues developer-channel positioning. Three strategic archetypes dominate: multinational electronics conglomerates with inverter technology portfolios, appliance specialists emphasizing localized assembly, and construction-channel integrators targeting built-in specifications. Competitive moves concentrate on strategic partnerships with New Administrative Capital developers and portfolio diversification into sensor-equipped commercial units.
Among multinational electronics conglomerates, Samsung and LG Electronics exemplify the inverter-technology tier competing for Greater Cairo and Alexandria retail presence. Whirlpool Corporation occupies a position within the construction-channel integrator archetype, with its built-in configurations specified in residential tower developments. Panasonic Corporation and Sharp represent additional Japanese-origin players competing across mid-tier convection and grill segments. Toshiba anchors a position in the premium-feature tier with advanced cooking automation capabilities.
| Leading Market Players |
|---|
| Toshiba |
| Castle |
| Samsung |
| Panasonic Corporation |
| Ariston |
| LG Electronics |
| Hoover |
| Whirlpool Corporation |
| Sharp |
| Others |
Supply & Pricing Matrix
Egyptian Organization for Standardization and Quality certification gates both supplier qualification and price differentiation in microwave procurement, compressing margins for uncertified imports while rewarding localized assemblers with institutional contract access. This dual-gate mechanism forces manufacturers to absorb compliance costs upfront or exit the premium tier entirely.
Pricing Analysis
Developer-direct procurement anchors pricing structures for built-in configurations along the New Administrative Capital corridor, where volume commitments and specification bundling override spot-market dynamics. Price differentiation rests on inverter technology certification and after-sales service bundling rather than raw feature counts. Cost compression in basic solo units intensifies as electricity tariff reforms squeeze total-cost-of-ownership calculations for price-sensitive Upper Egypt households. Residential retail buyers in Greater Cairo exhibit lowest price sensitivity for convection-equipped premium tiers.
Supply Chain Analysis
China and South Korea anchor magnetron and inverter component fabrication, feeding knocked-down kit assembly operations in 10th of Ramadan City and Obour City industrial zones. Egyptian assemblers draw from East Asian magnetron suppliers, copper winding substrates, and ceramic cavity insulation materials. Single-source vulnerability concentrates in magnetron sourcing, exposing localized production to freight cost spikes and currency mismatch risks. Distribution runs through Alexandria port infrastructure for bulk import arrivals, with secondary redistribution to Delta region retail networks and direct developer-channel delivery for New Administrative Capital fitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Independent technical service contracting expands faster than hardware shipments in Alexandria's hotel and catering chains, creating a recurring-revenue layer that outpaces equipment replacement cycles. This service-attach dynamic restructures procurement economics toward uptime guarantees and maintenance unbundling.
For Market Incumbents: Shield installed base relationships by embedding sensor-equipped units with multi-year service contracts in Alexandria commercial catering accounts. Accelerate certification investment to maintain Egyptian Organization for Standardization and Quality eligibility as testing queues extend. Deepen backward integration into knocked-down kit assembly ahead of local-content preference thresholds to defend margin position against tariff-exposed fully assembled imports.
For New Entrants and Emerging Players: Egyptian Organization for Standardization and Quality fast-track certification unlocks government canteen contract eligibility previously closed to uncertified suppliers. Target Alexandria's lagging replacement cycles with mid-tier grill and convection models priced below Samsung and LG retail positioning. Pursue e-commerce platform partnerships with extended warranty programs to bypass thin electronics retailer presence in secondary Delta cities.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed appliance distributors holding exclusive developer relationships along the New Administrative Capital corridor. Long-term viability hinges on construction-channel lock-in duration and service network density rather than brand equity alone. Monitor electricity tariff reform announcements as the inflection signal for premium-tier demand elasticity shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Local-Content Assembly Investment | Knocked-down kit operations in 10th of Ramadan City secure tariff preference for government procurement eligibility. |
| Sensor Technology Integration | Humidity-sensing automation reduces labor dependency in Alexandria hotel chain catering operations. |
| Developer-Channel Partnership | Exclusive fitment specifications in New Administrative Capital towers create captive volume through construction cycle. |
| After-Sales Service Unbundling | Independent technical contracting displaces manufacturer-captive agreements where uptime guarantees dominate procurement. |
| E-Commerce Platform Expansion | Digital penetration fills distribution gaps in Alexandria and Upper Egypt with delivery-logistics coverage. |
Research Methodology
Initial hypotheses were tested against primary input from appliance category managers at electronics retailers, procurement leads at New Administrative Capital developers, technical service heads at Alexandria hotel chains, and regulatory affairs specialists at Egyptian Organization for Standardization and Quality, then refined against secondary validation from customs tariff records, energy-efficiency certification databases, construction-sector procurement filings, and retail audit data. Bottom-up channel volume estimates triangulated with top-down macroeconomic consumption projections.
Variance decomposition across product type, technology tier, application segment, and distribution channel structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Electricity tariff reform scenarios and local-content requirement phase-ins served as scenario inputs alongside construction pipeline data for New Administrative Capital residential towers.
The analysis sits within stated boundaries; outcomes outside sustained construction activity in the New Administrative Capital corridor or accelerated electricity subsidy reform would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and magnetron supply continuity. Recalibration cycles align with material shifts in regulatory enforcement intensity and construction-sector procurement windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Japan Massage Equipment Market
Appliances
Fully Integrated Dishwasher Market
Appliances
Minibar Refrigerators Market
Appliances
Sanitary Towel Machine Market
Appliances
Domestic Food Preparation Appliances Market
Appliances
Smart Washing Machine Market
Appliances
Saudi Arabia Dishwasher Market
Appliances
Middle East and Africa Commercial Dishwashers Market
Appliances
Colombia Laundry Appliances Market
Appliances
US Electric Rice Cooker Market
Appliances
Germany Compact Dishwasher Market
Appliances
Electric Rice Cooker Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
Kuwait Dishwasher Market
Appliances
Turkey Washing Machine Market