
 Bathroom Heaters Market | 2026-2036
Bathroom Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Bathroom Heaters Market Outlook
The bathroom heater category is restructuring around a sharp split between premium infrared and ceramic systems with smart controls and basic convection units sold on price. Panasonic Corporation leverages its sensor technology and home automation ecosystem to anchor the premium segment. Stiebel Eltron competes through German engineering credibility and deep specialization in electric heating systems. Glen Dimplex Group sustains broad manufacturing scale across both mid-range and entry-level product lines.
Bathroom heaters are enclosed-space thermal appliances designed to raise ambient temperature in wet-room environments, typically rated between 500W and 2,400W output with IPX4 minimum ingress protection against water spray. Manufacturers form heating elements from aluminum oxide, quartz tubes, or PTC ceramic cores, then enclose them in corrosion-resistant housings for safe operation in humid conditions. Wall-mounted units dominate residential installations where permanent fixture integration matters, while portable models capture rental and seasonal demand with plug-and-move flexibility. Infrared technology leads growth trajectories as consumers prioritize instant radiant warmth and reduced air circulation in compact bathrooms.
EPA ENERGY STAR specifications and EU Ecodesign Directive efficiency thresholds compel manufacturers to redesign heating elements and control systems for lower standby consumption. The EU F-Gas Regulation and REACH chemical restrictions further constrain refrigerant-based and coated component choices in imported products. Stakeholders must monitor evolving efficiency tier thresholds and smart-home interoperability standards as these rules increasingly determine market access and product positioning.
Market Dynamics
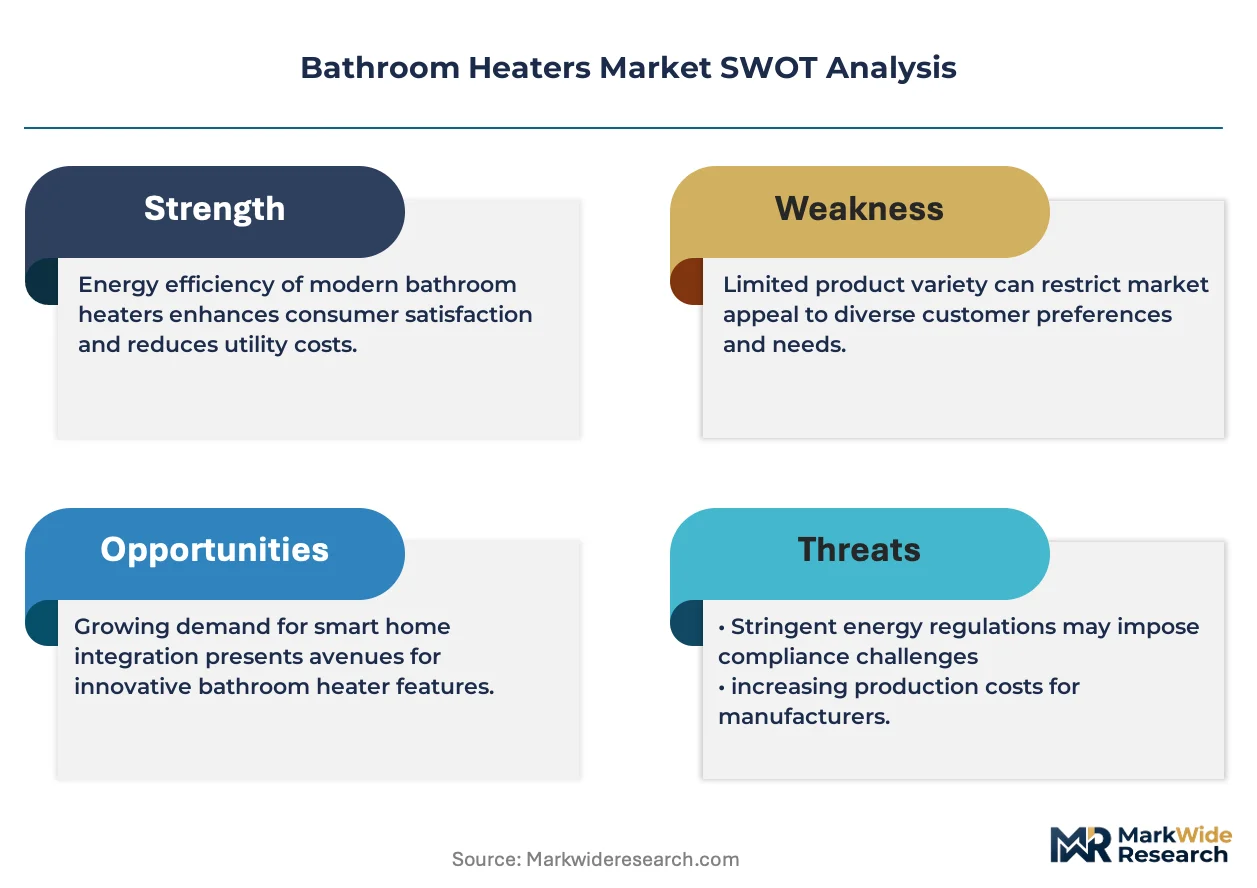
The bathroom heater market is restructuring around a technology bifurcation where infrared radiant systems with smart controls command premium positioning while basic convection units compete on acquisition cost alone.
Growth Catalysts
- EU Ecodesign Directive:Efficiency mandates from Brussels compel manufacturers to redesign heating elements for lower standby consumption, accelerating replacement cycles across German and French residential renovation projects.
- Infrared technology penetration:Quartz tube and carbon fiber elements deliver instant radiant warmth with minimal air circulation, appealing to compact bathroom installations where space constraints dominate buyer preference.
- Residential renovation spending:North American and European homeowners allocate discretionary budgets to bathroom comfort upgrades, prioritizing fixture integration and permanent installation over portable alternatives.
Market Restraints
- Aluminum oxide ceramic cost volatility:Heating element substrates face input price pressure from energy-intensive kiln processing, compressing margins for mid-range PTC ceramic core manufacturers.
- Wall-mounted installation concentration:Permanent fixture demand ties revenue to construction and renovation cycles, exposing suppliers to housing market downturns in Germany and the United States.
- EU F-Gas Regulation constraints:Refrigerant-based heat pump bathroom heaters face import restrictions and component redesign requirements, limiting product line expansion for Asian manufacturers.
Strategic Opportunities
- China urban bathroom upgrade wave:Tier-1 and Tier-2 city apartment renovations create demand for IPX4-rated infrared panels with minimalist aesthetic integration.
- Smart home interoperability:Matter protocol adoption enables voice and app control integration, opening premium positioning for manufacturers with sensor technology capabilities.
- India residential electrification:Grid expansion and bathroom appliance adoption in metropolitan clusters present first-mover advantage for compact wall-mounted convection units.
Industry Challenges
- IPX4 certification timeline compression:Water ingress testing protocols for wet-room electrical safety extend product development cycles, delaying market entry for new entrants.
- Legacy thermostat integration complexity:Smart control retrofits must interface with existing home automation infrastructure, requiring firmware customization and technical support capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bathroom Heaters Market |
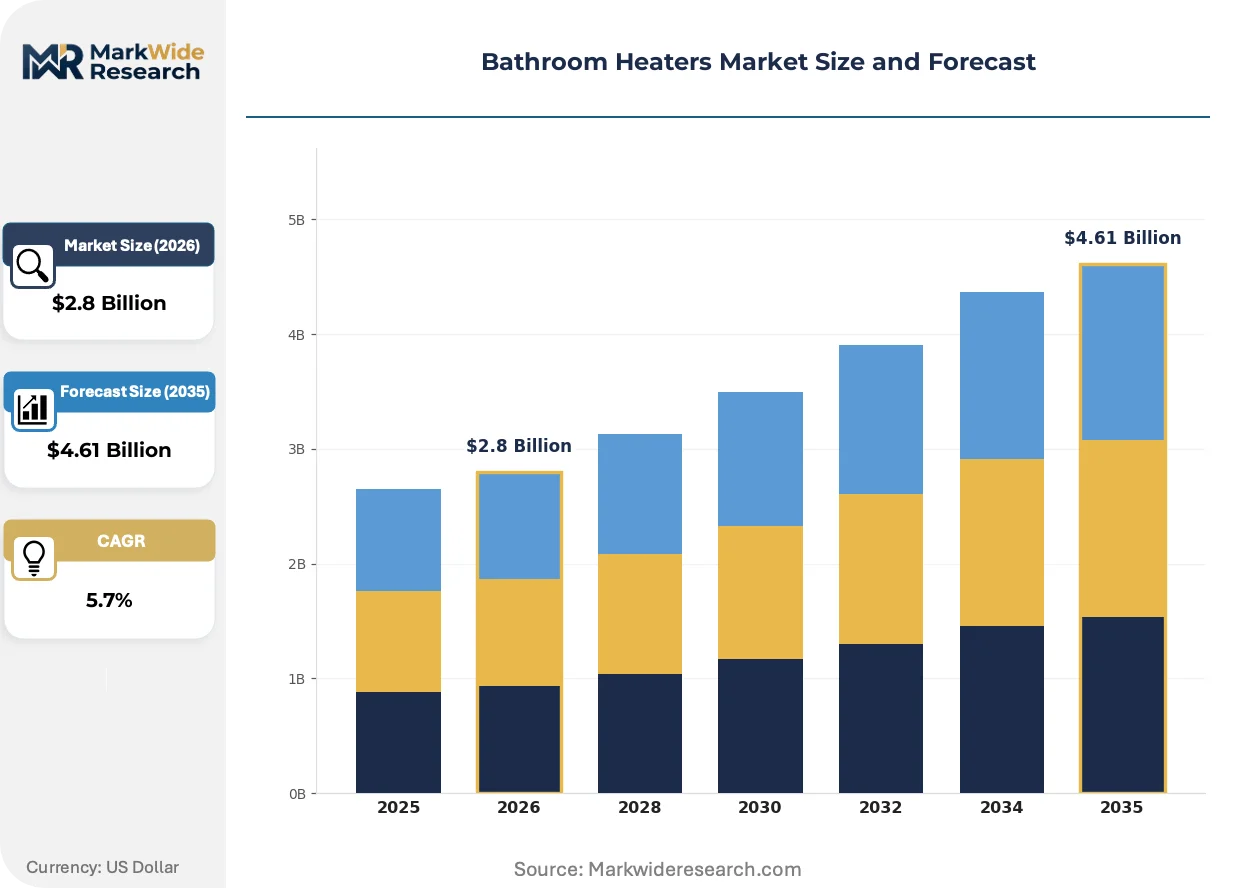
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Ceiling-Mounted, Portable, Radiant Technology: Electric, Gas, Infrared, Hydroponic End User: Residential, Commercial, Hospitality, Healthcare Installation Type: Fixed, Temporary, Integrated, Standalone |
| Companies Covered | Panasonic Corporation, Stiebel Eltron, Glen Dimplex Group, Honeywell International Inc., Aupu, OPPLE, Philips, Lasko Products LLC, Broan-NuTone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bathroom Heaters Market Strategic Shifts
Product development in bathroom heating is accelerating around three vectors: sensor-enabled climate control, regulatory efficiency thresholds, and shifting channel economics that favor direct manufacturer engagement with renovation contractors.
Carbon fiber infrared panels is converging with occupancy-sensing algorithms to deliver targeted warmth only when bathrooms are occupied. High-end residential developers in Germany and the Netherlands specify these systems for new construction, compressing demand for always-on convection units and enabling premium pricing for intelligent thermal management.
EPA ENERGY STAR specifications for electric space heaters are tightening standby power limits, forcing redesigns of control electronics and heating element geometries. Manufacturers serving the United States market must recertify product lines, with wall-mounted infrared systems better positioned to meet wattage-per-square-foot efficiency thresholds than legacy convection designs.
Renovation contractors now specify bathroom heaters directly rather than deferring to homeowner selection, consolidating purchase influence into professional channels. This pattern concentrates in North American and European markets where whole-bathroom remodeling projects dominate, displacing retail showroom selection and favoring manufacturers with trade-focused sales organizations and specification support tools.
Bathroom Heaters Market Segmentation
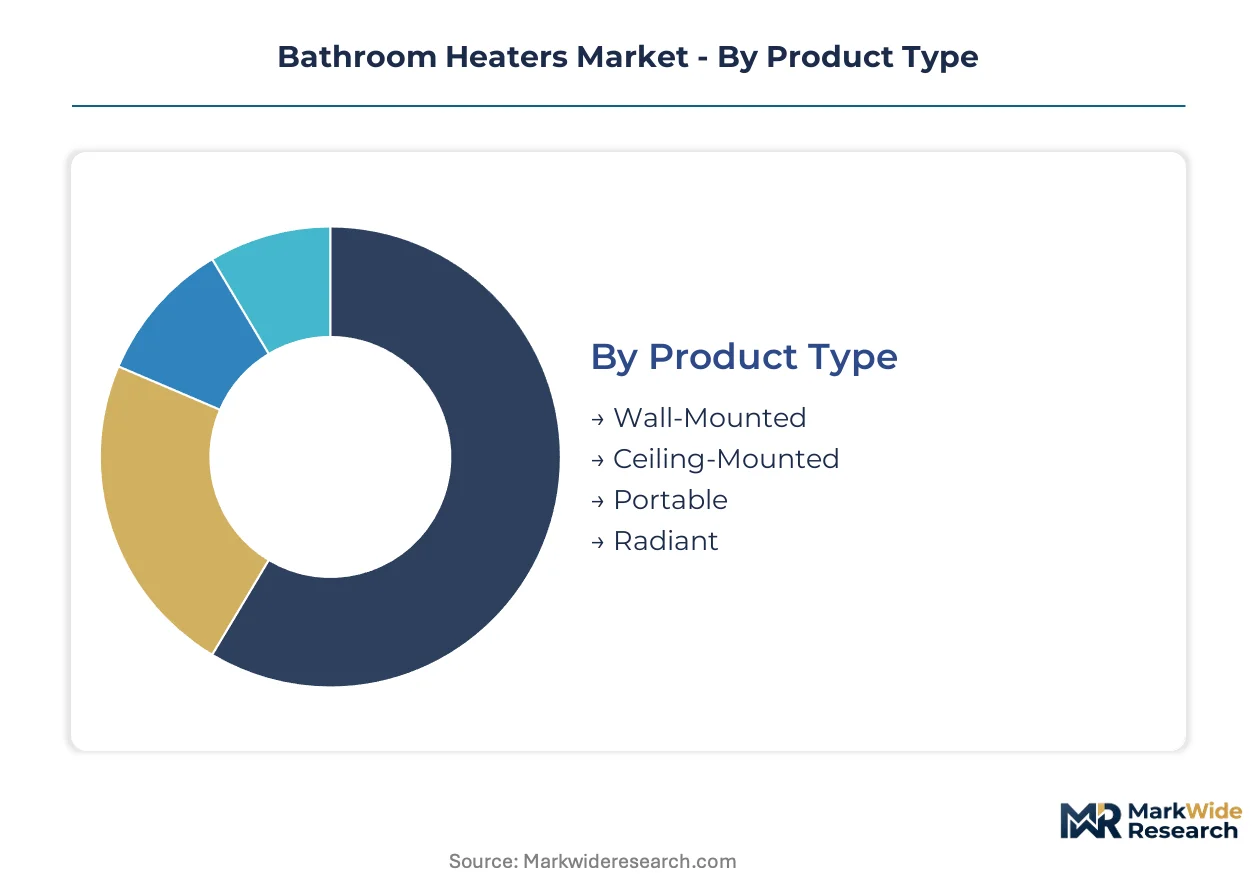
Bathroom heater procurement decisions split across technical specifications, energy infrastructure compatibility, and installation permanence. Manufacturers align R&D and distribution strategies to these axes because purchase criteria diverge sharply between renovation contractors specifying permanent fixtures and consumers seeking seasonal flexibility.
Product Type:
Wall-mounted units anchor residential renovation specifications where permanent fixture integration drives contractor preference.
- Wall-Mounted:Aluminum oxide or PTC ceramic heating elements enclosed in IPX4-rated housings mount on vertical surfaces above towel rails or vanity zones. German and French residential renovation projects specify these for permanent thermal comfort upgrades, with contractors prioritizing hardwired electrical integration over plug flexibility.
- Ceiling-Mounted:Infrared panels and recessed heating modules suspend overhead to preserve wall space in compact bathrooms. Demand concentrates in Dutch and Belgian new construction where minimalist aesthetic integration overrides conventional fixture placement, with developers specifying carbon fiber elements for instant radiant output.
- Portable:Plug-in convection and ceramic units with IPX4 housings serve rental properties and seasonal heating needs. These units capture price-sensitive demand in United Kingdom multi-tenant housing.
- Radiant:Dedicated infrared emitters using quartz tubes or carbon fiber deliver targeted warmth without air circulation. These systems gain specification in Austrian and Swiss alpine residential projects where draft-free operation matters.
Wall-mounted leads on scale; radiant leads on momentum.
Technology:
Energy source selection depends on grid infrastructure maturity, gas network availability, and efficiency regulation thresholds.
- Electric:Resistive and ceramic element systems dominate markets with reliable grid infrastructure. United States residential installations favor these for straightforward retrofit compatibility with existing 240V bathroom circuits.
- Gas:Flued and flueless combustion units serve regions with established natural gas distribution. Italian and Spanish residential markets maintain demand where gas infrastructure predates electric heating adoption.
- Infrared:Quartz tube and carbon fiber radiant technologies deliver instant warmth with minimal thermal lag. These systems expand most quickly in German and Austrian markets where EU Ecodesign Directive efficiency thresholds favor low standby consumption.
- Hydroponic:Wet-system towel rails and radiator-style units integrate with central heating circuits. United Kingdom renovation projects specify these for aesthetic continuity with traditional bathroom fixtures.
Electric leads on scale; infrared leads on momentum.
End User:
Application context determines safety certification requirements, duty cycle expectations, and control system complexity.
- Residential:Single-family and multi-unit housing drives volume demand for IPX4-rated units with occupancy-based controls. Chinese Tier-1 city apartment renovations specify minimalist infrared panels.
- Commercial:Office buildings and retail facilities require durable heating solutions with centralized building management integration. These installations prioritize thermostat interoperability over consumer-facing smart features.
- Hospitality:Hotels and resorts demand rapid heat-up capability and aesthetic refinement for guest bathroom environments. Premium properties in Dubai and Singapore specify designer-integrated infrared systems.
- Healthcare:Hospitals and aged-care facilities require anti-ligature housings and infection-control surface finishes. These specifications concentrate in Japanese and Australian institutional procurement.
Residential leads on scale; hospitality leads on momentum.
Installation Type:
Permanence of mounting determines distribution channel economics and technical support requirements.
- Fixed:Hardwired wall and ceiling units require licensed electrical installation. These dominate German and Austrian markets where regulatory compliance mandates professional fitting.
- Temporary:Plug-in portable units with freestanding or clamp mounting serve seasonal and rental applications. These capture demand in United Kingdom student housing and short-term rental properties.
- Integrated:Heating modules built into vanity units, mirror cabinets, or shower enclosures. Italian bathroom furniture manufacturers specify these for complete wet-room system sales.
- Standalone:Self-contained tower and floor units with independent controls. These serve utility bathrooms and secondary spaces in North American suburban homes.
Fixed leads on scale; integrated leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's renovation-driven specification of infrared bathroom heaters contrasts with China's urban apartment upgrade wave, while the United States maintains steady retrofit demand through contractor channels. Each market shapes product standards through distinct regulatory and infrastructure conditions.
Germany
The EU Ecodesign Directive compels manufacturers to redesign heating elements for minimal standby consumption, accelerating replacement cycles across residential renovation projects. REACH chemical restrictions constrain coated component choices in imported products. Bavarian housing cooperatives specify carbon fiber infrared panels for new construction in Munich and Nuremberg.
United States
EPA ENERGY STAR specifications tighten standby power limits for electric space heaters, forcing recertification of product lines serving the market. The IRA's residential energy efficiency incentives influence contractor specification behavior. Pacific Northwest metropolitan clusters prioritize hardwired wall-mounted units for bathroom remodeling in Seattle and Portland.
China
Tier-1 and Tier-2 city apartment renovations create demand for IPX4-rated infrared panels with minimalist aesthetic integration. The country's national standards body enforces electrical safety certification for wet-room appliances. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou supply compact wall-mounted units for domestic and export markets.
United Kingdom
Multi-tenant housing and student accommodation sustain demand for portable plug-in convection units with seasonal flexibility. Building regulations mandate minimum energy efficiency standards for fixed electrical heating. Greater London renovation contractors specify hydroponic towel rails for aesthetic continuity with traditional bathroom fixtures.
India
Grid expansion and bathroom appliance adoption in metropolitan clusters present first-mover positioning for compact wall-mounted convection units. The Bureau of Indian Standards enforces electrical safety certification for humid-environment appliances. Maharashtra's Mumbai-Pune corridor drives specification of entry-level fixed installations in new residential towers.
Bathroom Heaters Market Competitive Environment
Top-tier vendors anchor premium infrared and smart-control segments, while mid-range specialists compete on manufacturing scale and regional distribution density. The market structure exhibits moderate consolidation around heating technology specialists and diversified appliance conglomerates. Two strategic archetypes dominate: sensor-technology integrators leveraging home automation ecosystems, and engineering-focused specialists commanding specification credibility. Competitive moves concentrate on smart-home interoperability certification and trade-channel specification support tools.
Among diversified appliance conglomerates, Panasonic Corporation and Honeywell International Inc. occupy positions spanning premium sensor-enabled systems and broad distribution reach. Stiebel Eltron exemplifies the engineering-specialist archetype with concentrated expertise in electric heating systems. Glen Dimplex Group represents manufacturing-scale players sustaining presence across mid-range and entry-level product lines.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Stiebel Eltron |
| Glen Dimplex Group |
| Honeywell International Inc. |
| Aupu |
| OPPLE |
| Philips |
| Lasko Products LLC |
| Broan-NuTone |
| Others |
Value Chain & Pricing Dynamics
Heating element engineering talent concentrates in Bavaria and Baden-Württemberg, where labor-cost differentials between German precision manufacturing and Asian assembly operations drive 40-60% pricing-tier spreads between premium infrared systems and entry-level convection units.
Pricing Analysis
The bundled-vs-unbundled service split separates contractor-specified fixed installations with integrated smart controls from portable retail units sold without installation support. Three-tier pricing structure across premium, standard, and economy levels reflects IPX4 certification grade, carbon fiber element quality, and Matter protocol compatibility. Pricing pressure stems from aluminum oxide ceramic substrate cost volatility in energy-intensive kiln processing. Rental property managers and student housing operators exhibit highest price sensitivity, while German housing cooperatives prioritize engineering credibility over acquisition cost.
Supply Chain Analysis
Reverse-logistics flows for warranty returns and refurbishment concentrate in Yangtze River Delta manufacturing hubs, where defective heating elements undergo ceramic core reclamation. Component sourcing draws from China for PTC ceramic cores, Germany for precision sensor modules, and Japan for quartz tube substrates. Single-source vulnerability persists in carbon fiber heating element supply from specialized Japanese manufacturers. Distribution runs through renovation contractor specification channels in North America and Europe, displacing traditional retail showroom networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Ecodesign Directive efficiency tier escalations force replacement cycles regardless of economic conditions, embedding demand elasticity directly into compliance deadlines.
For Market Incumbents: Anticipate margin compression from Asian manufacturers achieving IPX4 certification parity by investing in captive sensor technology development and Matter protocol certification ahead of interoperability mandates. Prioritize backward integration into ceramic heating element production to offset aluminum oxide cost volatility. Defend specification relationships with German and Austrian renovation contractors through dedicated trade-channel technical support teams. For New Entrants and Emerging Players: Enter via India's Maharashtra corridor where grid expansion and bathroom appliance first-adoption creates unserved demand for compact wall-mounted convection units below incumbent price floors. Target Tier-2 Chinese city apartment renovations seeking minimalist infrared panels without premium German branding. Pursue direct-to-contractor distribution bypassing established retail channels entirely. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-range manufacturing-scale players lacking smart-control differentiation but sustaining cash flow from hydroponic towel rail heritage lines. Five-to-ten-year viability hinges on regulatory efficiency tier escalation continuing to obsolete legacy convection inventory. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for heat pump bathroom heater import restriction severity.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Interoperability Certification | Matter protocol compliance opens specification access to Apple HomeKit and Google Nest ecosystems. |
| Backward Integration into Ceramic Elements | In-house PTC core production insulates margins from aluminum oxide kiln energy cost spikes. |
| Renovation Contractor Channel Development | Direct specification relationships with German housing cooperatives displace retail distribution economics. |
| Carbon Fiber Heating Element R&D | Instant radiant output technology captures premium positioning in Dutch minimalist bathroom design. |
| India Market Entry Localization | BIS certification and compact wall-mounted form factors address Mumbai-Pune corridor electrification. |
Study Parameters
Coverage spans Germany, the United States, China, the United Kingdom, and India, with primary inputs from each market's renovation contractor networks, electrical appliance distributors, and regulatory compliance officers. The research combined structured interviews with heating element procurement managers at OEMs, specification engineers at bathroom furniture manufacturers, and certification specialists at testing laboratories with secondary validation from EU Ecodesign Directive implementation reports, EPA ENERGY STAR specifications, and BIS electrical safety standards. Trade data from customs records, SEC 10-K filings of diversified appliance conglomerates, and industry association production statistics supported bottom-up and top-down triangulation.
Rate-of-change decomposition separated volume growth from pricing dynamics across the projection horizon, modeling segmentation dimensions including product type, heating technology, installation permanence, and end-use application. CAGRs were derived from regression analysis against residential renovation spending indices, housing permit data, and regulatory replacement cycle assumptions. Forecast inputs incorporated EU efficiency tier escalation schedules, China urban bathroom upgrade penetration curves, and India grid expansion timelines without year-specific anchoring.
Inputs from regulatory filing databases and trade association production surveys were available through the study window; gaps in real-time contractor specification data introduce uncertainty bands around near-term volume allocations. Forecasts reflect assumptions regarding continued EU Ecodesign Directive enforcement, stable aluminum oxide ceramic supply, and Matter protocol adoption velocity. Practitioners should monitor EU F-Gas Regulation amendment proposals, China GB standards revisions, and India PLI scheme appliance eligibility expansions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Global Vended Laundry Equipment Market
Appliances
North America Tumble Dryers Market
Appliances
Refrigerator Door Seal Market
Appliances
Refrigerator Repair Service Market
Appliances
UAE Microwave Ovens Market
Appliances
United States Microwave Oven Market
Appliances
India Washing Machine Market
Appliances
Smart Ceiling Fan Market
Appliances
Fully Automatic Dishwasher Market
Appliances
Qatar Microwave Ovens Market
Appliances
Qatar Dishwashers Market
Appliances
United States Multi-Functional Oven Market
Appliances
Induction Cooktops Market
Appliances
Residential Vacuum Cleaners Market
Appliances
UAE Dishwasher Market
Appliances
Oman Microwave Ovens Market