
 Qatar Microwave Ovens Market | 2026-2036
Qatar Microwave Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Microwave Ovens Market Analytics
Asset-light leasing models for commercial kitchen equipment is narrowing the competitive field in Qatar's microwave oven sector. Samsung Electronics leverages its regional distribution infrastructure to sustain presence across premium hospitality installations. LG Electronics anchors its position through localized service networks that reduce downtime for commercial end users. Midea Group competes on manufacturing scale, offering cost-efficient units that appeal to budget-conscious residential buyers in Doha's expanding residential zones.
Microwave ovens are electromagnetic appliances operating at 2.45 GHz, utilizing magnetron-generated radiation to excite water molecules and produce thermal energy for food preparation, reheating, and defrosting across domestic and commercial settings. Convection and grill product types command premium positioning in Qatar's hospitality procurement channels, where dual-functionality reduces equipment footprint in space-constrained commercial kitchens. Smart technology integration represents the fastest-growing structural segment, with WiFi-enabled units gaining traction among tech-forward residential consumers in Doha's upscale developments.
Qatar's Ministry of Commerce and Industry enforces mandatory GSO conformity assessment for electrical appliances, while the Qatar General Organization for Standardization and Metrology sets energy efficiency benchmarks that manufacturers must satisfy for market access. Qatar's Civil Defense Authority mandates fire safety certifications for commercial kitchen installations, directly influencing product specification requirements in hotel and restaurant tenders. Stakeholders must monitor evolving smart appliance cybersecurity protocols as connected microwave platforms proliferate in both residential and commercial deployment scenarios.
Market Dynamics
Qatar's hospitality construction pipeline is compressing procurement cycles for commercial kitchen equipment, with operators demanding faster installation timelines and integrated smart functionality to meet compressed hotel opening schedules mandated by Qatar Tourism Authority targets.
Growth Catalysts
- Qatar General Organization for Standardization and Metrology energy benchmarks:New efficiency mandates are forcing equipment upgrades across Doha's hotel clusters, creating replacement demand for compliant convection-grill units.
- Asset-light leasing models:Commercial kitchen operators in Lusail and The Pearl are shifting from ownership to operational leases, expanding addressable market for premium equipment providers.
- Smart home integration:WiFi-enabled microwave platforms are gaining traction in West Bay residential towers, driven by developer-specified home automation packages.
Market Restraints
- Magnetron supply concentration:Core component sourcing depends on East Asian manufacturing clusters, exposing Qatar distributors to shipping volatility through Strait of Hormuz routes.
- Qatar Civil Defense fire safety certification:Commercial installation approvals require extended testing protocols, stretching tender-to-delivery timelines for hospitality projects.
- Induction cooking substitution:High-end residential developments in Msheireb Downtown are specifying induction ranges with microwave drawers, compressing standalone unit demand.
Strategic Opportunities
- Al Wakrah and Al Khor residential expansion:Government housing initiatives in northern and southern Qatar are creating first-time buyer markets underserved by premium appliance retailers.
- Cybersecurity protocol convergence:Qatar's National Cyber Security Agency guidelines for IoT appliances create compliance barriers that favor established smart platform vendors with certified security architectures.
- Cloud kitchen proliferation:Delivery-focused food operations in Industrial Area zones require compact, high-duty-cycle equipment configurations distinct from traditional restaurant specifications.
Industry Challenges
- Commercial technician certification gaps:Qatar's vocational training infrastructure produces insufficient magnetron repair specialists, forcing manufacturers to fly in regional service engineers for warranty claims.
- Legacy electrical infrastructure incompatibility:Older residential buildings in central Doha lack dedicated circuits for high-wattage convection units, limiting retrofit sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Microwave Ovens Market |
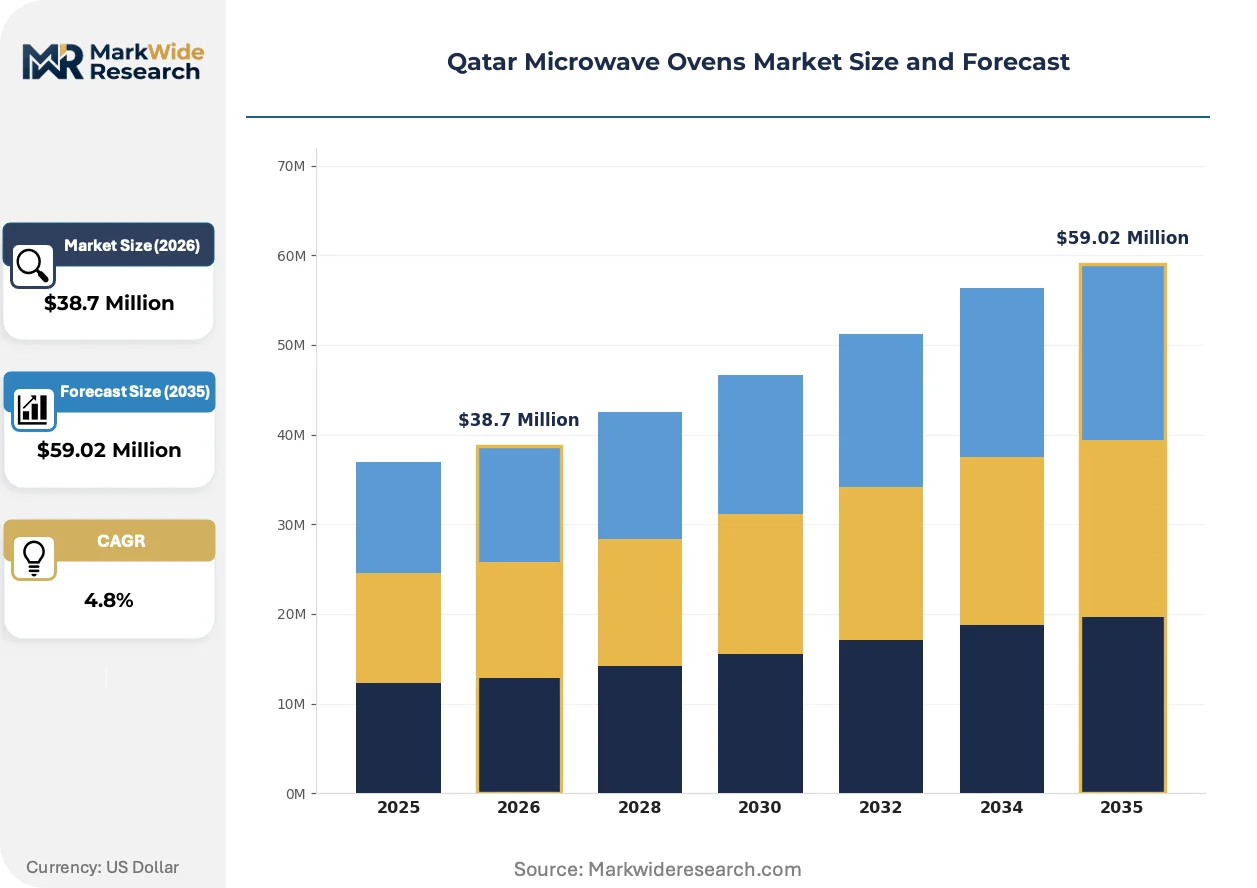
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $59.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection, Grill, Solo, Over-the-Range End User: Residential, Commercial, Hospitality, Industrial Technology: Countertop, Built-in, Smart, Conventional Distribution Channel: Online, Offline, Retail Stores, Wholesale |
| Companies Covered | LG Electronics, Samsung Electronics, Panasonic Corporation, Whirlpool Corporation, Sharp Corporation, Toshiba Corporation, GE Appliances, Midea Group, Hoover, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Microwave Ovens Market Evolving Landscape
Smart connectivity and energy efficiency mandates are restructuring procurement specifications across Qatar's dual residential and commercial channels, compressing the viable product set toward connected, certified platforms.
Inverter power control technology is collapsing energy consumption differentials between cooking modes. Doha hotel operators are specifying inverter-equipped units to meet Qatar General Organization for Standardization and Metrology tiered efficiency requirements. The technology is collapsing the premium-standard price gap as base models adopt variable power output.
Qatar Civil Defense Authority fire suppression integration rules now mandate automatic shutoff protocols for commercial kitchen installations. Equipment vendors must certify flame-detection sensor compatibility before tender eligibility. High-volume catering operations in Education City and Aspire Zone are prioritizing pre-certified units to avoid installation delays.
Subscription-based maintenance contracts are displacing traditional break-fix service relationships. Commercial operators in Lusail Marina district are bundling equipment leasing with predictive maintenance analytics. This shift is most visible among international hotel chains standardizing procurement across their Qatar properties.
Qatar Microwave Ovens Market Segmentation
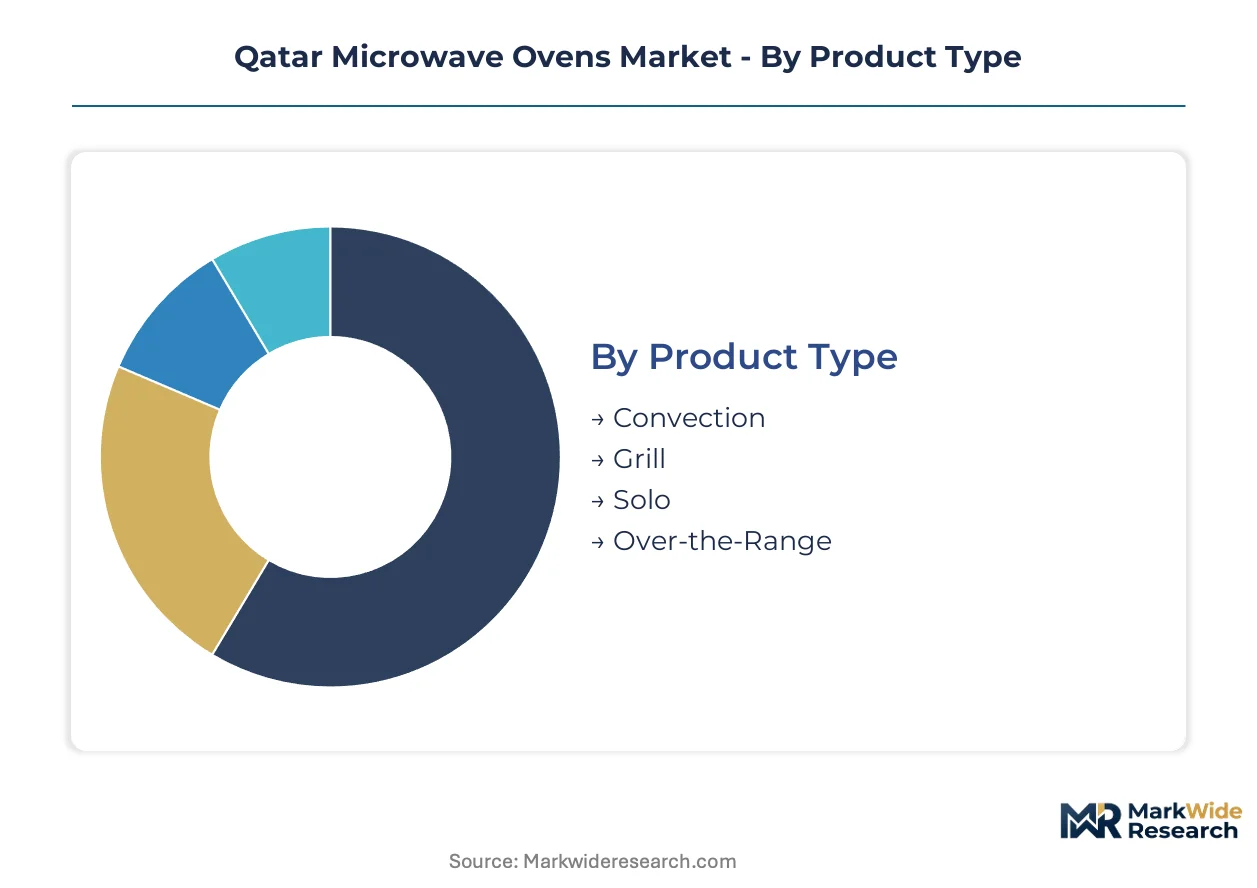
Segmentation in Qatar's microwave oven market reflects the country's bifurcated demand structure: compressed hospitality procurement cycles in Doha's hotel clusters versus tech-forward residential specifications in West Bay and Lusail developments. Understanding these segment boundaries allows manufacturers to align certification, connectivity, and service capabilities with distinct buyer expectations.
Product Type:
Mature convection and grill formats dominate commercial procurement, while emerging smart-enabled variants are capturing residential premium positioning in Doha's upscale tower developments.
- Convection:Combines microwave radiation with circulated hot air for baking and roasting functions in a single footprint. Doha hotel operators specify these units to meet Qatar General Organization for Standardization and Metrology energy benchmarks while reducing kitchen equipment count in space-constrained back-of-house layouts.
- Grill:Integrates quartz or metal-sheath heating elements for surface browning alongside standard microwave operation. Qatar's hospitality procurement channels prioritize grill functionality for high-volume catering operations in Education City and Aspire Zone venues where menu versatility must coexist with rapid throughput.
- Solo:Basic microwave-only units serving price-sensitive residential segments in Al Wakrah and Al Khor government housing initiatives.
- Over-the-Range:Combined ventilation-cooking platforms specified by developers in The Pearl's luxury residential towers to maximize kitchen spatial efficiency.
Convection handles the majority of throughput in commercial channels; smart-enabled convection-grill hybrids are climbing the fastest in West Bay residential specifications.
End User:
Cost tier stratification separates asset-heavy ownership models in residential segments from operational lease structures gaining traction in commercial and hospitality deployment.
- Residential:Individual household purchasers in Doha's expanding northern and southern zones, with demand bifurcating between basic solo units for first-time buyers and connected platforms for tech-forward consumers in Msheireb Downtown.
- Commercial:Independent restaurants and catering operations across Industrial Area and Al Wakrah, where equipment financing preferences are shifting from purchase to subscription-based maintenance bundles.
- Hospitality:International hotel chains and local boutique properties concentrated in Lusail Marina and West Bay, procurement governed by Qatar Civil Defense fire safety certification requirements and Qatar Tourism Authority compressed opening timelines.
- Industrial:High-volume food production facilities and central kitchens serving institutional clients, requiring heavy-duty magnetron configurations with extended duty cycles.
Hospitality commands the highest equipment specification density; cloud kitchen proliferation in Industrial Area is expanding commercial segment share most rapidly.
Technology:
Application context determines technology selection: countertop portability for leased commercial spaces versus built-in integration for developer-specified residential packages.
- Countertop:Freestanding units deployed where installation flexibility outweighs aesthetic integration, prevalent in commercial lease arrangements and older Doha residential stock lacking dedicated appliance housing.
- Built-in:Cabinet-integrated platforms specified by developers in Lusail and The Pearl luxury towers, requiring coordination with kitchen millwork suppliers during construction phase.
- Smart:WiFi-enabled platforms with app control and voice assistant compatibility, gaining traction in West Bay residential towers where home automation packages are developer-mandated and subject to Qatar National Cyber Security Agency IoT guidelines.
- Conventional:Non-connected mechanical control units serving budget residential segments and commercial operators prioritizing operational simplicity over connectivity features.
Built-in technology anchors developer procurement volumes; smart platforms are expanding most quickly among Qatar's premium residential completions.
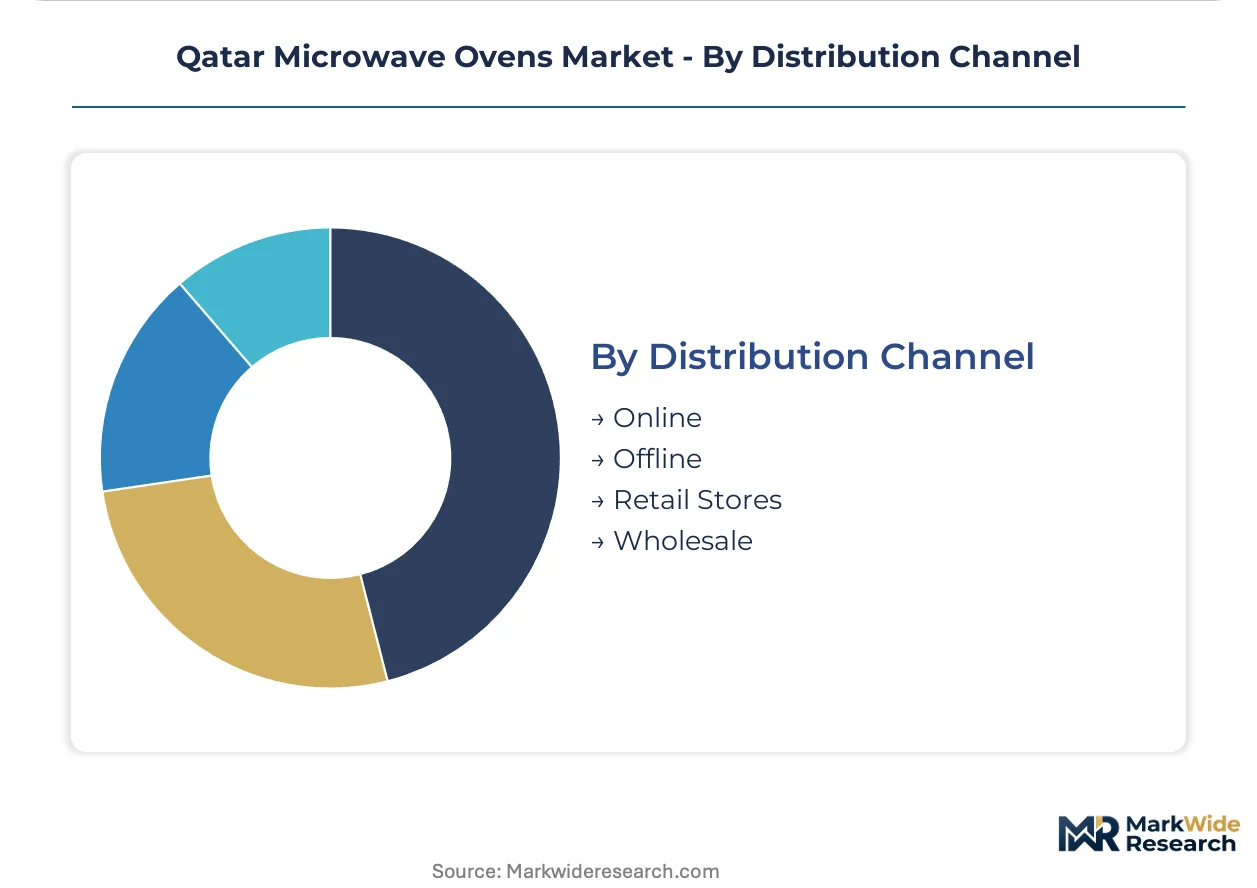
Distribution Channel:
Customer type and purchase urgency shape channel selection: immediate replacement demand favors retail immediacy, while planned new-build specifications flow through wholesale project channels.
- Online:E-commerce platforms serving tech-savvy residential consumers in Doha and Al Wakrah, with delivery logistics constrained by magnetron handling requirements and warranty registration protocols.
- Offline:Traditional showroom-based sales supporting tactile evaluation for residential purchasers, particularly in appliance-dedicated retail zones along Salwa Road.
- Retail Stores:Branded experience centers and multi-brand appliance outlets, where Samsung Electronics and LG Electronics maintain presence for premium segment visibility.
- Wholesale:Project-direct supply arrangements serving hospitality developers and kitchen equipment contractors, bypassing retail markup for volume procurement in Lusail and Education City developments.
Wholesale channels handle the majority of hospitality project volume; online penetration is gaining share fastest among residential replacement purchases in Doha's connected consumer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Doha's hospitality procurement clusters, while residential demand in Qatar's peripheral zones operates on thinner margins constrained by government housing budget ceilings.
Doha Metropolitan Area
West Bay luxury towers and Lusail Marina developments drive premium built-in microwave specifications, with developer-mandated home automation packages requiring Qatar National Cyber Security Agency IoT compliance. Qatar Tourism Authority compressed hotel opening timelines compress procurement cycles for international chains. Msheireb Downtown's smart city infrastructure prioritizes connected appliance integration in residential units.
Al Wakrah
Government housing initiatives for first-time buyers create volume demand for basic solo microwave units, with procurement flowing through centralized municipal supply contracts. Qatar General Organization for Standardization and Metrology energy benchmarks apply to mass-market segments despite lower specification density. Industrial Area cloud kitchen proliferation requires compact high-duty-cycle equipment distinct from traditional restaurant configurations.
Al Khor
Northern residential expansion programs generate replacement demand as infrastructure matures, with retail appliance penetration lagging Doha by several years. The country's national standardization body extends conformity assessment protocols to emerging commercial zones. Northern logistics corridors channel distribution through consolidated wholesale hubs serving scattered residential clusters.
The Pearl
Luxury residential specifications prioritize over-the-range ventilation-cooking platforms to maximize spatial efficiency in high-value kitchen millwork. Qatar Civil Defense Authority fire safety certifications govern developer tender requirements. International property management companies standardize appliance packages across their Qatar portfolios, creating volume concentration for certified vendors.
Industrial Area
Delivery-focused food operations and central kitchens serving institutional clients demand heavy-duty magnetron configurations with extended duty cycles. The country's civil defense regulator mandates automatic shutoff protocols for high-volume catering installations. Labor camp-adjacent food service operations create distinct equipment requirements separate from hospitality procurement channels.
Qatar Microwave Ovens Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in magnetron and control module supply. Qatar's microwave oven sector structures around three tiers: multinational electronics conglomerates with regional distribution infrastructure, mid-scale manufacturers competing on production efficiency, and niche specialists serving specific installation formats. Consolidation pressure operates through asset-light leasing models that favor vendors with integrated service networks. Dominant competitive moves include localized service capability expansion and smart platform certification against emerging cybersecurity protocols.
Among South Korean electronics conglomerates, LG Electronics and Samsung Electronics exemplify the integrated platform archetype, leveraging regional distribution infrastructure and localized service networks to anchor positions across Qatar's premium hospitality and residential segments. Chinese manufacturer Midea Group occupies a position within the scale-driven tier, competing on manufacturing efficiency for budget-conscious residential buyers in Doha's expanding peripheral zones. These three players represent the competitive spectrum: full-service platform integration, regional service anchoring, and cost-efficient volume supply.
| Leading Market Players |
|---|
| LG Electronics |
| Samsung Electronics |
| Panasonic Corporation |
| Whirlpool Corporation |
| Sharp Corporation |
| Toshiba Corporation |
| GE Appliances |
| Midea Group |
| Hoover |
| Others |
Value Network & Pricing Analysis
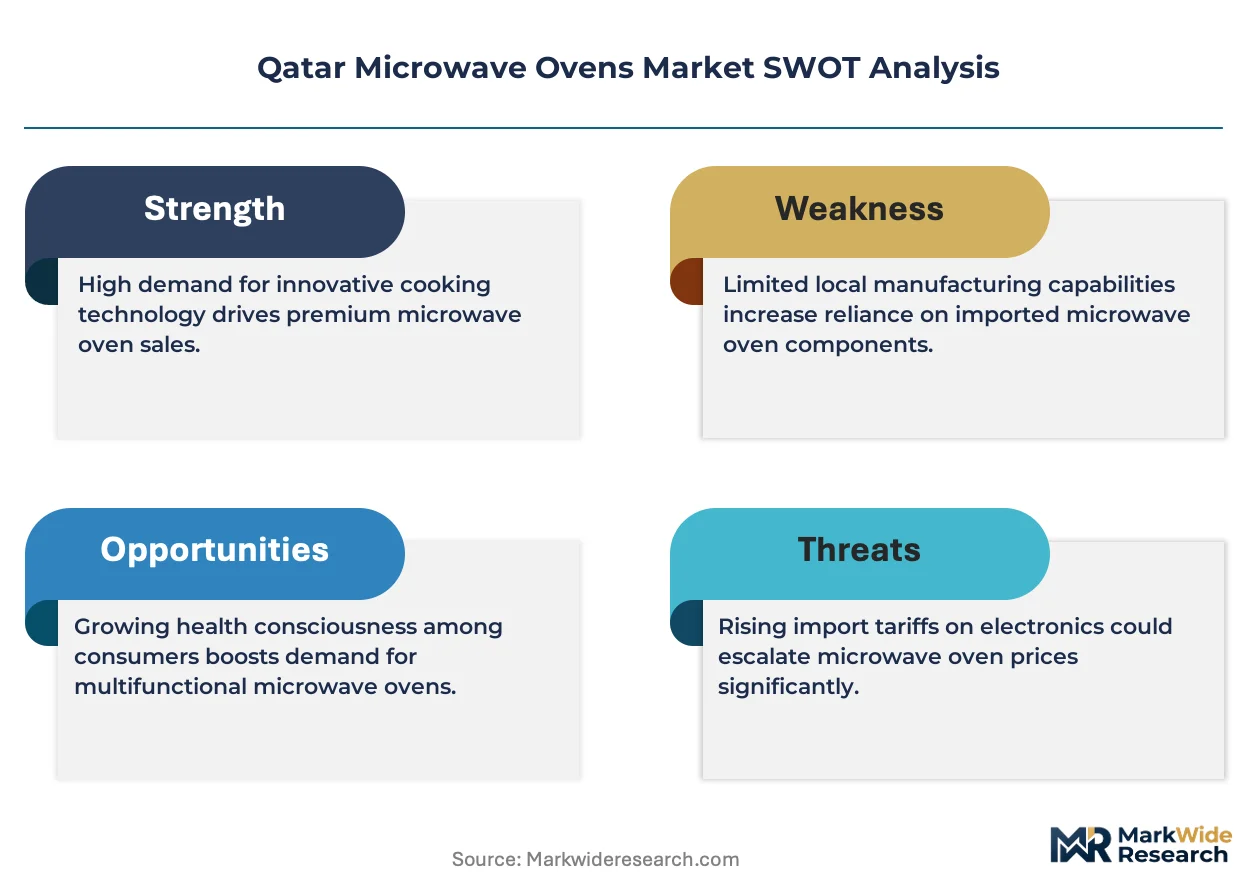
Magnetron supply concentration in East Asian manufacturing clusters exposes Qatar distributors to shipping volatility through Strait of Hormuz routes, forcing a three-tier pricing structure across premium, standard, and economy levels while compressing margins on entry-grade units. This chokepoint dependency shapes procurement strategies for both hospitality operators and residential developers.
Pricing Analysis
Industrial OEM buyers anchor Qatar's microwave pricing structure through volume procurement of convection-grill units for hospitality clusters. Price differentiation rests on Qatar General Organization for Standardization and Metrology certification tiers and after-sales service bundling. Cost compression in the solo unit segment is intensifying because Midea Group's manufacturing scale advantages feed budget residential demand in Al Wakrah and Al Khor. First-time buyers in government housing initiatives exhibit highest price sensitivity; international hotel chains in Lusail Marina show lowest sensitivity due to operational lease structures.
Supply Chain Analysis
Magnetron cores and control modules feed from manufacturing concentrations in China, South Korea, and Japan. Raw material dependencies center on rare earth elements for magnetron cathodes, stainless steel for cavity construction, and semiconductor components for smart platforms. Single-source vulnerability runs through specialized magnetron suppliers with limited geographic diversification. Distribution runs through consolidated wholesale hubs serving Doha's hospitality procurement channels and retail appliance zones along Salwa Road for residential replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset-light leasing model consolidation among international hotel chains has shifted bargaining power toward procurement consortiums, compressing vendor margins and favoring platform-integrated suppliers with certified service networks.
For Market Incumbents: Entrench position through predictive maintenance analytics bundling and Qatar National Cyber Security Agency IoT certification investment. Magnetron repair specialist scarcity threatens warranty fulfillment timelines; establish captive training partnerships with Qatar's vocational institutes. Backward integration into control module sourcing reduces exposure to East Asian semiconductor volatility. For New Entrants and Emerging Players: Cloud kitchen operators in Industrial Area zones represent the most penetrable entry point given their distinct equipment specifications and underserved maintenance relationships. Al Wakrah first-time buyer housing initiatives offer volume scale with lower certification barriers than hospitality channels. Direct-to-operator leasing with embedded service contracts bypasses established wholesale distribution. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors service-integrated platform vendors over pure manufacturing plays. Five-to-ten year viability hinges on cybersecurity protocol convergence and smart home integration mandates. Acquisition targets should demonstrate Qatar Civil Defense pre-certification and localized technician networks. The signal to watch is Qatar Tourism Authority hotel opening timeline acceleration as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Qatar National Cyber Security Agency IoT Certification | Compliance barrier creation favors established smart platform vendors with certified security architectures. |
| Predictive Maintenance Analytics Bundling | Subscription revenue streams displace break-fix relationships in Lusail Marina commercial operator base. |
| Magnetron Repair Specialist Training Partnerships | Vocational pipeline investment addresses Qatar's certified technician shortage and reduces warranty claim resolution times. |
| Cloud Kitchen Equipment Specification Development | Compact high-duty-cycle configurations capture Industrial Area delivery-focused food operation demand. |
| Operational Lease Model Expansion | Asset-light structures align with international hotel chain procurement standardization across Qatar properties. |
Research Methodology
Cross-validation between primary interviews with commercial kitchen operators, hospitality procurement directors, appliance retail channel managers, and Qatar General Organization for Standardization and Metrology officials anchors the qualitative findings. Secondary validation draws from Qatar Civil Defense Authority certification records, Qatar Tourism Authority hospitality development databases, customs import manifests for electrical appliances, and SEC filings of listed multinational electronics conglomerates. Bottom-up equipment unit demand modeling triangulates against top-down sectoral spending estimates.
Calibration against historical hospitality construction completion rates and residential tower handover schedules shapes the projection framework across the analysis window. Segmentation dimensions include product type, end-user category, technology format, and distribution channel, with additional granularity on Qatar Civil Defense certification status. CAGRs derive from trend extrapolation adjusted for regulatory mandate implementation timelines and smart platform adoption curves in West Bay residential developments.
Macroeconomic conditions sit as an overlay; deviation in oil price volatility, construction sector liquidity, and Strait of Hormuz shipping risk would shift the trajectory. Forecasts embed assumptions on Qatar General Organization for Standardization and Metrology energy benchmark enforcement intensity and Qatar National Cyber Security Agency IoT guideline finalization. Cross-checking against Qatar Tourism Authority published hospitality pipeline data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Clothing Iron Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
Europe Garment Steamers Market
Appliances
Smart Washing Machine Market
Appliances
Asia Pacific Compact Dishwasher Market
Appliances
Residential Vacuum Cleaners Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
India Washing Machine Market
Appliances
Bathroom Heaters Market
Appliances
Middle East Portable Washing Machines Market
Appliances
Digital Showers Market
Appliances
Smart Dishwasher Market
Appliances
Global Vended Laundry Equipment Market
Appliances
Saudi Arabia Electric Water Heater Market
Appliances
Laundry Dryer Market
Appliances
Conveyor Dishwasher Market