
 Window Air Conditioners Market | 2026-2036
Window Air Conditioners Market Size, Share, and Industry Trends Forecast 2026-2036
Window Air Conditioners Market Outlook
Inverter compressor technology is rewriting the cost-performance equation for window air conditioners, enabling variable-speed cooling that cuts energy draw versus fixed-speed legacy units. LG Electronics leverages its dual-rotary inverter platform to dominate premium positioning in North American retail channels. Midea anchors global manufacturing scale through captive compressor production in Guangdong province. Carrier differentiates on commercial-grade reliability for hospitality and small-office deployments.
Window air conditioners are self-contained cooling units designed for installation within a window aperture or through-wall sleeve, typically housing compressor, condenser, evaporator, and blower in a single chassis with cooling capacities ranging from 5,000 to 25,000 BTU per hour. These systems serve spaces where central HVAC retrofit proves structurally impractical or economically unjustified, delivering targeted thermal management for individual rooms or open-plan zones up to approximately 1,000 square feet. The inverter segment within product type is capturing margin pools as energy-efficiency premiums justify higher unit prices, while fixed-type units retain volume dominance in price-sensitive emerging markets. Smart and Wi-Fi-enabled control types are expanding fastest, driven by utility demand-response programs and consumer preference for app-based scheduling, though manual and remote-control variants still occupy the bulk of replacement sales in older housing stock.
The EPA's HFC phasedown under the AIM Act and corresponding DOE minimum efficiency standards are reshaping product design requirements and compliance costs for manufacturers selling into the United States. India's Bureau of Energy Efficiency star-rating mandates and China's GB standards for room air conditioner efficiency create divergent certification burdens that fragment regional product portfolios. Stakeholders must monitor refrigerant transition timelines and efficiency tier escalations to align R&D pipelines with jurisdictions where regulatory stringency is tightening fastest.
Market Dynamics
The EPA's AIM Act HFC phasedown is compressing refrigerant supply chains and forcing compressor redesigns across the window air conditioner industry, while inverter technology penetration accelerates replacement cycles in premium residential segments.
Growth Catalysts
- Inverter compressor adoption:Variable-speed cooling technology cuts energy consumption versus fixed-speed legacy units, driving retrofit demand in urban apartment blocks across India and Southeast Asia.
- India's BEE star-rating mandates:Efficiency tier escalations compel manufacturers to upgrade product portfolios, creating volume leadership in tropical climate zones with expanding middle-class housing stock.
- Utility demand-response programs:Smart and Wi-Fi-enabled control integration allows grid operators to manage peak loads, accelerating connected unit deployment in North American retail channels.
Market Restraints
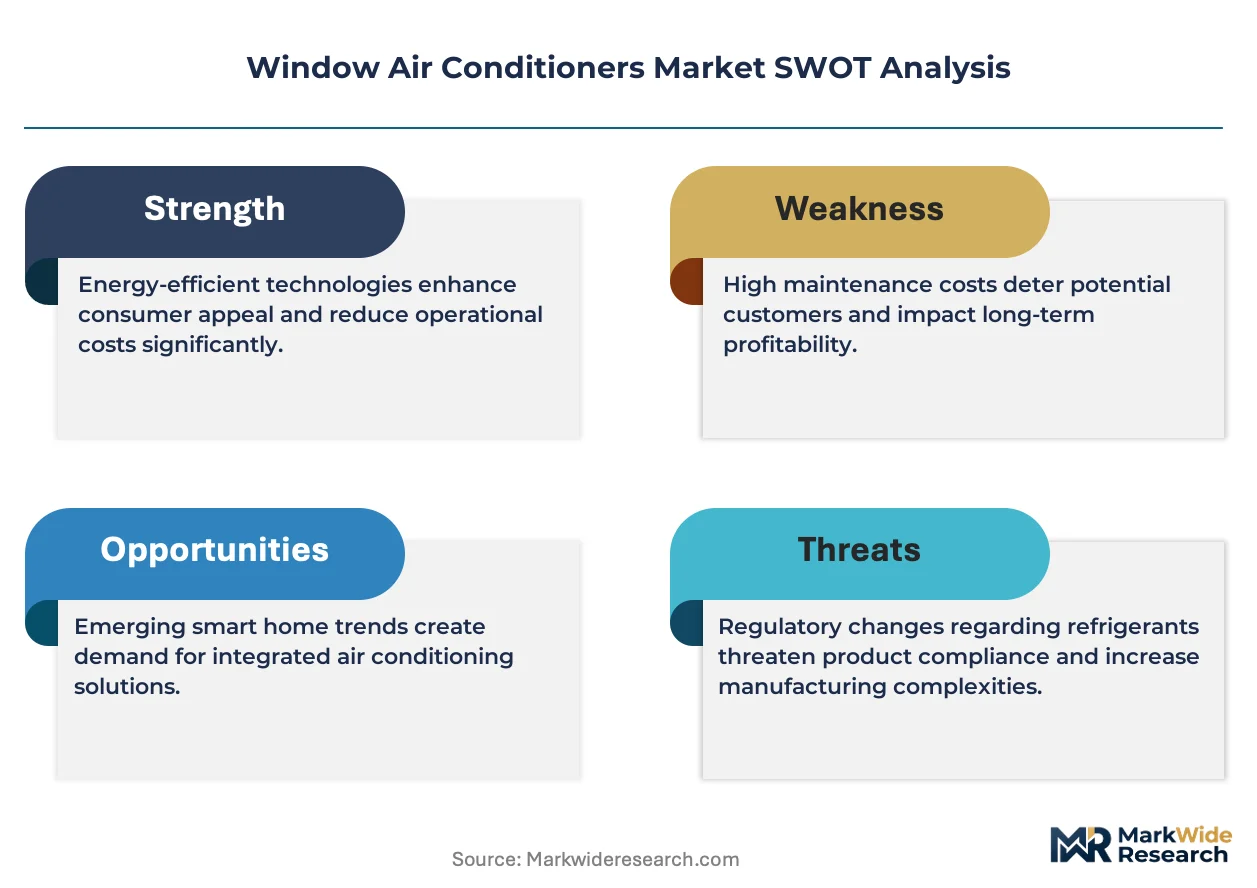
- Copper and aluminum input volatility:Raw material price swings compress manufacturing margins, particularly for fixed-type units where cost competition prevents full pass-through to retail pricing.
- Guangdong province supply concentration:Captive compressor production clusters in southern China create geographic risk exposure for brands dependent on single-source manufacturing ecosystems.
- Central HVAC substitution threat:Mini-split and ductless systems capture share in small-office and hospitality deployments where installation flexibility offsets higher upfront capital requirements.
Strategic Opportunities
- Tier-2 and Tier-3 Indian cities:Underpenetrated housing stock in secondary urban centers offers volume expansion for economy-tier fixed-speed units ahead of efficiency mandate phase-ins.
- Commercial-grade reliability positioning:Hospitality and small-office segments reward durability premiums, creating margin pools distinct from commodity residential replacement cycles.
- Refrigerant transition R&D alignment:Early adoption of low-GWP alternatives ahead of EPA enforcement timelines positions manufacturers for compliance cost advantages in US distribution channels.
Industry Challenges
- Refrigerant certification complexity:Divergent EPA, EU F-Gas Regulation, and India's Ozone Depleting Substances rules fragment product development pipelines, extending compliance timelines for multi-jurisdictional portfolios.
- Legacy housing electrical infrastructure:Older apartment blocks in dense urban cores lack circuit capacity for high-BTU inverter units, forcing derated installations or electrical upgrade coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Window Air Conditioners Market |
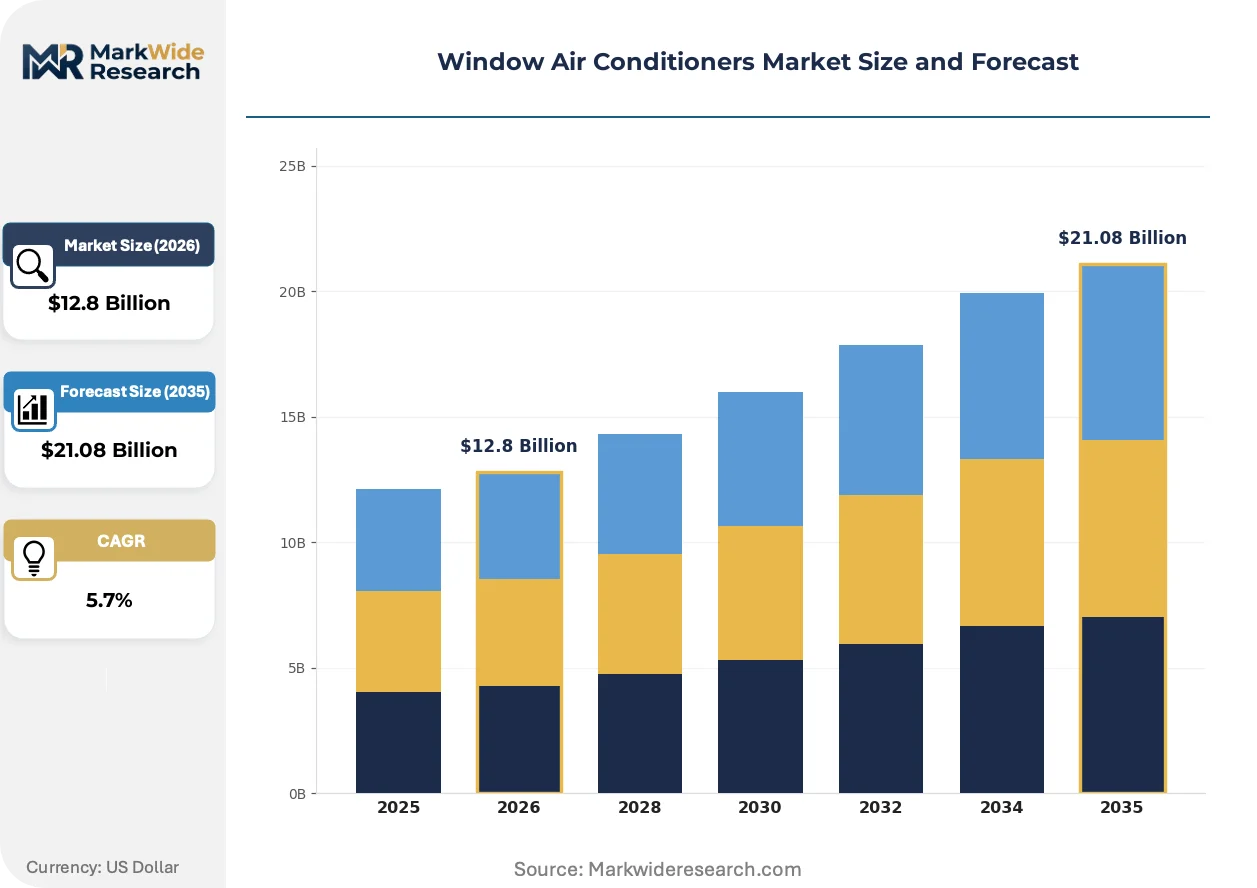
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Portable, Inverter, Hybrid Cooling Capacity: 5000 BTU, 7000 BTU, 10000 BTU, 12000 BTU Control Type: Manual, Remote Control, Smart, Wi-Fi Enabled End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | LG Electronics, Carrier, Midea, Trane Technologies, Daikin Industries, Frigidaire, Hisense, Rheem Manufacturing, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Window Air Conditioners Market Strategic Shifts
Inverter-driven variable-speed architectures are rewriting the cost-performance equation for window air conditioners, while regulatory pressure on refrigerants and connectivity mandates reshape product design requirements across manufacturing bases.
Dual-rotary inverter compressor platforms are collapsing the energy-efficiency gap between window units and mini-split systems. Property managers in multi-family housing are specifying these platforms for common-area cooling retrofits. The technology is collapsing premium pricing power for fixed-speed legacy units in markets where electricity tariffs structure operating cost visibility.
The EPA's AIM Act HFC phasedown and corresponding DOE efficiency standards are mandating refrigerant transitions and compressor redesigns for US-bound production. Manufacturers face dual certification burdens as India's BEE star-rating mandates and China's GB standards diverge on test protocols. The regulatory patchwork is compressing product portfolio standardization, forcing region-specific chassis and control configurations.
Smart control integration is shifting buyer preferences toward app-based scheduling and utility-managed demand response. E-commerce channels are capturing replacement sales from traditional appliance retailers, particularly for Wi-Fi-enabled units where installation simplicity reduces service bundling requirements. This channel rotation is most visible in North American and European markets where housing stock age sustains steady replacement demand.
Window Air Conditioners Market Segmentation
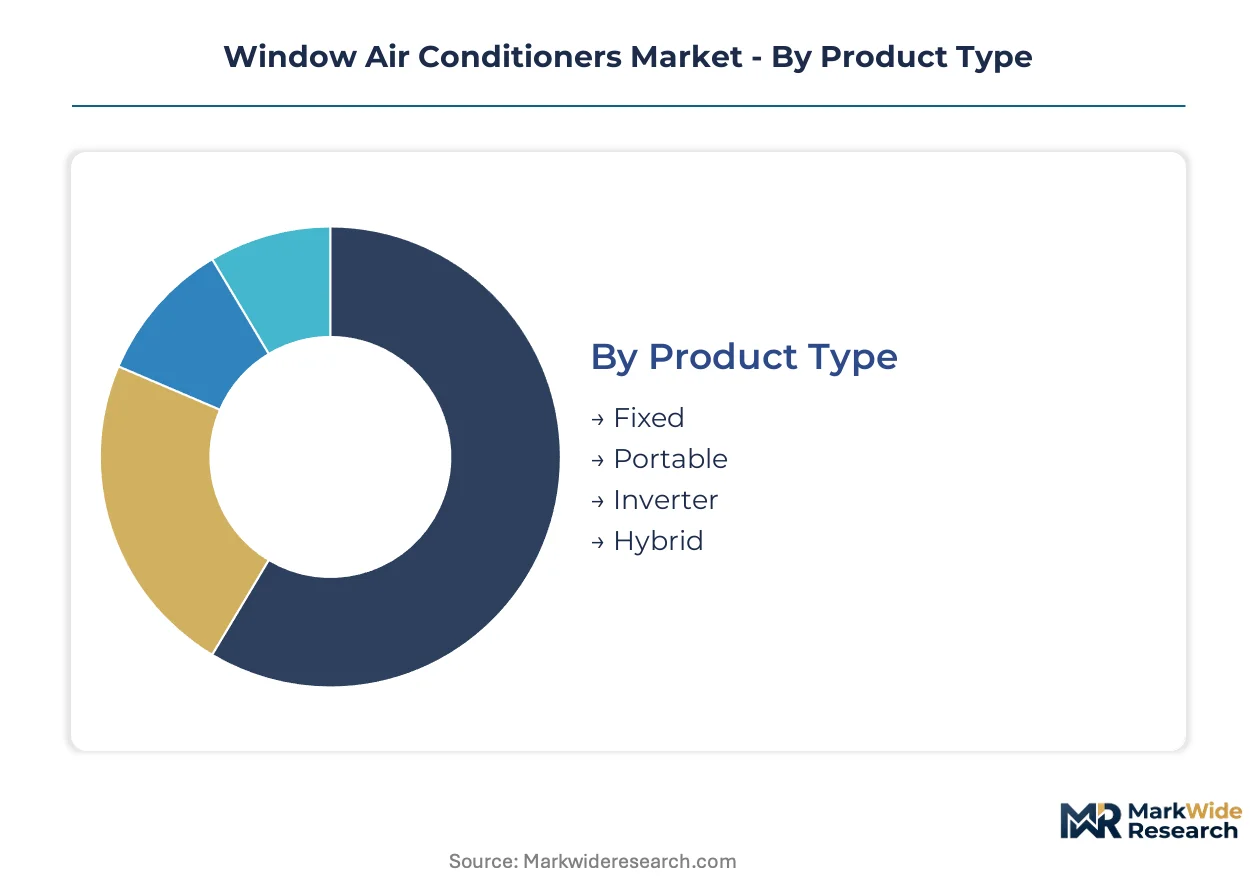
Window air conditioner segmentation reveals how technology tiers, capacity bands, and control interfaces align with distinct installation constraints and operating cost sensitivities across housing vintages and building types. Manufacturers configure chassis dimensions, compressor architectures, and refrigerant charges to match these discrete demand pockets rather than pursuing universal platforms.
Product Type:
Cooling requirements span from basic seasonal relief to year-round climate management, with each product architecture optimizing for different duty cycles and electrical infrastructure limitations.
- Fixed:Single-speed compressor units with constant blower operation dominate replacement cycles in legacy apartment stock where circuit capacity restricts power draw. India's BEE star-rating mandates are compressing margins for manufacturers reliant on fixed-speed volumes ahead of efficiency tier escalations.
- Inverter:Variable-speed compressor platforms modulate cooling output to match thermal load, cutting energy consumption versus fixed-speed equivalents. Property managers in Southeast Asian multi-family housing are specifying these for common-area retrofits where electricity tariffs structure operating cost visibility.
- Portable:Self-contained units on casters exhaust condenser air through flexible ducting, serving spaces where window installation is structurally prohibited or lease terms forbid permanent mounting. Demand concentrates in European rental markets with strict landlord-tenant fixture regulations.
- Hybrid:Dual-mode systems combining vapor-compression cooling with evaporative or heat-pump heating functionality extend operating seasons in transitional climate zones. These units capture premium positioning in North American regions with wide annual temperature swings.
The dominant share belongs to Fixed units, while Inverter is closing the gap fastest.
Cooling Capacity:
Capacity selection maps directly to room volume and envelope thermal performance, with oversizing penalties in humidity control and energy efficiency creating precise sizing discipline among contractors and informed consumers.
- 5000 BTU:Compact chassis designed for spaces up to 150 square feet, typically bedrooms or home offices. These units face displacement pressure from mini-split alternatives in renovation-heavy markets.
- 7000 BTU:Mid-range capacity serving 250-400 square foot zones including studio apartments and small retail footprints. India's expanding middle-class housing stock in Tier-2 cities sustains volume for this segment.
- 10000 BTU:Workhorse specification for open-plan residential zones and small commercial deployments up to 450 square feet. Hospitality operators in tropical climates specify these for guest room retrofits where central HVAC retrofit is capital-prohibitive.
- 12000 BTU:Maximum standard window-aperture capacity serving large living areas or combined zones up to 550 square feet. Electrical infrastructure limitations in older urban cores restrict penetration despite cooling performance advantages.
The 10000 BTU specification anchors volume leadership, though 12000 BTU is expanding most quickly as electrical upgrade coordination becomes standard in renovation workflows.
Control Type:
Interface sophistication stratifies across buyer demographics, with connected controls commanding price premiums justified by utility program participation and operational convenience.
- Manual:Mechanical thermostat and rocker-switch operation persists in replacement sales for aging housing stock where technology aversion or rental property cost minimization dominates purchase criteria.
- Remote Control:Infrared handset operation enables temperature adjustment without accessing the chassis, standard in mid-tier fixed-speed and entry inverter units across price-sensitive emerging markets.
- Smart:Microprocessor-based climate management with programmable schedules and occupancy sensing. North American utility demand-response programs are accelerating deployment through rebate structures and time-of-use rate incentives.
- Wi-Fi Enabled:Cloud-connected platforms supporting smartphone app control and voice assistant integration. E-commerce channels capture disproportionate share of these units where installation simplicity reduces service bundling requirements.
Manual and Remote Control variants retain combined volume dominance, yet Wi-Fi Enabled is climbing the fastest as channel rotation toward online retail favors connected feature sets.
End User:
Application context dictates durability specifications, operating hour expectations, and service response requirements that separate commercial-grade from residential product lines.
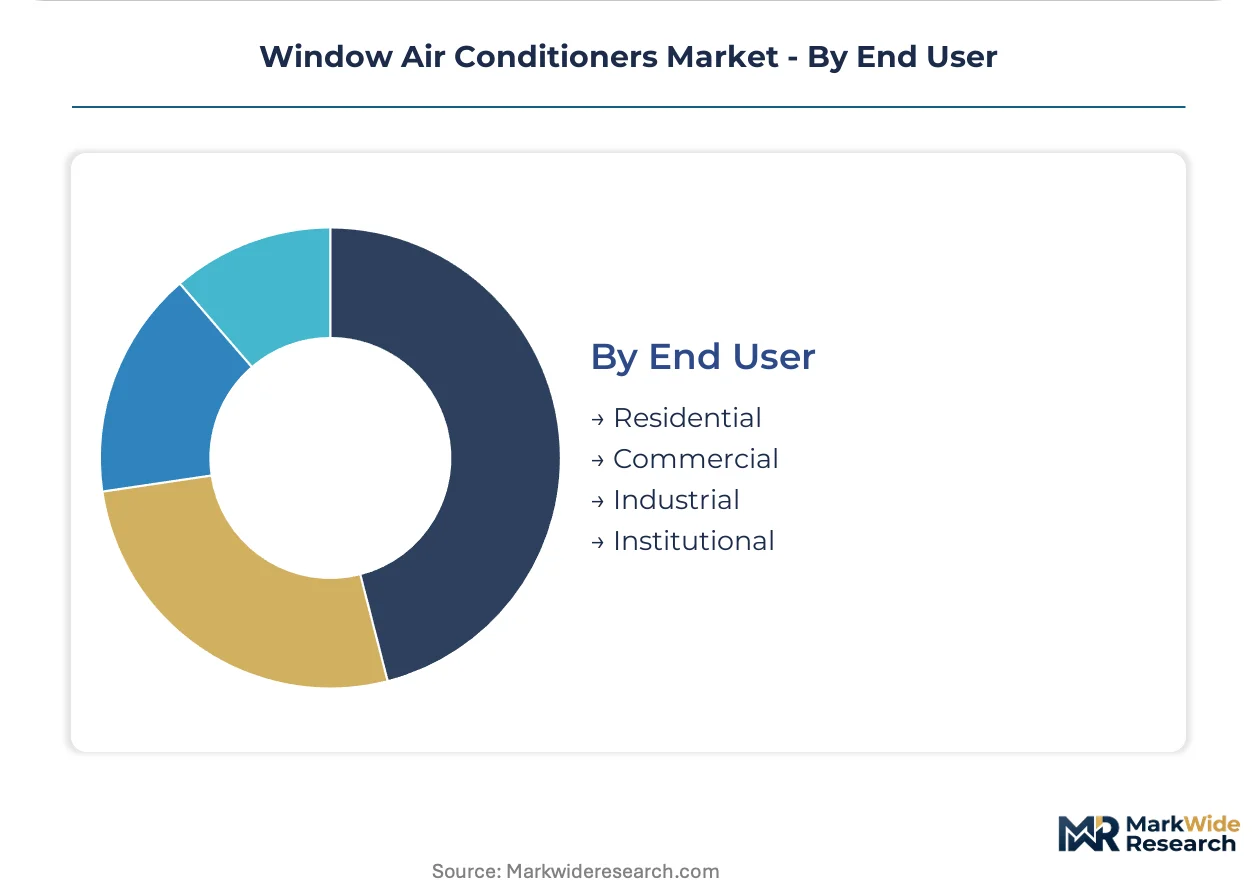
- Residential:Individual household installations across owned and rental housing, with replacement cycles averaging 8-12 years depending on climate severity and maintenance discipline. Retrofit demand in urban apartment blocks is accelerating upgrade timelines.
- Commercial:Small-office, retail, and hospitality deployments requiring extended warranty terms and rapid service response. Carrier and LG Electronics compete for this margin pool through reliability positioning distinct from commodity residential cycles.
- Industrial:Supplementary cooling for process areas, server closets, and break rooms in manufacturing facilities where central HVAC zoning proves inadequate. These applications stress compressor durability through continuous operation regimes.
- Institutional:Schools, healthcare clinics, and government facilities with procurement protocols emphasizing lifecycle cost analysis and compliance documentation. EPA refrigerant transition timelines create procurement urgency for fleet replacements.
Residential captures the dominant share, while Commercial is gaining share fastest as durability premiums reward manufacturers with service network depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt heavily toward manufacturing concentration in East Asia, with finished unit shipments flowing to deficit markets in North America and Europe. India and Southeast Asia absorb growing volumes as domestic production scales to meet tropical climate demand.
United States
Replacement cycles in aging urban apartment stock sustain import dependence for window units, particularly in legacy housing across the Northeast and Midwest. The EPA's AIM Act HFC phasedown and DOE efficiency standards are compressing product portfolios eligible for domestic sale. Distribution concentrates through big-box retail channels in Texas and Florida, where cooling-degree-day intensity supports year-round demand.
China
Guangdong province anchors captive compressor production and finished unit assembly for global export, with GB standards on room air conditioner efficiency creating divergent test protocols from Western markets. MIIT industrial policy and dual carbon goals are accelerating inverter technology penetration in domestic sales. The Pearl River Delta cluster ships standard-efficiency fixed-speed units to price-sensitive emerging markets across Africa and Latin America.
India
Tier-2 and Tier-3 city housing expansion drives volume leadership for economy-tier fixed-speed units ahead of BEE star-rating mandate escalations. The Bureau of Energy Efficiency's efficiency tier schedule compresses margins for manufacturers reliant on legacy portfolios. Manufacturing investment concentrates in Gujarat and Tamil Nadu, where state industrial policies attract assembly operations serving domestic and Middle Eastern export markets.
Germany
Rental market fixture restrictions and strict landlord-tenant regulations sustain portable unit demand alongside conventional window installations. The EU F-Gas Regulation and REACH compliance requirements fragment product certification from US and Asian standards. Distribution runs through specialized HVAC wholesalers in North Rhine-Westphalia and Bavaria, where commercial-grade reliability specifications command durability premiums.
Japan
High electricity tariffs and space constraints in dense urban cores favor compact, high-efficiency inverter architectures. METI energy conservation standards and JIS certification requirements create technical barriers for non-domestic manufacturers. The Kanto region around Tokyo concentrates premium product development and domestic sales channels, with Osaka-based distributors serving western Japan's commercial retrofit segments.
Window Air Conditioners Market Competitive Environment
On the supply side, the industry is consolidating around scale-driven manufacturers with captive compressor production and tiered specialists competing on efficiency certification and connectivity features. Three strategic archetypes dominate: vertically integrated conglomerates controlling upstream component supply, premium-tier brands commanding retail price positioning through inverter technology, and contract manufacturers serving private-label channels. Competitive moves center on refrigerant transition R&D alignment ahead of regulatory deadlines and e-commerce channel expansion to capture replacement sales with reduced service bundling.
Among Asia-Pacific-based conglomerates, LG Electronics and Midea exemplify divergent scale strategies, with the former representing premium-tier inverter positioning and the latter anchoring volume manufacturing through backward integration into compressor production. Carrier occupies a position within the commercial-grade reliability archetype, targeting hospitality and small-office deployments where extended warranty terms and service network depth justify pricing premiums distinct from commodity residential cycles.
| Leading Market Players |
|---|
| LG Electronics |
| Carrier |
| Midea |
| Trane Technologies |
| Daikin Industries |
| Frigidaire |
| Hisense |
| Rheem Manufacturing |
| GE Appliances |
| Others |
Value Chain & Pricing Dynamics
The Shenzhen-Los Angeles transpacific corridor's freight volatility feeds directly into landed cost spreads between Guangdong-assembled units and North American retail pricing, amplifying margin compression for fixed-speed inventory while insulating inverter-tier premiums from commodity turbulence.
Pricing Analysis
Technology-generation pricing gaps separate fixed-speed legacy units from inverter platforms and emerging hybrid architectures. Three-tier pricing structure across premium, standard, and economy levels tracks BEE star ratings and Wi-Fi connectivity bundles. Cost compression in fixed-speed tiers is intensifying because India's efficiency mandate escalations compress manufacturer margins ahead of compliance deadlines. Price sensitivity concentrates in Tier-2 Indian city housing expansion, while North American hospitality operators show lowest sensitivity to upfront capital for commercial-grade reliability specifications.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for window air conditioner manufacturers. Production gravity centers on Guangdong province, South Korea, and Thailand for compressor and chassis assembly. Raw material dependencies draw from Chilean copper cathode, Australian aluminum ingot, and Chinese rare-earth magnet feedstock. Single-source vulnerability in Guangdong's captive compressor ecosystem threatens output continuity. Distribution runs through big-box retail consolidation in Texas and Florida alongside e-commerce channel rotation for Wi-Fi-enabled units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart control platform interoperability is shifting window air conditioners toward home-automation ecosystem integration, with utility demand-response API standardization creating winner-take-most dynamics for connected-unit market share.
For Market Incumbents: Insulate premium positioning by accelerating dual-rotary inverter R&D pipelines ahead of EPA refrigerant enforcement timelines. Deepen backward integration into compressor production to offset Guangdong supply concentration risk. Defend against mini-split substitution in small-office segments by extending commercial-grade warranty terms and service network density.
For New Entrants and Emerging Players: Tier-3 Indian city housing stock with pending BEE mandate phase-ins represents the most penetrable entry point for economy-tier fixed-speed volume capture. European rental market portable-unit demand under strict landlord-tenant fixture regulations offers secondary white-space. E-commerce direct-to-consumer channels bypass traditional retail service-bundling requirements for Wi-Fi-enabled SKU launches.
For Investors and Strategic Acquirers: Regional inverter-technology specialists with captive R&D and localized certification capabilities present the highest-value acquisition profile. Long-term viability hinges on refrigerant-transition readiness and smart-platform integration depth across the projection horizon. Monitor EPA enforcement timeline acceleration and utility rebate program expansion as inflection indicators for connected-unit adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition R&D Alignment | Early low-GWP adoption secures EPA compliance cost advantages in US channels. |
| Backward Integration into Compressor Production | Captive supply of dual-rotary platforms insulates margin from Guangdong concentration risk. |
| Smart Control Platform Integration | Utility demand-response API compatibility drives North American retail channel preference. |
| Tier-2/Tier-3 India Distribution Expansion | Pre-mandate housing stock capture builds volume ahead of BEE efficiency tier escalations. |
| Commercial-Grade Reliability Positioning | Hospitality and small-office segments reward durability premiums distinct from commodity cycles. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with HVAC manufacturing executives, utility demand-response program managers, and multi-family property operators; and secondary validation through EPA AIM Act filings, BEE star-rating schedules, customs trade data, and SEC equipment manufacturer disclosures. Bottom-up unit shipment modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs span product type segmentation, cooling capacity bands, control interface tiers, and end-use application contexts. CAGRs derived from regression analysis against cooling-degree-day intensity, housing stock vintage, and regulatory compliance cost trajectories. Specific inputs include refrigerant transition timelines, inverter technology penetration curves, and e-commerce channel share evolution.
Practitioners should monitor EPA enforcement acceleration, copper-aluminum input volatility, and utility rebate program expansion for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Shared Shoe Washing Machine Market
Appliances
Electric Ranges Market
Appliances
Intelligent Electric Rice Cooker Market
Appliances
AI Washing Machine Market
Appliances
Electric Dryers Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
Garments Steamer Market
Appliances
India Washing Machine Market
Appliances
Refrigerator Door Seal Market
Appliances
Domestic Food Preparation Appliances Market
Appliances
Clothing Iron Market
Appliances
North America Compact Dishwasher Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
US Washing Machine Parts Market
Appliances
Germany Compact Dishwasher Market
Appliances
Hair Removal Appliances Market