
 Russia Telecom Market | 2026-2036
Russia Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Telecom Market Insights
Enterprise buyer concentration is shifting as Russian banks, energy conglomerates, and federal agencies consolidate procurement under long-term managed service contracts rather than fragmented vendor relationships. MegaFon PJSC leverages its integrated cloud and cybersecurity portfolio to anchor large enterprise accounts in Moscow and Saint Petersburg. Rostelecom sustains dominance across fixed-line and fiber infrastructure through its government-backed Universal Service Obligation mandate. Mobile TeleSystems PJSC differentiates via vertical integration into fintech and media streaming services bundled with connectivity.
Russia telecom encompasses the transmission of voice, data, and video services across wired and wireless infrastructure operating on licensed spectrum bands and fiber-optic backbones, with 5G NR deployments currently concentrated in sub-6 GHz frequencies due to equipment availability constraints. The primary commercial purpose centers on enabling enterprise digitalization, consumer broadband access, and state-critical communications resilience. Mobile services generate the largest revenue pool but face margin compression from regulatory tariff ceilings, while fiber-optic infrastructure captures expanding share as Rostelecom and regional operators extend GPON coverage to secondary cities. Cloud-based deployment models are accelerating fastest among enterprise segments seeking to bypass capital-intensive on-premise hardware procurement.
The Ministry of Digital Development, Communications and Mass Media sets licensing frameworks and spectrum allocation rules that directly determine operator rollout timelines and capital deployment priorities. Russia's Federal Antimonopoly Service scrutinizes wholesale interconnection rates between Tier-1 operators, shaping competitive dynamics in regional markets. The Federal Security Service mandates encryption and data localization standards for critical infrastructure operators, filtering equipment vendor eligibility. Stakeholders must monitor how import substitution requirements for network hardware reshape supplier relationships and total cost of ownership models across the forecast horizon.
Market Dynamics
Sovereign internet mandates and domestic equipment substitution requirements are forcing network operators to reconfigure supplier relationships and capital deployment timelines across Russia's telecommunications infrastructure.
Growth Catalysts
- Federal Universal Service Obligation:Government-backed mandates ensure fiber backbone extension into underserved regions, locking in predictable revenue streams for fixed-line infrastructure operators.
- Financial services digitalization:Russian banks and insurers are consolidating secure connectivity procurement under multi-year managed service frameworks.
- GPON technology deployment:Gigabit passive optical networks enable cost-efficient last-mile fiber delivery to secondary cities beyond Moscow and Saint Petersburg.
Market Restraints
- Import substitution hardware mandates:Restrictions on foreign network equipment procurement compress vendor choice and extend deployment timelines for 5G infrastructure.
- Regulatory tariff ceilings:Federal Antimonopoly Service price controls on mobile services limit margin expansion despite rising operational costs.
- Equipment availability constraints:Sub-6 GHz spectrum dominates 5G NR rollouts due to limited domestic production of millimeter-wave base station components.
Strategic Opportunities
- Enterprise cloud migration:Moscow-based data center buildouts create demand for low-latency fiber interconnects and edge computing nodes.
- Cybersecurity service bundling:Federal Security Service encryption standards position compliant operators to capture premium enterprise accounts.
- Central Federal District concentration:Advanced digitalization in this region offers template models for replication in Volga and Siberian federal districts.
Industry Challenges
- Legacy PSTN integration:Operators face technical complexity migrating circuit-switched voice infrastructure to IP-based cores without service disruption.
- Domestic equipment certification timelines:Federal Security Service hardware approval processes extend procurement cycles for critical network components.
- Specialized engineering talent scarcity:Shortages in fiber-optic splicing and 5G network optimization constrain rollout velocity in remote regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Telecom Market |
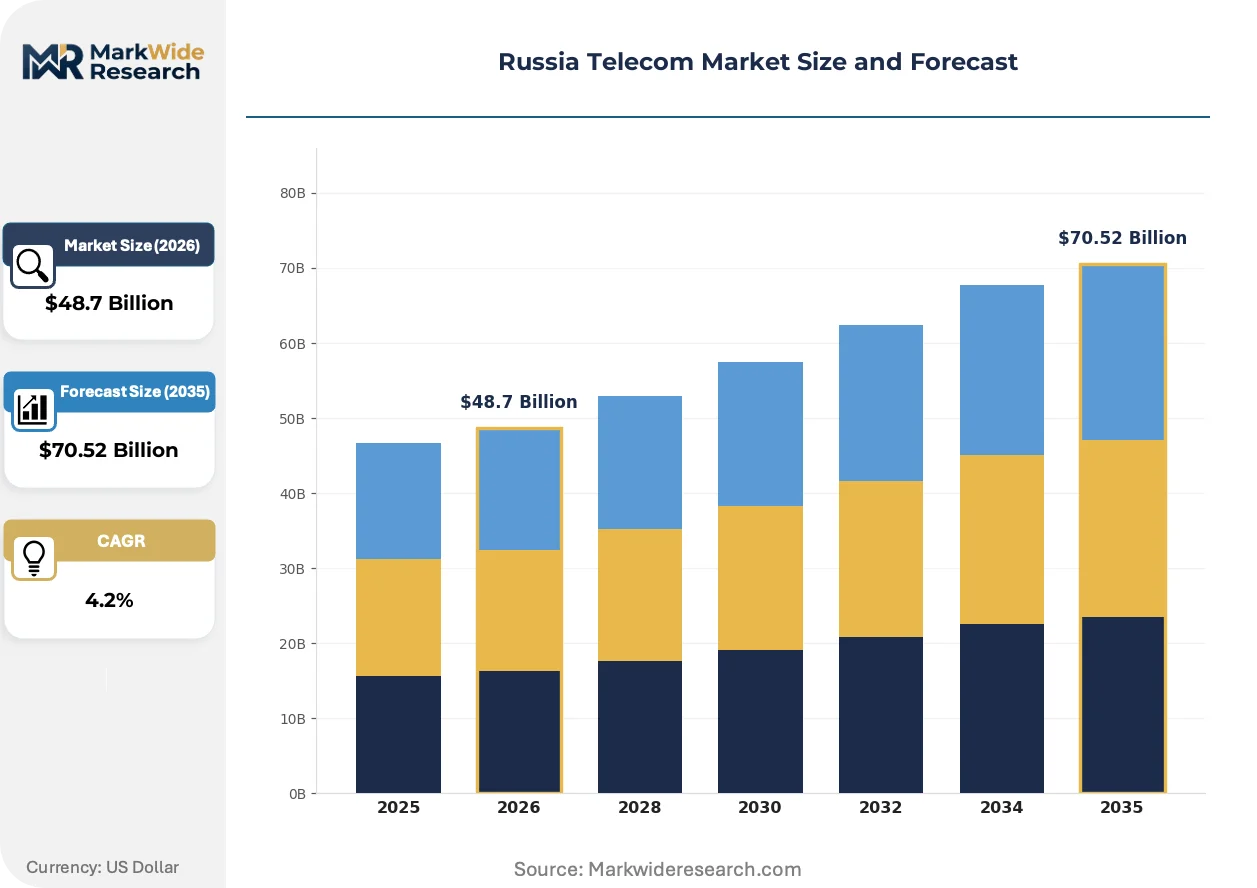
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Fixed-line, Internet, VoIP Technology: 4G, 5G, Fiber Optic, Satellite End User: Residential, Business, Government, Educational Deployment: On-premise, Cloud-based, Hybrid, Managed Services |
| Companies Covered | Tele2 Russia, Yota, Mobile TeleSystems PJSC (MTS), Tinkoff Mobile, SberMobile, MegaFon PJSC, Rostelecom, MGTS, Beeline (PJSC VimpelCom), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Telecom Market Trends and Innovations
Network function virtualization and software-defined infrastructure are dismantling traditional hardware-centric deployment models across Russian telecommunications, compressing capital requirements and accelerating service velocity.
Open RAN architectures are rewriting how mobile operators construct radio access networks. MegaFon and regional challengers are piloting multi-vendor RAN deployments to reduce dependency on single-source base station suppliers. This disaggregation is enabling faster feature rollout while complicating system integration responsibilities.
The Ministry of Digital Development's data localization requirements are compelling foreign cloud providers to establish Russian Federation-based infrastructure. This regulatory pressure is fragmenting global cloud architectures and creating captive demand for domestic data center operators with certified compliance frameworks.
Enterprise buyers in Russia's energy and logistics sectors are consolidating telecommunications procurement under outcome-based connectivity contracts. Traditional per-port or per-megabit pricing is yielding to guaranteed service-level agreements with penalty structures. This shift is most visible in Saint Petersburg's port and industrial corridor, where operational technology networks demand 99.999% uptime commitments.
Russia Telecom Market Segmentation
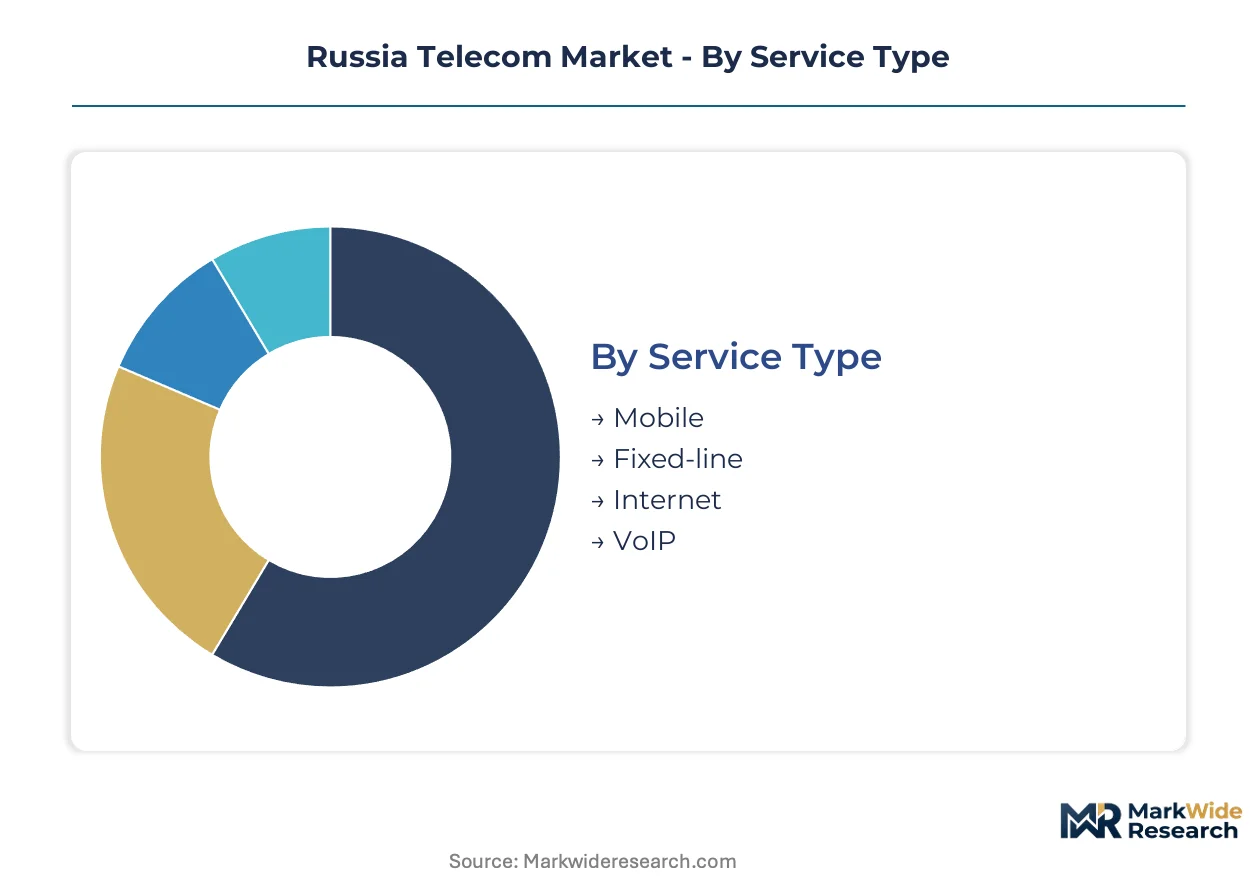
Russia's telecom market segments reflect divergent infrastructure maturity and procurement models. Service type and technology layers determine capital intensity, while end-user and deployment categories shape margin structures and contract duration.
Service Type:
Standalone connectivity services operate independently from bundled ICT offerings, creating distinct margin profiles across the four primary service categories.
- Mobile:Cellular voice and data services delivered over licensed spectrum with nationwide roaming obligations. Moscow and Saint Petersburg account for disproportionate ARPU concentration as enterprise mobility contracts expand. Regulatory tariff ceilings compress margins despite rising data consumption.
- Fixed-line:Traditional circuit-switched and IP-based voice services over copper and fiber infrastructure. Rostelecom's Universal Service Obligation mandate secures revenue predictability in secondary cities and rural territories where wireless alternatives prove uneconomical.
- Internet:Broadband access via fiber, DSL, and fixed wireless technologies. GPON deployments accelerate in the Central Federal District as regional operators replicate Moscow's gigabit coverage models.
- VoIP:Packet-switched voice services riding over IP networks with quality-of-service guarantees. Enterprise adoption concentrates in financial services verticals seeking cost arbitrage against legacy PSTN interconnects.
Volume placements concentrate in Mobile; the faster expansion belongs to Internet.
Technology:
Cost tiers separate mature, depreciated infrastructure from capital-intensive next-generation deployments requiring fresh spectrum and hardware investment.
- 4G:LTE-Advanced networks providing ubiquitous coverage across Russia's federal districts. Spectrum refarming initiatives in the 800 MHz and 2600 MHz bands extend service life as operators delay full 5G migration.
- 5G:NR deployments concentrated in sub-6 GHz frequencies due to domestic millimeter-wave component shortages. Moscow pilot zones demonstrate enterprise private network applications for manufacturing and logistics campuses.
- Fiber Optic:GPON and active Ethernet backbones delivering symmetric gigabit speeds. Secondary city buildouts in the Volga Federal District follow Central District deployment templates.
- Satellite:Geostationary and low-earth orbit constellations serving remote Arctic and Siberian territories beyond fiber economic reach. Government subsidies anchor demand for universal connectivity mandates.
Revenue gravity sits with 4G; steepest expansion trajectory attaches to Fiber Optic.
End User:
Customer type determines contract structure, with government and enterprise segments favoring multi-year managed service frameworks over residential prepaid models.
- Residential:Individual consumers and households purchasing connectivity through retail channels. Price sensitivity dominates procurement, with churn concentrated in mobile segments following promotional period expiration.
- Business:Corporate entities procuring bundled connectivity, cloud, and cybersecurity services. Banking and energy conglomerates in Moscow consolidate vendor relationships under outcome-based SLA contracts.
- Government:Federal agencies and state enterprises with sovereign internet compliance requirements. Federal Security Service encryption mandates filter vendor eligibility and extend procurement cycles.
- Educational:Universities and research institutes requiring high-capacity research networks. Ministry of Education connectivity programs channel funding toward secondary city institution upgrades.
Contract value concentrates in Business; the fastest share gains belong to Government.
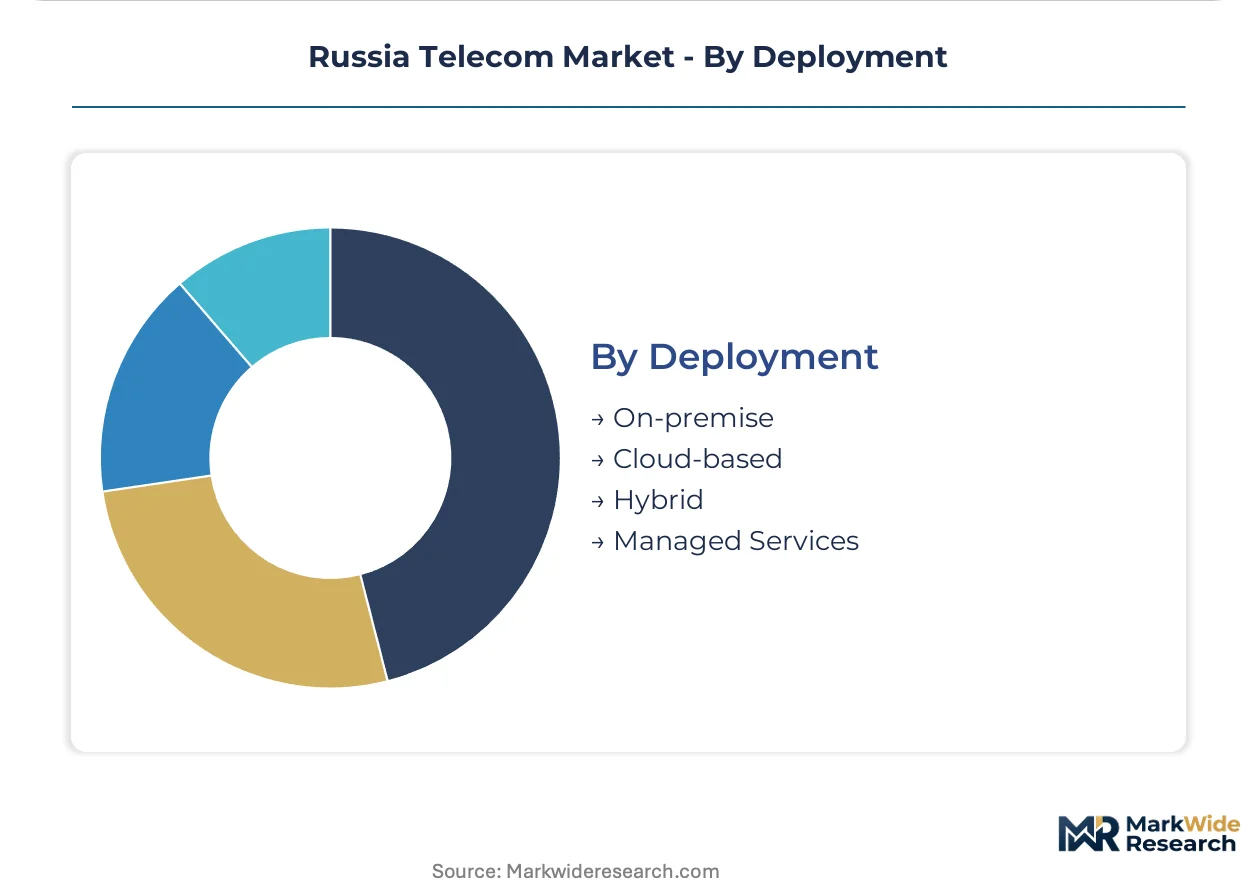
Deployment:
Maturity stages separate legacy on-premise infrastructure from cloud-native delivery models accelerating among capital-constrained enterprise buyers.
- On-premise:Customer-owned switching, routing, and server infrastructure requiring dedicated facilities and operational staff. Declining share reflects enterprise preference for opex-based consumption models.
- Cloud-based:Network functions virtualized and delivered as subscription services from operator data centers. MegaFon's integrated cloud portfolio captures Moscow-based enterprise migrations.
- Hybrid:Mixed architectures preserving sensitive workloads on-premise while bursting non-critical traffic to cloud. Financial services compliance requirements sustain hybrid demand despite full-cloud migration pressure.
- Managed Services:End-to-end network operation outsourced to telecom operators under long-term contracts. Federal agencies favor this model to bypass specialized engineering recruitment challenges.
Installed base concentrates in On-premise; Managed Services climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Moscow and the Central Federal District, where data center buildouts and enterprise cloud migration outpace other territories. Secondary cities follow deployment templates established in the capital, while remote regions depend on subsidized universal service mandates.
Central Federal District
Moscow anchors fiber-optic backbone density and hosts the majority of enterprise managed service contracts. The Ministry of Digital Development channels spectrum allocation priorities toward this district first. Rostelecom's GPON buildouts in Moscow Oblast establish replication models for surrounding oblasts.
Northwestern Federal District
Saint Petersburg concentrates port and industrial corridor demand for operational technology networks with stringent uptime requirements. Federal Security Service encryption mandates filter vendor eligibility for critical infrastructure operators. The city's data center cluster attracts low-latency interconnect investments from Tier-1 operators.
Volga Federal District
Nizhny Novgorod and Kazan drive secondary city fiber deployment following Central District templates. Regional operators replicate GPON coverage models with government-backed Universal Service Obligation funding. Industrial zones in Tatarstan and Samara Oblast generate demand for private 5G campus networks.
Siberian Federal District
Novosibirsk anchors research network demand from universities and technology parks requiring high-capacity connectivity. Ministry of Education programs channel funding toward institution upgrades in secondary cities. Satellite coverage fills gaps beyond fiber economic reach in remote territories.
Far Eastern Federal District
Vladivostok serves as the gateway for transpacific cable landing points and cross-border interconnect capacity. Federal subsidies sustain universal connectivity mandates across sparsely populated Arctic and Pacific territories. The district lags in 5G deployment due to equipment availability constraints and extended procurement cycles.
Russia Telecom Market Competitive Landscape
Moscow-based operators anchor the premium tier; regional specialists hold procurement relationships in secondary federal districts. The market structures around three dominant archetypes: state-backed infrastructure incumbents with universal service mandates, vertically integrated mobile-first groups with fintech and media portfolios, and challenger brands competing on price in saturated urban markets. Competitive moves center on long-term managed service contract consolidation and multi-vendor Open RAN pilot programs to reduce supplier dependency.
Within the state-backed tier, Rostelecom exemplifies the fixed-line infrastructure incumbent model. MegaFon PJSC and Mobile TeleSystems PJSC occupy positions as integrated mobile-first groups diversifying beyond core connectivity. These three anchors represent distinct strategic postures: Rostelecom leverages government mandates for rural fiber extension, MegaFon emphasizes cloud and cybersecurity bundling for enterprise accounts, and MTS pursues vertical integration into adjacent digital services.
| Leading Market Players |
|---|
| Tele2 Russia |
| Yota |
| Mobile TeleSystems PJSC (MTS) |
| Tinkoff Mobile |
| SberMobile |
| MegaFon PJSC |
| Rostelecom |
| MGTS |
| Beeline (PJSC VimpelCom) |
| Others |
Pricing and Supply Chain Analysis
Federal Security Service encryption certification mandates gate qualified supply access and premium-tier pricing eligibility for network operators serving government and critical infrastructure accounts. Equipment vendors lacking FSB hardware approval face exclusion from the highest-margin procurement segments, compressing competitive alternatives and anchoring price premiums for compliant domestic suppliers.
Pricing Analysis
Volume placements concentrate in mass-market mobile and internet tiers where regulatory tariff ceilings compress margins, while premium enterprise connectivity and managed services capture superior returns. Price differentiation rests on Federal Security Service certification status and guaranteed service-level agreement uptime commitments, with banking and energy conglomerates in Moscow showing lowest price sensitivity. Cost compression in consumer mobile segments is intensifying because MegaFon and MTS bundle adjacent digital services to offset connectivity margin erosion. Residential prepaid subscribers exhibit highest price sensitivity, churning aggressively following promotional period expiration.
Supply Chain Analysis
Regional distribution centers in Moscow and Saint Petersburg anchor hub-and-spoke patterns for network equipment deployment across federal districts. Manufacturing concentration sits with China, South Korea, and domestic Russian producers for base station components, optical transceivers, and GPON equipment. Raw material dependencies span gallium nitride semiconductors, fiber-optic preforms, and rare-earth magnet materials for antenna systems. Single-source vulnerability around millimeter-wave base station components creates procurement bottlenecks extending 5G rollout timelines. Distribution runs through Rostelecom's centralized logistics infrastructure and operator-direct procurement channels for large-scale infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
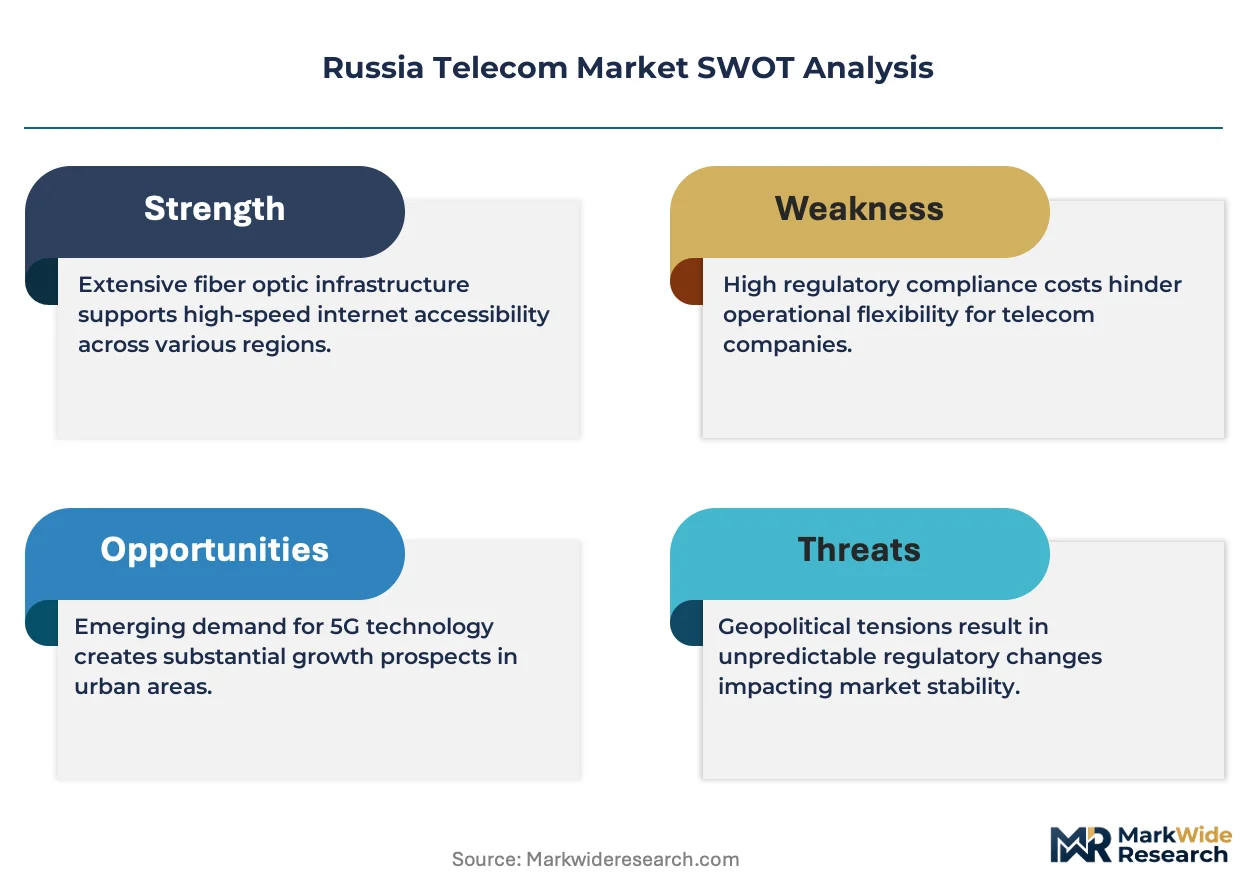
Russia's telecom market functions as a cost-of-compliance story where Federal Security Service hardware certification requirements erect barrier-to-entry moats favoring incumbent operators with established government relationships and approved vendor portfolios.
For Market Incumbents: Lock in long-term managed service contracts with federal agencies and energy conglomerates before import substitution mandates fully mature. Deepen backward integration into domestic equipment procurement channels to insulate margins from foreign supply disruption. MegaFon's integrated cloud portfolio demonstrates how cybersecurity bundling anchors premium enterprise accounts against price-based challengers. For New Entrants and Emerging Players: The price-point gap between premium FSB-certified infrastructure and economy-grade consumer connectivity creates white-space opportunity in mid-market enterprise segments. Secondary cities in the Volga Federal District offer penetrable geography where regional operators lack cloud service integration depth. A go-to-market angle emphasizing hybrid deployment flexibility for financial services compliance requirements bypasses direct confrontation with Rostelecom's universal service mandate. For Investors and Strategic Acquirers: Ministry of Digital Development spectrum allocation announcements are the leading indicator that capital deployment cycles will accelerate or compress. Long-term viability over the coming decade rests on positioning within sovereign internet infrastructure rather than consumer connectivity commoditization. Acquisition targets should display established FSB certification pipelines and concentrated government contract backlogs. The signal to monitor is Rostelecom's GPON extension rate into secondary cities, which forecasts enterprise demand migration patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Pilot Deployment | MegaFon's multi-vendor RAN trials reduce base station supplier dependency while accelerating feature rollout timelines. |
| Managed Service Contract Consolidation | Rostelecom's Universal Service Obligation anchors predictable revenue streams across underserved rural territories. |
| Cybersecurity Service Bundling | FSB encryption standards position compliant operators to capture premium enterprise accounts in Moscow's financial district. |
| Domestic Equipment Certification Investment | Import substitution mandates reward early movers with approved vendor status for critical infrastructure procurement. |
| Edge Computing Node Expansion | Moscow data center buildouts create demand for low-latency fiber interconnects serving enterprise cloud migration. |
Research Methodology
Independent corroboration across network operator procurement executives, Federal Security Service compliance officers, and regional infrastructure vendors underwrites the qualitative findings in this analysis. Primary fieldwork engaged chief technology officers at Tier-1 mobile operators, fixed-line infrastructure planners at Rostelecom, enterprise IT procurement leads at Moscow-based banks, and data center operations directors. Secondary validation drew from Ministry of Digital Development spectrum allocation filings, Federal Antimonopoly Service interconnection rate rulings, customs import data on network equipment, and operator capex disclosures. Bottom-up service revenue modeling triangulated against top-down infrastructure deployment tracking.
Comparable-period anchoring to historical subscriber growth, ARPU evolution, and capital intensity ratios established the forecast baseline across the projection horizon. The analytical framework modeled service type segmentation by mobile, fixed-line, internet, and VoIP; technology layers spanning 4G, 5G, fiber optic, and satellite; and deployment modes including on-premise, cloud-based, hybrid, and managed services. CAGRs derived from equipment shipment trajectories, spectrum utilization efficiency trends, and enterprise cloud adoption velocity. Industry-specific inputs incorporated GPON port deployment rates and FSB hardware certification pipeline backlogs.
Inputs from operator financial disclosures and regulatory filings were available through the study window; gaps in real-time millimeter-wave component production capacity introduce uncertainty bands around 5G deployment velocity assumptions. Forecasts reflect documented assumptions regarding import substitution timeline adherence and sovereign internet infrastructure spending continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
Iceland Telecom Market
Telecommunications
Global 5G Enterprise Market
Telecommunications
Global Dense Wave Digital Multiplexing (DWDM) System Market
Telecommunications
Underwater Modems Market
Telecommunications
Switzerland Telecom Market
Telecommunications
Dialer Market
Telecommunications
IP PBX Market
Telecommunications
Virtualized RAN (Vran) Market
Telecommunications
France Telecom Market
Telecommunications
Utility Communications Market
Telecommunications
Telecom Services Market
Telecommunications
Mobile Fronthaul and Backhaul Market
Telecommunications
5G Equipment Market
Telecommunications
Mission Critical Communication (MCX) Market
Telecommunications
Bahrain Telecom Market