
 Global Telecom Towers Market | 2026-2036
Global Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telecom Towers Market Foresight
Mobile network operators is pivoting toward dense 5G NR deployments, forcing tower designs to accommodate heavier multi-tenant antenna arrays. American Tower Corporation leverages its North American portfolio to anchor long-term lease contracts with major carriers. Indus Towers Limited dominates the Indian subcontinent through aggressive co-location strategies that maximize tenancy ratios per structure.
Global telecom towers are steel or concrete structures engineered to heights between 30 and 150 meters, designed to support multiple antenna systems with wind-load ratings exceeding 200 kilometers per hour while ensuring electromagnetic interference shielding for co-located equipment. Lattice tower configurations sustain margin pools in rural and remote installations where height and durability outweigh aesthetic constraints. Small cell deployments are accelerating fastest in urban corridors, though rooftop installations face zoning friction that camouflage designs navigate through municipal aesthetic compliance.
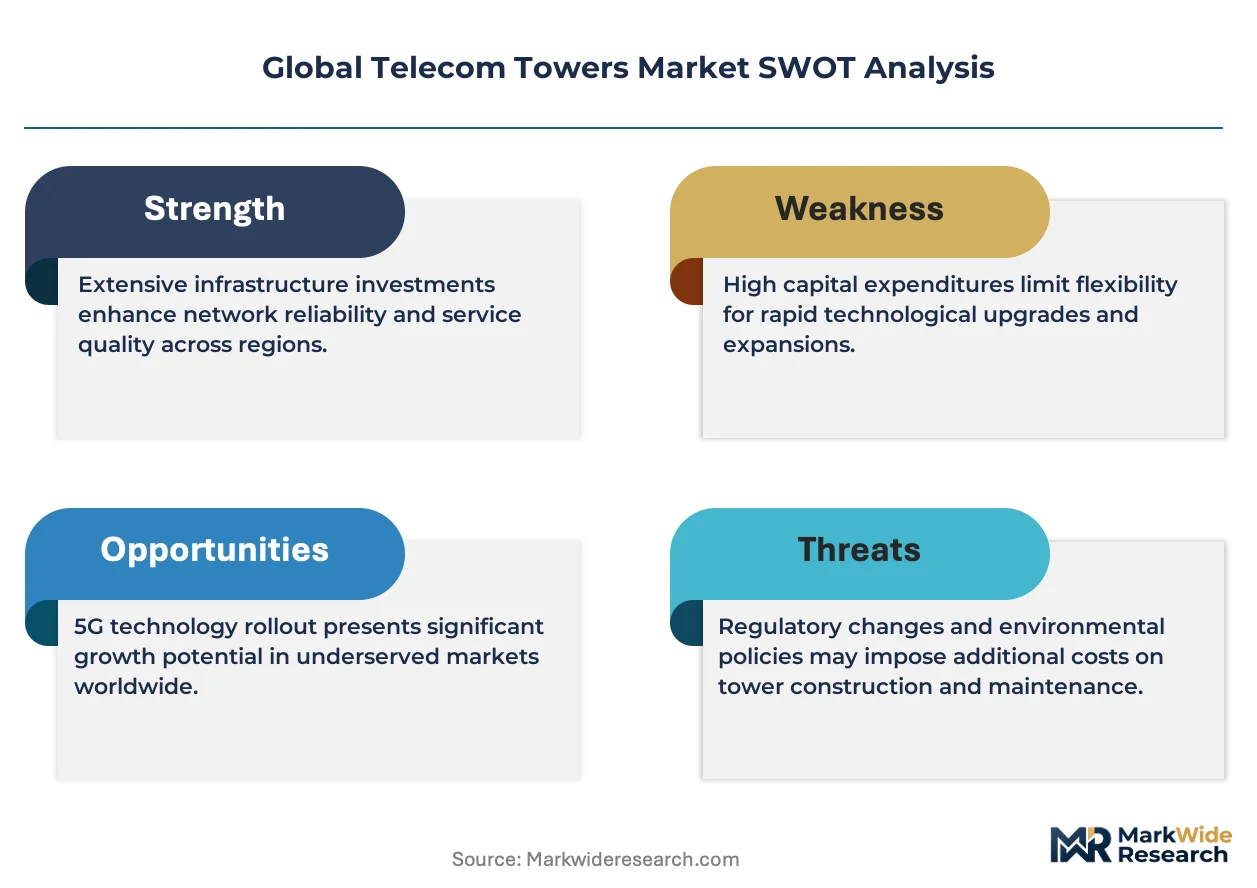
The Federal Communications Commission in the United States enforces RF exposure limits and structural lighting standards that dictate tower placement near residential zones, while India's Department of Telecommunications mandates sharing infrastructure to reduce visual clutter and optimize spectrum efficiency. The European Union's Electronic Communications Code imposes wholesale access obligations that reshape tower ownership economics across member states. Stakeholders must monitor evolving national broadband targets and spectrum auction timelines to align capital deployment with regulatory windows.
Market Dynamics
The migration from 4G to 5G New Radio infrastructure is compressing tower replacement cycles and forcing structural recertification across legacy portfolios. Mobile network operators now prioritize load-bearing capacity over height optimization, reshaping capital allocation patterns for steel lattice and monopole deployments.
Growth Catalysts
- BharatNet Program:India's rural broadband mandate accelerates greenfield tower construction across underserved districts, creating anchor tenancy for multi-operator infrastructure sharing.
- 5G NR Spectrum Auctions:Mid-band allocation in Germany, South Korea, and Brazil compels densification strategies that favor small cell attachments to existing macro structures.
- Steel Alloy Innovation:High-strength low-alloy specifications reduce foundation footprints by 15-20%, enabling faster permitting in environmentally sensitive zones.
Market Restraints
- Zoning Fragmentation:Municipal aesthetic boards in France, Italy, and Spain impose height restrictions and camouflage requirements that extend permitting timelines by 8-14 months.
- Specialized Welding Supply:Certified structural steel fabricators concentrate in China and South Korea, creating geographic single-source vulnerability for lattice tower orders.
- Electromagnetic Interference:Co-location density limits from India's Department of Telecommunications cap tenancy ratios below equipment thermal thresholds.
Strategic Opportunities
- Sub-Saharan Africa:Towercos are penetrating Nigeria, Kenya, and Tanzania where mobile money adoption drives data consumption without legacy copper infrastructure to dismantle.
- Edge Computing Integration:Micro data center enclosures at tower base stations reduce latency for autonomous vehicle networks and industrial IoT clusters.
- Renewable Power Mandates:South Africa's carbon reduction framework subsidizes solar-hybrid tower installations, cutting diesel generator dependency in off-grid locations.
Industry Challenges
- RF Engineer Scarcity:Spectrum planning and interference modeling expertise concentrates among retiring cohorts in North America and Western Europe, constraining deployment velocity.
- Structural Recertification Backlogs:Third-party inspection capacity bottlenecks delay 5G upgrade approvals, particularly for pre-2010 galvanized steel installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telecom Towers Market |
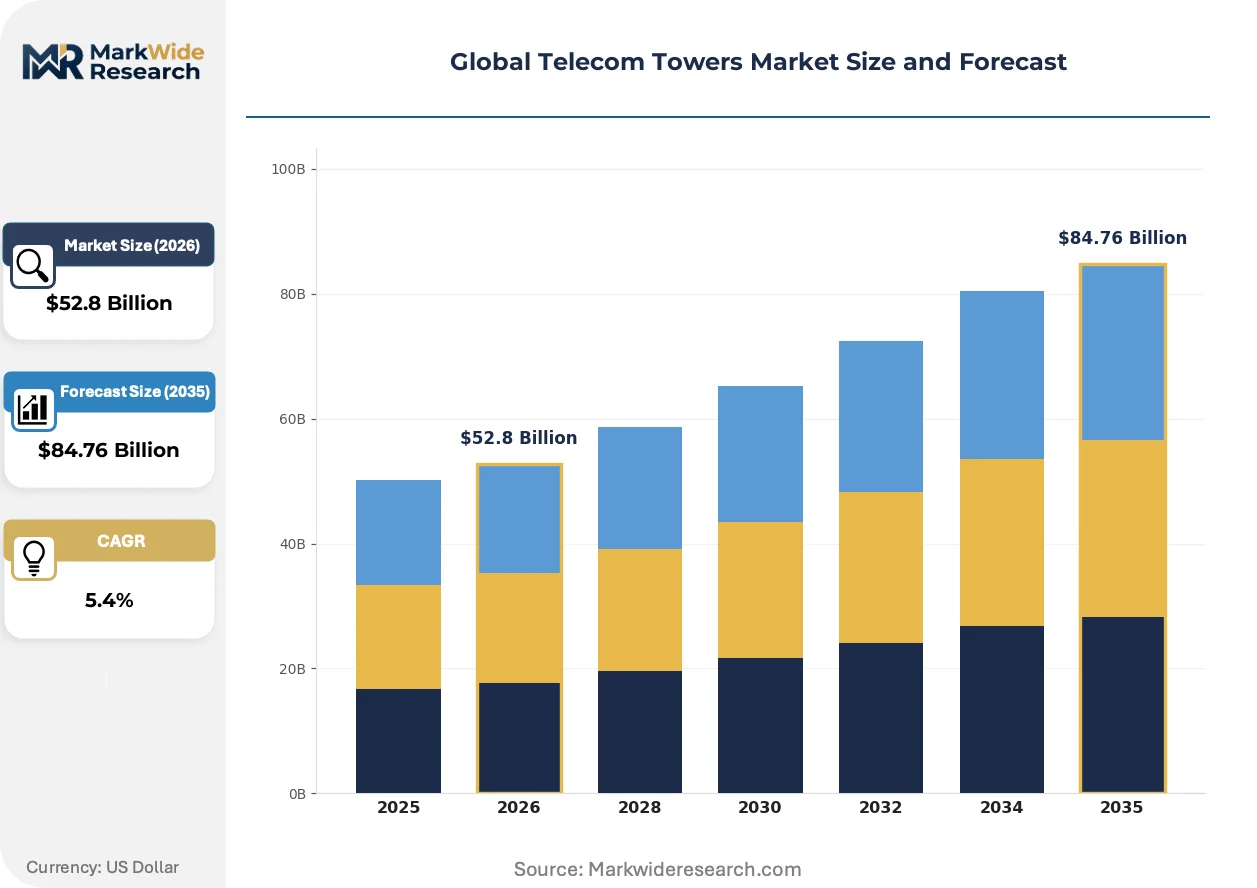
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $84.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tower Type: Monopole, Lattice, Guyed, Rooftop, Camouflage Technology: 4G LTE, 5G NR, Microwave, Fiber Optic, Small Cell Application: Voice Communication, Data Transmission, Internet Services, Emergency Services, Broadcasting End User: Mobile Network Operators, Tower Infrastructure Providers, Government Agencies, Internet Service Providers, Private Enterprises |
| Companies Covered | Indus Towers Limited, Helios Towers PLC, American Tower Corporation, Cellnex Telecom SA, IHS Holding Ltd., China Tower Corporation, Crown Castle International Corp., Phoenix Tower International, SBA Communications Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telecom Towers Market Shifts & Advancements
Active antenna systems and massive MIMO configurations are redrawing tower topology requirements, compressing the physical footprint of radio equipment while multiplying power and cooling loads. Equipment vendors and tower operators now co-design structures rather than retrofitting legacy assets.
Composite reinforcement materials are absorbing shear stress from heavier antenna arrays without adding structural mass. European tower operators in Germany and the Netherlands are piloting carbon fiber-steel hybrid monopoles to extend asset life. This material transition is absorbing capital that previously flowed toward complete steel replacement programs.
The European Union's Electronic Communications Code mandates wholesale infrastructure access, forcing incumbent tower owners to publish standardized co-location pricing. This regulatory pressure is compressing margin structures in France and Spain while accelerating operational separation of network assets from retail operators. Passive infrastructure now trades as regulated utilities rather than proprietary competitive weapons.
Mobile network operators are consolidating vendor relationships and demanding integrated design-build-maintain contracts spanning structural steel, power systems, and fiber backhaul. This bundling preference is displacing fragmented procurement of tower steel, civil works, and electrical installation across separate contracts. The shift is most visible in India's competitive bidding for BharatNet Phase III rural deployments.
Global Telecom Towers Market Segmentation
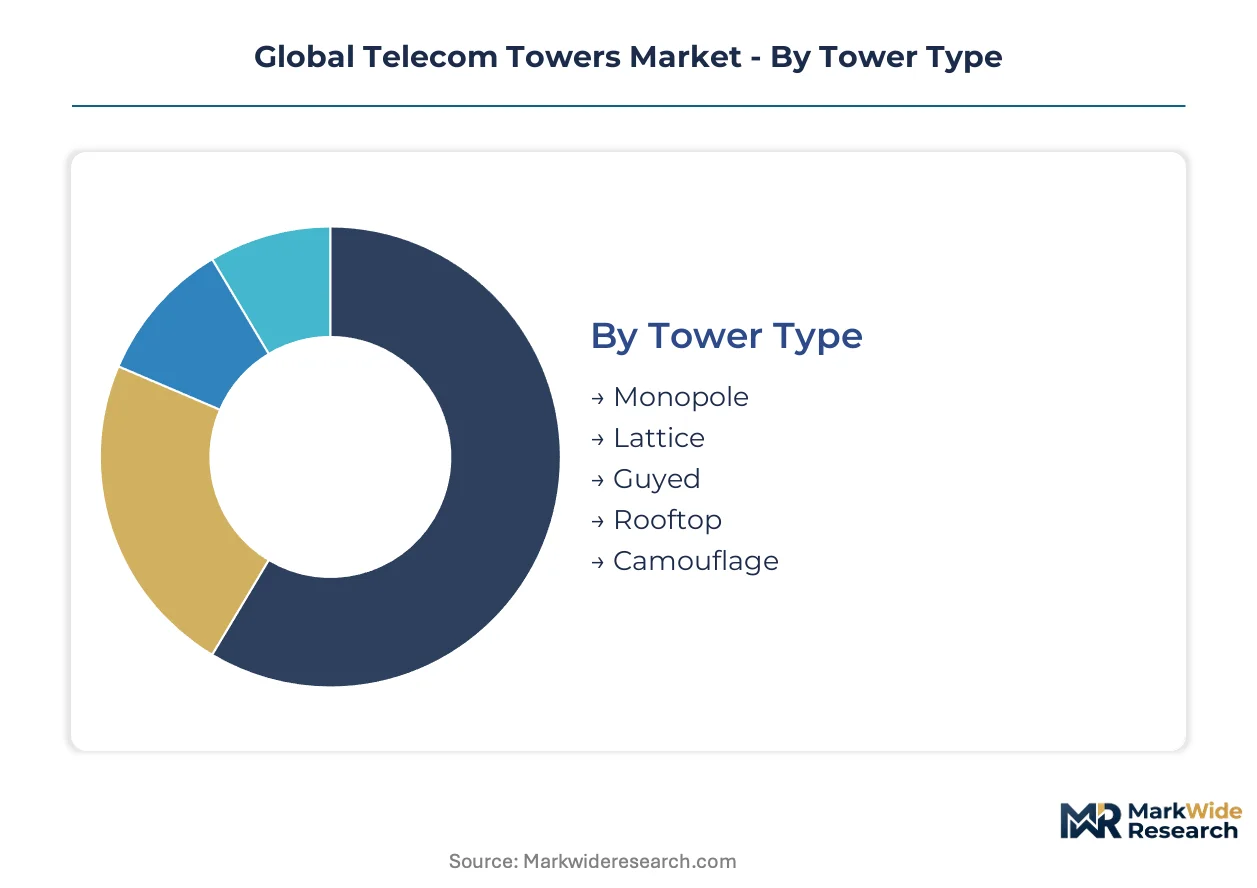
Tower configurations diverge sharply by deployment economics and regulatory environment. Buyers select structures based on load-bearing requirements for multi-tenant antenna arrays, foundation constraints, and municipal aesthetic mandates. Each segmentation dimension reveals distinct procurement patterns across rural, suburban, and urban deployment zones.
Tower Type:
Cost tier separates buyers most decisively in this category, with foundation complexity and steel tonnage driving total installed cost differentials of threefold or more between configurations.
- Lattice:Triangular or square steel frameworks engineered for heights exceeding 80 meters with modular bolted construction. Demand concentrates in India's BharatNet rural corridors and Sub-Saharan African markets where height and wind-load tolerance outweigh aesthetic considerations, though specialized welding supply bottlenecks in East Asia extend lead times.
- Monopole:Tapered steel tubes offering minimal visual footprint and faster municipal permitting in European suburban zones. Germany and the Netherlands are piloting carbon fiber-steel hybrid variants to extend asset life without complete replacement, absorbing capital previously allocated to full steel renewal programs.
- Guyed:Masts stabilized by tensioned cable arrays enabling extreme height at reduced steel weight. Remote broadcasting and microwave backhaul applications in mountainous terrain of Switzerland and Austria favor this cost-optimized configuration.
- Rooftop:Non-ground-based installations leveraging existing building structures. Urban densification in Seoul and São Paulo accelerates deployment, though zoning friction and landlord negotiation complexity constrain velocity.
- Camouflage:Structures disguised as trees, flagpoles, or architectural elements. France, Italy, and Spain mandate these designs near residential zones, extending permitting timelines by 8-14 months but enabling placement otherwise prohibited.
Lattice towers anchor installed volumes across emerging markets; camouflage configurations are gaining share fastest in European regulatory environments.
Technology:
Application maturity creates the dividing line here, with legacy infrastructure carrying sunk costs while next-generation deployments demand structural recertification and power system upgrades.
- 5G NR:New Radio infrastructure supporting massive MIMO and millimeter-wave spectrum. Mid-band spectrum allocations in Germany, South Korea, and Brazil compel densification strategies that favor small cell attachments to existing macro structures, compressing tower replacement cycles.
- 4G LTE:Legacy macro-cell technology still generating revenue through voice and data traffic. Existing installations in India and Indonesia require load-bearing recertification before 5G overlay, creating inspection backlogs for pre-2010 galvanized steel portfolios.
- Small Cell:Low-power nodes deployed at 200-500 meter intervals. Urban corridors in Tokyo and New York absorb the steepest deployment acceleration, though fiber backhaul availability constrains site selection.
- Microwave:Point-to-point radio links for backhaul in fiber-scarce regions. Mountainous terrain in Peru and Nepal maintains demand for line-of-sight tower configurations.
- Fiber Optic:Wired backhaul infrastructure co-located at tower base stations. Tower operators in Nigeria and Kenya bundle fiber access with antenna space to capture integrated connectivity revenues.
4G LTE retains the largest installed base; 5G NR is climbing the fastest as spectrum auctions conclude across major markets.
Application:
Revenue stability varies dramatically by application, with emergency services and broadcasting offering long-term tenancy contracts against volatile consumer data pricing.
- Data Transmission:Mobile internet traffic driving spectrum efficiency requirements. Mobile money adoption in Nigeria, Kenya, and Tanzania accelerates data consumption without legacy copper infrastructure to dismantle, creating greenfield tower demand.
- Voice Communication:Declining but residual 2G/3G circuit-switched services. Rural India and Southeast Asian islands maintain coverage obligations that subsidize uneconomic site economics through universal service funds.
- Internet Services:Fixed wireless access and broadband substitution. South Africa's carbon reduction framework subsidizes solar-hybrid tower installations for off-grid internet delivery, cutting diesel generator dependency.
- Emergency Services:Public safety networks requiring hardened infrastructure with backup power. FirstNet deployments in the United States mandate structural redundancy and 99.999% availability standards.
- Broadcasting:Terrestrial television and radio transmission. Mountainous regions in Switzerland and Austria maintain guyed mast configurations for line-of-sight coverage.
Data transmission dominates revenue contribution; internet services are expanding most quickly as fixed wireless access displaces copper.
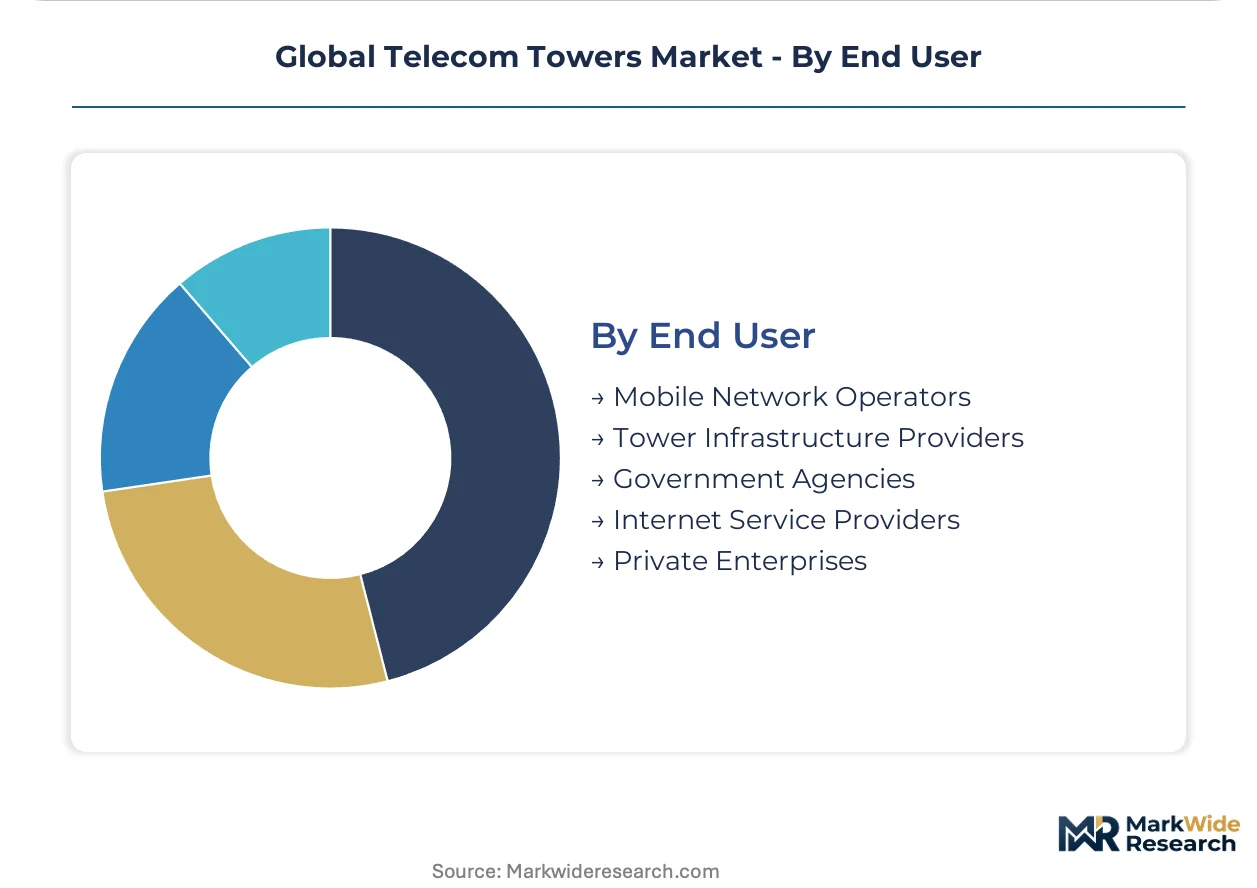
End User:
Balance sheet capacity and regulatory positioning separate buyers, with government mandates forcing infrastructure sharing that alters ownership economics.
- Mobile Network Operators:Carriers divesting tower assets to free capital for spectrum acquisition. India's Department of Telecommunications mandates infrastructure sharing to reduce visual clutter, accelerating operational separation of network assets from retail operations.
- Tower Infrastructure Providers:Independent tower companies maximizing tenancy ratios per structure. Indus Towers Limited dominates the Indian subcontinent through aggressive co-location strategies, while American Tower Corporation anchors long-term lease contracts in North America.
- Government Agencies:Public entities deploying rural broadband and emergency networks. India's BharatNet program creates anchor tenancy for multi-operator infrastructure sharing across underserved districts.
- Internet Service Providers:Fixed-line operators extending wireless coverage. Brazil's regional ISPs lease tower space to bypass last-mile fiber construction in favela and rural zones.
- Private Enterprises:Mining, logistics, and agricultural operators building captive networks. Autonomous vehicle networks and industrial IoT clusters in Germany drive micro data center enclosures at tower base stations for edge computing integration.
Mobile network operators retain the largest historical deployment base; tower infrastructure providers are capturing share fastest as asset divestitures accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting tower fabrication capacity toward jurisdictions with streamlined permitting regimes, as European aesthetic mandates and American RF exposure standards inflate compliance costs relative to Asian manufacturing bases.
India
BharatNet Phase III rural deployments and private operator 5G densification are absorbing record steel volumes for lattice structures. The Department of Telecommunications mandates infrastructure sharing to reduce visual clutter, accelerating tenancy-based revenue models. Tower fabrication clusters in Gujarat and Maharashtra supply galvanized steel to Indus Towers and emerging regional towercos.
United States
FirstNet public safety mandates and mid-band 5G spectrum deployment are forcing structural recertification of pre-2010 installations. The FCC enforces RF exposure limits and structural lighting standards that dictate placement near residential zones. American Tower Corporation anchors long-term lease contracts across the Southeast and Southwest corridors where population density supports multi-tenant economics.
Germany
Mid-band 5G NR spectrum allocation compels densification strategies favoring small cell attachments to existing macro structures. The EU Electronic Communications Code imposes wholesale access obligations that compress margin structures for incumbent tower owners. Carbon fiber-steel hybrid monopole pilots in the Netherlands and western Germany are extending asset life without complete replacement.
Brazil
Regional ISPs lease tower space to bypass last-mile fiber construction in favela and rural zones, driving demand for guyed masts in mountainous terrain. ANVISA coordinates with national telecom regulators on RF safety compliance for dense urban co-location. São Paulo and Rio de Janeiro absorb the steepest small cell deployment acceleration, though fiber backhaul availability constrains site selection.
Nigeria
Mobile money adoption accelerates data consumption without legacy copper infrastructure to dismantle, creating greenfield tower demand across Lagos and Abuja corridors. Towercos penetrate alongside Chinese equipment vendors who bundle structural steel with radio hardware. Solar-hybrid installations subsidized by carbon reduction frameworks are cutting diesel generator dependency in off-grid northern states.
Global Telecom Towers Market Competitive Landscape
Asset divestiture and operational separation dominate the current landscape as mobile network operators monetize passive infrastructure to fund spectrum acquisition. The vendor base concentrates around three strategic archetypes: independent tower companies maximizing tenancy ratios, carrier-captive entities managing legacy portfolios, and emerging market specialists capturing rural build mandates. Competitive positioning hinges on lease contract duration, structural steel procurement scale, and permitting velocity across fragmented municipal jurisdictions.
Among independent tower companies with multi-continental footprints, American Tower Corporation and Cellnex Telecom SA exemplify the tenancy-ratio optimization archetype, while Indus Towers Limited anchors the emerging market infrastructure-sharing model. China Tower Corporation occupies a distinct position as a state-coordinated national monopoly with captive access to domestic steel supply chains. These three entities collectively represent the spectrum of competitive approaches: American Tower emphasizes long-term lease anchoring in regulated North American markets, Cellnex leverages EU wholesale access mandates to consolidate fragmented national portfolios, and Indus deploys aggressive co-location strategies across India's government-mandated sharing regime.
| Leading Market Players |
|---|
| Indus Towers Limited |
| Helios Towers PLC |
| American Tower Corporation |
| Cellnex Telecom SA |
| IHS Holding Ltd. |
| China Tower Corporation |
| Crown Castle International Corp. |
| Phoenix Tower International |
| SBA Communications Corporation |
| Others |
Supply & Pricing Matrix
Steel-grade certification divergence between high-strength low-alloy lattice structures and standard galvanized monopoles manifests in procurement premiums of threefold or more, with certified fabricators in China and South Korea capturing margin pools that European aesthetic-mandate compliance erodes through extended permitting timelines.
Pricing Analysis
Direct-to-towerco volume contracts dominate channel economics, with American Tower Corporation and Indus Towers Limited anchoring decade-long lease structures that insulate against spot steel volatility. Price differentiation separates wind-load-certified installations from standard configurations, while municipal camouflage requirements in France and Italy compress margins through 8-14 month permitting delays. Cost compression in lattice tower procurement intensifies as BharatNet Phase III aggregations consolidate buyer power. Regional ISPs in Brazil exhibit highest price sensitivity, whereas FirstNet-mandated public safety deployments in the United States absorb premium structural redundancy without volume negotiation.
Supply Chain Analysis
Structural steel refurbishment flows from decommissioned 4G installations in India and Indonesia are feeding secondary markets for rural BharatNet deployments, reducing raw material draw from primary mills. Certified welding capacity concentrates in China, South Korea, and Gujarat-based fabrication clusters, with high-strength low-alloy specifications resting on nickel and chromium supply chains vulnerable to export restriction volatility. Distribution runs through towerco-direct procurement and OEM-bundled equipment packages, with American Tower Corporation and Cellnex Telecom SA consolidating vendor relationships into integrated design-build-maintain contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Telecom Towers Market compounds steadily as 5G NR densification mandates structural replacement cycles that regenerate demand regardless of macroeconomic headwinds.
For Market Incumbents: Cement tenancy-ratio leadership through aggressive co-location packaging that captures multi-operator attachments per structure, while deepening backward integration into certified steel fabrication to offset single-source vulnerability from East Asian welding supply concentration. Indus Towers Limited's infrastructure-sharing dominance in India demonstrates how regulatory-mandated sharing regimes can be operationalized into durable competitive moats against emerging regional towercos. For New Entrants and Emerging Players: Digital-channel route partnerships with mobile money platforms in Nigeria, Kenya, and Tanzania unlock greenfield tower demand without legacy copper dismantling costs that burden developed-market entrants. Target Sub-Saharan African corridors where data consumption accelerates through financial inclusion applications rather than subscriber growth alone, positioning solar-hybrid installations as carbon-compliant alternatives to diesel-dependent incumbent portfolios. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented municipal permitting regimes in France, Italy, and Spain compress margins below operational separation thresholds for carrier-captive tower portfolios. Tower infrastructure providers with tenancy-ratio optimization capabilities and streamlined regulatory navigation represent the most viable acquisition archetype. Practitioners should monitor spectrum auction timelines and national broadband target announcements as inflection signals that precede capital deployment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber-Steel Hybrid Monopole Deployment | German and Dutch pilots extend asset life without complete steel replacement, redirecting capital from renewal programs. |
| Integrated Design-Build-Maintain Contract Consolidation | Indian BharatNet Phase III bidding favors bundled procurement that displaces fragmented tower steel and civil works contracts. |
| Solar-Hybrid Tower Installation Scale-Up | South Africa's carbon reduction framework subsidizes off-grid deployments that cut diesel generator dependency. |
| Edge Computing Micro Data Center Integration | German automotive and industrial IoT clusters demand base-station latency reduction for autonomous vehicle networks. |
| Structural Recertification Capacity Expansion | Pre-2010 galvanized steel portfolios in the United States require third-party inspection throughput that bottlenecks 5G upgrade approvals. |
Research Methodology
Direct dialogue with tower infrastructure executives, mobile network operator procurement leads, structural steel fabrication plant managers, and Department of Telecommunications regulatory officials grounded qualitative insights that secondary validation from TRAI circulars, FCC RF exposure rulings, EU Electronic Communications Code implementations, and towerco SEC filings triangulated against bottom-up tenancy-ratio modeling and top-down steel tonnage demand estimates.
Installed base projections across lattice, monopole, and small cell configurations derived from spectrum auction schedules, national broadband targets, and load-bearing recertification backlogs over the projection horizon. Segmentation modeling captured tower type, technology generation, application, and end-user archetype dimensions, with CAGRs calibrated against historical replacement cycles and emerging market penetration curves.
The model assumes a particular technology adoption path; alternative pathways for massive MIMO and millimeter-wave deployment would alter the outlook for structural specifications and power system upgrades. Forecasts reflect assumptions about regulatory stability in India's infrastructure-sharing mandate and the European Union's wholesale access obligations. Practitioners should monitor spectrum auction outcomes, municipal permitting reform announcements, and steel alloy innovation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Carrier Infrastructure in Telecom Applications Market
Telecommunications Infrastructure
Japan Telecom Towers Market
Telecommunications Infrastructure
Terrestrial Trunked Radio (TETRA) System Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
Telecom Network Infrastructure Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Communication Repeater Market
Telecommunications Infrastructure
Mexico Telecom Tower Market
Telecommunications Infrastructure
Germany Telecom Towers Market
Telecommunications Infrastructure
Latin America Telecom Tower Market
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market
Telecommunications Infrastructure
Philippines Telecom Towers Market
Telecommunications Infrastructure
Thailand Telecom Towers Market
Telecommunications Infrastructure
Iraq Telecom Market