
 Myanmar Telecom Market | 2026-2036
Myanmar Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Myanmar Telecom Market Outlook
Multi-source infrastructure procurement is expanding as operators diversify beyond single-vendor network dependencies. MPT leverages its state-backed legacy to sustain nationwide backbone coverage across Myanmar's seven states. Mytel anchors its position through integrated tower assets and defense-affiliated spectrum holdings. ATOM Myanmar competes aggressively on data pricing while navigating foreign ownership constraints.
Myanmar telecom encompasses wireless and wireline communication services delivering voice, data, and internet connectivity through radio frequency spectrum, fiber-optic cable, and copper infrastructure operating across 700 MHz to 3.5 GHz bands. These systems enable commercial transactions, government service delivery, and social coordination across a population where mobile penetration exceeds fixed-line availability by orders of magnitude. Mobile services dominate revenue generation as prepaid subscriptions constitute the primary access mechanism for residential and micro-enterprise users. Value-added services represent the fastest-expanding margin pool as mobile money, content streaming, and cloud connectivity penetrate beyond urban centers. Fixed-line and broadband segments remain structurally constrained by last-mile deployment costs outside Yangon and Mandalay metropolitan zones.
The Posts and Telecommunications Department enforces licensing under Myanmar's Telecommunications Law while the Myanmar Investment Commission screens foreign capital participation in operator equity. Spectrum allocation decisions directly determine which technologies—4G, LTE, or future 5G—operators can deploy in specific geographic license areas. Stakeholders must monitor regulatory shifts around tower sharing mandates and data localization requirements that could reshape capital intensity and competitive parity.
Market Dynamics
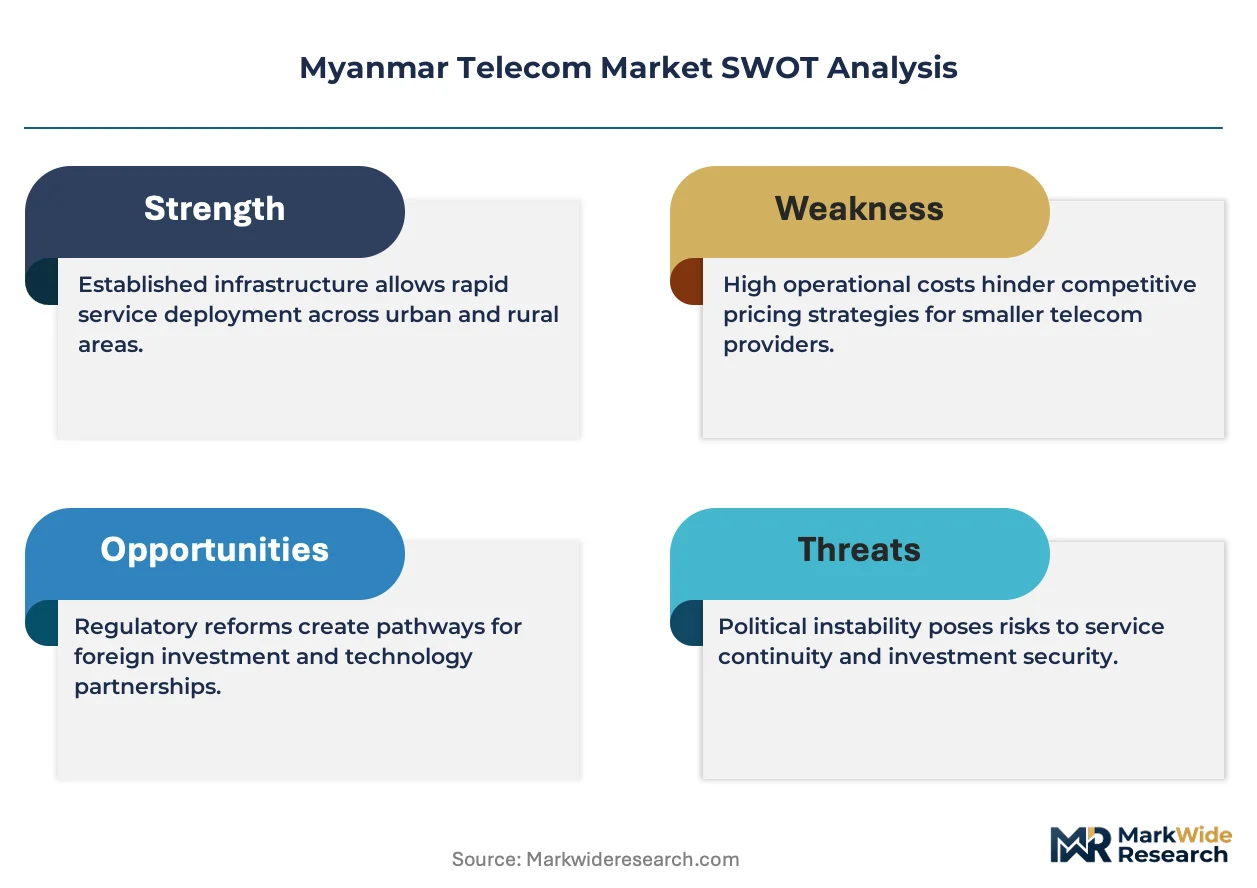
Spectrum scarcity in the 700 MHz to 2.6 GHz bands is forcing operators toward aggressive infrastructure sharing and dynamic spectrum allocation under Posts and Telecommunications Department mandates.
Growth Catalysts
- Rural mobile banking adoption:Agricultural trading platforms and microfinance applications are driving data consumption among smallholder enterprises in Myanmar's central dry zone.
- Telecommunications Law reforms:Licensing streamlining by the Posts and Telecommunications Department is accelerating new entrant spectrum access and tower deployment approvals.
- Fiber backhaul densification:Yangon-Mandalay corridor investments are enabling enterprise-grade broadband uptake in secondary urban centers.
Market Restraints
- Foreign ownership ceilings:Myanmar Investment Commission equity restrictions limit capital inflow for network modernization and 5G preparation.
- Power grid unreliability:Diesel generator dependency at rural tower sites inflates opex and constrains site expansion beyond grid-connected zones.
- Device affordability gap:Low smartphone penetration in Shan and Kachin states restricts ARPU expansion despite network availability.
Strategic Opportunities
- Sagaing and Chin state underpenetration:Sparse competitor presence creates first-mover potential for operators willing to deploy solar-hybrid tower solutions.
- Mobile money convergence:Integration of wallet services with agricultural commodity payments unlocks subscriber stickiness in rural value chains.
- Tower sharing mandates:Proposed infrastructure unbundling regulations would reduce duplicate capex and accelerate rural rollout timelines.
Industry Challenges
- Tower zoning disputes:Municipal permit delays in Yangon townships stall small cell densification needed for capacity relief.
- Legacy 2G/3G sunsetting complexity:Subscriber migration to VoLTE requires handset replacement programs that strain customer acquisition budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myanmar Telecom Market |
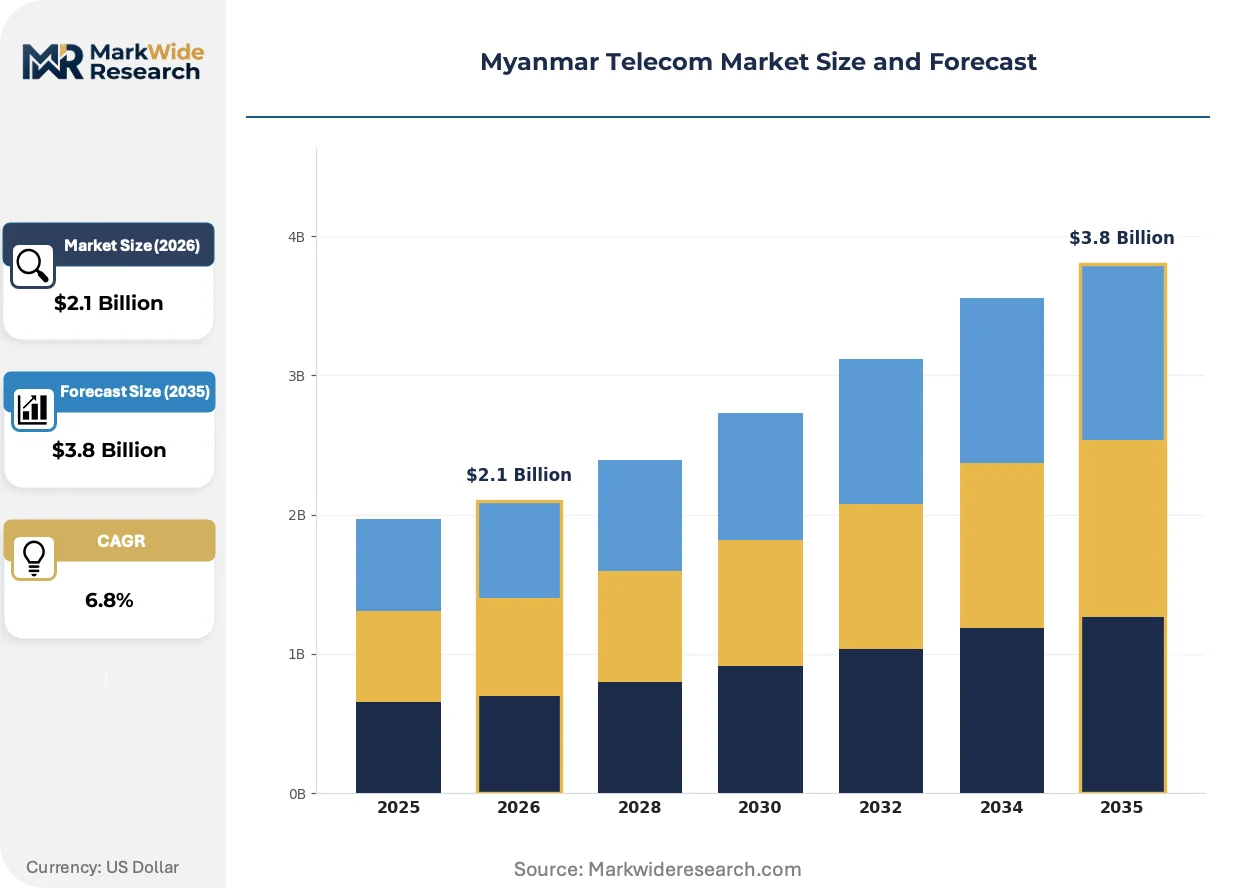
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 4G, 3G, LTE, GSM Service Type: Mobile, Fixed-line, Broadband, Value-Added Services Pricing Model: Prepaid, Postpaid, Bundled Services, Pay-As-You-Go End User: Residential, Enterprises, Government, Public Sector |
| Companies Covered | Myanma Posts and Telecommunications (MPT), Mytel, ATOM Myanmar, Ooredoo Myanmar, Telenor Myanmar, Myanmar Broadband Telecom Co Ltd, Global Technology Company, FRONTIIR Company Limited, Yatanarpon Teleport (YTP), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myanmar Telecom Market Strategic Shifts
Open RAN architectures are disrupting vendor lock-in patterns as operators seek supply chain resilience against equipment sourcing constraints. The shift toward disaggregated hardware and software layers is reshaping procurement criteria and integration timelines.
Virtualized radio access networks are integrating cloud-native baseband processing with commodity hardware to reduce per-site deployment costs. MPT and emerging operators are piloting these architectures in Yangon metro zones to validate interoperability before rural scaling. The technology is integrating multi-vendor management platforms that compress operational complexity and accelerate feature deployment cycles.
Posts and Telecommunications Department spectrum refarming directives are mandating 2.1 GHz reallocation for 4G services ahead of 5G readiness frameworks. This industrial consequence forces accelerated subscriber device refresh programs and network modernization capex commitments. Rural license areas face compressed timelines for compliance, driving tower sharing negotiations among incumbents.
Enterprise procurement of connectivity services is consolidating toward managed service contracts with guaranteed SLA tiers rather than raw bandwidth purchases. System integrators and IT service providers are displacing direct operator relationships in banking and logistics verticals. This pattern is most visible in Mandalay's emerging industrial zones where manufacturing tenants demand bundled security and cloud access.
Myanmar Telecom Market Segmentation
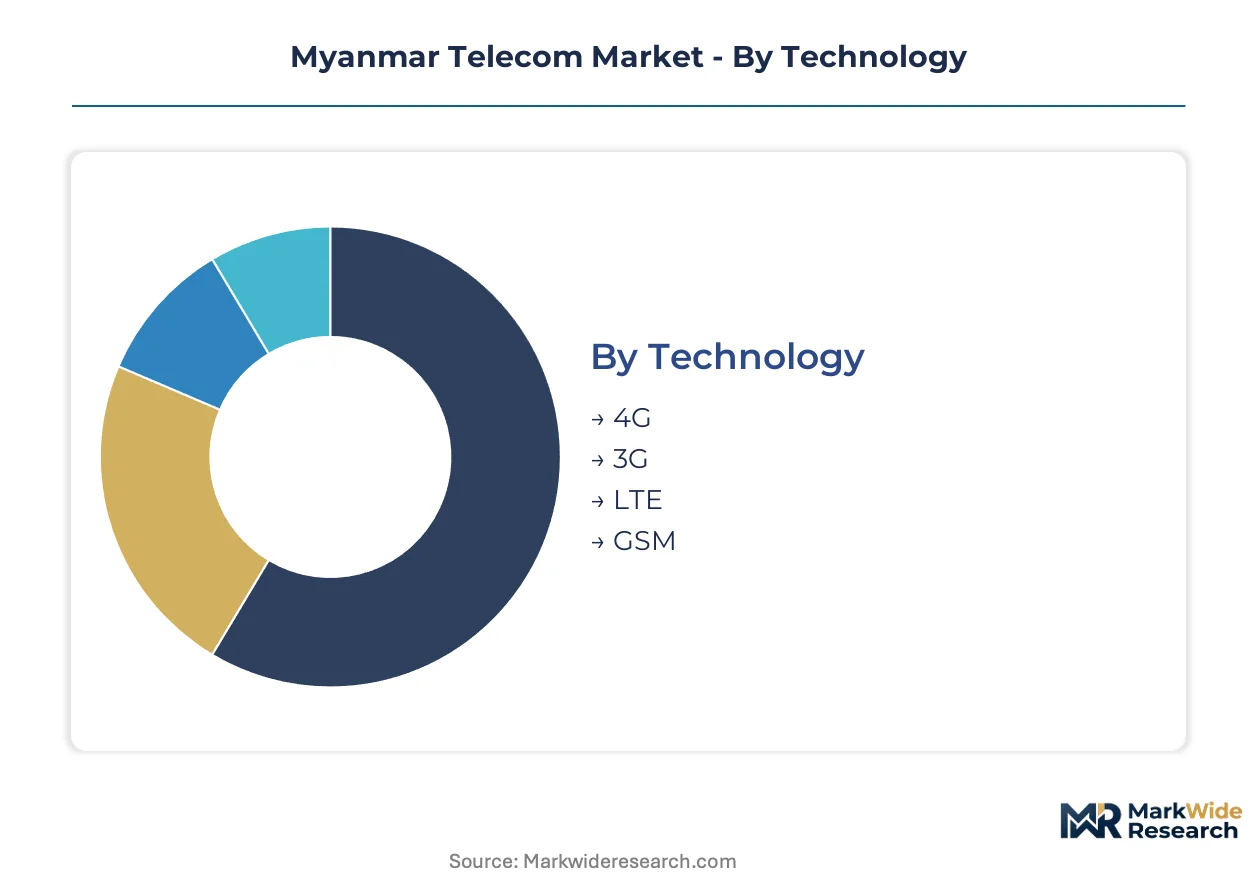
Myanmar's telecom segmentation reveals how infrastructure legacy and regulatory constraints fragment commercial opportunity across technology vintages and service tiers. Operator resource allocation follows these fault lines as spectrum scarcity forces hard choices between urban capacity and rural coverage.
Technology:
Supply concentration in 4G equipment channels investment toward LTE-capable infrastructure while legacy network obligations drain maintenance budgets.
- 4G:Dominant mobile data bearer utilizing 1800 MHz and 2100 MHz bands with carrier aggregation. Yangon and Mandalay corridors absorb the bulk of baseband capacity as enterprise demand for guaranteed throughput intensifies.
- LTE:IP-based packet switching architecture enabling VoLTE voice substitution. Posts and Telecommunications Department refarming mandates are compressing deployment timelines in rural license areas where backhaul fiber remains sparse.
- 3G:Transitional data layer operating on 2100 MHz spectrum. Subscriber migration pressures are accelerating sunsetting discussions among operators balancing opex reduction against handset replacement subsidies.
- GSM:2G voice foundation using 900 MHz spectrum for basic connectivity. Remote townships in Chin and Sagaing states still depend on this layer where smartphone penetration lags network availability.
Today's leader: 4G. Tomorrow's challenger: LTE.
Service Type:
Margin structure varies dramatically by service layer as commoditized voice yields to data and platform economics.
- Mobile:Prepaid-dominated access mechanism serving residential and micro-enterprise users across 700 MHz to 2.6 GHz spectrum. Agricultural trading platforms in the central dry zone are accelerating data consumption among smallholder enterprises previously limited to voice.
- Value-Added Services:Mobile money, content streaming, and cloud connectivity bundles. This layer is expanding most quickly as wallet integration with commodity payments locks subscriber stickiness in rural value chains.
- Broadband:Fixed wireless and fiber-to-the-premises delivering enterprise-grade throughput. Deployment concentrates in Yangon-Mandalay corridor where fiber backhaul density supports SLA-guaranteed contracts.
- Fixed-line:Copper and fiber voice services with structural constraints outside metropolitan zones. Last-mile deployment costs restrict viable addressable market to government and legacy commercial accounts.
Volume concentrates in mobile. Value migrates toward value-added services.
Pricing Model:
Customer liquidity constraints and banking infrastructure gaps determine which pricing mechanisms achieve scale.
- Prepaid:Dominant mechanism requiring zero credit infrastructure. Accounts for the overwhelming share of residential subscriptions as informal sector workers prioritize expenditure control.
- Postpaid:Contract-based billing with credit verification. Enterprises and government entities anchor demand where procurement departments manage centralized telecommunications budgets.
- Pay-As-You-Go:Per-use data and voice without bundle commitment. Appeals to seasonal agricultural workers with irregular income patterns.
- Bundled Services:Converged voice, data, and content packages. Operators deploy these to reduce churn and upgrade ARPU in competitive urban markets.
Cash dominance favors prepaid. Formalization trends favor postpaid.
End User:
Procurement sophistication and SLA requirements segment the addressable market into distinct sales motions.
- Residential:Individual and household consumers purchasing through retail channels. Price sensitivity dominates as informal sector employment limits discretionary communication spending.
- Enterprises:Corporate accounts demanding managed connectivity with security and cloud integration. System integrators are displacing direct operator relationships in banking and logistics verticals.
- Government:Central and state administration contracts for secure communications. Posts and Telecommunications Department oversight shapes procurement specifications and vendor eligibility.
- Public Sector:Health, education, and emergency services with universal service obligations. Rural school connectivity programs and telemedicine initiatives drive subsidized deployment mandates.
Scale sits with residential. Margin sits with enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage shapes infrastructure deployment patterns as operators migrate capital toward sub-regions with streamlined permitting and lower compliance burdens under Posts and Telecommunications Department frameworks.
Yangon Region
Enterprise-grade fiber backhaul densification drives demand from banking and logistics verticals requiring SLA-guaranteed connectivity. The Posts and Telecommunications Department prioritizes spectrum allocation for this corridor under national digital economy directives. Hlaing Tharyar and South Dagon industrial zones anchor tower deployment as manufacturing tenants consolidate procurement toward managed service contracts.
Mandalay Region
Agricultural trading platforms and microfinance applications accelerate data consumption among smallholder enterprises in the central dry zone. Myanmar Investment Commission foreign ownership guidelines shape operator equity structures serving this market. Amarapura and Pyin Oo Lwin sub-regions concentrate baseband capacity expansion where smartphone penetration lags network availability.
Sagaing Region
Sparse competitor presence creates first-mover positioning for operators deploying solar-hybrid tower solutions beyond grid-connected zones. Power grid unreliability forces diesel generator dependency that inflates opex at rural sites. Monywa and Kalay townships represent addressable markets where mobile money convergence with commodity payments could unlock subscriber stickiness.
Shan State
Device affordability gaps restrict ARPU expansion despite network availability across mountainous terrain. The Posts and Telecommunications Department licensing reforms are compressing deployment timelines for new entrant spectrum access. Taunggyi and Lashio municipal clusters concentrate retail channel distribution as seasonal agricultural workers drive pay-as-you-go data purchases.
Rakhine State
Underpenetration in coastal townships creates strategic whitespace for operators willing to absorb higher per-site deployment costs. Tower sharing mandates under proposed infrastructure unbundling regulations would reduce duplicate capex burdens. Sittwe and Kyaukpyu port zones anchor submarine cable landing points that enable international bandwidth aggregation for domestic backhaul.
Myanmar Telecom Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue rural coverage expansion through alternative energy infrastructure. The market structure consolidates around state-affiliated legacy operators and foreign-backed challengers navigating equity restriction frameworks. Three archetypes dominate: nationwide backbone incumbents with tower asset control, price-aggressive data challengers with foreign capital constraints, and regional specialists leveraging municipal permit relationships. Competitive intensity centers on infrastructure sharing negotiations and spectrum refarming compliance timelines.
Within the state-affiliated tier, Myanma Posts and Telecommunications anchors nationwide backbone coverage across seven states through legacy infrastructure assets. Mytel occupies a position integrating defense-affiliated spectrum holdings with captive tower portfolios. ATOM Myanmar exemplifies the foreign-backed challenger archetype competing on data pricing while navigating Myanmar Investment Commission ownership constraints. These three operators collectively represent the competitive fault lines shaping capital allocation between urban capacity densification and rural coverage expansion.
| Leading Market Players |
|---|
| Myanma Posts and Telecommunications (MPT) |
| Mytel |
| ATOM Myanmar |
| Ooredoo Myanmar |
| Telenor Myanmar |
| Myanmar Broadband Telecom Co Ltd |
| Global Technology Company |
| FRONTIIR Company Limited |
| Yatanarpon Teleport (YTP) |
| Others |
Value Chain & Pricing Dynamics
Diesel fuel price volatility at rural tower sites cascades through operator cost structures into subscriber pricing tiers, with Posts and Telecommunications Department rural coverage mandates compressing margin recovery timelines for solar-hybrid infrastructure investments.
Pricing Analysis
Input-cost pass-through from generator fuel and equipment imports shapes a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on fiber backhaul availability and VoLTE certification status. Cost compression in economy tiers is intensifying because diesel logistics inflate opex at off-grid sites. Smallholder agricultural enterprises exhibit highest price sensitivity; banking and logistics verticals show lowest.
Supply Chain Analysis
Myanmar Investment Commission local-content thresholds are redirecting procurement toward ASEAN assembly facilities for baseband units and antenna systems. Equipment sourcing draws from China, South Korea, and Vietnam for radio units, batteries, and fiber cable. Single-source vulnerability concentrates in 4G baseband processor supply. Distribution runs through operator-captive tower portfolios and third-party infrastructure companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Myanmar telecom functions as a stable compounder where rural mobile banking adoption generates recurring data revenue streams resistant to cyclical downturns.
For Market Incumbents: To counter spectrum refarming compliance deadlines, accelerate VoLTE migration subsidies in Chin and Sagaing states while deepening tower sharing negotiations to defray rural capex burdens. For New Entrants and Emerging Players: Municipal permit facilitators in secondary townships unlock whitespace in Rakhine coastal zones and Sagaing solar-hybrid corridors where incumbent presence remains sparse. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists controlling distributed energy infrastructure assets as grid reliability constraints persist.| Strategic Initiative | Industry Significance |
|---|---|
| Solar-Hybrid Tower Deployment | Diesel substitution at off-grid sites cuts opex and extends coverage beyond Posts and Telecommunications Department rural mandates. |
| Open RAN Architecture Pilot | Multi-vendor interoperability trials in Yangon metro zones reduce equipment lock-in and accelerate feature deployment cycles. |
| Mobile Money Platform Integration | Wallet convergence with agricultural commodity payments locks subscriber stickiness in central dry zone value chains. |
| Fiber Backhaul Densification | Yangon-Mandalay corridor investments enable SLA-guaranteed enterprise contracts displacing direct operator relationships. |
| Spectrum Refarming Compliance | 2.1 GHz reallocation for 4G services ahead of 5G frameworks forces accelerated subscriber device refresh programs. |
Study Parameters
Multiple input streams — network infrastructure audits, regulatory filing reviews, and operator procurement disclosures — were reconciled against primary interviews with tower company executives, Posts and Telecommunications Department officials, mobile money platform managers, and rural banking technology leads. Secondary validation incorporated Myanmar Investment Commission foreign ownership records, operator spectrum license databases, and telecommunications equipment import manifests. Bottom-up subscriber projections and top-down infrastructure capacity estimates were cross-referenced.
Historical capex deployment patterns were cross-referenced against panel input from infrastructure planners to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include technology vintage, service tier, pricing mechanism, and end-user procurement sophistication. CAGRs were derived from infrastructure rollout timelines and subscriber upgrade elasticities. Forecast inputs incorporated solar-hybrid deployment cost curves and mobile money transaction volume trajectories.
Revisions become necessary when Posts and Telecommunications Department licensing reforms, Myanmar Investment Commission foreign ownership adjustments, or grid reliability improvements materialize differently than modeled. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
Global GPON Technology Market
Telecommunications
IP Centrex Platforms Market
Telecommunications
Portable Base Station (PBS) Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
Chile Telecom Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
Australia Telecom Market
Telecommunications
Fixed Voice Market
Telecommunications
Hungary ICT Market
Telecommunications
MVNO Market
Telecommunications
Free Space Optics (FSO) Communication Market
Telecommunications
5G in Defense Market
Telecommunications
5G Radio Access Network Market
Telecommunications
TV White Space Spectrum Market
Telecommunications
Spain ICT Market