
 Angola Telecom Market | 2026-2036
Angola Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Angola Telecom Market Insights
Market Context
Mobile money agent networks is rewriting last-mile access economics across Angola's semi-urban corridors. Unitel leverages its tower infrastructure to sustain dominance in prepaid voice and data bundles. Movicel anchors its position through aggressive pricing in secondary cities like Benguela and Lubango. Angola Cables controls the subsea cable landing points that determine international bandwidth costs for all retail providers.
Technical Definition and Structural Segments
Angola Telecom encompasses wireline, wireless, and data transmission infrastructure delivering voice, internet, and digital services across a territory of 1.25 million square kilometers with low population density. Fiber optic backbone deployment connects coastal population centers while satellite technology serves interior provinces where terrestrial rollout remains uneconomical. Mobile service type generates the largest revenue pool as smartphone penetration climbs, yet value-added services including mobile money and cloud hosting represent the fastest-expanding margin segment. Fixed-line infrastructure remains concentrated in government and enterprise end user categories, with residential uptake constrained by installation costs and informal settlement geography.
Regulatory Framework and Outlook
INACOM governs licensing, interconnection rates, and universal service obligations, while the Angolan Ministry of Telecommunications and Information Technology sets broadband penetration targets that shape operator capex priorities. The country's national cybersecurity framework and data protection standards, aligned with SADC regional guidelines, impose compliance costs that favor larger operators with dedicated legal and technical teams. Stakeholders must monitor spectrum auction timelines and infrastructure sharing mandates that will determine whether new entrants can challenge the incumbent duopoly structure.

Market Dynamics
INACOM's spectrum reallocation mandate is compressing the rural coverage gap by reallocating sub-1 GHz bands for 4G LTE expansion, forcing operators to rebalance capital between Luanda density plays and interior province buildouts.
Growth Catalysts
- Mobile financial services penetration:Agent networks are extending transactional banking to unbanked populations across semi-urban corridors, creating stickiness in prepaid subscriber bases.
- Subsea cable infrastructure:Angola Cables controls international bandwidth landing points, reducing wholesale data costs for retail providers and enabling competitive data bundle pricing.
- National cybersecurity framework:Compliance alignment with SADC regional guidelines is accelerating enterprise cloud adoption as data localization requirements mature.
Market Restraints
- Terrestrial fiber economics:Low population density across 1.25 million square kilometers renders interior fiber deployment structurally unprofitable without universal service subsidies.
- Import dependency for equipment:Network hardware and smartphone supply chains concentrate in Asian manufacturing hubs, exposing operators to currency volatility and shipping friction.
- Informal settlement geography:Luanda's musseques lack formal addressing and property rights, blocking standardized last-mile installation workflows.
Strategic Opportunities
- Huíla and Namibe provinces:Secondary cities like Lubango show rising smartphone penetration with limited fixed-line competition, creating greenfield mobile data markets.
- Enterprise cloud hosting:Government digitization mandates are displacing on-premise server infrastructure in ministries and state-owned enterprises.
- Satellite-backhauled rural cells:Convergence of geostationary capacity with solar-powered base stations enables commercial service in previously uneconomic localities.
Industry Challenges
- RF engineering talent scarcity:Spectrum optimization and network planning functions lack sufficient trained personnel within Angola's technical education pipeline.
- Legacy copper infrastructure:Angola Telecom's aging fixed-line plant requires costly maintenance while generating declining revenue, complicating capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angola Telecom Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Fixed-Line, Internet, Value-Added Services Technology: 4G LTE, Fiber Optic, DSL, Satellite End User: Residential, Business, Government, Non-Profit Pricing Model: Prepaid, Postpaid, Bundled Packages, Freemium |
| Companies Covered | Unitel, Movicel, Angola Telecom, Africell, TV Cabo, Angola Cables, MS Telecom, Mercury Telecom, Startel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angola Telecom Market Trends and Innovations
Network architecture decisions are pivoting from coverage-centric builds to capacity-layer investments, with virtualization and edge computing displacing traditional hardware-heavy deployment models across both mobile and fixed infrastructure.
Open RAN architectures are hybridizing vendor ecosystems by decoupling radio hardware from baseband software, allowing operators to mix suppliers and reduce single-source dependency. MNO procurement teams are piloting multi-vendor configurations in Luanda test zones. This technology is hybridizing traditional equipment procurement patterns and compressing long-term maintenance contract values.
INACOM's infrastructure sharing mandates are forcing co-location agreements on cell towers and fiber ducts, reducing duplicate civil works in dense urban corridors. The regulatory pressure is accelerating standardized interconnection pricing frameworks. Mobile operators in Luanda Province are responding by consolidating passive infrastructure into joint venture structures.
Enterprise buyers are unbundling connectivity from managed services, procuring raw bandwidth through wholesale arrangements while retaining internal IT control. Systems integrators and direct carrier sales teams are losing share to self-service portal models. This pattern is most visible in oil and gas sector headquarters seeking cost transparency for multi-site WAN contracts.
Angola Telecom Market Segmentation
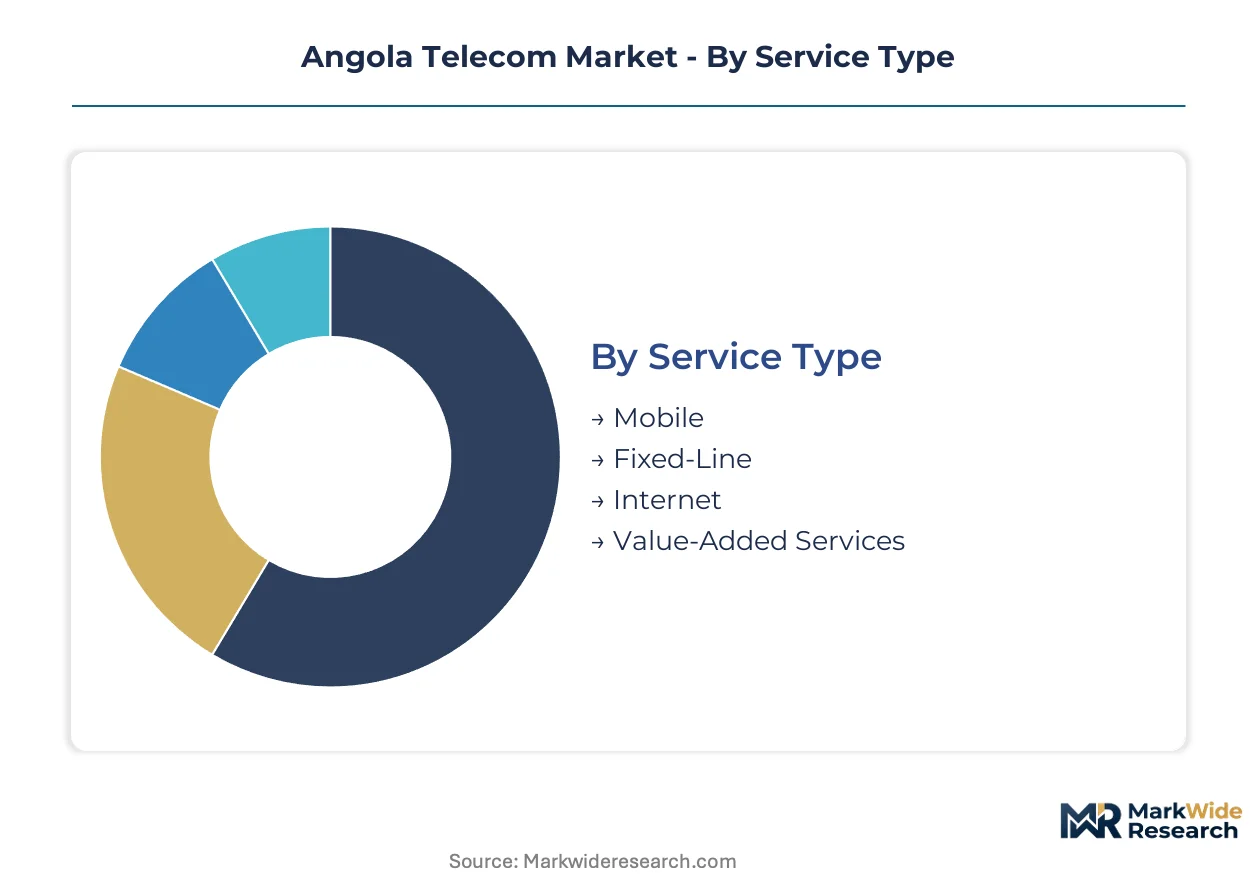
Service heterogeneity across Angola's 1.25 million square kilometer territory demands granular segmentation to match infrastructure economics with subscriber willingness-to-pay. Operators must align technology deployment with settlement density and formal property rights to capture value across divergent consumption patterns.
Service Type:
After-sales service intensity varies dramatically across service categories, with mobile requiring dense agent networks for SIM replacement and airtime top-up versus fixed-line demanding truck-roll maintenance for copper plant failures.
- Mobile:Wireless voice and data services delivered through cellular base stations dominate subscriber counts. Luanda Province concentrates smartphone-driven data consumption as Unitel and Movicel compete on prepaid bundle pricing.
- Internet:Dedicated data connectivity spans fiber-to-the-premises, fixed wireless, and mobile broadband variants. Enterprise demand in oil and gas headquarters drives premium leased-line contracts with strict SLAs.
- Fixed-Line:Legacy copper-based voice services and limited fiber deployments serve government offices and formal businesses. Installation costs and musseques geography constrain residential expansion outside central Luanda.
- Value-Added Services:Mobile money, cloud hosting, and enterprise managed services generate expanding margins. INACOM's data localization requirements accelerate ministry and SOE cloud migration timelines.
Mobile holds the largest share; momentum sits with Value-Added Services.
Technology:
Capital intensity and operational complexity stratify sharply across technology layers, with fiber demanding trenching rights-of-way while satellite enables rapid rural coverage without terrestrial infrastructure.
- 4G LTE:Mobile broadband standard deployed across coastal population centers and expanding into interior provinces via sub-1 GHz spectrum reallocation. INACOM's rural coverage mandates accelerate base station buildouts in Huíla and Namibe.
- Fiber Optic:High-capacity backbone and last-mile deployments connecting Luanda enterprise clusters. Angola Cables' subsea landing points reduce international bandwidth costs that flow through to retail pricing.
- Satellite:Geostationary and emerging LEO solutions serve uneconomic interior localities. Solar-powered rural cells with satellite backhaul now achieve commercial viability in previously unserved provinces.
- DSL:Copper-pair based broadband leveraging Angola Telecom's legacy fixed-line plant. Aging infrastructure requires costly maintenance while subscriber migration to wireless alternatives accelerates.
Fiber Optic commands premium pricing; 4G LTE shows the steepest expansion trajectory.
End User:
Procurement sophistication and contract scale diverge substantially across end-user categories, with government tenders requiring extensive compliance documentation versus residential prepaid transactions completed through informal agent networks.
- Residential:Individual and household subscribers purchasing prepaid mobile services primarily. Benguela and Lubango secondary cities exhibit rising smartphone penetration with limited fixed-line competition.
- Business:Corporate entities procuring multi-site WAN connectivity and managed services. Oil and gas sector headquarters unbundle connectivity from IT services to retain cost transparency.
- Government:Ministries and state-owned enterprises subject to digitization mandates. National cybersecurity framework compliance favors operators with dedicated legal and technical teams.
- Non-Profit:NGOs and international organizations operating across remote provinces. Satellite-dependent connectivity requirements align with humanitarian logistics footprints.
Business generates highest ARPU; Government contracts are climbing the fastest.
Pricing Model:
Working capital requirements and churn exposure vary across pricing structures, with prepaid eliminating receivables risk while postpaid enables service differentiation through device financing and loyalty programs.
- Prepaid:Pay-in-advance model dominating mobile subscriber acquisition. Agent network density in semi-urban corridors enables cash-based transactions among unbanked populations.
- Postpaid:Monthly billing with credit checks and contract terms. Enterprise and affluent residential segments prefer predictable costs and premium customer service channels.
- Bundled Packages:Combined voice, data, and content offerings reducing price transparency. Unitel leverages tower infrastructure to sustain bundle competitiveness against Movicel's aggressive secondary-city pricing.
- Freemium:Basic service tiers with paid upgrades for enhanced features. Mobile money platforms deploy zero-rated transfers to build transaction volume before monetizing advanced financial products.
Prepaid captures volume leadership; Bundled Packages gain share fastest.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Luanda-Benguela railway corridor and the Soyo oil terminal anchor Angola's coastal infrastructure spine, while the Lobito Atlantic Corridor positions the country as a regional logistics bridge connecting interior mining provinces to Atlantic shipping lanes.
Luanda Province
Smartphone penetration and enterprise connectivity investments concentrate in this coastal metropolitan zone. INACOM's spectrum reallocation mandates accelerate 4G LTE base station density in musseques informal settlements. The capital's fiber optic backbone attracts oil and gas sector headquarters seeking premium leased-line contracts with strict SLAs.
Benguela Province
Rising mobile data consumption in secondary city corridors drives infrastructure competition between prepaid bundle providers. The national telecommunications regulator enforces infrastructure sharing mandates on cell towers to reduce duplicate civil works. Lobito port's logistics ecosystem generates demand for enterprise WAN connectivity from shipping and customs clearance operations.
Huíla Province
Lubango's limited fixed-line competition creates greenfield opportunities for mobile data market expansion. Sub-1 GHz spectrum reallocation enables 4G LTE rural coverage buildouts mandated by universal service obligations. Solar-powered base stations with satellite backhaul achieve commercial viability in this interior plateau region.
Namibe Province
Port infrastructure and fishing industry clusters generate concentrated demand for maritime connectivity solutions. The Ministry of Telecommunications and Information Technology's broadband penetration targets shape operator capital expenditure priorities in this coastal province. Desert geography favors fixed wireless and satellite solutions over terrestrial fiber deployment.
Cabinda Province
Offshore oil production enclaves require specialized telecommunications infrastructure for platform and logistics coordination. Data localization requirements under the national cybersecurity framework accelerate ministry cloud migration timelines in this administratively distinct territory. Satellite-dependent connectivity dominates due to geographic isolation from mainland fiber networks.
Angola Telecom Market Competitive Landscape
On the supply side, the industry is structured around a duopoly core with emerging challengers and infrastructure specialists occupying adjacent positions. Mobile network operators compete through prepaid bundle pricing and tower infrastructure leverage, while wholesale bandwidth providers control international connectivity economics. Two strategic archetypes dominate: integrated national operators with legacy fixed-line assets, and mobile-focused challengers with lean cost structures. Competitive moves concentrate on infrastructure sharing joint ventures and spectrum positioning ahead of anticipated auction timelines.
Within the integrated operator tier, Unitel and Angola Telecom exemplify contrasting strategic postures toward legacy asset utilization versus wireless-centric growth. Among mobile challengers, Movicel occupies a position defined by aggressive secondary-city pricing. Angola Cables anchors the wholesale infrastructure segment through subsea cable landing point control. These three entities collectively represent the supply-side configuration shaping retail pricing and coverage expansion trajectories.
| Leading Market Players |
|---|
| Unitel |
| Movicel |
| Angola Telecom |
| Africell |
| TV Cabo |
| Angola Cables |
| MS Telecom |
| Mercury Telecom |
| Startel |
| Others |
Pricing and Supply Chain Analysis
Luanda's fiber optic landing points and tower infrastructure clusters concentrate supply-side capacity, granting Angola Cables and integrated operators asymmetric leverage over wholesale bandwidth pricing and downstream retail bundle rates across coastal metropolitan zones.
Pricing Analysis
Volume-discount tiering structures dominate enterprise connectivity procurement, with oil and gas headquarters negotiating multi-site WAN contracts at scale while residential prepaid subscribers face rigid per-MB rates. Price differentiation rests on SLA stringency and installation geography, with musseques informal settlements incurring premium truck-roll costs. Pricing pressure stems from Movicel's aggressive secondary-city positioning in Benguela and Lubango. Government tenders exhibit lowest price sensitivity due to digitization mandate compliance requirements.
Supply Chain Analysis
Supplier-financing facilities from Asian equipment manufacturers extend payment terms for network hardware procurement, easing currency volatility exposure for Angolan operators. Manufacturing concentrates in China, South Korea, and Taiwan for base stations, fiber optic cable, and smartphones. Raw material dependencies span rare earth elements for radio frequency components, copper for legacy plant maintenance, and lithium for solar-powered rural cell backup systems. Single-source vulnerability runs through subsea cable landing point control. Distribution runs through operator-direct procurement with limited channel intermediation.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Angola's telecom market sits at a platform-economics inflection where mobile money interoperability and Open RAN vendor disaggregation are rewiring competitive moats around ecosystem control rather than physical infrastructure alone.
For Market Incumbents: Pre-empt infrastructure commoditization by consolidating passive tower assets into joint ventures with standardized interconnection pricing, while accelerating vertical integration into enterprise cloud hosting to capture ministry digitization spend. Movicel's pricing aggression in secondary cities and INACOM's infrastructure sharing mandates threaten legacy margin structures. Fiber backbone leverage and spectrum positioning remain critical defensive levers. For New Entrants and Emerging Players: Huíla Province's greenfield mobile data opportunity offers lowest competitive density among penetrable geographies, with Lubango's limited fixed-line competition and rising smartphone penetration creating addressable white space. Satellite-backhauled rural cells in Namibe's desert corridors and Cabinda's isolated oil enclaves present second-tier targets. A wholesale bandwidth resale model bypassing capex-heavy terrestrial builds offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mobile money platform operators with dense agent networks, as transaction-based monetization builds predictable fee streams detached from volatile ARPU competition. Long-term viability favors infrastructure-light challengers with spectrum flexibility and regulatory compliance capabilities. The signal to watch is INACOM's auction timeline for sub-1 GHz bands, which would signal entry window viability for third-mobile-player consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Infrastructure Sharing Joint Venture | Consolidates passive tower assets under INACOM mandate, reducing duplicate civil works in Luanda density corridors. |
| Mobile Money Platform Integration | Interoperability with banking networks deepens stickiness among unbanked rural populations via agent network density. |
| Open RAN Pilot Deployment | Multi-vendor radio configurations in Luanda test zones reduce single-source dependency on legacy equipment suppliers. |
| Satellite-Backhauled Rural Expansion | Solar-powered base stations with geostationary links unlock commercial viability in Huíla and Namibe interior provinces. |
| Enterprise Cloud Hosting Buildout | Data localization compliance under national cybersecurity framework captures ministry and SOE server migration demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with network engineering directors, INACOM regulatory affairs leads, enterprise IT procurement managers at oil and gas headquarters, mobile money platform operations heads, and satellite connectivity specialists. Secondary validation drew from INACOM spectrum allocation filings, Angola Cables subsea capacity disclosures, Ministry of Telecommunications broadband penetration targets, SADC regional cybersecurity guideline documents, and operator capex announcements. Bottom-up subscriber and revenue modeling triangulated against top-down macroeconomic and regulatory scenario analysis.
Calibration against historical penetration curves and infrastructure deployment timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology layer, end-user category, and pricing structure, with provincial population density and formal property rights geography as Angola-specific modifiers. CAGRs were derived from fitted growth curves adjusted for spectrum auction timing and universal service obligation enforcement intensity. Forecast inputs incorporated smartphone adoption elasticity and international bandwidth cost trajectories.
Practitioners should monitor INACOM auction timelines, currency volatility against the kwanza, and subsea cable capacity expansion announcements for early signals of competitive inflection. Forecasts reflect documented assumptions about regulatory enforcement consistency and infrastructure subsidy continuity. Macroeconomic instability, accelerated spectrum reallocation, or satellite-to-terrestrial substitution breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Telecom Operations Management Market
Telecommunications
Carrier Aggregation Solutions Market
Telecommunications
Bahrain Telecom Market
Telecommunications
5G Monetization Market
Telecommunications
Global Esim Market
Telecommunications
Cloud Telephony Service Market
Telecommunications
Poland Telecom Market
Telecommunications
Cambodia ICT Market
Telecommunications
Private Branch Exchange Market
Telecommunications
Cambodia Telecom Market
Telecommunications
Standalone 5G Network Market
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
Chile Telecom Market
Telecommunications
Competitive Local Exchange Carriers (CLEC) Market
Telecommunications
Global Small Cell 5G Network Market