
 TD-LTE Ecosystem Market | 2026-2036
TD-LTE Ecosystem Market Size, Share, and Industry Trends Forecast 2026-2036
TD-LTE Ecosystem Market Outlook
Chinese base station manufacturing capacity is shifting toward integrated small-cell architectures. Huawei Technologies leverages its domestic supply chain depth to sustain cost advantages in macro base station deployments. Ericsson anchors its position through R&D intensity in massive MIMO configurations for dense urban environments. Nokia Corporation differentiates via its AirScale portfolio, which specializes in cloud-native radio access architectures.
The TD-LTE ecosystem comprises the integrated hardware, software, and services enabling Time Division Duplex Long Term Evolution wireless communications, operating in paired spectrum allocations with subframe configurations optimized for asymmetric uplink-downlink traffic patterns. Its primary commercial purpose is delivering high-speed mobile broadband in markets where TDD spectrum assignments predominate, particularly across unpaired frequency bands in Asia and emerging economies. Network Solutions commands margin pools as operators virtualize core functions, while User Equipment competes on chipset efficiency where MediaTek and Qualcomm drive integration density. IoT Connectivity represents the fastest-growing application segment as utility and industrial sensors migrate from legacy 2G networks.
China's MIIT enforces domestic GB standards and dual carbon goals that shape base station power efficiency mandates, while India's TRAI spectrum auction frameworks directly determine operator capex timing and vendor selection criteria. The EU AI Act and CSRD reporting requirements increasingly influence how European telecom operators evaluate supplier ESG credentials in procurement decisions. Stakeholders must monitor TDD spectrum refarming announcements and 5G non-standalone migration timelines to calibrate TD-LTE equipment lifecycle investments.
Market Dynamics
Spectrum refarming timelines and 5G non-standalone migration schedules compress TD-LTE equipment replacement cycles, forcing vendors to optimize for transitional coexistence architectures rather than greenfield deployments.
Growth Catalysts
- Rural Broadband Mandates:India's BharatNet initiative and comparable programs in Indonesia and Bangladesh accelerate base station procurement for unserved districts. Government subsidies reduce operator capex barriers.
- Industrial IoT Migration:Utility and manufacturing sectors replace 2G sensor networks with TD-LTE modules. China's MIIT spectrum policies reserve unpaired bands for machine-type communications.
- Energy Efficiency Standards:Dual carbon goals in China enforce GB-compliant base station power consumption thresholds. Equipment refresh cycles shorten as older hardware fails efficiency audits.
Market Restraints
- Semiconductor Supply Concentration:Advanced baseband processor fabrication concentrates in Taiwan and South Korea foundries. Geopolitical friction threatens equipment delivery schedules.
- 5G Substitution Pressure:Non-standalone 5G overlays in urban cores reduce TD-LTE capacity expansion requirements. Operators defer 4G investments where 5G spectrum is already cleared.
- Input Cost Volatility:Gallium nitride and silicon carbide substrate prices fluctuate with electric vehicle demand. RF component costs pressure macro base station margins.
Strategic Opportunities
- Private Network Deployments:Mining and port operators in Indonesia and Vietnam adopt TD-LTE for campus-wide coverage. Spectrum leasing frameworks in Southeast Asia enable enterprise direct procurement.
- Multi-RAT Convergence:Software-defined radio platforms unify TD-LTE and 5G NR processing. This architecture extends equipment lifecycles through firmware upgrades rather than hardware swaps.
- Carbon Border Adjustments:EU CBAM and CSRD reporting requirements favor suppliers with documented supply chain emissions. Chinese vendors with verified green manufacturing credentials gain procurement preference.
Industry Challenges
- RF Engineering Talent Scarcity:Massive MIMO beamforming and mmWave integration require specialized signal processing expertise. Southeast Asian operators compete with semiconductor firms for limited talent pools.
- Legacy System Interoperability:TD-LTE core networks must maintain backward compatibility with 2G/3G signaling protocols for voice fallback. Testing matrices multiply certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TD-LTE Ecosystem Market |
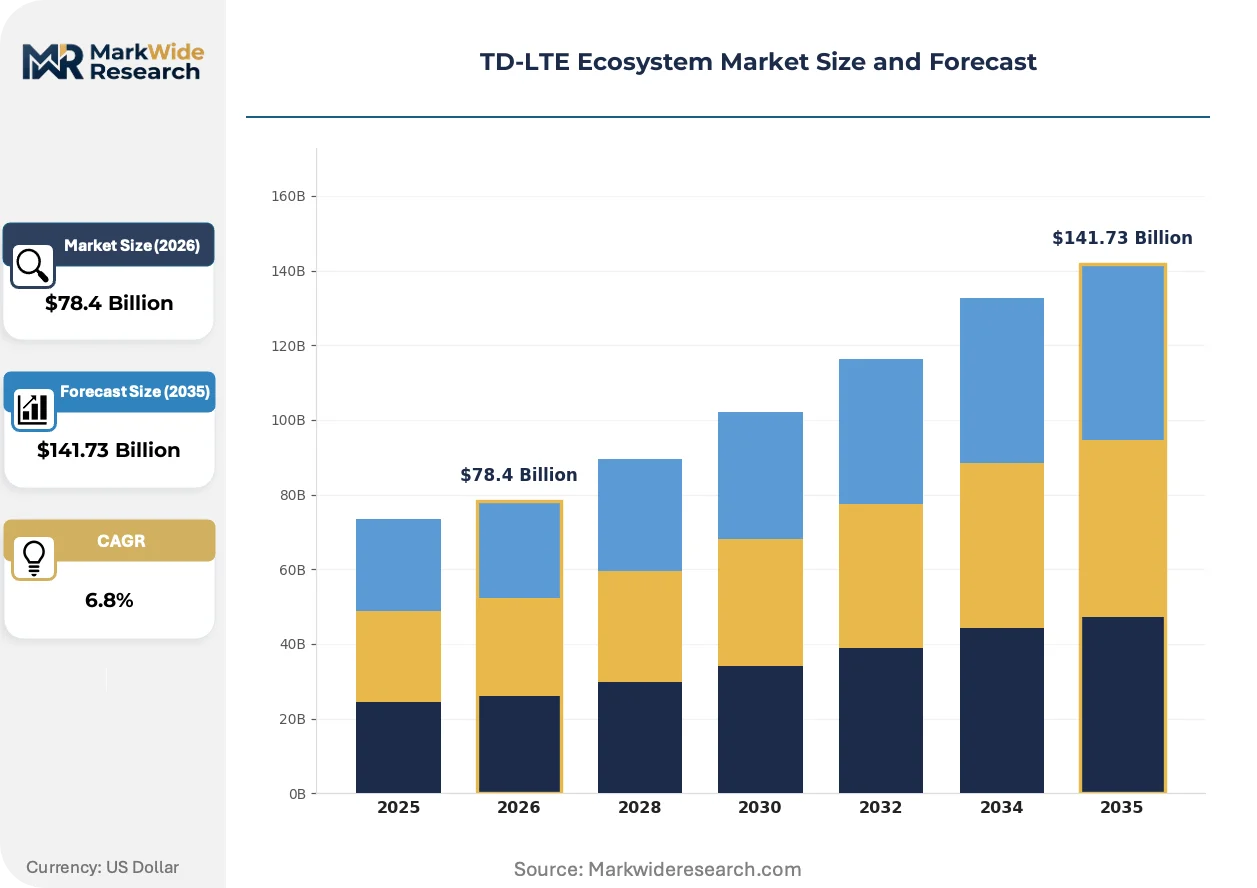
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Stations, User Equipment, Network Solutions, Antennas Deployment Model: Private Network, Public Network, Hybrid Network, Cloud-based Solutions End User: Telecom Operators, Enterprises, Governments, Resellers Application: Smart Cities, IoT Connectivity, Mobile Broadband, Video Streaming |
| Companies Covered | Huawei Technologies, ZTE Corporation, Ericsson, Nokia Corporation, Samsung Electronics, Qualcomm Incorporated, MediaTek Inc., Broadcom Inc., Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TD-LTE Ecosystem Market Strategic Shifts
Open RAN disaggregation is fragmenting traditional vendor stacks, enabling multi-supplier base station deployments and compressing hardware margins while expanding software and integration service opportunities.
Integrated small-cell architectures with embedded antennas and baseband processing are absorbing indoor coverage deployments from distributed antenna systems. Enterprise buyers in retail and healthcare verticals favor these compact units for rapid installation. The technology is absorbing what were previously separate indoor infrastructure categories.
China's MIIT enforcement of GB standards for base station power consumption and electromagnetic compatibility is accelerating component substitution toward gallium nitride power amplifiers. Domestic suppliers gain procurement preference through certified compliance. Equipment tenders in Chinese provincial networks now weight energy efficiency metrics above raw throughput specifications.
Utility operators are consolidating vendor relationships from multi-supplier maintenance contracts toward single-source network-as-a-service agreements. This concentrates procurement authority with national champions in India and state grid corporations in China. The shift is most visible in smart metering deployments where fifteen-year service commitments replace traditional equipment purchase models.
TD-LTE Ecosystem Market Segmentation
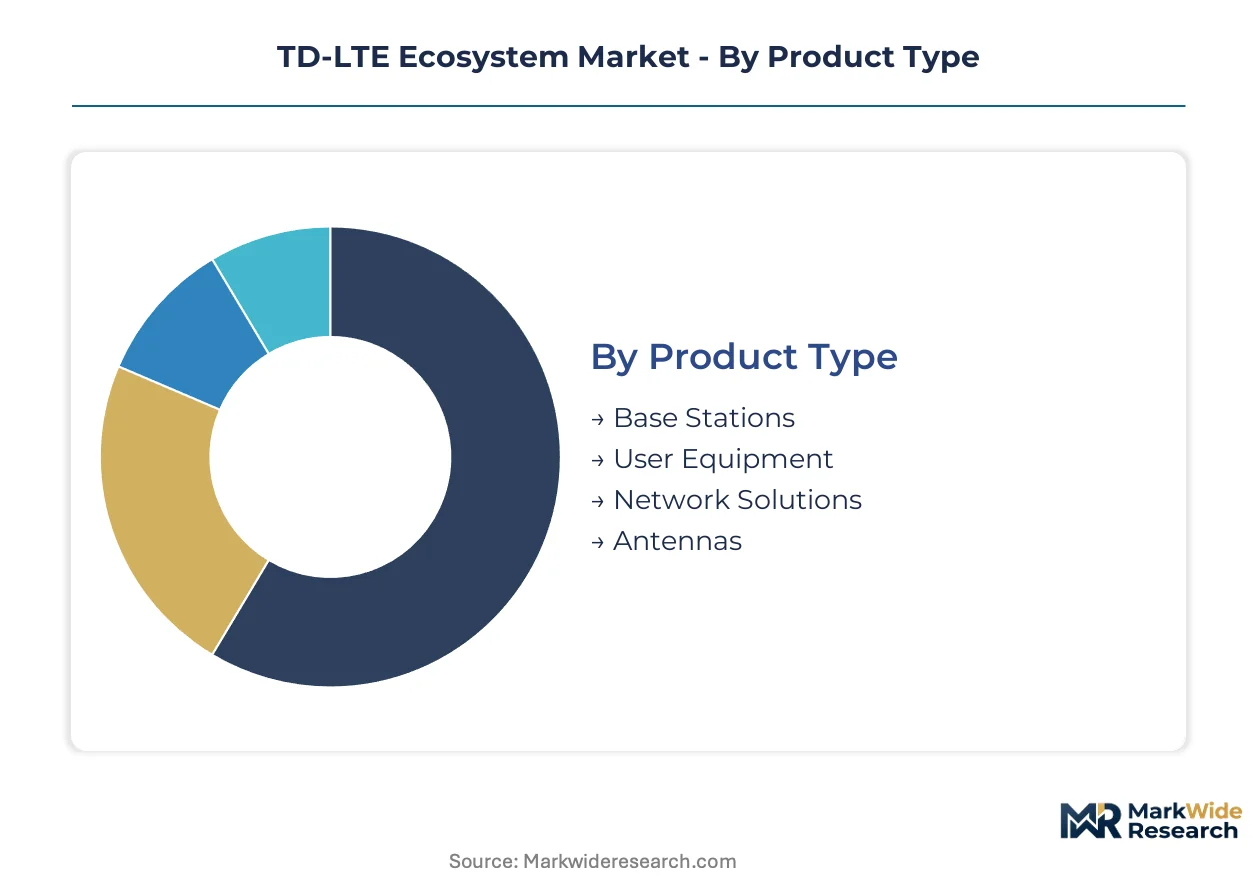
TD-LTE procurement patterns diverge sharply across deployment contexts, with spectrum allocation regimes and ownership structures dictating equipment specifications, vendor selection criteria, and lifecycle investment horizons. Understanding these segment boundaries enables suppliers to calibrate R&D roadmaps and channel strategies against diverging buyer requirements.
Product Type:
Capital intensity and technical complexity separate buyers in this category, with infrastructure owners prioritizing energy efficiency certifications and module interoperability over raw throughput metrics.
- Base Stations:Macro and small-cell radio units incorporating gallium nitride power amplifiers and massive MIMO antenna arrays. China's provincial network tenders now weight GB-compliant power consumption thresholds above peak data rates, shortening refresh cycles for legacy silicon-based deployments.
- User Equipment:Handsets, dongles, and embedded modules containing TD-LTE baseband processors and RF front-ends. Southeast Asian operators bundle low-cost devices with rural broadband subscriptions, compressing average selling prices while expanding unit volumes in Indonesia and Bangladesh.
- Network Solutions:Core network virtualization platforms and evolved packet core software enabling subscriber management and traffic routing. India's TRAI-mandated network-as-a-service frameworks concentrate procurement authority with national champions seeking fifteen-year operational commitments.
- Antennas:Passive and active antenna systems with embedded beamforming capabilities for unpaired spectrum bands. Port operators in Vietnam deploy integrated small-cell units with embedded antennas to bypass distributed antenna system complexity.
Base stations lead volumes today; network solutions are gaining share fastest as operators virtualize core functions.
Deployment Model:
Ownership risk allocation and spectrum access methods determine buyer preferences, with enterprise direct procurement rising where regulatory frameworks permit unlicensed or lightly licensed TDD band assignments.
- Private Network:Campus-wide TD-LTE deployments using leased or locally coordinated spectrum for industrial automation and critical communications. Mining operators in Indonesia procure dedicated infrastructure to guarantee latency performance for autonomous haulage systems.
- Public Network:Commercial mobile broadband infrastructure operated by licensed carriers under national spectrum assignments. India's BharatNet subsidies accelerate base station procurement for unserved rural districts, reducing operator capex barriers.
- Hybrid Network:Architectures combining dedicated enterprise radio access with public network core integration for voice fallback and wide-area roaming. Manufacturing facilities in China leverage MIIT-reserved unpaired bands for machine-type communications while maintaining public network interoperability.
- Cloud-based Solutions:Radio access network functions delivered via edge computing infrastructure with centralized orchestration. European operators evaluate supplier ESG credentials under EU CSRD reporting requirements when selecting cloud-native architectures.
Public networks dominate installed capacity; private networks are expanding most quickly as spectrum leasing frameworks mature in Southeast Asia.
End User:
Procurement sophistication and contract duration vary substantially, with government buyers emphasizing domestic content requirements and extended service warranties against enterprise preferences for rapid deployment flexibility.
- Telecom Operators:Licensed carriers deploying wide-area TD-LTE coverage under national spectrum allocations. Reliance Jio and comparable operators in Bangladesh prioritize integrated small-cell architectures for indoor coverage absorption.
- Enterprises:Corporations and industrial groups establishing private wireless networks for campus automation and asset tracking. Utility operators consolidate vendor relationships toward single-source agreements, replacing multi-supplier maintenance contracts.
- Governments:National and provincial agencies funding rural broadband initiatives and public safety communications. China's MIIT enforces dual carbon goals that shape base station power efficiency mandates across state-backed procurement.
- Resellers:Systems integrators and value-added distributors bundling equipment with installation and managed services. These intermediaries dominate in markets where operator technical capacity remains limited.
Telecom operators anchor current procurement volumes; enterprises show the steepest expansion trajectory as industrial IoT migration accelerates.
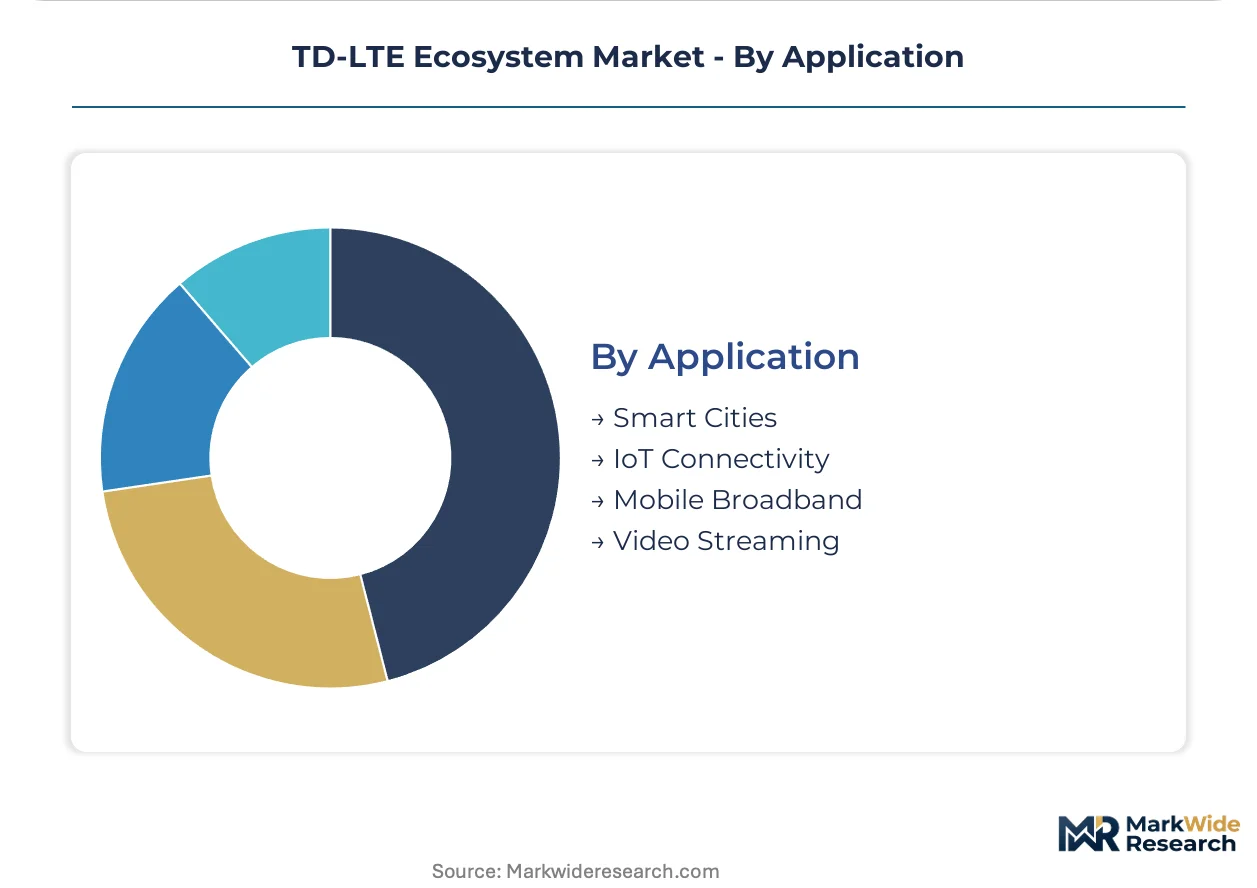
Application:
Traffic asymmetry ratios and quality-of-service requirements differentiate use cases, with video-centric applications demanding subframe configurations optimized for downlink capacity against sensor networks prioritizing uplink efficiency.
- Smart Cities:Integrated municipal infrastructure combining surveillance, traffic management, and environmental monitoring over unified TD-LTE networks. Chinese provincial governments specify GB standards for electromagnetic compatibility in urban densification projects.
- IoT Connectivity:Machine-type communications for utility metering, agricultural sensors, and industrial telemetry. This segment climbs the fastest as legacy 2G networks sunset and operators migrate sensor fleets to unpaired TDD spectrum.
- Mobile Broadband:Consumer data services delivering high-speed internet access to smartphones and fixed wireless terminals. Rural broadband mandates in India and Indonesia sustain equipment demand where 4G network completion lags subscriber growth.
- Video Streaming:Content delivery requiring sustained downlink throughput for over-the-top media services. Dense urban deployments favor massive MIMO configurations to manage peak-hour congestion.
Mobile broadband generates the largest equipment volumes today; IoT connectivity is gaining share fastest as utility and manufacturing sectors complete network migrations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics favor Chinese equipment manufacturers benefiting from MIIT's domestic GB standards and dual carbon mandates that raise compliance costs for foreign rivals. Indian operators exploit BharatNet subsidies to compress rural deployment timelines. Southeast Asian spectrum leasing frameworks create private network opportunities unavailable in mature markets.
China
Provincial network tenders under MIIT direction prioritize GB-certified power efficiency over peak throughput, accelerating gallium nitride adoption in base station power amplifiers. The Yangtze River Delta manufacturing corridor concentrates small-cell production for domestic absorption and Belt and Road export. State grid corporations consolidate procurement authority through fifteen-year network-as-a-service agreements replacing equipment purchase models.
India
TRAI-mandated spectrum auction frameworks directly determine operator capex timing, with BharatNet subsidies reducing rural deployment barriers for unserved districts. Karnataka and Tamil Nadu host dense clusters of systems integrators bundling TD-LTE equipment with installation services. Reliance Jio anchors procurement volumes through integrated small-cell architectures for indoor coverage absorption.
Indonesia
Mining operators in Kalimantan and Papua procure dedicated private networks to guarantee latency performance for autonomous haulage systems. The country's spectrum leasing frameworks enable enterprise direct procurement bypassing carrier intermediaries. Jakarta-based resellers dominate technical capacity-limited markets through bundled managed service offerings.
Vietnam
Port operators in Ho Chi Minh City and Hai Phong deploy integrated small-cell units with embedded antennas to bypass distributed antenna system complexity. Manufacturing facilities leverage locally coordinated spectrum for campus automation while maintaining public network interoperability. The government mandates domestic content thresholds in public safety communications tenders.
Bangladesh
Operators prioritize low-cost user equipment bundles with rural broadband subscriptions, compressing average selling prices while expanding unit volumes. Dhaka-based national champions concentrate procurement authority through network-as-a-service frameworks. The country's regulator shapes vendor selection criteria through spectrum auction timing and rural coverage obligations.
TD-LTE Ecosystem Market Competitive Environment
Chinese producers anchor one tier through domestic supply chain depth and MIIT-compliant manufacturing; European specialists hold premium positioning through R&D intensity in massive MIMO configurations. The vendor base stratifies across integrated stack providers, disaggregated Open RAN suppliers, and chipset specialists. Three archetypes dominate: national champions leveraging policy preference, technology licensors monetizing patent portfolios, and systems integrators capturing deployment services. Competitive moves concentrate on multi-RAT convergence architectures and carbon credential verification for EU procurement.
Within the national champion tier, Huawei Technologies and ZTE Corporation exemplify vertically integrated supply chain control from baseband processors to antenna systems. Ericsson and Nokia Corporation occupy positions emphasizing cloud-native radio access architectures and ESG-compliant manufacturing credentials. Qualcomm Incorporated and MediaTek Inc. anchor the chipset specialization vector, driving integration density in user equipment processors. These six entities collectively represent the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Huawei Technologies |
| ZTE Corporation |
| Ericsson |
| Nokia Corporation |
| Samsung Electronics |
| Qualcomm Incorporated |
| MediaTek Inc. |
| Broadcom Inc. |
| Intel Corporation |
| Others |
Value Chain & Pricing Dynamics
RF engineering talent concentration in Shenzhen and Bangalore widens labor-cost differentials between premium-tier massive MIMO systems and economy small-cell units. China's MIIT power efficiency mandates compress margins on legacy silicon-based hardware while rewarding gallium nitride-certified suppliers with procurement preference.
Pricing Analysis
Distributor margins absorb 12-18 percent of equipment value in Southeast Asian markets where Jakarta-based resellers bundle installation services with hardware. Three-tier pricing structure across premium massive MIMO, standard macro base stations, and economy small-cell units reflects certification grade and after-sales warranty duration. Cost compression in economy tiers intensifies because MediaTek and Qualcomm chipset integration reduces baseband processor costs. Rural broadband operators in India and Bangladesh exhibit highest price sensitivity, while European telecoms prioritize ESG-compliant suppliers regardless of premium.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea foundries for advanced baseband processor fabrication. Component sourcing draws from China for gallium nitride power amplifiers, Vietnam for antenna assembly, and Germany for precision RF filters. Raw material dependencies center on gallium nitride substrates, silicon carbide wafers, and rare-earth magnet materials for antenna positioning systems. Tariff exposure threatens equipment delivery schedules as geopolitical friction disrupts cross-border semiconductor shipments. Distribution runs through national champions in India and state grid corporations in China, consolidating procurement authority away from fragmented reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in TD-LTE equipment hinges on gallium nitride component substitution reducing power consumption penalties and premium-tier shift toward network-as-a-service contracts with fifteen-year operational commitments.
For Market Incumbents: Anticipate 5G non-standalone migration compressing TD-LTE replacement cycles by optimizing multi-RAT convergence architectures that extend equipment lifecycles through firmware upgrades. Defend against Open RAN disaggregation threatening hardware margins by deepening software and integration service revenue pools. Prioritize certification investment in China's GB-compliant power efficiency standards to maintain procurement preference in provincial network tenders.
For New Entrants and Emerging Players: Capture private network deployment opportunities in Indonesia's mining sector and Vietnam's port automation verticals where spectrum leasing frameworks enable enterprise direct procurement. Focus white-space targeting on industrial IoT connectivity modules for utility sensor migrations from sunset 2G networks. Pursue go-to-market partnerships with systems integrators in Karnataka and Tamil Nadu clusters bundling equipment with rural installation services.
For Investors and Strategic Acquirers: National champions with vertically integrated supply chains from baseband processors to antenna systems are the most active acquirer in this space, consolidating procurement authority through network-as-a-service frameworks. Long-term viability centers on suppliers with verified green manufacturing credentials qualifying for EU CBAM and CSRD procurement preference. Target acquisition archetypes include software-defined radio platform specialists enabling TD-LTE and 5G NR unified processing. Watch TDD spectrum refarming announcements as the critical inflection signal for equipment lifecycle investment calibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-RAT Convergence Platform Development | Extends equipment lifecycles through firmware upgrades rather than hardware swaps, preserving operator capex. |
| Gallium Nitride Power Amplifier Transition | MIIT GB standards enforce power efficiency thresholds that disqualify legacy silicon-based base station submissions. |
| Network-as-a-Service Contract Structuring | Fifteen-year operational commitments replace equipment purchase models, concentrating procurement authority with national champions. |
| Private Network Spectrum Leasing | Indonesia and Vietnam frameworks enable mining and port operators to bypass carrier intermediaries for campus coverage. |
| Open RAN Software Stack Investment | Disaggregated vendor stacks fragment traditional hardware margins while expanding integration service revenue pools. |
Study Parameters
Direct dialogue with base station procurement directors, network planning engineers at tier-1 operators, RF component sourcing managers, and systems integrator executives grounded qualitative findings in operational reality. Secondary validation drew from MIIT equipment certification databases, TRAI spectrum auction records, EU CSRD reporting disclosures, and customs trade data for gallium nitride component flows. Bottom-up and top-down triangulation reconciled equipment shipment volumes against operator capex disclosures.
Bottom-up modeling aggregated segment-level equipment procurement patterns across base stations, user equipment, network solutions, and antenna systems. Top-down verification cross-checked aggregate market value against national broadband initiative budgets and spectrum auction proceeds. Segmentation dimensions included product type, deployment model, end user category, and application vertical with regional regulatory cluster overlays. CAGRs derived from fitted growth curves calibrated to historical equipment replacement cycles and announced 5G migration timelines. Industry-specific forecast inputs incorporated MIIT dual carbon mandate compliance deadlines and BharatNet rural coverage obligation schedules.
Spectrum refarming announcements, 5G non-standalone migration delays, and gallium nitride substrate price volatility are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about operator capex timing and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Kuwait Telecom Market
Telecommunications
Fixed LTE Market
Telecommunications
North America Underwater Communication Systems Market
Telecommunications
Bangladesh Telecommunication Industry Market
Telecommunications
Smart SIM Market
Telecommunications
Virtualized RAN (Vran) Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
Nigeria Telecom Market
Telecommunications
5G RAN Market
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
Global SS7 Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
Medical 5G Market
Telecommunications
Global SMB Telecom Voice and Data Services Market
Telecommunications
Australia Mobile Virtual Network Operator (MVNO) Market