
 GSM Mobile Phone Market | 2026-2036
GSM Mobile Phone Market Size, Share, and Industry Trends Forecast 2026-2036
GSM Mobile Phone Market Analysis
Dual-SIM capability is reorganizing the GSM mobile phone competitive landscape. Transsion dominates African markets with localized manufacturing and offline distribution networks. Samsung leverages its component supply chain to sustain margin resilience in entry-level segments. Xiaomi anchors online channel volumes in South Asia through aggressive pricing architecture.
GSM mobile phones rely on second-generation cellular technology operating at 850, 900, 1800, or 1900 MHz bands, using time-division multiple access to route voice and limited data services across carrier networks. These devices serve primarily as affordable communication tools in emerging markets where network infrastructure remains predominantly 2G or 3G. Feature phones retain structural importance as the largest product type by unit volume, while rugged phones command premium pricing in industrial and government end-user categories. Prepaid service type arrangements generate the highest transaction frequency across consumer segments, though bundled packages are gaining traction among business users seeking predictable connectivity costs.
India's BIS certification mandates and the PLI scheme reshape manufacturing location decisions for GSM device producers. E-waste directives under EU REACH and RoHS frameworks constrain material choices for phones sold in European markets. Stakeholders must monitor spectrum reallocation timelines as regulators in multiple countries sunset 2G bands, forcing portfolio transitions toward 4G LTE-compatible hardware even at entry price points.
Market Dynamics
Spectrum reallocation timelines across multiple countries are forcing GSM device producers to accelerate 4G LTE migration even at entry price points, compressing the viable production window for pure 2G hardware and reshaping portfolio investment priorities.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for electronics manufacturing are attracting component suppliers and assembly operations to Indian industrial corridors, reducing landed costs for African and South Asian distribution.
- Rural education programs:Sub-Saharan African governments are procuring feature phones for digital literacy initiatives, creating institutional demand separate from consumer replacement cycles.
- Dual-SIM architecture:Hardware supporting multiple carrier subscriptions is fragmenting prepaid user bases across network operators, increasing device attach rates in markets with fragmented telecom infrastructure.
Market Restraints
- Input cost volatility:Memory chip and display panel pricing fluctuations squeeze margin predictability for entry-level device assemblers operating on thin hardware spreads.
- Supply concentration risk:Battery cell production clusters in East Asian manufacturing hubs create single-source dependency for African-market distributors with limited alternative supplier qualification.
- Technical limitation:2G network capacity constraints restrict data service monetization, capping average revenue per user for carriers and reducing device subsidy budgets.
Strategic Opportunities
- Sub-Saharan Africa's prepaid segment:Underpenetrated rural populations in Nigeria, Ethiopia, and the Democratic Republic of Congo represent volume expansion potential for localized distribution networks.
- E-waste recovery mandates:EU REACH and RoHS frameworks are creating compliance service opportunities for refurbishment and recycling operators serving European secondary markets.
- Offline retail digitization:Point-of-sale financing integration with traditional distributor networks is enabling smartphone upgrade pathways for feature phone users in South Asian tier-3 cities.
Industry Challenges
- Certification timeline compression:India's BIS approval processes for new device variants are extending product launch windows, requiring parallel regulatory track management.
- Legacy system integration:Carrier billing and voucher redemption infrastructure in 2G-dominant markets requires maintaining software compatibility layers across hardware generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GSM Mobile Phone Market |
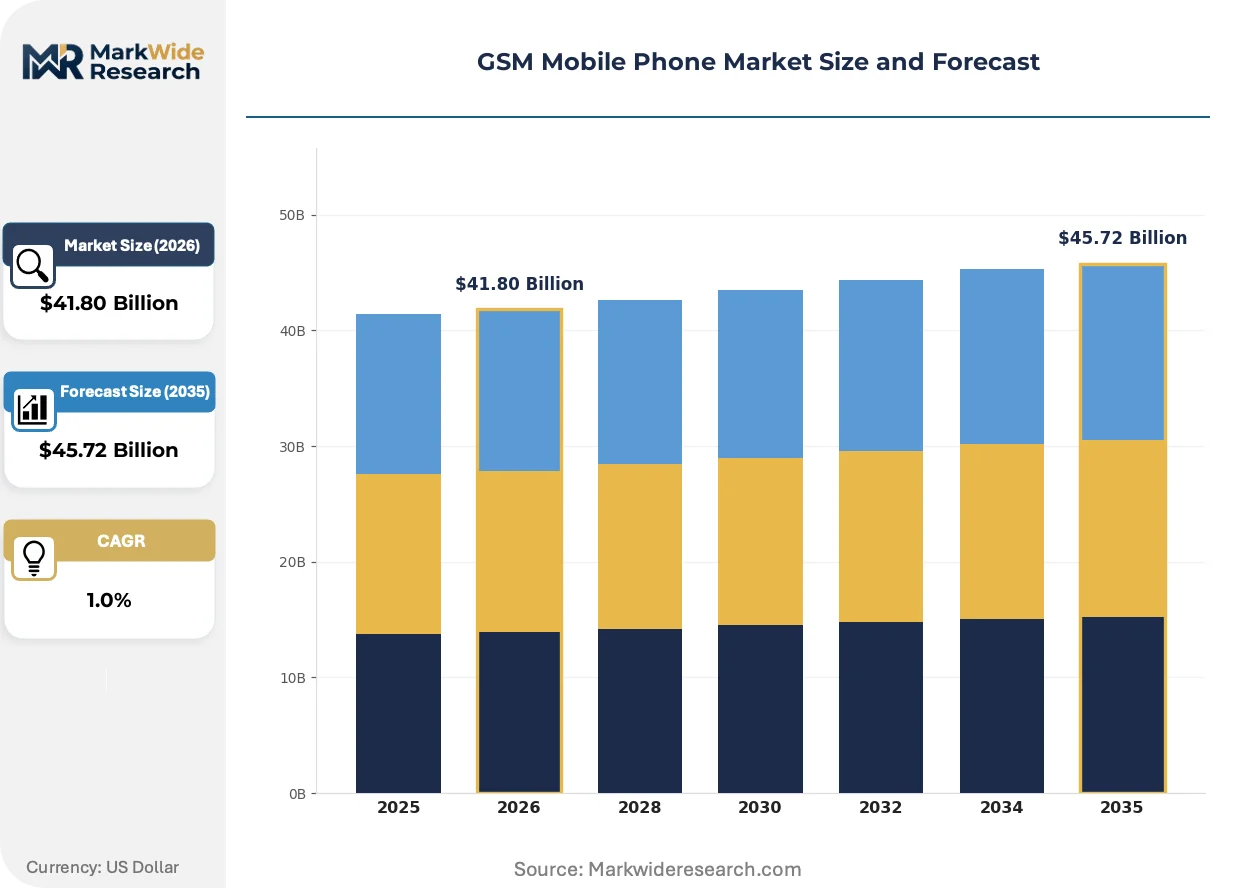
| Market Size in 2026 | $41.80 Billion |
| Market Size in 2035 | $45.72 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Feature Phones, Basic Phones, Rugged Phones End User: Consumer, Business, Educational Institutions, Government Technology: 4G LTE, 5G, GSM, Dual-SIM Service Type: Postpaid, Prepaid, Data-Only Plans, Bundled Packages |
| Companies Covered | Oppo, Transsion, Samsung, Sony, Motorola, Apple, Vivo, HMD Global, Xiaomi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GSM Mobile Phone Market Emerging Trajectories
Component miniaturization and software-defined radio architectures are eroding the traditional cost barriers between feature phone and smartphone categories, enabling functional convergence at price points previously reserved for voice-only devices.
KaiOS and similar lightweight operating systems are fragmenting the feature phone segment by enabling app ecosystems on sub-dollar hardware specifications. Educational procurement officers in Kenya and Bangladesh are specifying these platforms for student device programs. The resulting demand bifurcation is compressing margins for pure voice-hardware specialists while rewarding software-integrated suppliers.
EU spectrum harmonization directives under the European Electronic Communications Code are accelerating 2G sunset schedules in member states. German and French regulators have published concrete band reallocation timelines, forcing inventory clearance strategies for distributors serving migrant worker remittance corridors. Hardware producers are responding with dual-mode 2G/4G baseband chipsets to bridge transition periods.
Prepaid voucher digitization is reshaping distribution economics in cash-dominant economies. Nigerian and Indonesian carriers are migrating airtime sales to mobile money platforms, reducing working capital requirements for informal retail agents. This channel transformation is concentrating volume with distributors capable of integrating financial technology partnerships, sidelining traditional cash-and-carry wholesalers in urban centers.
GSM Mobile Phone Market Segmentation
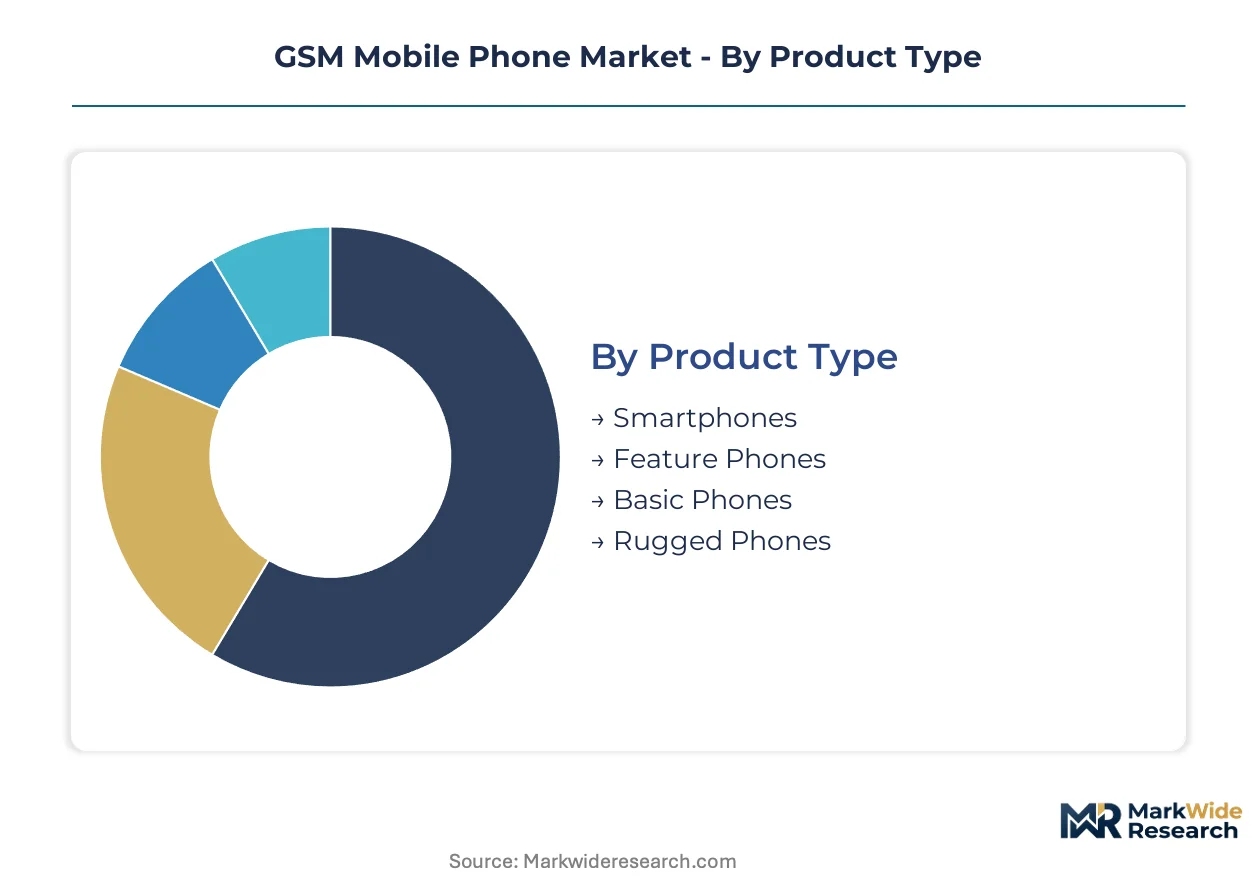
GSM mobile phone segmentation reveals divergent hardware specifications across regulatory environments, with certification requirements in India and spectrum mandates in Europe reshaping product category viability. Understanding these divisions exposes where margin pools concentrate and which technology transitions threaten incumbent positioning.
Product Type:
EU REACH and RoHS material restrictions elevate compliance costs for rugged phone variants sold in European markets, while India's BIS certification timelines compress launch windows for feature phone refreshes.
- Feature Phones:Voice-centric devices with limited data capability dominate unit shipments across sub-Saharan African prepaid markets. Kenyan and Bangladeshi education ministries specify these platforms for student procurement programs, creating institutional demand insulated from consumer replacement cycles.
- Rugged Phones:Reinforced chassis and ingress protection ratings command premium positioning in industrial and government end-use categories. German and French 2G sunset timelines are forcing inventory clearance strategies for distributors serving migrant worker corridors.
- Smartphones:Full touchscreen interfaces with app ecosystems are penetrating South Asian tier-3 cities through point-of-sale financing integration.
- Basic Phones:Minimalist voice-only hardware maintains structural importance in cash-dominant economies with voucher-based airtime distribution.
Feature phones handle the majority of throughput; rugged phones are climbing the fastest on share as industrial certification requirements tighten.
End User:
Customer procurement patterns split sharply between individual cash purchases and institutional tender processes, with divergent margin structures and sales cycle durations.
- Consumer:Individual prepaid subscribers in Nigeria, Ethiopia, and the Democratic Republic of Congo drive volume through fragmented telecom infrastructure. Dual-SIM hardware attach rates are highest in this segment as users optimize across carrier networks.
- Educational Institutions:Government digital literacy initiatives in Kenya and Bangladesh specify KaiOS-enabled devices, bifurcating demand away from pure voice-hardware specialists.
- Business:Corporate fleet deployments prioritize predictable connectivity costs through bundled package arrangements.
- Government:Public sector procurement mandates domestic assembly quotas under India's PLI scheme, altering supplier qualification criteria.
Consumer segment anchors absolute volume; educational institutions are gaining share fastest as sovereign digitization programs scale.
Technology:
Baseband chipset selection now determines market access duration as regulators publish concrete band reallocation schedules.
- Dual-SIM:Hardware supporting multiple carrier subscriptions fragments prepaid user bases across network operators. This architecture is expanding most quickly in markets with incomplete telecom infrastructure coverage.
- 4G LTE:Fourth-generation compatibility is becoming mandatory at entry price points as 2G capacity constraints restrict carrier monetization.
- GSM:Second-generation time-division multiple access technology retains dominance in rural education programs and ultra-low-cost segments.
- 5G:Fifth-generation capability remains peripheral in GSM-addressable price tiers due to component cost premiums.
GSM handles residual volume commitments; dual-SIM is the fastest mover on share as carrier fragmentation deepens.
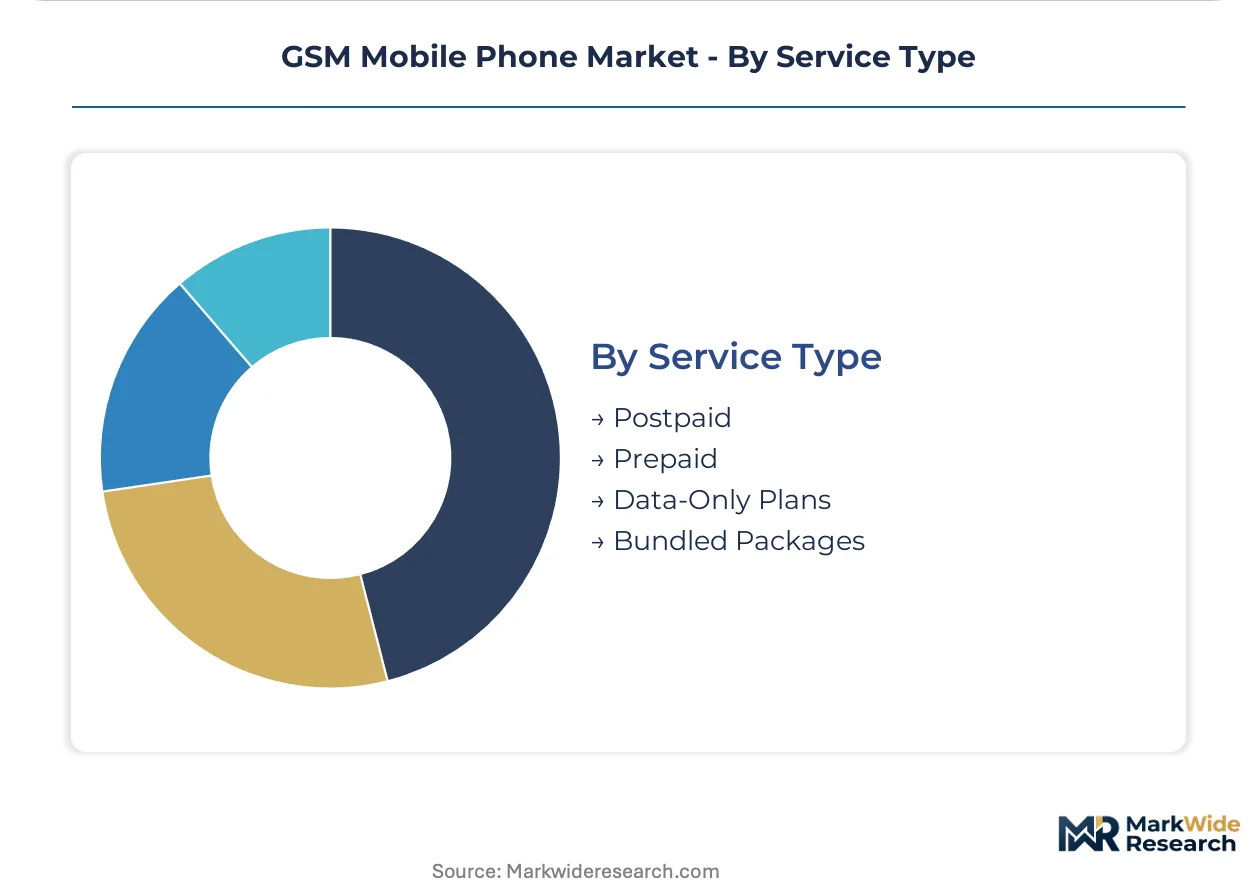
Service Type:
Payment structure selection directly influences device subsidy availability and distributor working capital requirements.
- Prepaid:Voucher-based airtime purchases generate highest transaction frequency across consumer segments. Nigerian and Indonesian carriers are migrating these sales to mobile money platforms, reducing informal retail agent capital requirements.
- Bundled Packages:Combined voice-data-hardware offerings are gaining traction among business users seeking cost predictability.
- Postpaid:Monthly billing arrangements concentrate in urban centers with formal banking penetration.
- Data-Only Plans:Connectivity-only subscriptions serve secondary device and IoT gateway applications.
Prepaid dominates transaction frequency; bundled packages are expanding most quickly as enterprise procurement formalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly operations cluster in Indian industrial corridors under the PLI scheme, while distribution networks concentrate in sub-Saharan African prepaid markets. Component sourcing spans East Asian manufacturing hubs with battery cell production creating single-source dependencies.
India
Domestic manufacturing scales through the PLI scheme attracting component suppliers to Gujarat and Tamil Nadu corridors. BIS certification timelines compress product launch windows, forcing parallel regulatory track management. Noida and Chennai clusters host assembly operations serving African and South Asian distribution networks with reduced landed costs.
Nigeria
Prepaid subscriber bases fragment across dual-SIM hardware as users optimize across carrier networks. Carriers migrate airtime sales to mobile money platforms, reducing working capital for informal retail agents. Lagos distribution networks concentrate volume with distributors integrating financial technology partnerships.
Germany
EU spectrum harmonization directives accelerate 2G sunset schedules, forcing inventory clearance strategies for distributors. REACH and RoHS frameworks constrain material choices for phones sold in European markets. Berlin and Munich serve as compliance service hubs for refurbishment operators addressing e-waste recovery mandates.
Bangladesh
Education ministries specify KaiOS-enabled devices for student procurement programs, bifurcating demand from pure voice-hardware specialists. Point-of-sale financing integration enables smartphone upgrade pathways in tier-3 cities. Dhaka-based distributors anchor localized networks for institutional tender processes.
Kenya
Government digital literacy initiatives create institutional demand insulated from consumer replacement cycles. M-Pesa mobile money integration reshapes voucher-based airtime distribution economics. Nairobi distribution clusters concentrate procurement for regional education programs spanning East African Community markets.
GSM Mobile Phone Market Vendor Landscape
Concentration sits with diversified electronics conglomerates and specialized regional distributors. The vendor base spans tiered capability levels with component supply chain control separating premium positioning from margin-compressed entry segments. Two strategic archetypes dominate: integrated hardware-software platforms and offline distribution specialists. Competitive moves center on geographic licensing partnerships and backward integration into baseband chipset sourcing.
Among Asia-based diversified manufacturers, Transsion, Samsung, and Xiaomi occupy distinct archetype positions. Transsion exemplifies the Africa-focused distribution specialist model with localized manufacturing and offline network penetration. Samsung represents the component-integrated conglomerate archetype leveraging captive supply chain assets for margin resilience. Xiaomi anchors the online-channel volume position through aggressive pricing architecture in South Asian markets.
| Leading Market Players |
|---|
| Oppo |
| Transsion |
| Samsung |
| Sony |
| Motorola |
| Apple |
| Vivo |
| HMD Global |
| Xiaomi |
| Others |
Supply Flow & Price Mechanics
Dual-mode 2G/4G baseband chipset substitution for legacy single-band silicon is compressing hardware margins while shifting assembly location decisions toward Indian PLI corridors and away from traditional East Asian hubs. This input transition simultaneously erodes pricing power for pure 2G specialists and rewards integrated suppliers capable of bridging spectrum reallocation timelines.
Pricing Analysis
India's BIS certification dictates the pricing tier structure across entry-level and mid-range hardware categories. Three-tier pricing separates rugged industrial-grade devices from standard consumer feature phones from economy voice-only units. Price differentiation stems from certification grade and volume scale, with educational procurement tenders commanding 15-20 point discounts over retail channels. Cost compression in economy tiers is intensifying because memory chip volatility squeezes assemblers operating on thin hardware spreads. Prepaid subscribers in sub-Saharan Africa exhibit highest price sensitivity; government fleet buyers in Kenya and Bangladesh demonstrate lowest sensitivity due to sovereign digitization budget insulation.
Supply Chain Analysis
China and South Korea anchor battery cell and display panel production for GSM device assembly. Component sourcing draws from East Asian manufacturing hubs with battery cell production clusters creating single-source dependency for African-market distributors. Supply chain risk centers on logistics chokepoint exposure through Singapore and Hong Kong transshipment nodes. Distribution runs through fragmented offline retail networks in Lagos, Nairobi, and Dhaka, with informal agents handling last-mile voucher sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
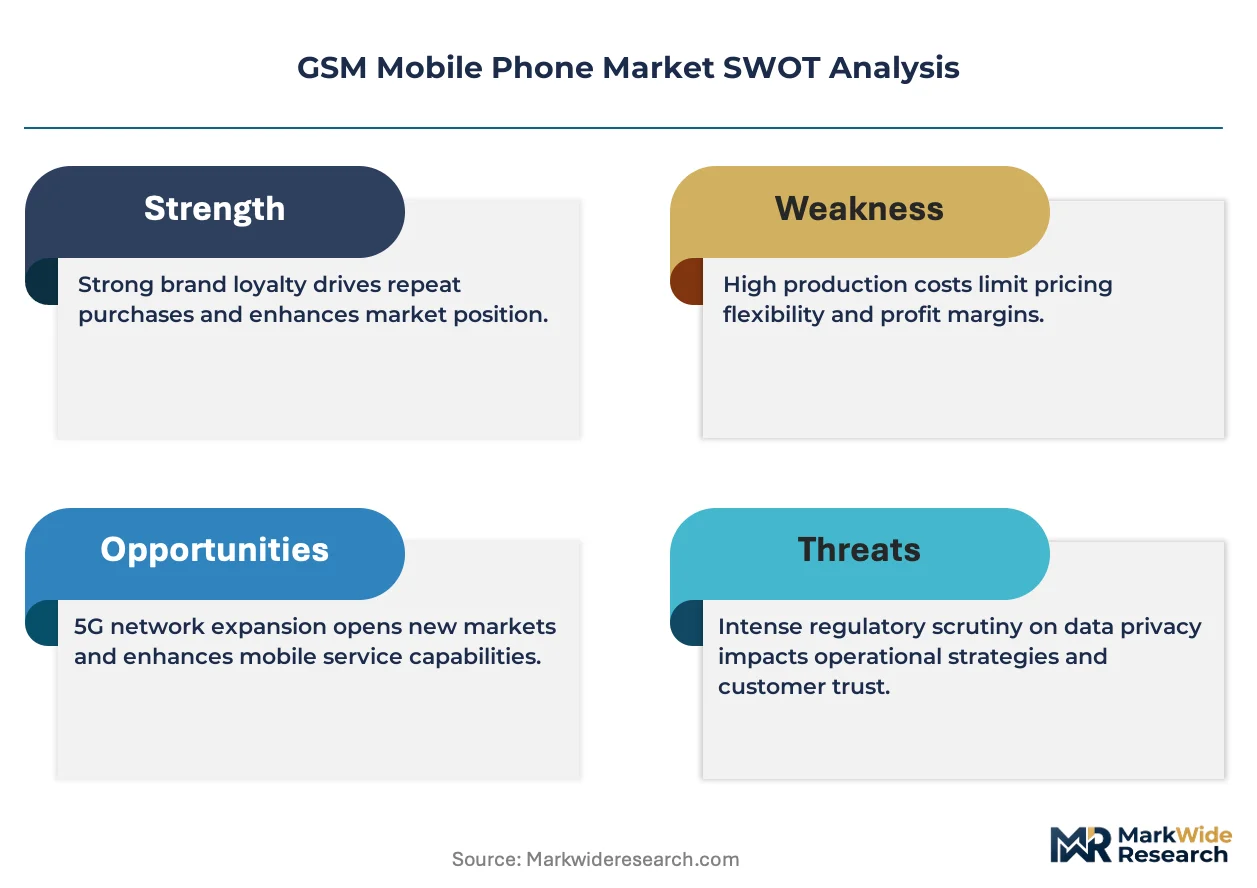
Spectrum reallocation mandates across Germany, France, and India constitute a regulatory inflection forcing portfolio transitions toward 4G-compatible hardware even at entry price points, compressing viable production windows for legacy 2G specialists.
For Market Incumbents: Shield margin pools in African distribution networks by deepening backward integration into baseband chipset sourcing. Transsion's localized manufacturing model in Ethiopia and Nigeria provides template for tariff-resistant positioning. Certification investment in India's BIS parallel-track management defends against launch window compression. For New Entrants and Emerging Players: Differentiate on KaiOS-enabled feature phone platforms for educational procurement channels in Kenya and Bangladesh. White-space concentration sits with sovereign digital literacy programs specifying app-capable sub-dollar hardware. Tier-3 South Asian cities offer penetrable upgrade pathways through point-of-sale financing integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Africa-focused distribution specialists lacking 4G transition capabilities. Long-term viability hinges on dual-mode hardware portfolio breadth and Indian PLI scheme qualification. Signal to watch: concrete 2G sunset timeline announcements from Nigerian and Ethiopian regulators.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Baseband Migration | Hardware bridging 2G/4G protocols extends market access duration across African and South Asian regulatory environments. |
| Indian PLI Scheme Qualification | Domestic assembly certification reduces landed costs for distribution networks serving prepaid consumer segments. |
| KaiOS Platform Integration | Lightweight operating system enables app ecosystems on sub-dollar specifications for education ministry tenders. |
| Mobile Money Partnership | Carrier airtime digitization concentrates volume with distributors integrating M-Pesa and similar financial technology platforms. |
| E-Waste Recovery Compliance | EU REACH and RoHS adherence opens refurbishment service opportunities in European secondary markets. |
Methodological Framework
Initial hypotheses were tested against primary input from device procurement officers at African education ministries, Indian electronics manufacturing executives, Nigerian distribution network heads, and European regulatory affairs specialists and refined through secondary validation. Primary fieldwork combined structured interviews with secondary sources including BIS certification databases, EU spectrum reallocation notices, TRAI policy circulars, and customs trade records for component flows. Bottom-up volume triangulation across product type, end user, and technology segments was cross-checked against top-down value estimates from assembly capacity disclosures.
Variance decomposition across the projection horizon isolates volume drivers from pricing dynamics. Segmentation dimensions modeled include product type, end user category, baseband technology generation, and service payment structure. CAGRs were derived from installed base replacement cycles overlaid with spectrum sunset timelines and educational procurement schedules. Industry-specific forecast inputs include carrier subsidy budget trajectories and component spot pricing volatility indices.
The analysis sits within stated boundaries; outcomes outside sustained 2G network operation in target markets or accelerated 4G component cost declines would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and educational program funding continuity. Recalibration cycles align with material shifts in spectrum reallocation announcements and PLI scheme eligibility revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Mobile Fronthaul and Backhaul Market
Telecommunications
Oman Telecom Market
Telecommunications
Poland Telecom Market
Telecommunications
International Wholesale Voice Carrier Market
Telecommunications
TV White Space Spectrum Market
Telecommunications
Dialer Market
Telecommunications
Germany Critical Communication Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Africa Roaming Tariff Market
Telecommunications
5G Transport Networks Market
Telecommunications
Medical 5G Market
Telecommunications
Cloud Radio Access Network (C-RAN) Market
Telecommunications
Finland Telecom Market
Telecommunications
Smart SIM Market
Telecommunications
Global Roaming Tariff Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market