
 Voip Phone Market | 2026-2036
Voip Phone Market Size, Share, and Industry Trends Forecast 2026-2036
Voip Phone Market Analysis
FCC enhanced 911 location accuracy mandates is consolidating the cost-of-entry calculus for VoIP hardware vendors selling into North America. Cisco Systems leverages its enterprise routing heritage to sustain dominance in on-premises Session Initiation Protocol deployments. Microsoft Corporation anchors cloud voice through deep Teams integration with existing Office productivity suites. Zoom Video Communications competes on video-first unified communications, extending its brand from meetings into telephony replacement.
A VoIP phone transmits voice communications as packetized data over Internet Protocol networks rather than traditional circuit-switched telephone lines, typically supporting codecs such as G.711 or G.729 at bandwidth thresholds between 64 kbps and 8 kbps. These devices serve commercial environments requiring scalable, software-configurable voice infrastructure with lower per-line operational expenditure than legacy TDM systems. Hard phones retain the largest installed base among product categories, though soft phones grow fastest as remote work normalizes bring-your-own-device policies. Cloud-based technology captures expanding margin pools through recurring subscription revenue, while on-premises deployment remains entrenched in regulated sectors demanding local call control.
FCC rules shape product certification requirements for US market access, while CE marking under EU Radio Equipment Directive governs electromagnetic compatibility for European distribution. India's TRAI interconnect regulations and net neutrality frameworks influence pricing models for cross-border VoIP termination. Stakeholders must monitor divergence between national lawful interception mandates and end-to-end encryption capabilities as policy tension intensifies.
Market Dynamics
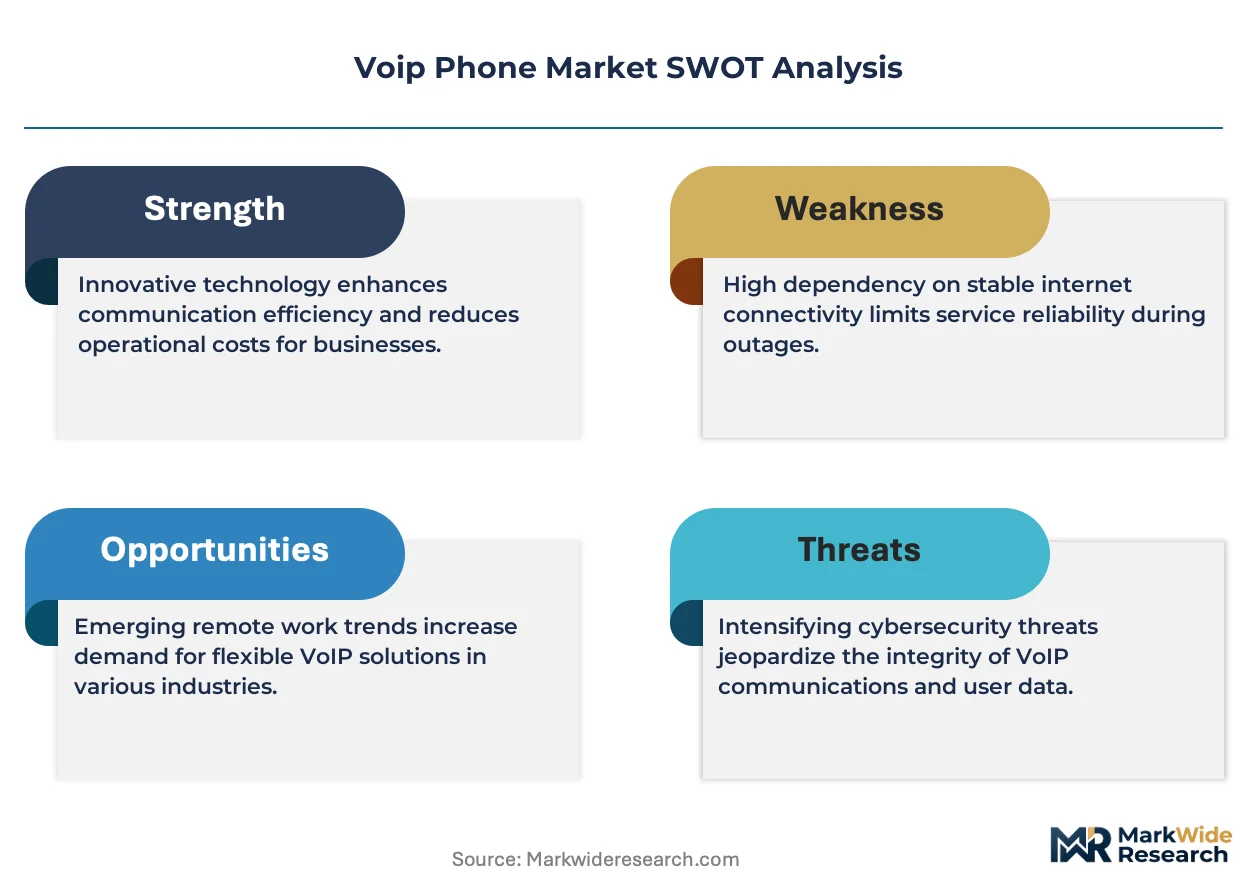
Cloud migration is compressing traditional hardware refresh cycles as healthcare providers and financial institutions abandon on-premises PBX estates for subscription-based voice infrastructure. This shift redistributes vendor revenue from upfront equipment sales toward recurring platform fees.
Growth Catalysts
- India's TRAI interconnect framework:Small enterprises and call centers in Mumbai and Bangalore exploit liberalized termination rates to deploy SIP endpoints at scale, driving bulk procurement volumes.
- Remote work normalization:BYOD policies in professional services firms accelerate soft phone adoption, expanding addressable device counts beyond traditional desk phone ratios.
- G.729 codec efficiency:Bandwidth-constrained branch offices in emerging markets deploy low-bitrate voice compression to maintain call quality over shared internet links.
Market Restraints
- FCC enhanced 911 mandates:Location accuracy requirements for nomadic VoIP users raise certification costs and extend product launch timelines for new entrants targeting US distribution.
- Semiconductor supply concentration:Voice processor and Ethernet PHY chip fabrication concentrates in Taiwan and South Korea, exposing hardware vendors to geopolitical disruption risk.
- Encryption-lawful interception tension:End-to-end voice encryption capabilities conflict with national wiretap mandates in multiple jurisdictions, complicating product architecture decisions.
Strategic Opportunities
- Underpenetrated rural healthcare:Federally qualified health centers in Mississippi and Alabama lack modern voice infrastructure, creating replacement demand for cloud-based systems with integrated patient callback workflows.
- AI-powered voice analytics:Convergence of natural language processing with real-time transcription enables premium service tiers for compliance-heavy sectors including legal and insurance claims processing.
- EU CSRD reporting requirements:Sustainability disclosure mandates drive procurement preference toward vendors with documented supply chain carbon footprints and circular hardware take-back programs.
Industry Challenges
- SIP trunk interoperability testing:Fragmented protocol implementations across carrier networks force vendors to maintain extensive certification matrices, extending engineering overhead.
- Legacy TDM integration complexity:Financial institutions with decades-old copper infrastructure require phased migration support, demanding specialized professional services capacity that strains vendor delivery organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voip Phone Market |
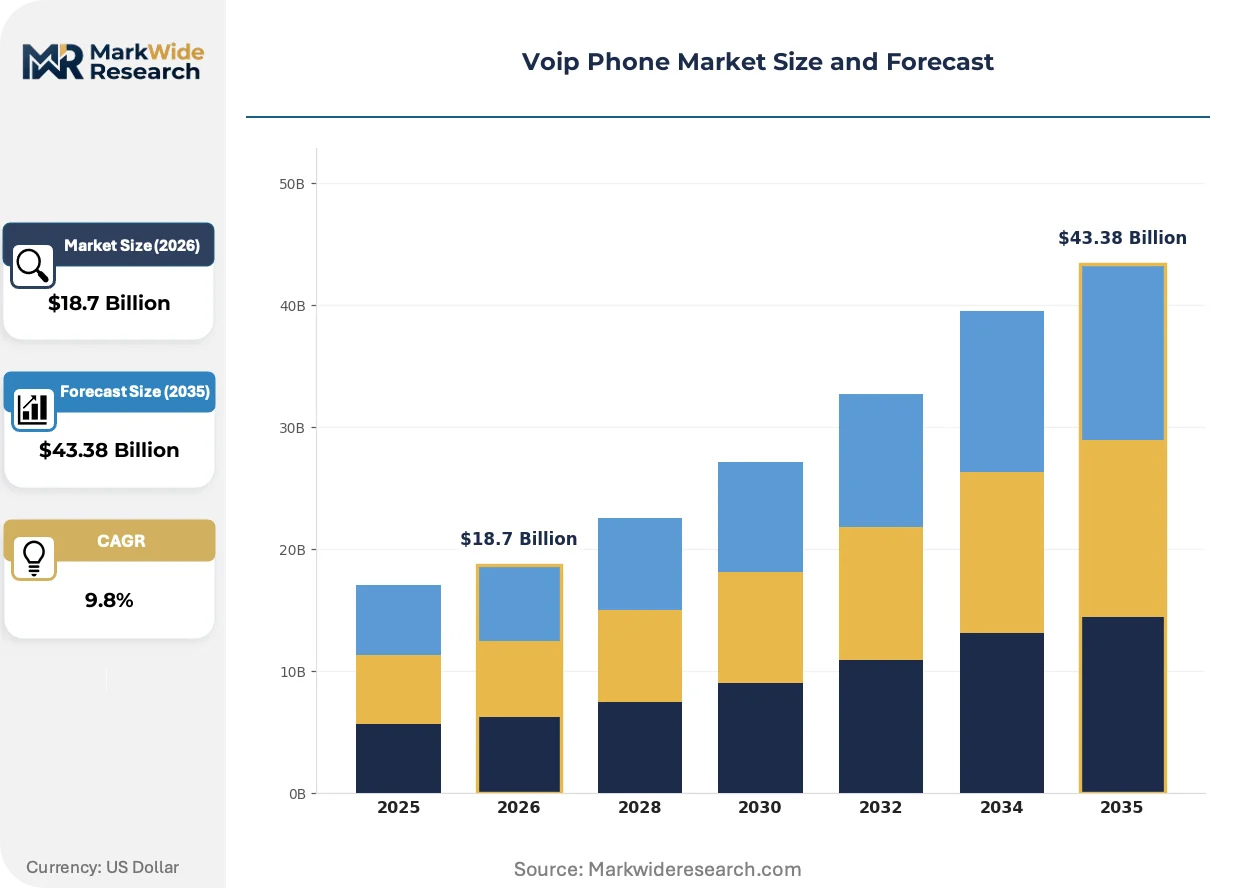
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $43.38 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Phones, Soft Phones, Conference Phones, Wireless Phones Technology: Session Initiation Protocol, WebRTC, Voice over LTE, Cloud-based End User: Small Enterprises, Large Corporations, Call Centers, Home Users Deployment: On-premises, Cloud, Hybrid, Managed Services |
| Companies Covered | Cisco Systems, Microsoft Corporation, Zoom Video Communications, RingCentral, 8x8, Vonage, Nextiva, Mitel Networks Corporation, Ribbon Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voip Phone Market Emerging Trajectories
Artificial intelligence integration is absorbing routine voice infrastructure functions and redefining how enterprises evaluate telephony platform value beyond basic call completion metrics.
WebRTC is absorbing browser-native voice and video capabilities into unified communications platforms, eliminating plugin dependencies and reducing client-side deployment friction. Mid-market enterprises in Germany and the Netherlands adopt WebRTC-based soft phones to bypass traditional desktop application management. This absorption collapses the distinction between web conferencing and telephony, pressuring standalone hardware vendors to demonstrate incremental value.
EU AI Act risk classification rules impose documentation and human oversight requirements on voice systems employing biometric identification or emotion recognition. Vendors serving European enterprises must re-engineer feature sets to exclude prohibited practices or obtain explicit consent frameworks. Financial services and public sector buyers in France and Spain now require AI Act compliance attestations in procurement evaluations, filtering vendor shortlists.
Subscription fatigue among IT procurement teams is compressing voice platform evaluation cycles and elevating total-cost-of-ownership transparency demands. Buyers in UK professional services firms increasingly reject opaque per-seat pricing in favor of usage-based models with granular cost allocation. This behavioral shift disadvantages vendors with complex licensing structures and rewards competitors offering straightforward consumption metering.
Voip Phone Market Segmentation
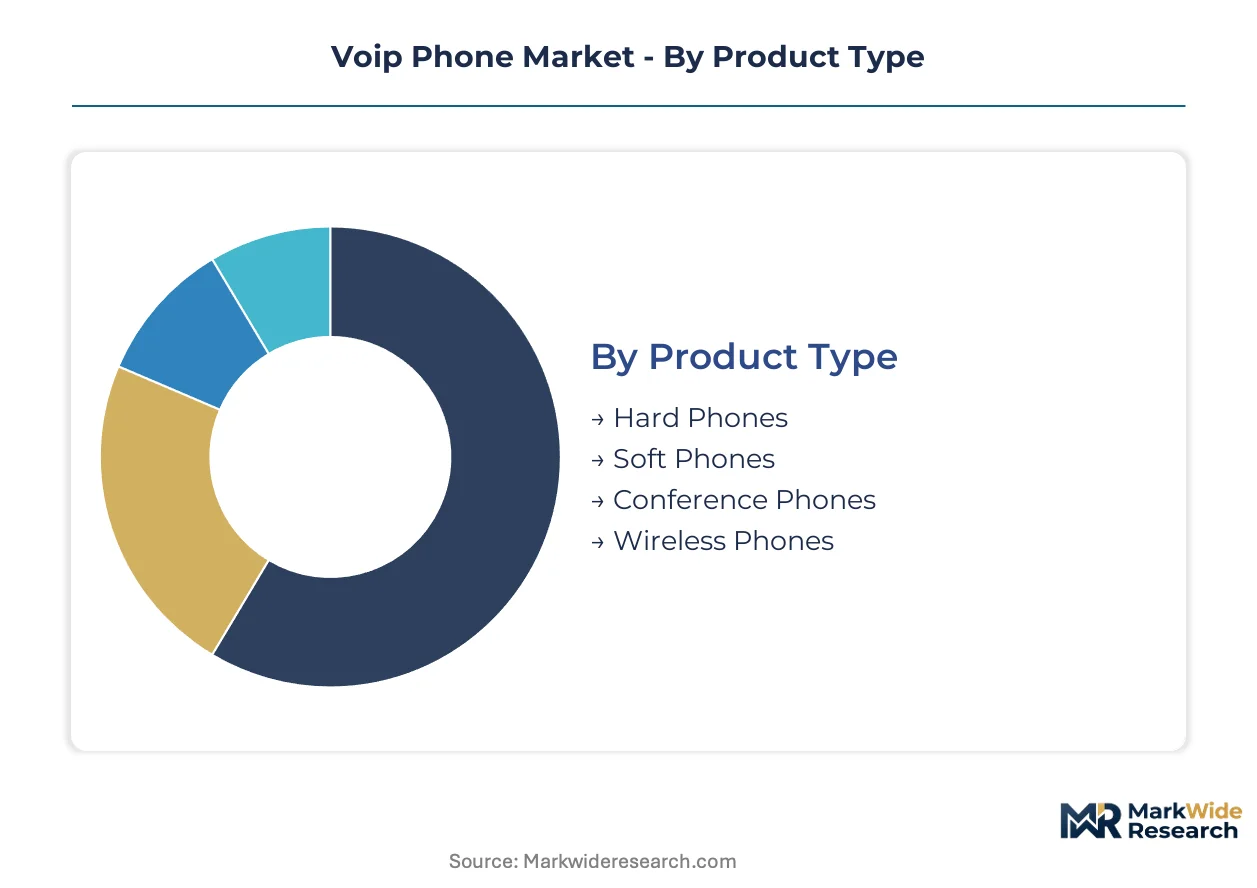
VoIP phone segmentation reveals divergent certification burdens across product architectures, with hardware-bound categories facing FCC Part 68 and CE marking complexity while software-centric segments navigate lighter compliance paths. Understanding these stratified requirements enables vendors to allocate engineering resources toward the highest-margin deployment modes.
Product Type:
FCC Part 68 registration and CE marking under the EU Radio Equipment Directive impose the heaviest certification loads on physical hardware segments, while purely software offerings bypass electromagnetic compatibility testing entirely.
- Hard Phones:Dedicated desktop devices with embedded voice processors and Ethernet PHY chips require FCC Part 68 registration for US market access and CE marking for European distribution. Healthcare systems in the United States accelerate replacement of aging PBX networks with these endpoints, though semiconductor supply concentration in Taiwan and South Korea exposes procurement timelines to geopolitical disruption risk.
- Soft Phones:Software applications running on general-purpose computing platforms eliminate hardware certification cycles entirely, relying instead on host device compliance. Professional services firms in the United Kingdom normalize bring-your-own-device policies, expanding addressable device counts beyond traditional desk phone ratios as remote work institutionalizes.
- Conference Phones:Room-based speakerphone systems with extended microphone arrays face amplified acoustic testing requirements under FCC regulations. Corporate headquarters in Germany deploy these units for hybrid meeting spaces.
- Wireless Phones:Wi-Fi and DECT handsets trigger additional radio frequency exposure assessments in multiple jurisdictions. Warehouse operations in the Netherlands adopt these for mobile workforce connectivity.
Leading the category by volume: Hard Phones. Growing fastest: Soft Phones.
Technology:
Protocol selection determines interoperability testing matrices and carrier certification depth, with mature standards offering streamlined deployment versus emerging technologies demanding extensive validation.
- Session Initiation Protocol:The dominant signaling standard for enterprise voice infrastructure, SIP requires extensive interoperability testing against fragmented carrier implementations. Small enterprises and call centers in Mumbai and Bangalore exploit India's TRAI interconnect framework to deploy SIP endpoints at scale, driving bulk procurement volumes through liberalized termination rates.
- WebRTC:Browser-native real-time communication eliminates client-side deployment friction and plugin dependencies. Mid-market enterprises in Germany and the Netherlands adopt WebRTC-based soft phones to bypass traditional desktop application management, collapsing distinctions between web conferencing and telephony.
- Voice over LTE:Mobile-native voice over 4G/5G networks requires carrier-specific certification for seamless handover. Field service operations in France leverage these for unified mobile communications.
- Cloud-based:Fully hosted voice infrastructure shifts operational burden to service providers, reducing on-site technical requirements. Federally qualified health centers in Mississippi and Alabama lacking modern infrastructure select these systems for rapid deployment.
Dominant by installed base: Session Initiation Protocol. Expanding most quickly: WebRTC.
End User:
Customer scale dictates pricing model elasticity and support infrastructure intensity, with enterprise segments demanding customized service level agreements versus standardized offerings for smaller accounts.
- Small Enterprises:Organizations with limited IT staff favor subscription-based consumption models with predictable monthly expenditure. India's small enterprises drive bulk SIP endpoint procurement through TRAI-facilitated termination rate advantages.
- Large Corporations:Complex multi-site deployments require dedicated account management and customized integration services. Financial institutions in the United States demand phased migration support for decades-old copper infrastructure.
- Call Centers:High-density agent environments prioritize G.729 codec efficiency to conserve bandwidth over shared internet links. Bangalore operations deploy these configurations at scale.
- Home Users:Residential adoption concentrates in price-sensitive segments with minimal technical support expectations. Remote workers in the United Kingdom utilize these for secondary line redundancy.
Highest revenue concentration: Large Corporations. Steepest expansion trajectory: Call Centers.
Deployment:
Architecture choice determines capital expenditure profile and regulatory exposure, with local control preserving compliance flexibility versus cloud delegation transferring operational risk.
- On-premises:Local PBX infrastructure maintains physical control over call data and lawful interception capabilities. Regulated sectors in the United States including healthcare and financial services retain this model for HIPAA and SEC compliance assurance.
- Cloud:Fully hosted voice platforms convert capital expenditure to recurring operational fees. Healthcare providers across the United States accelerate abandonment of on-premises estates for subscription-based alternatives.
- Hybrid:Mixed architectures preserve legacy TDM integration while selectively modernizing specific user populations. German manufacturing facilities deploy these for gradual workforce transition.
- Managed Services:Outsourced operational responsibility includes proactive monitoring and maintenance. Alabama and Mississippi rural health centers lacking technical capacity select these for integrated patient callback workflows.
Largest current footprint: On-premises. Gaining share fastest: Cloud.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates bulk procurement demand from small enterprises and call centers exploiting liberalized termination rates, while the United States drives cloud migration across healthcare and financial sectors. Regulatory divergence across major economies shapes certification burdens and go-to-market timelines for hardware vendors.
United States
FCC enhanced 911 location accuracy mandates raise certification costs and extend product launch timelines for nomadic VoIP services. Healthcare systems accelerate abandonment of aging PBX networks for cloud-based voice infrastructure. Federally qualified health centers in Mississippi and Alabama lack modern infrastructure, creating replacement demand for integrated patient callback workflows.
Germany
Mid-market enterprises adopt WebRTC-based soft phones to bypass traditional desktop application management. EU AI Act risk classification rules impose documentation requirements on voice systems employing biometric identification. Corporate headquarters deploy conference phone systems for hybrid meeting spaces, amplifying acoustic testing requirements.
India
Small enterprises and call centers in Mumbai and Bangalore exploit TRAI interconnect framework liberalization to deploy SIP endpoints at scale. Net neutrality frameworks influence pricing models for cross-border VoIP termination. Bangalore operations deploy G.729 codec configurations at scale to conserve bandwidth over shared internet links.
United Kingdom
Professional services firms normalize bring-your-own-device policies, expanding addressable device counts beyond traditional desk phone ratios. Subscription fatigue compresses voice platform evaluation cycles and elevates total-cost-of-ownership transparency demands. Buyers increasingly reject opaque per-seat pricing in favor of usage-based models with granular cost allocation.
France
Financial services and public sector buyers require EU AI Act compliance attestations in procurement evaluations, filtering vendor shortlists. Field service operations leverage Voice over LTE for unified mobile communications. Sustainability disclosure mandates drive procurement preference toward vendors with documented supply chain carbon footprints.
Voip Phone Market Vendor Landscape
United States producers anchor the cloud-platform tier; Taiwanese and South Korean component specialists hold upstream semiconductor concentration. The vendor base stratifies across three tiers: legacy equipment manufacturers with enterprise routing heritage, cloud-native platforms with productivity suite integration, and specialized pure-play voice providers. Consolidation pressure intensifies as recurring subscription revenue models displace upfront hardware sales, while interoperability certification requirements favor incumbents with established carrier relationships.
Within the enterprise infrastructure tier, Cisco Systems occupies a position representing on-premises deployment heritage, while Microsoft Corporation exemplifies cloud-platform integration with productivity software ecosystems. Zoom Video Communications anchors the video-first unified communications archetype, extending brand recognition from meetings into telephony replacement. These three entities collectively illustrate the strategic divergence between hardware-centric, platform-embedded, and collaboration-native competitive approaches.
| Leading Market Players |
|---|
| Cisco Systems |
| Microsoft Corporation |
| Zoom Video Communications |
| RingCentral |
| 8x8 |
| Vonage |
| Nextiva |
| Mitel Networks Corporation |
| Ribbon Communications |
| Others |
Supply Flow & Price Mechanics
Subscription fatigue among UK professional services firms compresses voice platform evaluation cycles and forces vendors toward transparent usage-based models, compelling supply chains to absorb certification cost burdens while compressing hardware margins across FCC Part 68 and CE marking tiers.
Pricing Analysis
Volume concentrates in hard phone shipments while margin pools shift toward cloud-based recurring subscriptions. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service bundling. Cost compression in entry-level hardware intensifies because semiconductor supply concentration limits procurement leverage. Small enterprises in India exhibit highest price sensitivity; regulated US healthcare systems demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Workforce availability constraints in Taiwan and South Korea concentrate voice processor and Ethernet PHY chip fabrication, exposing hardware vendors to geopolitical disruption risk. Semiconductor fabrication draws from specialized foundry capacity in Hsinchu and Seoul, while plastic enclosures and acoustic components source from Dongguan and Shenzhen. Single-source vulnerability in advanced node chip production threatens procurement timelines. Distribution runs through carrier-certified channel partners and direct enterprise sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor supply concentration in Taiwan and South Korea props pricing power for component specialists, constraining downstream hardware vendors and sustaining margin pressure across the analysis window.
For Market Incumbents: Cement carrier certification relationships to defend against WebRTC-native entrants collapsing telephony into browser-based platforms. Deepen backward integration into voice processor design to offset foundry concentration risk. Prioritize FCC Part 68 pre-certification investment to accelerate product launch timelines against new entrants. For New Entrants and Emerging Players: Capture underpenetrated rural healthcare infrastructure in Mississippi and Alabama through managed services wrappers around cloud voice platforms. Target federally qualified health centers lacking technical capacity for integrated patient callback workflows. Pursue usage-based pricing transparency as the primary go-to-market wedge against incumbent complexity. For Investors and Strategic Acquirers: The window for entry favors cloud-native platforms with embedded AI transcription capabilities over hardware-centric legacy vendors. Long-term viability hinges on recurring revenue retention and platform integration depth. Watch WebRTC adoption velocity in German and Dutch mid-market enterprises as the inflection signal for hardware displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| AI Voice Analytics Integration | Natural language processing convergence enables premium tiers for legal and insurance compliance workflows. |
| FCC Enhanced 911 Pre-Certification | Early compliance investment collapses product launch timelines for nomadic VoIP services in US distribution. |
| WebRTC Platform Migration | Browser-native deployment eliminates desktop application management overhead for German mid-market adopters. |
| Supply Chain Carbon Footprint Documentation | EU CSRD disclosure mandates filter procurement shortlists toward vendors with circular hardware programs. |
| TRAI Interconnect Rate Arbitrage | Liberalized termination pricing enables bulk SIP endpoint procurement at scale for Mumbai call centers. |
Methodological Framework
SEC filings, carrier interoperability certification databases, and EU regulatory disclosure repositories formed the secondary backbone, supplemented by primary interviews with VoIP platform engineering directors, healthcare IT procurement officers, carrier network operations leads, and TRAI policy specialists. Bottom-up shipment data triangulated against top-down enterprise voice infrastructure spending estimates.
Bottom-up modeling of hard phone, soft phone, and conference phone unit volumes reconciled with top-down cloud subscription revenue aggregates across the projection horizon. Segmentation dimensions included product architecture, deployment model, end-user scale, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating G.729 codec adoption rates and WebRTC penetration trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply disruption and FCC rulemaking evolution. Forecasts reflect documented assumptions regarding carrier certification timelines and enterprise cloud migration velocity. A small set of triggers warrants ongoing watch: Taiwan Strait logistics disruption, EU AI Act enforcement precedence, and India TRAI interconnect rate revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G RAN Market
Telecommunications
Satcom Terminal Market
Telecommunications
5G in Defense Market
Telecommunications
Cloud PBX Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Promotional Sms Market
Telecommunications
Hungary ICT Market
Telecommunications
Belgium Telecom Market
Telecommunications
Spain ICT Market
Telecommunications
Dialer Market
Telecommunications
Fixed LTE Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
Cellular Modem Market
Telecommunications
International Wholesale Voice Carrier Market
Telecommunications
Finland Telecom Market
Telecommunications
US Voice-Over LTE (Volte) Market