
 Polymer Excipients Market | 2026-2036
Polymer Excipients Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Excipients Market Analytics
Single-source supply of specialty cellulose derivatives is consolidating around integrated chemical producers with captive raw material streams. BASF SE leverages backward integration into petrochemical feedstocks to secure polyethylene glycol supply chains. Evonik Industries AG sustains technology leadership in functionalized polymethacrylates for controlled-release matrices. Croda International Plc specializes in lipid-polymer hybrid excipients, occupying a premium niche in parenteral formulation science.
Polymer excipients are macromolecular substances, typically with molecular weights exceeding 1,000 daltons, incorporated into dosage forms to confer mechanical strength, regulate drug release kinetics, or enhance active pharmaceutical ingredient stability through entrapment within hydrophilic or hydrophobic matrices. Their primary commercial purpose centers on enabling scalable manufacturing of tablets, capsules, and films while meeting pharmacopeial standards for purity, functionality, and lot-to-lot consistency. Cellulose derivatives dominate volume consumption across oral solid dosage applications, reflecting decades of toxicological validation and compendial acceptance. Polyvinylpyrrolidone commands higher margin pools in direct-compression formulations and solubilization systems for poorly soluble APIs. Powder forms retain the largest share of unit volume, though film formats accelerate in transdermal and orodispersible applications driven by pediatric and geriatric compliance needs.
FDA enforces Current Good Manufacturing Practice standards under 21 CFR Parts 210 and 211, compelling excipient suppliers to implement drug master files and quality agreements that mirror active ingredient rigor. The European Pharmacopoeia and USP-NF monographs collectively define functionality-related characteristics, from viscosity grades to particle size distributions, that determine batch suitability for specific formulation platforms. Excipient manufacturers must also navigate REACH registration requirements for novel synthetic polymers and EPA environmental release thresholds for large-volume production sites. Stakeholders should monitor how continuous manufacturing adoption alters excipient specification windows and real-time release testing protocols.
Market Dynamics
Continuous manufacturing adoption is compressing excipient specification windows and forcing real-time release testing protocols across pharmaceutical supply chains. FDA's Quality by Design initiative and ICH Q13 guidelines now demand tighter functionality-related characteristics from polymer suppliers.
Growth Catalysts
- Controlled-release formulation platforms:Multifunctional polymethacrylates enable zero-order kinetics in oral solid dosage forms, pulling demand from generic manufacturers scaling complex generics capacity.
- REACH registration pathways:Novel synthetic polymers gaining streamlined European market access accelerate specialty cellulose derivative substitution in high-margin parenteral applications.
- Geriatric compliance engineering:Orodispersible film formats incorporating polyvinylpyrrolidone matrices address swallowing difficulties, expanding pediatric and elderly prescription adherence.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene glycol producers face margin compression from ethylene oxide price swings tied to crude oil benchmarks.
- Cellulose pulp supply concentration:Specialty cellulose derivative manufacturers depend on Nordic and Southeast Asian pulp mills, creating single-source vulnerability.
- EPA environmental release thresholds:Large-volume production sites face capital-intensive scrubbing and wastewater treatment upgrades to maintain operating permits.
Strategic Opportunities
- Lipid-polymer hybrid parenteral systems:Liposomal and nanoparticle delivery platforms converge polymer science with lipid chemistry, opening oncology and vaccine formulation white space.
- Biopharma contract manufacturing expansion:United States-based CDMOs scaling biosimilar capacity require excipient suppliers with drug master file infrastructure and quality agreement templates.
- Real-time release testing protocols:Continuous manufacturing equipment vendors seek polymer suppliers capable of batch-less consistency certification, rewarding early analytical investment.
Industry Challenges
- Pharmacopeial functionality testing expertise:Formulation scientists with viscosity-grade-to-dissolution-profile correlation skills command premium compensation, constraining mid-tier supplier technical service capacity.
- Legacy batch record system integration:Excipient manufacturers adopting continuous lines face ERP reconfiguration costs and validation timelines that delay commercial launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Excipients Market |
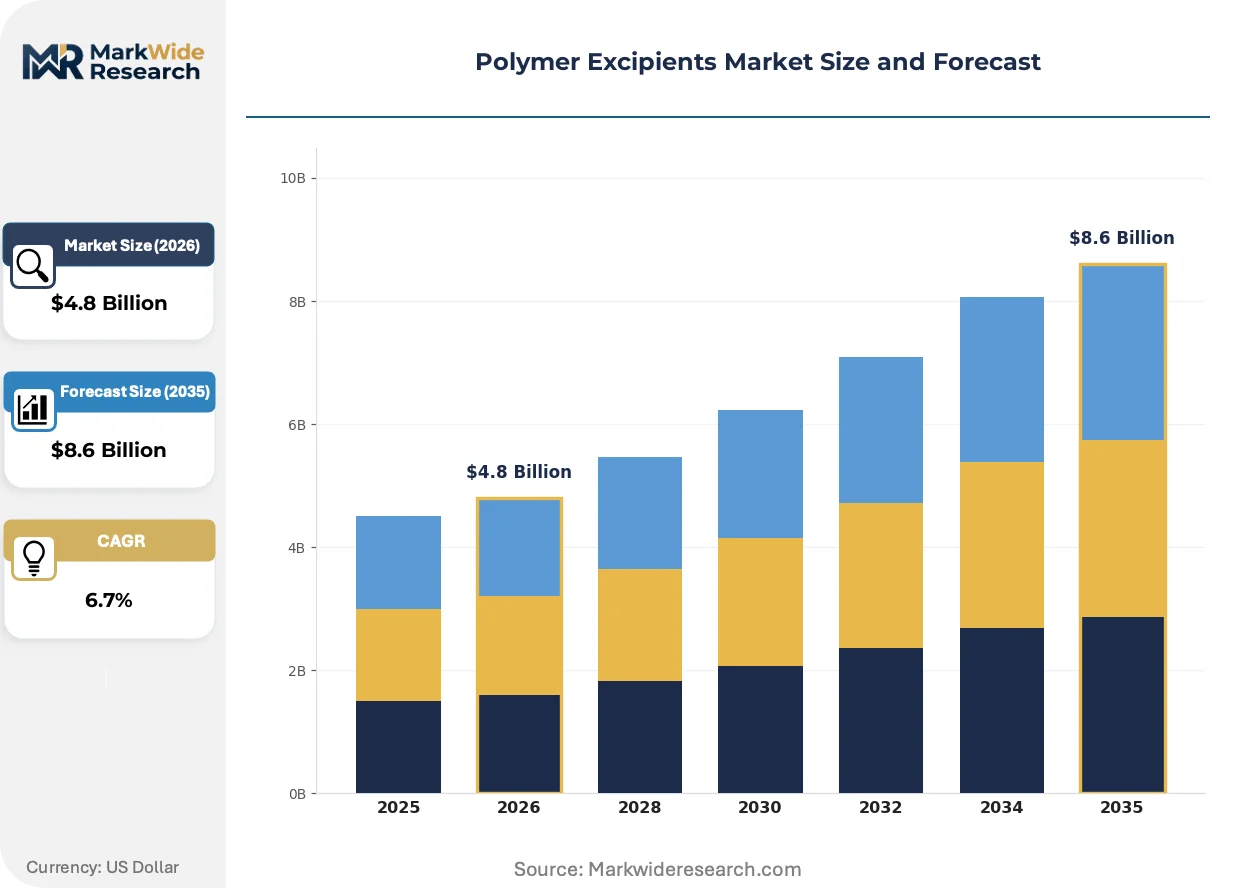
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Glycol, Cellulose Derivatives, Polyvinylpyrrolidone, Starch Application: Pharmaceuticals, Nutraceuticals, Personal Care, Food Industry Form: Powder, Granules, Tablets, Films End User: Contract Manufacturers, Research Institutions, Pharmaceutical Companies, Biotech Firms |
| Companies Covered | Ashland Inc., Lubrizol Corporation, BASF SE, Colorcon Inc., Merck KGaA, Evonik Industries AG, Roquette Frères, Croda International Plc, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Excipients Market Evolving Landscape
Hot-melt extrusion and 3D printing of personalized dosage forms are redrawing equipment-infrastructure requirements for excipient suppliers. These platforms demand thermal processing stability and shear-thinning precision absent from traditional wet-granulation specifications.
Hot-melt extrusion technology is decentralizing solid dispersion manufacturing from centralized toll processors to integrated pharmaceutical facilities. Generic manufacturers in Eastern Europe and Latin America are adopting twin-screw extruders for amorphous solid dispersion of poorly soluble APIs. This shift is compressing the addressable market for traditional solvent-based spray-drying service providers while expanding demand for thermoplastic polymer grades with precise torque rheology.
EMA's updated excipient risk assessment guidelines now mandate nitrosamine impurity screening for secondary amine-containing polymers. European manufacturers must retrofit analytical laboratories with LC-MS/MS detection capabilities or outsource testing to certified contract laboratories. Parenteral-grade polyethylene glycol and poloxamer suppliers face the steepest compliance curves given their direct bloodstream exposure profiles.
Formulation groups at midsize pharmaceutical companies are consolidating excipient vendor panels from fifteen-plus suppliers to four or five strategic partners with full pharmacopeial coverage. This consolidation favors integrated chemical producers with captive raw material streams and global drug master file portfolios. The United States exhibits the most pronounced vendor rationalization, driven by FDA inspection intensity and quality agreement negotiation burden.
Polymer Excipients Market Segmentation
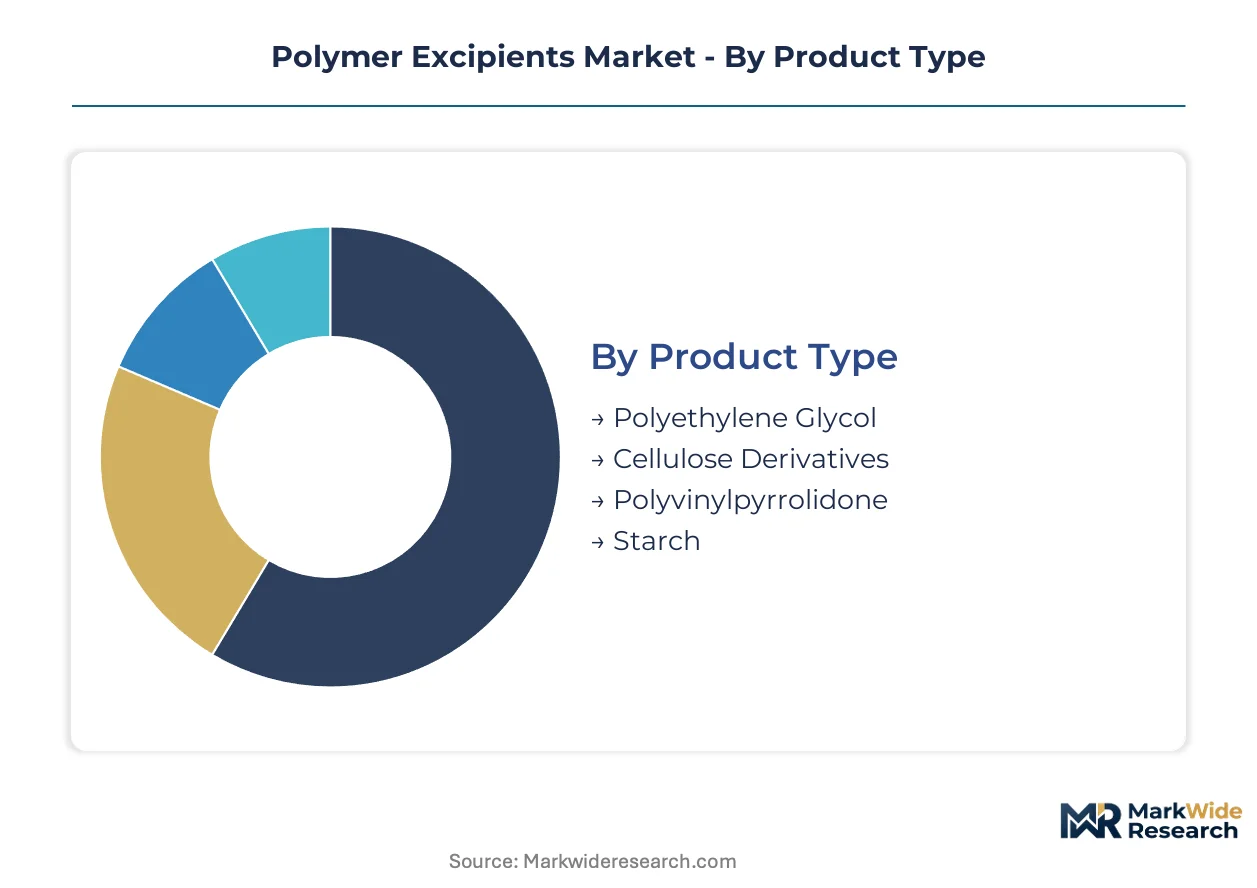
Polymer excipient selection directly determines manufacturing scalability, release kinetics precision, and regulatory compliance pathways. Formulation scientists match segment specifications to dosage form requirements, creating distinct competitive arenas within each category.
Product Type:
Supply concentration in petrochemical and cellulose feedstock streams shapes competitive dynamics across polymer chemistries.
- Cellulose Derivatives:Hydroxypropyl methylcellulose and microcrystalline cellulose dominate oral solid dosage volumes through decades of toxicological validation. Nordic and Southeast Asian pulp mill concentration creates single-source vulnerability for specialty grades.
- Polyethylene Glycol:Petrochemical-derived linear polymers with molecular weights from 200 to 35,000 daltons serve solubilization and ointment bases. Ethylene oxide price volatility tied to crude benchmarks compresses margins for non-integrated producers.
- Polyvinylpyrrolidone:Amorphous polymer with exceptional adhesive and complexation properties for direct-compression tablets and film coatings.
- Starch:Native and pregelatinized grades from corn and potato sources offer cost-sensitive disintegration and binding functionality.
Today's leader: Cellulose Derivatives. Tomorrow's challenger: Polyethylene Glycol.
Application:
Regulatory stringency tiers separate margin pools across end-use sectors, with parenteral and controlled-release platforms commanding premium positioning.
- Pharmaceuticals:Oral solid dosage forms, parenteral solutions, and transdermal patches require pharmacopeial-grade polymers with validated impurity profiles. FDA's Quality by Design initiative tightens functionality-related characteristic specifications for controlled-release matrices.
- Personal Care:Topical delivery systems and cosmetic film formers utilize technical-grade polymers with less stringent monograph compliance, opening private-label supply opportunities.
- Nutraceuticals:Dietary supplement tablets and capsules drive volume demand for standard-grade cellulose derivatives and starch.
- Food Industry:Edible films and encapsulation systems employ food-grade polymer specifications under separate regulatory frameworks.
Pharmaceuticals anchor current value capture. Personal Care offers the steepest expansion trajectory as dermal delivery science advances.
Form:
Processing equipment compatibility and powder flow properties determine form selection for specific manufacturing platforms.
- Powder:Dominant unit volume across wet granulation and direct-compression operations, with particle size distribution critical for blend uniformity.
- Films:Orodispersible and transdermal formats accelerate with pediatric and geriatric compliance engineering, requiring precise plasticizer integration.
- Granules:Pre-processed agglomerates improve flowability for high-speed tablet presses in continuous manufacturing lines.
- Tablets:Pre-compressed excipient bases simplify formulation development for small-batch clinical supply.
Powder maintains volume leadership. Films gain share fastest as patient-centric design priorities reshape dosage form preferences.
End User:
Procurement sophistication and quality agreement complexity segment the customer base into distinct service tiers.
- Pharmaceutical Companies:Integrated Big Pharma operations demand drug master file infrastructure, audit-ready quality systems, and dedicated technical service teams for formulation troubleshooting.
- Contract Manufacturers:CDMOs scaling biosimilar and complex generic capacity require excipient suppliers with validated supply continuity and regulatory response capabilities.
- Biotech Firms:Emerging biopharma companies prioritize speed-to-clinic over cost optimization, accepting premium pricing for ready-to-use excipient kits.
- Research Institutions:Academic and government laboratories drive small-volume demand for experimental polymer grades and custom synthesis services.
Pharmaceutical Companies command supplier attention today. Contract Manufacturers represent the most dynamic expansion segment as manufacturing outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The New Jersey-Pennsylvania pharmaceutical corridor anchors polymer excipient procurement intensity, with formulation scientists clustering around Princeton and Philadelphia CDMO campuses. Regulatory stringency tiers separate regional margin pools, with pharmacopeial-grade specifications commanding premium positioning against technical-grade alternatives.
United States
Biopharma contract manufacturers in Massachusetts and North Carolina expand controlled-release capacity for complex generics and biosimilars. FDA enforces Current Good Manufacturing Practice standards under 21 CFR Parts 210 and 211, compelling drug master file infrastructure investment. The New Jersey corridor concentrates excipient technical service teams serving Big Pharma formulation groups.
Germany
Integrated chemical producers in Ludwigshafen and Marl leverage captive petrochemical feedstocks for polyethylene glycol supply security. EMA's updated excipient risk assessment guidelines mandate nitrosamine impurity screening for secondary amine-containing polymers. The Rhine-Ruhr industrial cluster hosts functionalized polymethacrylate manufacturing for European parenteral markets.
India
Domestic generic manufacturers in Hyderabad and Ahmedabad scale oral solid dosage capacity for regulated export markets. CDSCO aligns with ICH Q13 guidelines on continuous manufacturing, tightening functionality-related characteristic specifications for cellulose derivatives. The Mumbai-Pune corridor attracts excipient suppliers establishing quality agreement templates for emerging biopharma outsourcing.
China
Toll processors in Jiangsu and Zhejiang provinces adopt twin-screw extruders for amorphous solid dispersion manufacturing. NMPA harmonizes pharmacopeial standards with USP-NF monographs for viscosity grades and particle size distributions. The Yangtze River Delta concentrates starch and pregelatinized excipient production for regional nutraceutical markets.
Switzerland
Specialty chemical producers in Basel maintain technology leadership in lipid-polymer hybrid systems for parenteral oncology formulations. Swissmedic enforces batch-to-lot consistency protocols that exceed standard pharmacopeial thresholds. The Basel-Zürich corridor serves as headquarters for global excipient portfolios spanning multiple polymer chemistries.
Polymer Excipients Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue lipid-polymer hybrid architectures and continuous manufacturing compatibility. The vendor base stratifies across three tiers: integrated petrochemical conglomerates with captive feedstock security, mid-cap cellulose specialists dependent on Nordic pulp streams, and niche lipid chemistry boutiques serving parenteral oncology. Two dominant competitive moves define current positioning: backward integration into raw material streams to neutralize price volatility, and analytical infrastructure investment to support real-time release testing protocols for continuous manufacturing lines.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify archetypes of feedstock control and functionalized polymer specialization respectively. BASF SE anchors petrochemical-derived supply chains through backward integration into ethylene oxide feedstocks. Evonik Industries AG occupies a position in polymethacrylate technology for controlled-release matrices. Croda International Plc represents the lipid-polymer hybrid specialist archetype, sitting within the premium parenteral formulation segment.
| Leading Market Players |
|---|
| Ashland Inc. |
| Lubrizol Corporation |
| BASF SE |
| Colorcon Inc. |
| Merck KGaA |
| Evonik Industries AG |
| Roquette Frères |
| Croda International Plc |
| The Dow Chemical Company |
| Others |
Value Network & Pricing Analysis
Ethylene oxide price volatility cascades through polyethylene glycol supply chains, compressing margins for non-integrated producers while rewarding backward-integrated chemical conglomerates with captive petrochemical feedstocks. Nordic pulp benchmark movements similarly transmit into specialty cellulose derivative pricing tiers, separating pharmacopeial-grade suppliers from technical-grade competitors.
Pricing Analysis
Input-cost pass-through dominates polyethylene glycol pricing, with ethylene oxide spot movements transmitting directly to contract renegotiations within 60-90 day windows. Three-tier pricing structure across premium pharmacopeial, standard industrial, and economy technical grades separates FDA-registered suppliers from regional generics. Pricing pressure stems from REACH registration cost amortization for novel synthetic polymers, forcing mid-tier producers toward volume discounts. Generic manufacturers in Eastern Europe exhibit highest price sensitivity, while parenteral oncology formulators accept substantial premiums for nitrosamine-screened grades.
Supply Chain Analysis
Freight cost inflation from Southeast Asian pulp mills to European compounding facilities is reshourcing specialty cellulose derivative procurement toward Nordic integrated producers. Supply concentrates in Germany, United States, and China for functionalized polymethacrylates; India and China for standard-grade cellulose derivatives; and Switzerland for lipid-polymer hybrid systems. Raw material dependencies center on ethylene oxide, dissolving-grade cellulose pulp, and pharmaceutical-grade lipids from vegetable or synthetic sources. Single-source vulnerability pervades Nordic pulp streams, with two mills supplying 70% of specialty-grade dissolving pulp. Distribution runs through qualified pharmaceutical distributors with temperature-controlled logistics and drug master file documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where continuous manufacturing adoption and ICH Q13 compliance requirements concentrate procurement with suppliers possessing validated analytical infrastructure and regulatory response capabilities.
For Market Incumbents: Anticipate CDMO consolidation reducing qualified supplier panels from fifteen to four strategic partners, necessitating drug master file portfolio expansion and dedicated technical service team investment. Defensive positioning requires real-time release testing protocol certification and backward integration into captive ethylene oxide or cellulose pulp streams to neutralize feedstock volatility. Threat substitution from lipid-polymer hybrid systems in parenteral oncology demands polymethacrylate technology refresh. For New Entrants and Emerging Players: Hot-melt extrusion-compatible thermoplastic polymer grades offer a technology-first wedge into generic manufacturer twin-screw extruder adoption curves across Eastern Europe and Latin America. White-space targets include orodispersible film format supply for geriatric compliance engineering and nitrosamine-screened parenteral-grade polyethylene glycol for European EMA compliance. Go-to-market leverage rests on ready-to-use excipient kits accelerating biotech speed-to-clinic timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap cellulose specialists possessing Nordic pulp offtake agreements and polymethacrylate technology licenses. Long-term viability hinges on continuous manufacturing compatibility and real-time release testing infrastructure across a 5-10 year technology transition window. Acquisition target archetype: integrated producers with captive feedstocks and pharmacopeial-grade certification. Signal to watch: FDA inspection intensity accelerating vendor rationalization toward drug master file-heavy suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | BASF SE's captive petrochemical feedstocks neutralize crude-linked price volatility for polyethylene glycol supply security. |
| Real-Time Release Testing Certification | Continuous manufacturing equipment vendors require batch-less consistency protocols from polymethacrylate suppliers. |
| Lipid-Polymer Hybrid R&D Expansion | Croda International Plc's parenteral oncology focus captures premium positioning in liposomal delivery platforms. |
| Drug Master File Portfolio Expansion | CDMO quality agreement templates demand Type II drug master file infrastructure for biosimilar excipient supply. |
| Nitrosamine Screening Laboratory Investment | EMA's secondary amine polymer guidelines compel LC-MS/MS capabilities for European parenteral market access. |
Research Methodology
Bottom-up pharmaceutical formulation modeling reconciled against top-down polymer excipient production tracking forms the analytical core of this study. Primary interviews with formulation scientists at Big Pharma and CDMO operations, regulatory affairs specialists, excipient procurement managers, and compounding pharmacists combined with secondary validation from FDA drug master file databases, USP-NF monograph revisions, EMA excipient risk assessment guidelines, and customs trade data for cellulose derivative and polyethylene glycol flows. Triangulation across supply-side capacity announcements and demand-side dosage form pipeline analysis calibrated segment-level outputs.
The input-output matrix framing connects ethylene oxide and cellulose pulp feedstock availability to downstream excipient grade production capacity across oral solid dosage, parenteral, and transdermal application segments. Segmentation dimensions include polymer chemistry, pharmacopeial grade tier, dosage form compatibility, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections and capacity utilization trajectories across the modeling period. Industry-specific forecast inputs incorporate ICH Q13 continuous manufacturing adoption curves and EMA nitrosamine screening compliance timelines.
The model holds under stable petrochemical feedstock pricing and sustained FDA/EMA regulatory stringency; deviation in cellulose pulp supply disruption or REACH registration pathway acceleration would shift volume trajectories toward substitute polymer chemistries. Forecasts reflect documented assumptions regarding continuous manufacturing penetration and CDMO outsourcing rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
India Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
North America Linear Low-Density Polyethylene Market
Polymers & Resins
Polyester Polyol Market
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
Europe Polyurethane Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Global Furan Resins Market
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Optically Clear Resin Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Global Resin Market