
 Rugged Servers Market | 2026-2036
Rugged Servers Market Size, Share, and Industry Trends Forecast 2026-2036
Rugged Servers Market Analysis
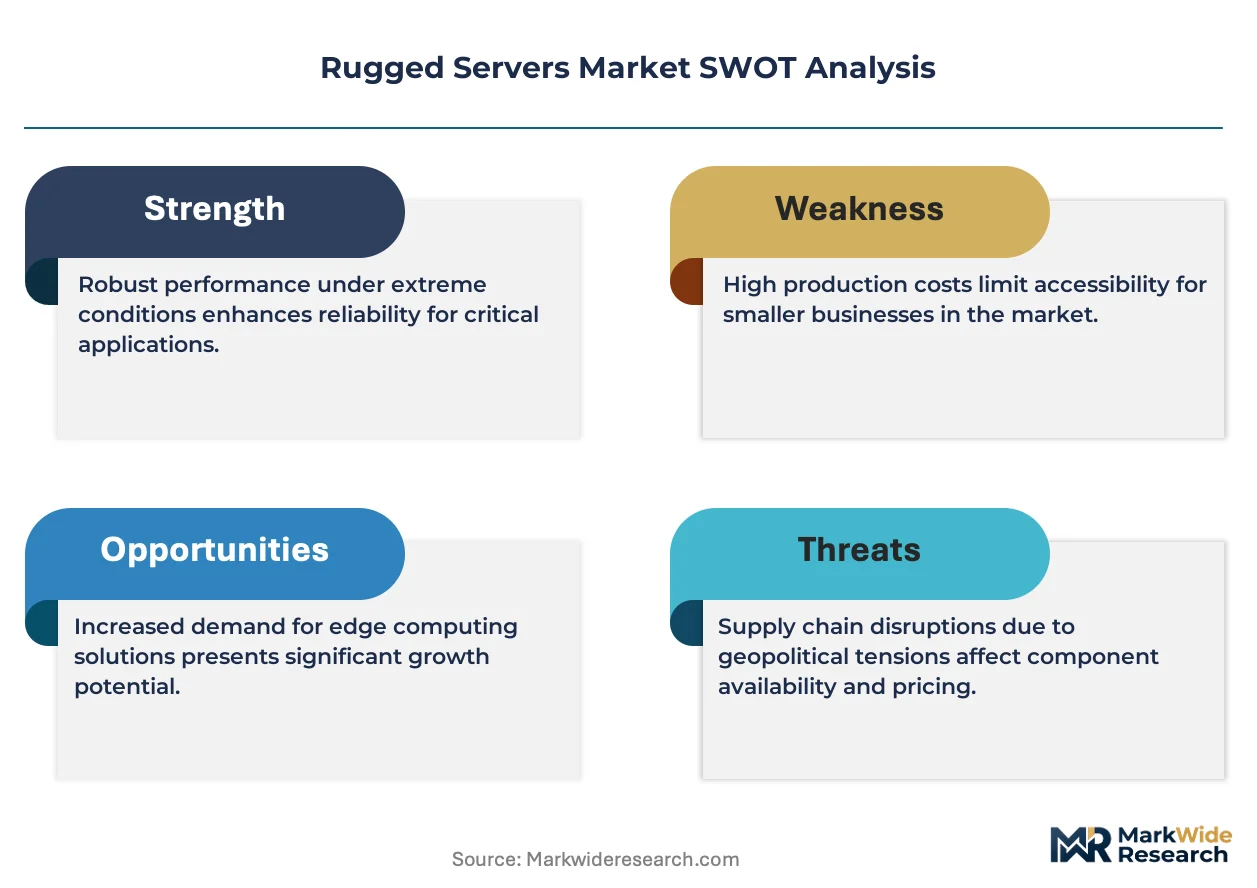
Software-defined feature licensing is decoupling hardware refresh cycles from capability upgrades in rugged server deployments. Mercury Systems leverages long-term sole-source relationships with US defense primes to sustain program-of-record positions across naval combat systems. Crystal Group specializes in thermal management architectures that dominate extreme-temperature outdoor installations for oil and gas telemetry.
Rugged servers are hardened computing platforms engineered to MIL-STD-810 shock/vibration specifications and IP67 environmental sealing, designed to operate in temperatures from -40°C to +85°C for mission-critical command, control, and data processing outside climate-controlled facilities. Rackmount form factors anchor defense datacenter consolidation programs where space-optimized density drives procurement specifications, while edge computing deployments in transportation and energy infrastructure represent the fastest-expanding technology segment as latency-sensitive analytics migrate closer to sensor arrays. Blade configurations occupy niche positions in airborne and maritime platforms where volumetric constraints and modular redundancy override cost considerations.
FAA certification requirements for ground-based air traffic control systems and FCC emissions standards for co-located communications gear shape product design cycles and testing expenditures for manufacturers serving federal infrastructure programs. NHTSA crashworthiness protocols for autonomous vehicle test fleets and EPA energy efficiency mandates for federal procurement create dual compliance burdens that filter vendor qualification pools. Stakeholders must weigh captive versus outsourced thermal testing capacity as qualification timelines extend and defense program budgets shift toward software-centric modernization roadmaps.
Market Dynamics
Defense procurement offices are decoupling hardware refresh cycles from capability upgrades through software-defined licensing models, compressing traditional server replacement timelines while extending platform service lives through firmware-based feature activation.
Growth Catalysts
- MIL-STD-810H Revision:Updated shock and vibration testing protocols are mandating hardened compute infrastructure across NATO battlefield command modernization programs, forcing wholesale electronics suite replacements in armored vehicle fleets.
- Edge Analytics Migration:Latency-sensitive sensor fusion applications in autonomous vehicle testbeds and oilfield telemetry networks are pulling compute resources away from centralized datacenters toward ruggedized field deployments.
- German Defense Spending:Rheinmetall and Krauss-Maffei Wegmann modernization contracts are concentrating demand for sealed, thermally-optimized rackmount systems in European land warfare platforms.
Market Restraints
- Thermal Subsystem Costs:Specialized heat pipe assemblies and conformal cooling channels command 35-40% BOM premiums over standard commercial servers, squeezing margins on fixed-price defense contracts.
- Qualification Timeline Compression:Extended FAA certification cycles for air traffic control ground systems and FCC emissions testing for co-located communications gear are stretching vendor cash conversion cycles.
- FPGA Supply Concentration:Programmable logic device sourcing remains captive to a limited foundry base, exposing rugged server manufacturers to allocation risk on signal processing acceleration cards.
Strategic Opportunities
- India Defense Indigenization:The country's PLI scheme for electronics manufacturing is creating local assembly incentives for MIL-STD-compliant systems serving domestic armored vehicle and naval combat system programs.
- Converged Edge-Cloud Architectures:Containerized workload portability between forward-deployed nodes and rear-echelon infrastructure is opening specification wins for vendors offering unified management stacks.
- EPA Federal Procurement Mandates:Energy efficiency thresholds for datacenter equipment are favoring liquid-cooled rugged designs in domestic infrastructure bids, penalizing legacy air-cooled alternatives.
Industry Challenges
- Thermal Engineering Talent Scarcity:Specialized expertise in conduction-cooled chassis design and phase-change material integration remains concentrated among a narrow cohort of defense-aerospace veterans, constraining vendor scaling.
- Legacy Bus Architecture Integration:Backward compatibility requirements for VME and VPX interconnects in fielded naval combat systems are fragmenting R&D resources across multiple signaling generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rugged Servers Market |
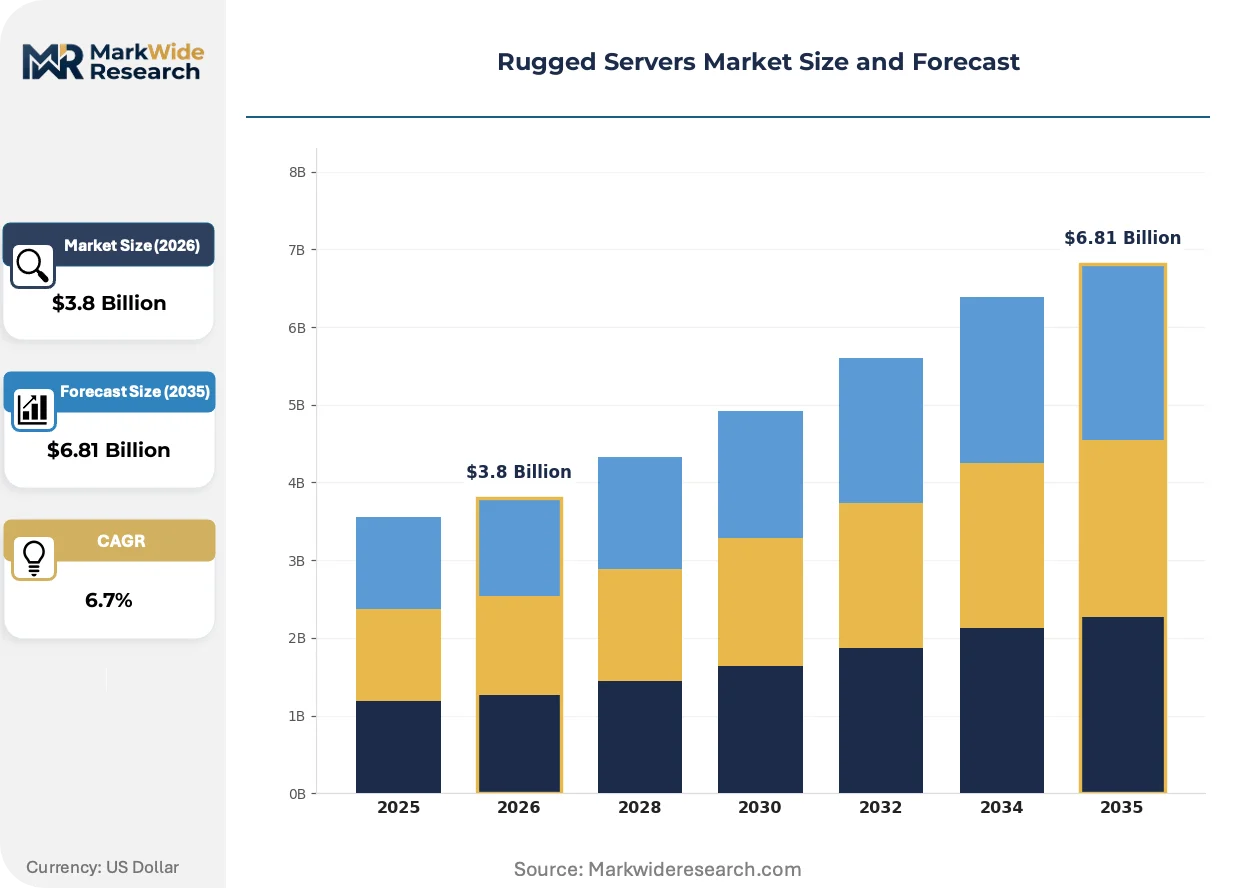
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rackmount, Blade, Tower, Compact End User: Military, Transportation, Manufacturing, Energy Technology: Edge Computing, Virtualization, Cloud Computing, AI Installation: On-Premises, Mobile, Fixed, Others |
| Companies Covered | Dell Technologies, Mercury Systems, Siemens AG, Crystal Group, Core Systems, Advantech Co., Ltd., Trenton Systems, Curtiss-Wright Corporation, Elma Electronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rugged Servers Market Emerging Trajectories
Compute architectures are migrating toward disaggregated resource pools where processing, storage, and acceleration functions ship as independent field-replaceable units rather than monolithic server blades.
Liquid cooling is integrating into sealed chassis designs through single-phase cold plates and pumped two-phase loops, enabling 500W+ processor thermal envelopes in ambient temperatures exceeding 70°C. Defense primes are specifying these subsystems for next-generation radar signal processors and electronic warfare suites. The technology is compressing volumetric constraints that previously forced performance trade-offs in airborne and maritime platforms.
The EU AI Act's risk classification framework is mandating conformity assessment procedures for automated decision systems in critical infrastructure, extending qualification timelines for European defense and energy sector deployments. Manufacturers are responding by pre-certifying training and inference pipelines rather than treating compliance as a customer-side integration burden. Air traffic management and autonomous vehicle test fleet operators represent the most affected buyer segments.
Buyers are unbundling hardware acquisition from sustainment services, demanding separate pricing for spares provisioning, field engineering support, and configuration management. Defense procurement offices in Germany and the United States are leading this shift toward performance-based logistics contracts. Channel partners with existing service footprints are capturing margin that previously accrued to original equipment manufacturers.
Rugged Servers Market Segmentation
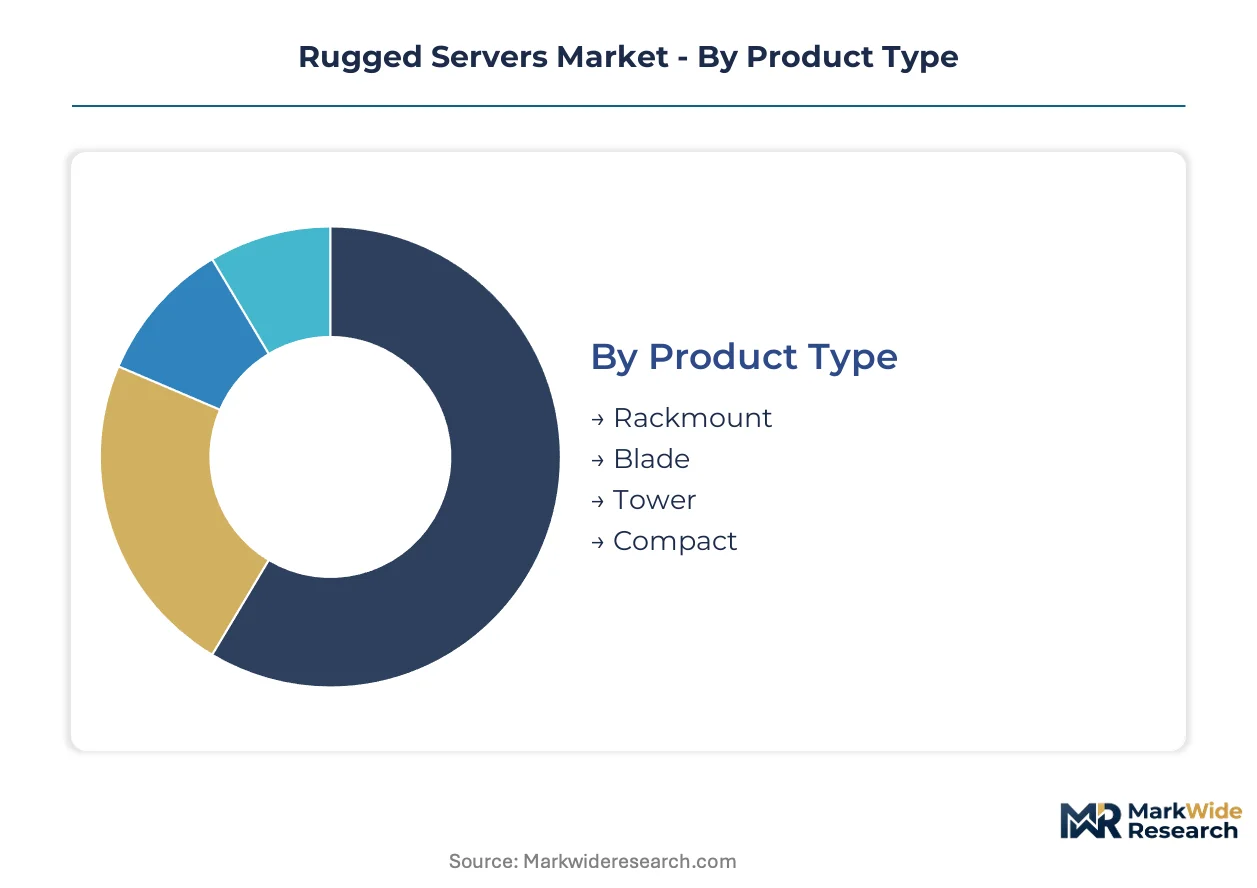
Rugged server procurement patterns diverge sharply across deployment contexts, with defense program offices prioritizing shock-hardened rackmount densities while energy operators favor thermally-optimized compact units for remote telemetry. Segment boundaries are blurring as software-defined licensing enables capability upgrades without hardware swaps, complicating traditional form-factor categorization.
Product Type:
Supply concentration in conduction-cooled chassis manufacturing sits with a narrow cohort of defense-aerospace specialists, constraining vendor scaling for high-specification variants.
- Rackmount:Standardized 19-inch and 23-inch form factors anchor defense datacenter consolidation programs where MIL-STD-810H shock certification and space-optimized density drive procurement specifications. German land warfare electronics modernization contracts through Rheinmetall and Krauss-Maffei Wegmann are concentrating demand for sealed, thermally-optimized rackmount systems in European armored vehicle fleets.
- Blade:Modular configurations with redundant power and cooling domains occupy volumetrically constrained airborne and maritime platforms where hot-swappability overrides unit economics. FAA certification requirements for ground-based air traffic control systems and FCC emissions standards shape extended product design cycles and testing expenditures for blade manufacturers serving federal infrastructure programs.
- Tower:Freestanding enclosures suit fixed-site industrial deployments with available floor space and moderate environmental exposure.
- Compact:Reduced-footprint designs address edge computing deployments in transportation and oilfield telemetry where sensor proximity demands minimal latency.
Rackmount configurations absorb the bulk of installed capacity; compact units are expanding most quickly as latency-sensitive analytics migrate closer to sensor arrays.
End User:
Customer procurement maturity varies across sectors, with defense offices leading performance-based logistics contracting while energy buyers still bundle hardware and sustainment.
- Military:Battlefield command systems, naval combat platforms, and armored vehicle electronics suites demand MIL-STD-810 shock and vibration certification plus IP67 environmental sealing for operation across -40°C to +85°C temperature ranges. NATO member state procurement offices are decoupling hardware refresh cycles from capability upgrades through software-defined licensing models.
- Transportation:Autonomous vehicle test fleets and rail signaling infrastructure require NHTSA crashworthiness protocols and FCC emissions compliance for co-located communications gear.
- Manufacturing:Shop-floor data acquisition and process control systems prioritize dust ingress protection and electromagnetic compatibility in heavy industrial environments.
- Energy:Oil and gas telemetry networks and renewable generation monitoring leverage extreme-temperature outdoor installations where thermal management architectures dominate vendor selection.
Military end users command the largest share of qualification-tested inventory; energy sector deployments are climbing the fastest as digital oilfield investments accelerate.
Technology:
Margin structures diverge across technology tiers, with AI acceleration cards carrying FPGA supply concentration risk while virtualization software enables recurring revenue capture.
- Edge Computing:Distributed processing nodes positioned proximal to sensor arrays reduce backhaul latency for real-time decision loops in autonomous systems and industrial automation. Containerized workload portability between forward-deployed nodes and rear-echelon infrastructure is opening specification wins for vendors offering unified management stacks.
- Virtualization:Hypervisor abstraction layers decouple operating environments from underlying hardware, extending platform service lives through firmware-based feature activation without physical replacement.
- Cloud Computing:Hybrid architectures connect field-hardened nodes to centralized infrastructure for non-time-critical analytics and long-term data retention.
- AI:Training and inference pipelines for automated decision systems face extended qualification timelines under the EU AI Act's risk classification framework for critical infrastructure deployments.
Edge computing absorbs the bulk of current deployment investment; AI-enabled configurations are gaining share fastest as electronic warfare and radar signal processing demands intensify.
Installation:
Channel economics vary by mobility requirement, with mobile deployments demanding field engineering footprints that shift margin toward service-capable partners.
- On-Premises:Fixed-site datacenter and control room installations benefit from climate-controlled environments that relax thermal design constraints and enable standard commercial cooling architectures.
- Mobile:Vehicle-mounted and forward-deployed platforms require active suspension isolation, conformal coatings, and sealed enclosures to sustain compute availability through shock, vibration, and contamination exposure.
- Fixed:Permanent outdoor installations such as air traffic control towers and pipeline monitoring stations combine weatherproofing with remote management capabilities for unmanned operation.
- Others:Specialized deployment modes including airborne rack integrations and maritime below-deck mounting adapt standard form factors to platform-specific mechanical interfaces.
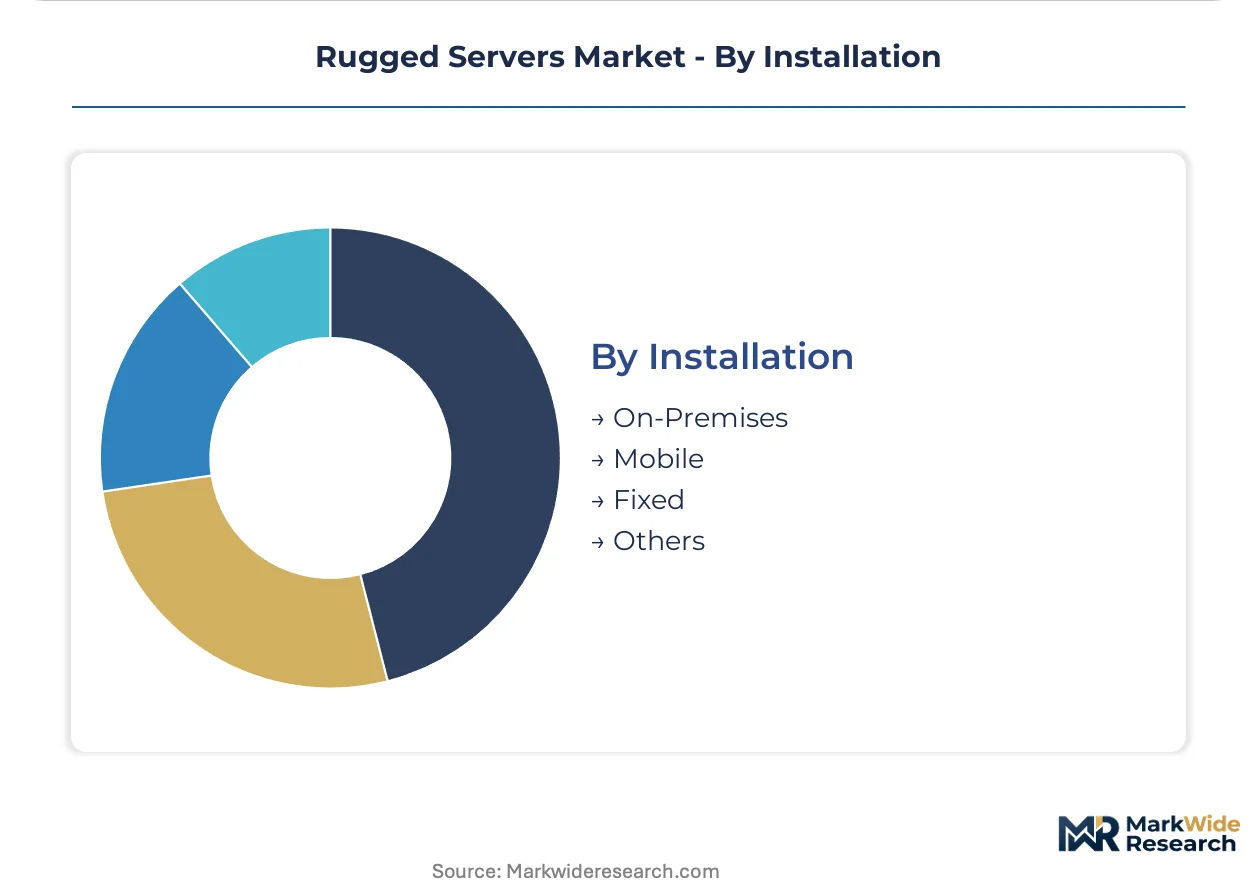
On-premises installations retain the largest installed base; mobile deployments are expanding most quickly as battlefield command modernization programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich and the Bavarian defense corridor anchor European procurement intensity for hardened compute platforms. Rheinmetall and Krauss-Maffei Wegmann modernization contracts concentrate demand for MIL-STD-810H certified rackmount systems in German armored vehicle fleets.
United States
Naval combat system modernization and battlefield command programs drive procurement through sole-source relationships with defense primes. FCC emissions standards and FAA certification requirements for ground-based air traffic control systems shape extended vendor qualification timelines. Mercury Systems sustains program-of-record positions across naval platforms from its Massachusetts operations.
Germany
Rheinmetall and Krauss-Maffei Wegmann electronics suite upgrades concentrate demand for thermally-optimized sealed enclosures in European land warfare platforms. The EU AI Act's risk classification framework extends conformity assessment timelines for automated decision systems in critical infrastructure. Bavaria's defense-industrial cluster around Munich anchors continental procurement volume for NATO battlefield command systems.
India
Domestic armored vehicle and naval combat system programs are expanding under the PLI scheme for electronics manufacturing. The country's national defense procurement regulator is tightening local content requirements for MIL-STD-compliant systems. Bengaluru and Hyderabad clusters are emerging as assembly locations for indigenous rugged server production.
China
Dual carbon goals and MIIT industrial digitization mandates are pulling compute resources toward edge deployments in energy and transportation infrastructure. GB standards for electromagnetic compatibility shape product design cycles for domestic vendors. The Yangtze River Delta manufacturing corridor concentrates chassis fabrication capacity for thermally-hardened platforms.
Japan
METI industrial automation roadmaps and maritime platform electronics upgrades sustain demand for conduction-cooled blade configurations. JIS standards for shock and vibration resistance filter vendor qualification pools for defense-aerospace applications. The Kanto region around Tokyo anchors procurement for naval combat system modernization programs.
Rugged Servers Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the rugged server value chain. The vendor base clusters around three strategic archetypes: defense-aerospace specialists with captive thermal engineering expertise, diversified industrial electronics houses leveraging cross-platform component sourcing, and regional system integrators serving domestic procurement mandates. Competitive positioning hinges on qualification timeline acceleration through pre-certified subsystem libraries and performance-based logistics contracting that shifts margin toward service-capable channel partners.
Within the defense-aerospace specialist tier, Mercury Systems and Curtiss-Wright Corporation exemplify archetypes built on long-term program-of-record relationships with NATO defense primes. Crystal Group occupies a position among thermally-focused specialists serving extreme-temperature outdoor installations. Siemens AG represents the diversified industrial electronics house model with cross-sector component leverage.
| Leading Market Players |
|---|
| Dell Technologies |
| Mercury Systems |
| Siemens AG |
| Crystal Group |
| Core Systems |
| Advantech Co., Ltd. |
| Trenton Systems |
| Curtiss-Wright Corporation |
| Elma Electronic |
| Others |
Supply Flow & Price Mechanics
Aluminum alloy price indices cascade through rugged server supply chains into three-tier pricing structures across premium, standard, and economy levels, with MIL-STD-810H certification grades and thermal subsystem complexity separating tiers. Defense procurement offices absorb premium positioning for shock-hardened rackmount densities, while energy sector buyers cluster in mid-tier compact units where after-sales service bundling commands margin.
Pricing Analysis
Margin tightening in economy-tier compact units reflects FPGA allocation risk and extended qualification timelines that compress vendor cash conversion cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by MIL-STD-810H certification depth, liquid-cooled versus air-cooled thermal architectures, and performance-based logistics contract inclusion. Cost-down pressure on blade configurations accelerates as FAA certification cycles for air traffic control ground systems stretch vendor working capital requirements. Military end users demonstrate lowest price sensitivity given sole-source program-of-record relationships; energy sector buyers exhibit highest elasticity, unbundling hardware from sustainment services.
Supply Chain Analysis
MIL-STD-810H qualification gating concentrates chassis fabrication capacity among defense-aerospace specialists in the United States, Germany, and Japan. Supply chains draw from Taiwan and South Korea for programmable logic devices, China for aluminum alloy chassis extrusions, and domestic foundries in buyer countries for final assembly. Single-source vulnerability in FPGA sourcing exposes rugged server manufacturers to allocation risk on signal processing acceleration cards. Distribution runs through defense primes with captive integration capabilities and regional system integrators serving domestic procurement mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rugged servers market sits in a technology-transition phase where liquid-cooled sealed chassis designs displace legacy air-cooled architectures in 500W+ processor deployments. Software-defined licensing models are decoupling hardware refresh from capability upgrade cycles.
For Market Incumbents: Acquire thermal engineering talent pools concentrated among defense-aerospace veterans to offset capability scarcity in conduction-cooled chassis design. Consolidate pre-certified subsystem libraries to compress FAA and FCC qualification timelines that threaten working capital. Deepen backward integration into heat pipe assemblies to defend margin position against 35-40% BOM premiums on specialized cooling components. For New Entrants and Emerging Players: Direct-to-defense-procurement digital channels offer specification entry points for vendors lacking sole-source relationships with US primes. Target India's PLI scheme for electronics manufacturing where domestic content requirements are tightening for MIL-STD-compliant systems. White-space exists in containerized workload portability solutions connecting forward-deployed edge nodes to rear-echelon cloud infrastructure. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive thermal testing capacity and established program-of-record positions. Long-term viability hinges on performance-based logistics contracting capabilities that shift margin toward service-heavy channel partners. Watch for inflection in German defense spending allocations to Rheinmetall and Krauss-Maffei Wegmann electronics suite modernization programs.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certified Subsystem Library Expansion | Compresses FAA certification timelines for air traffic control ground systems. |
| Liquid Cooling Architecture Investment | Enables 500W+ processors in ambient temperatures exceeding 70°C for radar signal processing. |
| Performance-Based Logistics Contracting | Captures margin shift from OEMs to service-capable channel partners in German procurement. |
| India PLI Scheme Localization | Positions vendors for domestic armored vehicle and naval combat system assembly mandates. |
| Containerized Workload Portability Platform | Unifies management stacks across forward-deployed edge nodes and rear-echelon infrastructure. |
Methodological Framework
Multi-period observation of defense procurement contract awards, thermal subsystem BOM compositions, and qualification timeline durations anchored the trend analysis, supplemented by interviews with program managers at NATO defense primes, thermal engineering directors at chassis manufacturers, and procurement officers at energy sector telemetry operators. Secondary validation drew from MIL-STD-810H revision documentation, FCC emissions testing registries, FAA certification databases, and EPA federal procurement mandate filings. Bottom-up unit shipment modeling triangulated against top-down defense budget allocation analysis across the analysis window.
Segment-weighting approaches distributed volume and value across rackmount, blade, and compact form factors; military, transportation, manufacturing, and energy end users; and edge computing, virtualization, cloud, and AI technology tiers. CAGRs were derived from deployment trajectory modeling tied to NATO battlefield command modernization schedules and digital oilfield investment cycles. Industry-specific inputs included Rheinmetall and Krauss-Maffei Wegmann electronics suite upgrade timelines and India PLI scheme localization incentives.
The model holds under steady defense budget commitments and stable FPGA foundry allocation; deviation in NATO procurement acceleration or Taiwan Strait supply disruptions would shift trajectory. A model refresh is warranted upon material change in MIL-STD-810H revision implementation schedules or EU AI Act conformity assessment timeline extensions for critical infrastructure deployments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Mexico Data Center Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Data Center IT Asset Disposition Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
United Arab Emirates Data Center Power Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
New Zealand Data Center Rack Market