
 China Internet Data Center Market | 2026-2036
China Internet Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
China Internet Data Center Market Outlook
Platform licensing revenue is reshaping competitive economics as operators monetize software stacks atop commodity infrastructure. China Telecom leverages its state-backed fiber backbone to dominate wholesale connectivity provisioning. GDS Services anchors premium positioning through hyperscale specialization for multinational cloud tenants. Chindata Group differentiates via captive renewable energy sourcing for its northern China campuses.
China Internet Data Center denotes purpose-built facilities housing servers, storage, and networking equipment with redundant power, precision cooling below 1.3 PUE, and cross-connect fiber density exceeding 500 strands per rack, serving as the physical substrate for enterprise IT workload hosting and interconnection. Colocation remains the margin-rich core as enterprises outsource facility ownership while retaining hardware control. Edge computing deployments within hybrid cloud architectures are expanding fastest at metro network peripheries to serve autonomous systems and industrial IoT latency requirements.
MIIT enforces GB 50174 design standards and dual carbon intensity targets that filter market entry toward efficient operators, while SAMR scrutinizes cross-border data flows under cybersecurity law. NMPA-aligned data governance for healthcare workloads adds sector-specific compliance layering. Stakeholders must weigh capex allocation between retrofitting legacy Tier II facilities against greenfield Tier IV construction in western renewable energy zones.
Market Dynamics
MIIT's dual carbon intensity mandates are compressing facility economics and forcing wholesale infrastructure replacement across northern China's coal-dependent grid zones.
Growth Catalysts
- Hyperscale cloud expansion:Alibaba Cloud and Tencent Cloud are commissioning multi-hundred-megawatt campuses in Greater Bay Area clusters to serve enterprise workload migration.
- GB 50174 Tier IV certification:MIIT enforcement of fault-tolerant design standards is filtering market entry toward operators capable of concurrent maintainability.
- Liquid cooling retrofits:Immersion and cold-plate systems are displacing air-cooled legacy infrastructure to meet sub-1.3 PUE requirements in Beijing-Tianjin-Hebei.
Market Restraints
- Land use restrictions:Municipal governments in core tier-one cities are limiting data center construction permits to control energy consumption quotas.
- Copper and power equipment costs:Busbar and transformer supply concentration in eastern manufacturing zones is inflating capex for western greenfield projects.
- Cross-border data governance:SAMR cybersecurity law compliance is adding operational friction for multinational tenants requiring transnational workload portability.
Strategic Opportunities
- Western renewable energy zones:Inner Mongolia and Gansu provinces offer stranded solar and wind capacity for off-grid hyperscale development.
- Edge computing at metro peripheries:Autonomous vehicle infrastructure and industrial IoT are creating latency-sensitive demand in Yangtze River Delta secondary cities.
- AI training cluster specialization:GPU-dense configurations for large language model development represent a premium tenant segment with distinct power density requirements.
Industry Challenges
- Skilled operations talent:Shortage of certified facility engineers capable of managing liquid cooling infrastructure and critical power systems is constraining expansion velocity.
- Legacy facility stranded asset risk:Tier II campuses in saturated eastern markets face accelerated obsolescence as tenants migrate to certified Tier IV alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Internet Data Center Market |
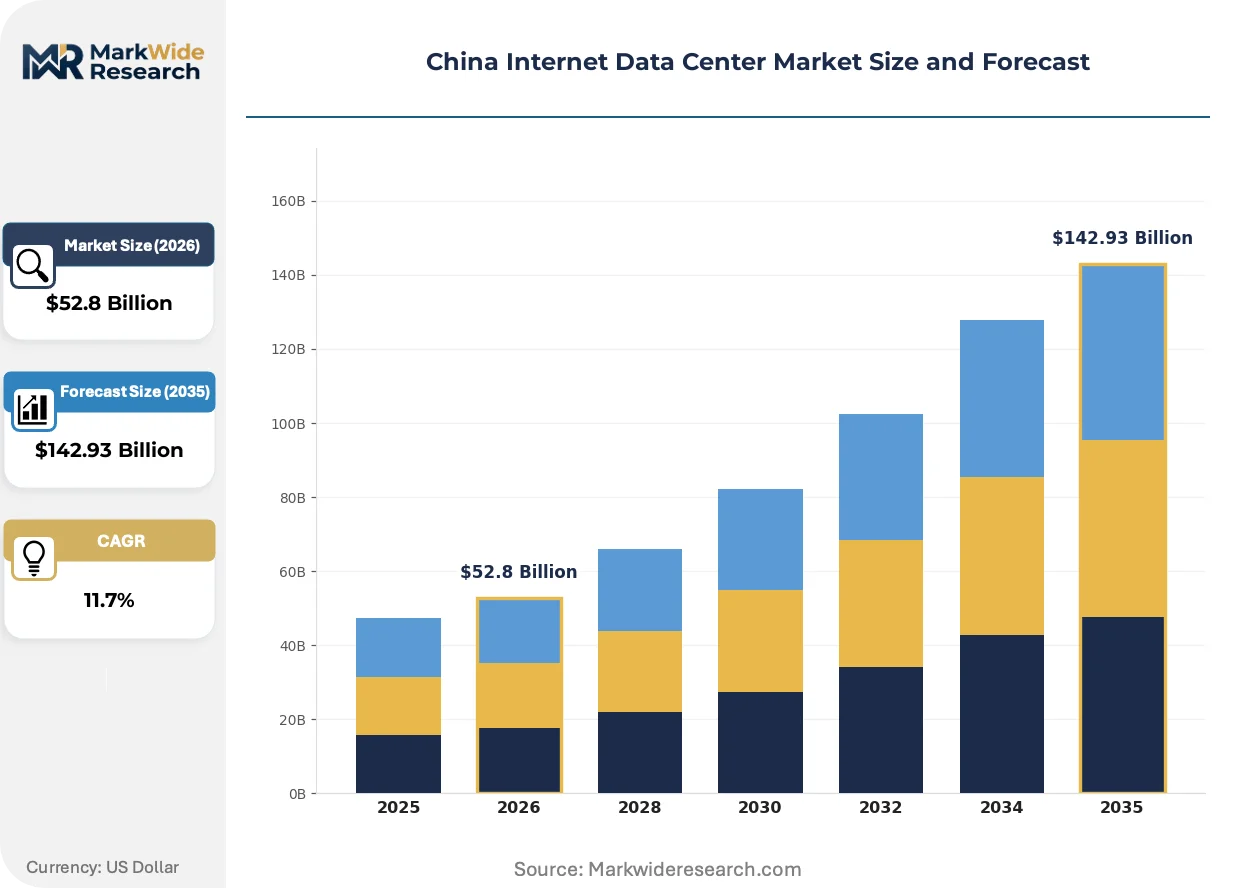
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $142.93 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Services, Cloud Services, Disaster Recovery End User: Retail Sector, Financial Services, Telecommunications, Government Technology: Hyperconverged Infrastructure, Virtualization, Networking, Security Solutions Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Edge Computing |
| Companies Covered | China Telecom, China Mobile, China Unicom, GDS Services, Chindata Group, VNET Group, Alibaba Group, Tencent, Chayora, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Internet Data Center Market Strategic Shifts
Software-defined infrastructure is dissolving traditional boundaries between compute, storage, and networking layers. Facility operators are repositioning as platform companies.
Software-defined power distribution is virtualizing electrical infrastructure management through intelligent rack-level PDUs and DCIM integration. Hyperscale tenants are deploying these systems to enable dynamic workload placement and real-time capacity optimization. This architecture is virtualizing the traditional electrical hierarchy and compressing commissioning timelines for multi-tenant environments.
MIIT's dual carbon goals are mandating renewable energy procurement percentages and carbon intensity tracking for all new data center permits. Operators must now contract directly with provincial grid entities for green power certificates or develop captive solar arrays. Northern China campuses are responding by relocating construction to western regions with surplus wind and photovoltaic capacity.
Enterprise procurement is consolidating vendor relationships around integrated platform providers offering colocation, connectivity, and managed services bundles. Channel intermediaries specializing in pure real estate brokerage are losing share to direct operator sales teams. This pattern is most pronounced in Shanghai and Shenzhen where multinational cloud tenants prefer single-accountability structures.
China Internet Data Center Market Segmentation
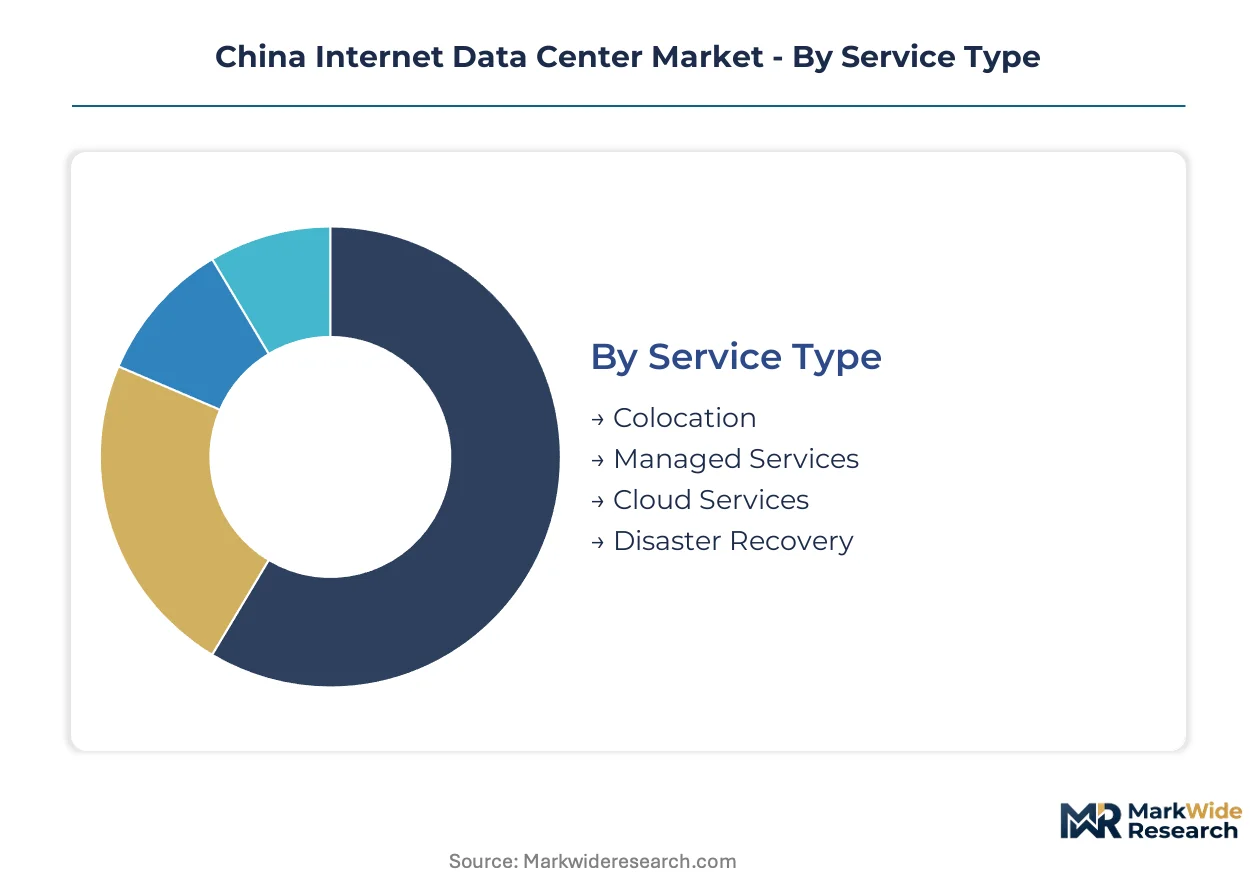
Segmentation in China's data center market reveals how tenant requirements diverge across workload criticality, compliance exposure, and infrastructure control preferences. MIIT's dual carbon mandates and SAMR data governance rules are reshaping which service configurations qualify for new permits.
Service Type:
Colocation dominates facility revenue as enterprises outsource physical infrastructure while retaining hardware sovereignty.
- Colocation:Tenants lease rack space, power, and cooling while owning servers, creating margin-rich recurring revenue for operators. Beijing-Tianjin-Hebei corridor concentration reflects proximity to state-owned enterprise headquarters and hyperscale cloud availability zones.
- Managed Services:Operators assume hardware lifecycle management, remote hands, and monitoring responsibilities. Financial services tenants in Shanghai and Shenzhen drive premium pricing for 24/7 operational support and NMPA-aligned audit trails.
- Cloud Services:Wholesale leasing to Alibaba Cloud, Tencent Cloud, and Huawei Cloud under long-term power purchase agreements.
- Disaster Recovery:Secondary site replication for tier-one city primary workloads, concentrated in western renewable energy zones for cost arbitrage.
The dominant share belongs to Colocation, while Managed Services is closing the gap fastest.
End User:
Demand concentration maps directly to regulatory intensity and data sovereignty requirements.
- Financial Services:Banks and insurers require GB 50174 Tier IV certification, encrypted cross-connects, and SAMR audit compliance. Shanghai Pudong and Shenzhen Qianhai clusters attract this segment through proximity to securities exchanges and payment clearing infrastructure.
- Telecommunications:China Telecom and China Unicom lease wholesale space for 5G core network functions and edge caching nodes. Yangtze River Delta secondary cities are seeing accelerated deployment for low-latency consumer services.
- Retail Sector:E-commerce platforms and omnichannel operators need burst capacity during promotional cycles.
- Government:Provincial cloud platforms and public service digitization projects mandate sovereign data residency.
Financial Services commands premium pricing per rack, with Telecommunications expanding most quickly through state-mandated infrastructure rollout.
Technology:
Technology choices determine power density ceilings and retrofit compatibility with liquid cooling mandates.
- Hyperconverged Infrastructure:Integrated compute-storage nodes reduce rack footprint and simplify lifecycle management. Greater Bay Area manufacturing enterprises favor this architecture for rapid deployment of ERP and MES systems.
- Virtualization:Software-defined compute partitioning enables multi-tenant density optimization.
- Networking:400G spine-leaf architectures and SD-WAN integration for inter-facility workload portability.
- Security Solutions:Hardware security modules and zero-trust network segmentation for SAMR cybersecurity law compliance.
Hyperconverged Infrastructure leads technology spending, though Security Solutions is gaining priority weighting from compliance-driven procurement.
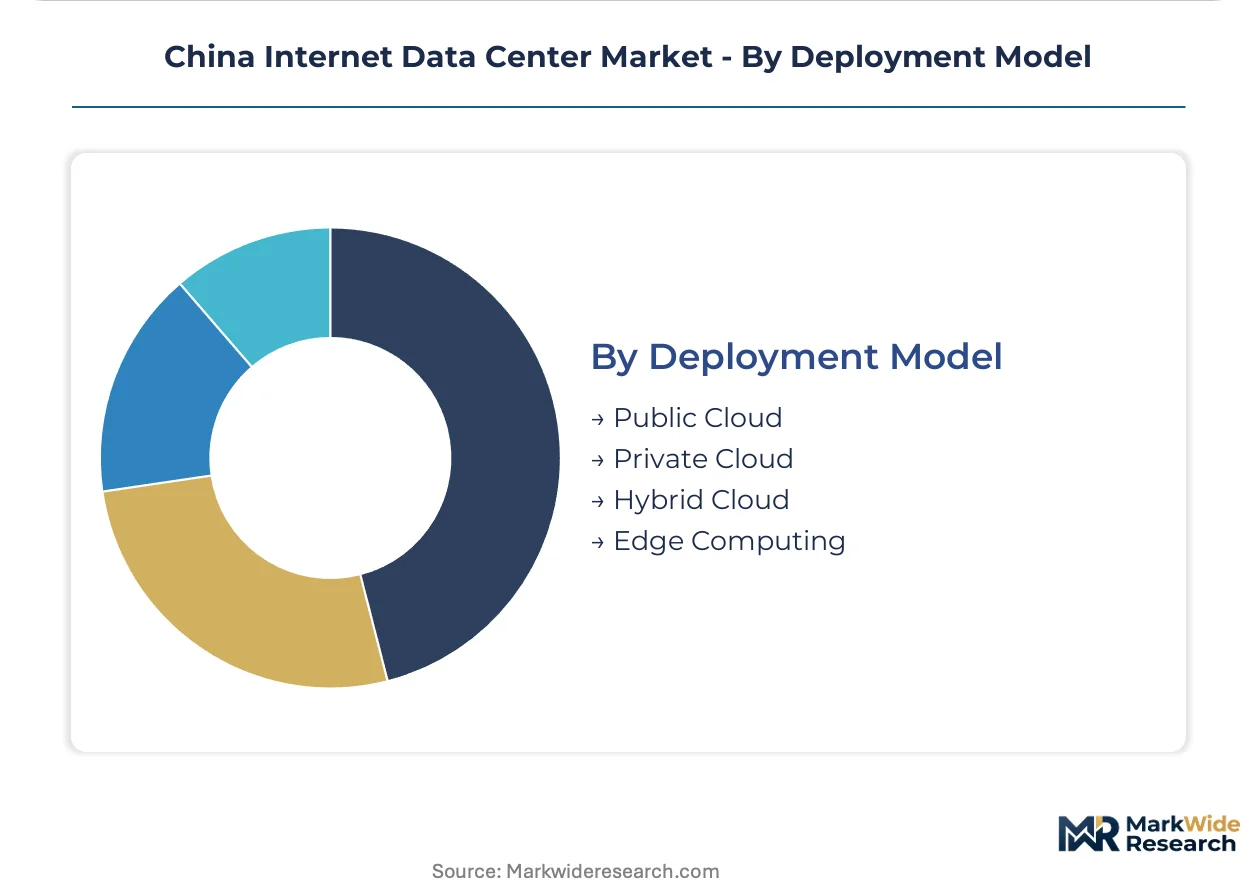
Deployment Model:
Deployment architecture selection reflects data classification tiers and latency tolerance boundaries.
- Hybrid Cloud:Combines on-premises colocation with burst capacity to public cloud, enabling workload portability without full migration. Multinational manufacturers in Suzhou and Dongguan prefer this model for operational technology isolation.
- Edge Computing:Micro data centers at metro network peripheries serve autonomous vehicle infrastructure and industrial IoT sub-10ms latency requirements. Yangtze River Delta secondary cities are seeing concentrated rollout.
- Private Cloud:Dedicated infrastructure for single-tenant control in regulated sectors.
- Public Cloud:Shared hyperscale facilities operated by cloud service providers directly.
Hybrid Cloud retains the largest installed base, while Edge Computing is climbing the fastest on autonomous systems deployment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing-Tianjin-Hebei clusters consume data center capacity for state-owned enterprise headquarters and hyperscale cloud zones, while Yangtze River Delta and Greater Bay Area geographies prioritize financial services latency and cross-border connectivity. Western renewable energy zones attract compute-intensive workloads through stranded solar and wind capacity.
Beijing-Tianjin-Hebei
Hyperscale cloud availability zones and SOE IT consolidation drive demand concentration in this northern corridor. MIIT enforces sub-1.3 PUE mandates through GB 50174 standards, forcing liquid cooling retrofits across legacy facilities. Zhangjiakou and Langfang sub-clusters absorb overflow capacity as Beijing municipal permits tighten.
Yangtze River Delta
Financial services tenants and semiconductor manufacturing supply chains anchor consumption in Shanghai, Suzhou, and Hangzhou metro zones. SAMR cybersecurity law compliance adds operational layering for cross-border data flows. Ningbo and Jiaxing secondary cities are seeing edge computing deployment for industrial IoT latency requirements.
Greater Bay Area
Cross-border financial connectivity and export-oriented manufacturing digitization distinguish demand in Shenzhen, Guangzhou, and Dongguan. MIIT dual carbon goals filter permits toward operators with renewable energy procurement contracts. Qianhai and Nansha sub-districts concentrate Tier IV certified facilities for multinational cloud tenants.
Western Renewable Energy Zones
Inner Mongolia and Gansu provinces offer stranded wind and photovoltaic capacity for off-grid hyperscale development. Provincial grid entities negotiate direct green power certificate contracts with operators. Hohhot and Lanzhou campuses serve training workloads for large language model development with distinct power density profiles.
Sichuan-Chongqing
Consumer internet platform expansion and gaming sector infrastructure anchor demand in this southwestern cluster. Local energy bureaus enforce carbon intensity tracking for all new facility permits. Chengdu and Chongqing metropolitan districts attract disaster recovery secondary sites through cost arbitrage against eastern primary workloads.
China Internet Data Center Market Competitive Environment
Capability concentration sits with hyperscale specialists commanding premium positioning through Tier IV certification and captive renewable sourcing; scale advantage sits with state-backed carriers leveraging fiber backbone density for wholesale connectivity provisioning. The market structures around three archetypes: state-owned telecommunications incumbents, independent hyperscale developers, and cloud service provider captive facilities. Competitive moves center on western greenfield capacity expansion and liquid cooling technology partnerships.
Within the state-backed carrier tier, China Telecom exemplifies wholesale connectivity dominance through backbone infrastructure control. GDS Services and Chindata Group occupy positions among independent developers specializing in multinational tenant hyperscale requirements. These three entities represent divergent strategic paths: fiber-integrated provisioning, premium certification specialization, and captive renewable energy sourcing respectively.
| Leading Market Players |
|---|
| China Telecom |
| China Mobile |
| China Unicom |
| GDS Services |
| Chindata Group |
| VNET Group |
| Alibaba Group |
| Tencent |
| Chayora |
| Others |
Value Chain & Pricing Dynamics
Zhangjiakou and Langfang sub-clusters in Hebei Province concentrate hyperscale capacity buildouts, translating stranded western renewable energy into pricing leverage for operators securing long-term power purchase agreements with provincial grid entities.
Pricing Analysis
Long-term offtake contracts dominate hyperscale tenant negotiations, with wholesale power purchase agreements anchoring rack-rate economics across northern China campuses. Pricing stratifies across GB 50174 Tier IV certification tiers, with fault-tolerant designs commanding premiums over concurrent maintainability-lacking alternatives. Cost compression in Tier II legacy facilities is intensifying because MIIT dual carbon mandates accelerate tenant migration to certified alternatives. Financial services tenants in Shanghai and Shenzhen exhibit lowest price sensitivity, prioritizing encrypted cross-connects and SAMR audit compliance over per-rack economics.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Quanta, and Wistron for server assembly, while Schneider Electric and Vertiv dominate critical power and cooling equipment. Geographic supply concentration draws from China for busbar and transformer fabrication, South Korea for memory modules, and Taiwan for advanced networking silicon. Copper and power equipment dependencies create single-source vulnerability when eastern manufacturing zones face logistics congestion. Distribution runs through direct operator sales teams displacing channel intermediaries in tier-one metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed services attach rates are expanding faster than raw colocation space, as operators capture recurring revenue through remote hands, hardware lifecycle management, and NMPA-aligned compliance layering.
For Market Incumbents: Build certification moats through accelerated GB 50174 Tier IV conversion of legacy Beijing-Tianjin-Hebei campuses before tenant migration accelerates. Defend against Chindata Group's captive renewable positioning by contracting direct green power certificates with Inner Mongolia grid entities. Prioritize liquid cooling engineering talent acquisition to constrain expansion velocity of underqualified competitors. For New Entrants and Emerging Players: Pursue edge computing deployment in Yangtze River Delta secondary cities where autonomous vehicle infrastructure and industrial IoT latency requirements outpace incumbent footprint. Western renewable energy zones offer the most penetrable geography for greenfield hyperscale development through stranded solar and wind capacity. Lead with AI training cluster specialization as a distinct go-to-market angle, targeting GPU-dense configurations for large language model development with unique power density profiles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hyperscale specialists with Tier IV certification and captive renewable sourcing over undifferentiated colocation operators. Long-term viability hinges on 5-10 year carbon intensity compliance trajectories under tightening MIIT enforcement. Watch for inflection through quarterly tracking of provincial permit issuance rates and liquid cooling retrofit completion timelines across northern China portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| GB 50174 Tier IV Certification Investment | MIIT enforcement of fault-tolerant standards filters market entry toward qualified operators. |
| Western Renewable Energy Zone Expansion | Inner Mongolia and Gansu stranded solar capacity enables off-grid hyperscale development with carbon compliance. |
| Liquid Cooling Technology Partnership | Immersion and cold-plate retrofits meet sub-1.3 PUE mandates in Beijing-Tianjin-Hebei corridor. |
| Managed Services Platform Integration | Remote hands and NMPA-aligned audit trails capture premium pricing from financial services tenants. |
| Edge Computing Metro Periphery Deployment | Yangtze River Delta secondary cities serve autonomous vehicle sub-10ms latency requirements. |
Study Parameters
Initial hypotheses were tested against primary input from data center facility engineers, hyperscale cloud procurement officers, MIIT regulatory compliance leads, and provincial grid planning directors, and refined through secondary validation against MIIT permit databases, SAMR cybersecurity law filings, hyperscaler capex disclosures, and GB standards technical committees. Bottom-up rack-level capacity aggregation triangulated against top-down provincial energy bureau consumption forecasts.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling service type, end user vertical, technology architecture, and deployment model dimensions alongside regional regulatory cluster variations. CAGRs derived from installed base evolution and replacement cycle timing, incorporating liquid cooling retrofit penetration curves and renewable energy procurement contract velocity as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in renewable energy certificate pricing, copper commodity volatility, or municipal land use permit issuance would shift the trajectory. Forecasts reflect documented assumptions on MIIT enforcement intensity and SAMR cross-border data governance evolution. Quarterly review of provincial permit issuance rates and hyperscale tenant migration timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Italy Data Center Server Market
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
Jakarta Data Center Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Taiwan Data Center Physical Security Market
Data Center Infrastructure
Rugged Servers Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Philippines Data Center Market
Data Center Infrastructure
Indonesia Data Center Construction Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
Cloud Network Infrastructure Market
Data Center Infrastructure
Thailand Data Center Power Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market