
 Middle East Data Center Market | 2026-2036
Middle East Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Data Center Market Outlook
The capital-intensity divergence between hyperscale-ready and legacy-telco operators is reorganizing competitive tiers across the Gulf. Khazna Data Centers leverages sovereign-backed balance sheets to anchor mega-facility development in Abu Dhabi. Gulf Data Hub competes through submarine cable landing rights and cross-border fiber connectivity. STC sustains geographic dominance via captive land and power allocations across Saudi Arabia's economic zones.
A data center constitutes a dedicated facility housing compute, storage, and networking infrastructure with controlled environmental parameters—typically maintaining ambient temperatures between 18°C and 27°C and power usage effectiveness ratios below 1.5 for modern builds—designed to ensure continuous availability of digital services for enterprises and cloud providers. Modular product types lead capital deployment timelines by compressing construction schedules from 24 months to under 12 months in Gulf markets. Colocation deployment structures capture expanding margin pools as enterprises exit owned-facility obligations. Cooling technology segments face structural pressure as ambient desert temperatures exceed 45°C during summer peaks, driving liquid-cooling adoption and evaporative system redesigns.
SFDA data-sovereignty requirements and UAE's dual-carbon goals constrain facility design while creating compliance-driven demand for certified local builds. Saudi CITC licensing frameworks and Bahrain's TRA cloud-first policies shape market access rules for foreign operators. Stakeholders must monitor sovereign wealth fund capital allocation shifts and power grid interconnection timelines before committing to multi-year capacity expansion.
Market Dynamics
Hyperscale cloud providers are compressing facility design cycles across the Gulf, forcing incumbent operators to choose between wholesale colocation pivots or stranded legacy assets. Sovereign wealth capital injections now determine competitive tiering more than operational efficiency.
Growth Catalysts
- Liquid cooling systems:Ambient desert temperatures exceeding 45°C during summer peaks are mandating evaporative redesigns and immersion cooling adoption for power-dense GPU clusters.
- SFDA data-sovereignty mandates:Saudi Arabia's pharmaceutical regulator requires local data residency for clinical trials and patient records, creating certified demand for Riyadh and Dammam builds.
- Submarine cable landings:New fiber routes through the Arabian Gulf are reducing latency to European and Asian markets, anchoring Dubai and Abu Dhabi as interconnection hubs.
Market Restraints
- Power grid interconnection delays:Transmission capacity expansion timelines in Saudi Arabia's economic zones lag behind facility commissioning schedules by 18-24 months.
- Desalinated water dependency:Evaporative cooling systems require reliable access to treated water, constraining site selection to coastal corridors with established desalination infrastructure.
- Construction labor concentration:Specialized data center contracting capacity clusters in South Asian markets, exposing build timelines to regional visa and mobility restrictions.
Strategic Opportunities
- Bahrain's cloud-first TRA policies:The telecommunications regulator's streamlined licensing frameworks attract foreign operators seeking Gulf market entry with lower capital barriers than Saudi Arabia or UAE.
- Edge computing for smart city deployments:Saudi Arabia's NEOM and UAE's Masdar City projects require distributed low-latency infrastructure, creating demand for modular micro-facilities outside primary metros.
- Green hydrogen power purchase agreements:UAE's dual-carbon goals are incentivizing renewable energy offtake contracts that improve facility carbon intensity ratings for ESG-sensitive hyperscale tenants.
Industry Challenges
- Certified engineering talent scarcity:Uptime Institute Tier III/IV design accreditation remains concentrated among European and North American professionals, extending commissioning timelines for Gulf greenfield projects.
- Legacy telco facility retrofits:Incumbent operators face stranded asset risk as enterprise customers migrate from single-tenant owned facilities to multi-tenant colocation with modern power usage effectiveness ratios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Data Center Market |
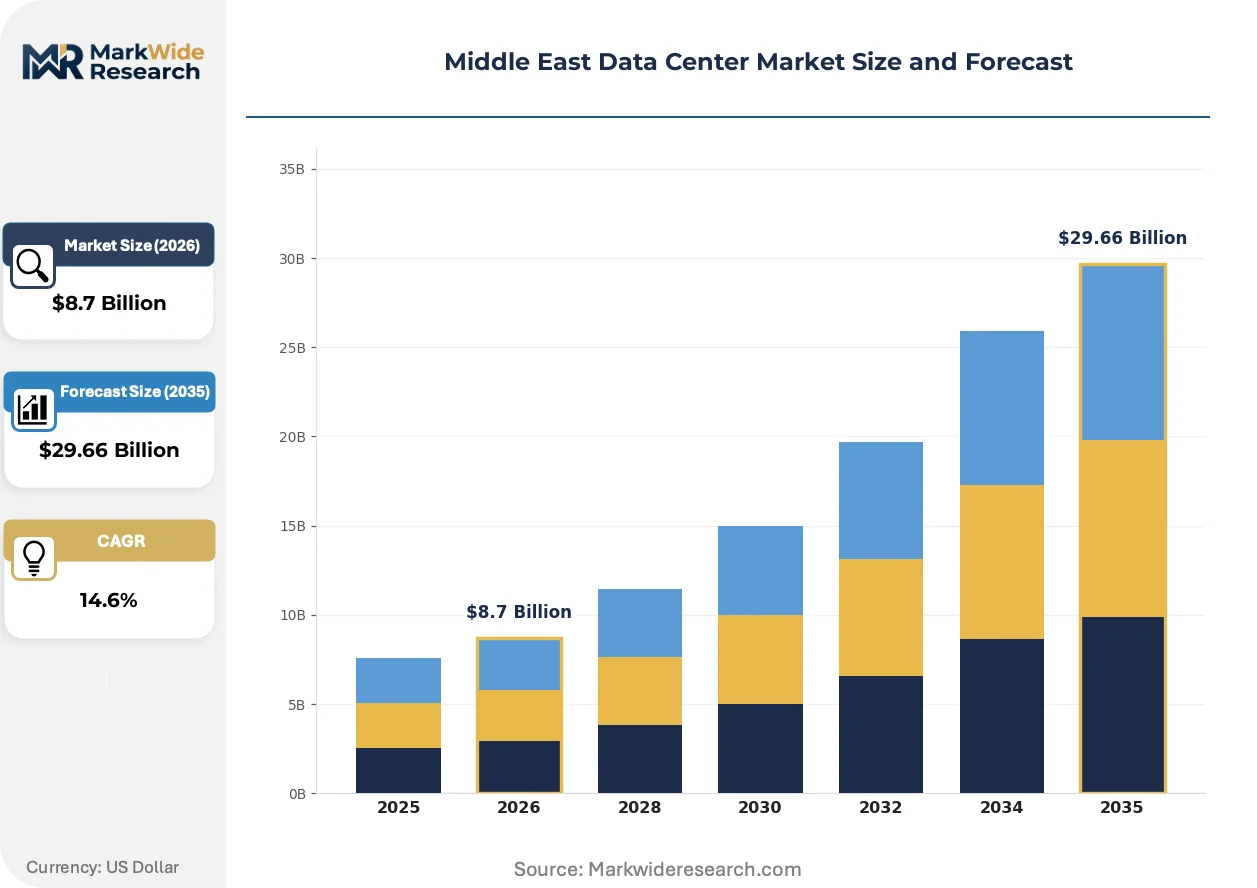
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Containerized, Traditional, Edge Deployment: On-Premise, Colocation, Managed Services, Cloud End User: IT & Telecom, BFSI, Government, Retail Technology: Cooling, Power Management, Networking, Security |
| Companies Covered | Khazna Data Centers, Ooredoo Data Center Services, Etisalat Digital, Zain, Batelco, STC, Moro Hub, Omantel, Gulf Data Hub, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Data Center Market Strategic Shifts
Facility architecture across the Middle East is splitting between hyperscale-ready mega-developments and distributed edge nodes, with cooling technology and power sourcing becoming the primary differentiation vectors.
Immersion cooling for AI training clusters is bifurcating deployment strategies across the Gulf. Oil-submerged server enclosures eliminate airborne particulate contamination while reducing mechanical refrigeration loads. Hyperscale cloud providers are specifying liquid-cooled racks for 100+ kilowatt densities, compressing traditional air-cooled designs into secondary markets. This technology is bifurcating competitive tiers between operators with capital to engineer custom solutions and those dependent on standardized builds.
UAE's dual-carbon regulatory framework is mandating renewable energy percentages for new facility approvals. The policy requires solar or wind power purchase agreements covering minimum operational loads, with compliance verified through third-party carbon accounting. Colocation providers in Dubai and Abu Dhabi are responding by securing 15-20 year offtake contracts with Mohammed bin Rashid Al Maktoum Solar Park developers.
Enterprise procurement patterns are consolidating vendor relationships around integrated design-build-operate contracts. Single-source accountability for mechanical, electrical, and plumbing systems is displacing fragmented general contracting models. Financial services and healthcare verticals in Riyadh and Dubai are driving this consolidation, seeking Uptime Institute certification guarantees backed by performance bonds rather than warranty coverage alone.
Middle East Data Center Market Segmentation
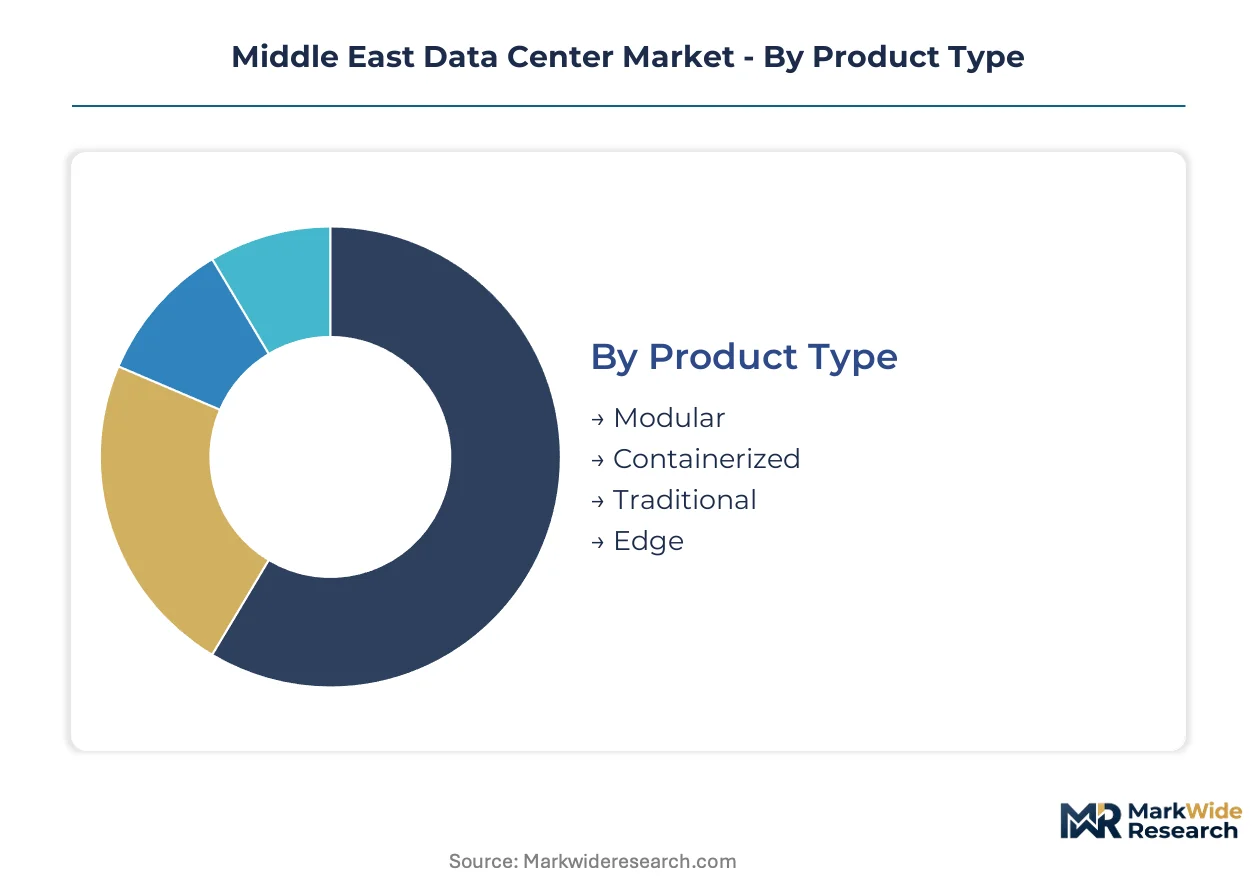
Facility architecture across the Gulf splits between hyperscale-ready mega-developments and distributed edge nodes, with product configuration and deployment structure determining competitive tiering. Segmentation reveals where sovereign wealth capital concentrates and which technology layers face structural pressure from desert climate constraints.
Product Type:
Margin pools concentrate in prefabricated solutions that compress commissioning timelines against power grid interconnection delays.
- Modular:Prefabricated power and cooling modules arrive site-ready, cutting construction schedules from 24 months to under 12 months. Saudi Arabia's economic zones and Dubai's free trade corridors absorb the majority of deployments as hyperscale cloud providers demand rapid capacity scaling.
- Containerized:Standardized 20-foot and 40-foot enclosures house complete IT infrastructure with integrated environmental controls. Edge computing nodes for NEOM and Masdar City smart city deployments favor this format for distributed low-latency positioning.
- Traditional:Stick-built facilities with custom mechanical and electrical systems serve legacy enterprise customers with single-tenant requirements.
- Edge:Micro-facilities under 500kW capacity position compute closer to data sources. Riyadh's financial district and Dubai's healthcare clusters generate concentrated demand for sub-10 millisecond latency.
The dominant share belongs to Modular, while Edge is closing the gap fastest.
Deployment:
Enterprise exit from owned-facility obligations is redistributing margin pools toward multi-tenant colocation with modern power usage effectiveness ratios.
- On-Premise:Single-tenant facilities owned and operated by end-users. SFDA data-sovereignty mandates preserve residual demand among Saudi pharmaceutical firms requiring certified local builds for clinical trial data.
- Colocation:Multi-tenant facilities where operators provide space, power, cooling, and physical security. Khazna Data Centers and Gulf Data Hub capture expanding margin pools as enterprises migrate from capital-intensive owned assets.
- Managed Services:Operators assume responsibility for IT infrastructure management beyond facility provision. Bahrain's cloud-first TRA policies attract foreign operators seeking lower capital barriers through service-based market entry.
- Cloud:Hyperscale cloud provider deployments anchor facility demand across Abu Dhabi, Dubai, and Riyadh. STC leverages captive land and power allocations to sustain geographic dominance in Saudi Arabia's economic zones.
Colocation holds the dominant position, though Cloud is expanding most quickly as hyperscale providers compress design cycles.
End User:
Compliance architecture varies sharply across verticals, with regulated industries commanding premium pricing for certified builds.
- IT & Telecom:Carriers and cloud service providers constitute the foundational demand layer. Submarine cable landing rights in Dubai and Abu Dhabi anchor interconnection hub development for regional traffic exchange.
- BFSI:Banks and insurers drive Uptime Institute Tier III/IV certification requirements. Riyadh's financial district generates concentrated demand for performance-bond-backed availability guarantees.
- Government:Sovereign wealth fund capital flows prioritize digital infrastructure for economic diversification. Saudi CITC licensing frameworks shape market access rules for foreign operators serving public sector contracts.
- Retail:E-commerce platforms and omnichannel operators require distributed capacity for transaction processing. UAE's dual-carbon goals constrain facility design while creating compliance-driven demand for certified local builds.
IT & Telecom claims the dominant share, while Government is gaining share fastest through sovereign capital allocation.
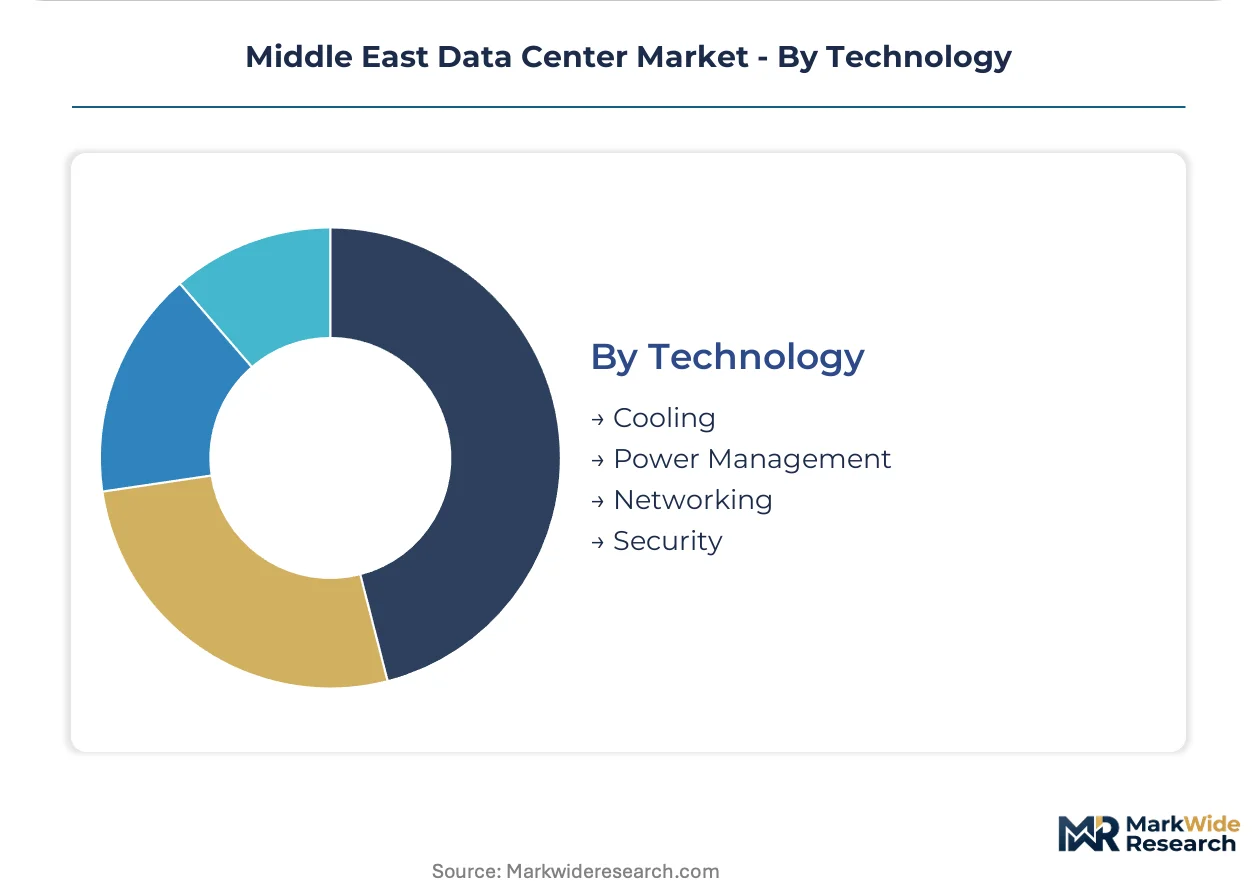
Technology:
Cooling technology faces structural pressure as ambient desert temperatures exceed 45°C during summer peaks, driving liquid-cooling adoption and evaporative system redesigns.
- Cooling:Immersion cooling for AI training clusters eliminates airborne particulate contamination while reducing mechanical refrigeration loads. Oil-submerged server enclosures support 100+ kilowatt rack densities specified by hyperscale cloud providers.
- Power Management:Uninterruptible power supply systems and switchgear configurations determine facility availability ratings. Green hydrogen power purchase agreements improve carbon intensity ratings for ESG-sensitive hyperscale tenants.
- Networking:Cross-connect density and fiber termination capacity differentiate interconnection hubs. New fiber routes through the Arabian Gulf reduce latency to European and Asian markets.
- Security:Physical access controls, biometric authentication, and surveillance systems protect against unauthorized entry. Financial services and healthcare verticals in Riyadh and Dubai drive consolidation around integrated design-build-operate security contracts.
Cooling commands the dominant share, though Power Management is climbing the fastest on renewable energy integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE operators command 15-20% pricing premiums over Saudi peers due to mature submarine cable landing rights and established interconnection density. Saudi Arabia's economic zones attract sovereign capital flows at scale but face power grid interconnection delays that compress facility utilization rates.
Saudi Arabia
SFDA data-sovereignty mandates for pharmaceutical clinical trials and patient records anchor certified facility demand in Riyadh and Dammam. Saudi CITC licensing frameworks impose capital requirements and local partnership rules that shape foreign operator market access. STC leverages captive land and power allocations across King Abdullah Economic City and Dammam's industrial zones to sustain geographic dominance.
United Arab Emirates
Dual-carbon regulatory mandates requiring renewable energy percentages for new facility approvals drive solar power purchase agreements with Mohammed bin Rashid Al Maktoum Solar Park developers. MOHAP healthcare data residency rules complement broader federal compliance architecture. Dubai and Abu Dhabi anchor submarine cable landings that reduce latency to European and Asian markets, cementing interconnection hub status.
Bahrain
The TRA's cloud-first policies attract foreign operators seeking Gulf market entry with streamlined licensing and lower capital barriers than Saudi Arabia or UAE. Financial services and fintech clusters in Manama generate concentrated demand for Uptime Institute Tier III certification. Bahrain's compact geography enables rapid fiber deployment connecting facilities to Saudi Arabia's Eastern Province markets.
Qatar
Ooredoo's integrated telecom-data center operations anchor national capacity expansion aligned with Qatar National Vision 2030 diversification targets. The Qatar Financial Centre regulatory framework imposes data localization requirements for banking and insurance operations. Lusail's smart city infrastructure generates distributed edge computing demand for sub-10 millisecond latency applications.
Oman
Omantel's submarine cable landing investments position Muscat as an emerging interconnection point for traffic between India and Europe. The Special Economic Zone Authority at Duqm offers land and power incentives for hyperscale facility development. Salalah's free zone attracts modular deployments serving East African and South Asian markets through fiber routes.
Middle East Data Center Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Gulf data center market. Sovereign-backed operators with captive land and power allocations compete against privately held specialists with submarine cable landing rights and cross-border fiber density. The competitive structure splits between hyperscale-ready mega-facility developers and distributed edge node operators serving smart city deployments. Dominant competitive moves include sovereign wealth capital injections for capacity expansion and strategic partnerships securing renewable energy offtake contracts.
Within the sovereign-backed tier, Khazna Data Centers and STC exemplify operators leveraging state-linked balance sheets for mega-facility development. Gulf Data Hub occupies a position among connectivity-focused specialists competing through submarine cable landing rights and interconnection density.
| Leading Market Players |
|---|
| Khazna Data Centers |
| Ooredoo Data Center Services |
| Etisalat Digital |
| Zain |
| Batelco |
| STC |
| Moro Hub |
| Omantel |
| Gulf Data Hub |
| Others |
Value Chain & Pricing Dynamics
Mega-facility scale economies in Abu Dhabi and Riyadh compress unit economics for hyperscale-ready builds while fragmenting pricing power among legacy telco operators with stranded single-tenant assets. This divergence anchors a dual-tier structure where sovereign-backed balance sheets sustain sub-market pricing for multi-year anchor tenants while independent operators defend utilization through customization premiums.
Pricing Analysis
The customization-premium spread separates hyperscale commodity colocation from certified enterprise builds. Standard multi-tenant rack pricing in Dubai and Riyadh tracks power density and cross-connect density, while Uptime Institute Tier III certification commands 15-20% premiums for financial services verticals. Price differentiation rests on certification grade and captive renewable energy sourcing. Cost compression in standard colocation tiers is intensifying as Khazna Data Centers and STC deploy sovereign-funded capacity. Government and BFSI segments show lowest price sensitivity due to compliance mandates, while retail and mid-market IT show highest elasticity.
Supply Chain Analysis
Inventory lead times for liquid cooling manifolds and high-density switchgear now stretch 26-32 weeks, constraining facility commissioning schedules against hyperscale demand surges. Manufacturing concentration for precision cooling equipment centers on Germany, Japan, and South Korea, while power distribution components draw from China and the United States. Supply chain risk centers on single-source vulnerability for immersion cooling fluids and specialized electrical switchgear. Distribution runs through EPC contractors with data center vertical expertise, anchored by South Asian construction labor pools exposed to visa mobility restrictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscale cloud providers' direct facility ownership threatens colocation operators' anchor tenant economics, forcing incumbents to defend through certification moats and captive energy sourcing. Substitution pressure from self-build strategies compresses pricing power for standardized capacity.
For Market Incumbents: Compound defensive positioning through Uptime Institute Tier IV certification investments in Riyadh and Dubai financial districts. Lock in 15-20 year renewable energy offtake contracts with Mohammed bin Rashid Al Maktoum Solar Park developers to secure ESG-sensitive hyperscale tenants. Vertical integration into modular manufacturing compresses construction timelines against power grid interconnection delays. For New Entrants and Emerging Players: Certification fast-track through Bahrain's TRA cloud-first licensing frameworks enables Gulf market entry with lower capital barriers than Saudi CITC or UAE dual-carbon compliance. Target edge computing nodes for NEOM and Masdar City smart city deployments with containerized sub-500kW formats. Lead with integrated design-build-operate contracts displacing fragmented general contracting models in financial services verticals. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among colocation operators with hyperscale anchor tenants and renewable energy purchase agreements already contracted. Long-term viability across the projection horizon favors connectivity-focused specialists with submarine cable landing rights and cross-border fiber density. Watch sovereign wealth fund capital allocation shifts toward digital infrastructure as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Offtake Contracting | Dual-carbon compliance in UAE mandates solar power purchase agreements for facility approvals. |
| Liquid Cooling Infrastructure Deployment | Immersion cooling adoption supports 100+ kilowatt rack densities specified by hyperscale cloud providers. |
| Submarine Cable Landing Rights Acquisition | Fiber connectivity through Arabian Gulf routes anchors Dubai and Abu Dhabi interconnection hub status. |
| Modular Manufacturing Integration | Prefabricated power and cooling modules compress construction schedules from 24 months to under 12 months. |
| Tier III/IV Certification Investment | Uptime Institute accreditation extends commissioning timelines but commands premium pricing from BFSI verticals. |
Study Parameters
Cross-validation between hyperscaler capex disclosures and sovereign wealth fund investment filings anchors the qualitative findings on facility demand trajectories. Primary interviews with data center development executives, EPC contractors, CITC licensing officers, and enterprise IT procurement leads combined with secondary validation through SEC filings, customs records for cooling equipment imports, and renewable energy offtake contract registries. Bottom-up facility-by-facility capacity builds and top-down cloud provider demand forecasts triangulate market sizing.
Sensitivity analysis across power grid interconnection timelines, hyperscale self-build probabilities, and renewable energy compliance thresholds shapes the projection horizon. Segmentation dimensions modeled include product configuration, deployment structure, end-use vertical, cooling technology tier, and regional regulatory cluster. CAGRs derive from facility commissioning schedules, utilization rate assumptions, and pricing trajectory modeling. Key inputs include ambient temperature cooling load calculations and submarine cable capacity expansion timelines.
Underlying assumptions cover sovereign capital commitment continuity, hyperscale demand persistence, and power infrastructure delivery schedules, with deviation risk concentrated in construction labor mobility restrictions and desalinated water supply reliability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Global Data Center Rack and Enclosure Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Denmark Data Center Physical Security Market
Data Center Infrastructure
Dedicated Server Hosting Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Virtual Infrastructure Manager Market
Data Center Infrastructure
Indonesia Data Center Construction Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
South America Data Center Power Market