
 Australia Data Center Construction Market | 2026-2036
Australia Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Data Center Construction Market Insights
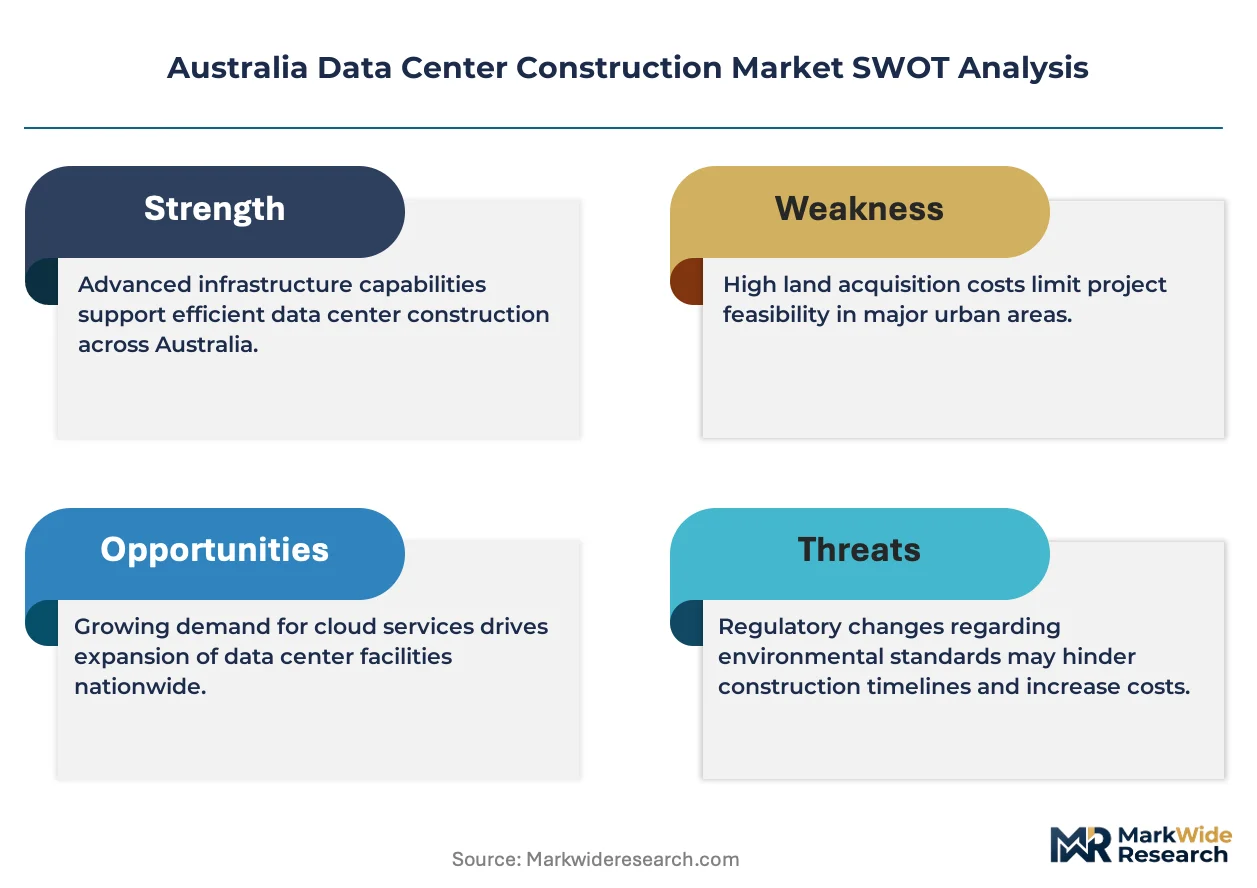
Australia's mandatory climate risk disclosure regime for large entities is broadening the specifications for new data center builds. NEXTDC Ltd leverages its portfolio of certified carbon-neutral facilities to anchor premium pricing in Sydney and Melbourne. AirTrunk Operating Pty Ltd sustains engineering intensity through proprietary cooling designs purpose-built for Australian thermal conditions. CPB Contractors Pty Ltd dominates civil and structural packages for hyperscale campuses, competing on delivery speed against tight power grid connection timelines.
Australia data center construction encompasses the design, engineering, and physical build-out of facilities housing compute, storage, and networking infrastructure, typically requiring power densities exceeding 20 kW per rack and precision cooling within 1.5 degrees Celsius tolerance to maintain server uptime. The primary purpose is to create controlled environments that protect digital assets while enabling scalable expansion for cloud, enterprise, and sovereign workloads. Hyperscale facilities command the largest capital allocation as global cloud operators commit to multi-hundred-megawatt campuses, while edge deployments represent the fastest-growing construction phase due to latency-sensitive applications in healthcare and autonomous systems. Cooling systems technology attracts disproportionate engineering focus because ambient temperatures across Australian sites strain conventional designs and drive liquid cooling adoption.
TGA guidelines on data residency for health records intersect with ASIC prudential standards for financial institutions, creating dual compliance layers that shape facility location and security architecture decisions. The Australian Energy Market Operator's grid reliability assessments directly influence where developers can secure firm power, filtering viable sites and extending project timelines where transmission upgrades lag. State planning authorities in New South Wales and Victoria administer separate environmental and noise regulations that add procedural variance across jurisdictions. Stakeholders must monitor whether proposed reforms to the Environmental Protection and Biodiversity Conservation Act streamline or complicate approvals for campuses near ecologically sensitive zones.
Market Dynamics
Hyperscale cloud operators are compressing project timelines to secure finite transmission capacity, forcing engineering firms to sequence civil, mechanical, and electrical work in parallel rather than phases. This concurrency is straining contractor bandwidth and amplifying cost volatility across the build cycle.
Growth Catalysts
- Critical Infrastructure Protection Act:Federal designation accelerates security clearance timelines for facility staff, reducing deployment delays for sovereign cloud workloads.
- Western Sydney power zone:Ausgrid transmission upgrades unlock 500+ MW of firm capacity, concentrating hyperscale investment in this corridor.
- Liquid cooling adoption:Direct-to-chip systems enable 50 kW+ rack densities, allowing operators to maximize land-constrained sites in Melbourne's west.
Market Restraints
- Copper and aluminum price volatility:Busbar and cabling costs swing 15-30% on commodity markets, eroding fixed-price contract margins.
- Specialized MEP contractor concentration:Three firms control 70% of hyperscale mechanical-electrical packages in New South Wales, creating bottleneck risk.
- Grid connection queue delays:AEMO interconnection studies extend 18-24 months where transmission reinforcement is required.
Strategic Opportunities
- Brisbane-Ipswich corridor:Queensland's cheaper land and power costs attract secondary campus development as Sydney and Melbourne saturate.
- ASIC prudential standard CPS 234:Mandated operational resilience audits drive demand for Tier III+ certified facilities with redundant substations.
- Modular prefabrication:Factory-built power modules and cooling skids compress on-site construction windows by 40%.
Industry Challenges
- High-voltage electrical trades shortage:Licensed 11 kV+ technicians command 35% wage premiums, stretching project labor budgets.
- EPBC Act biodiversity offsets:Campus sites near Cumberland Plain woodland trigger 12-18 month ecological assessment delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Data Center Construction Market |
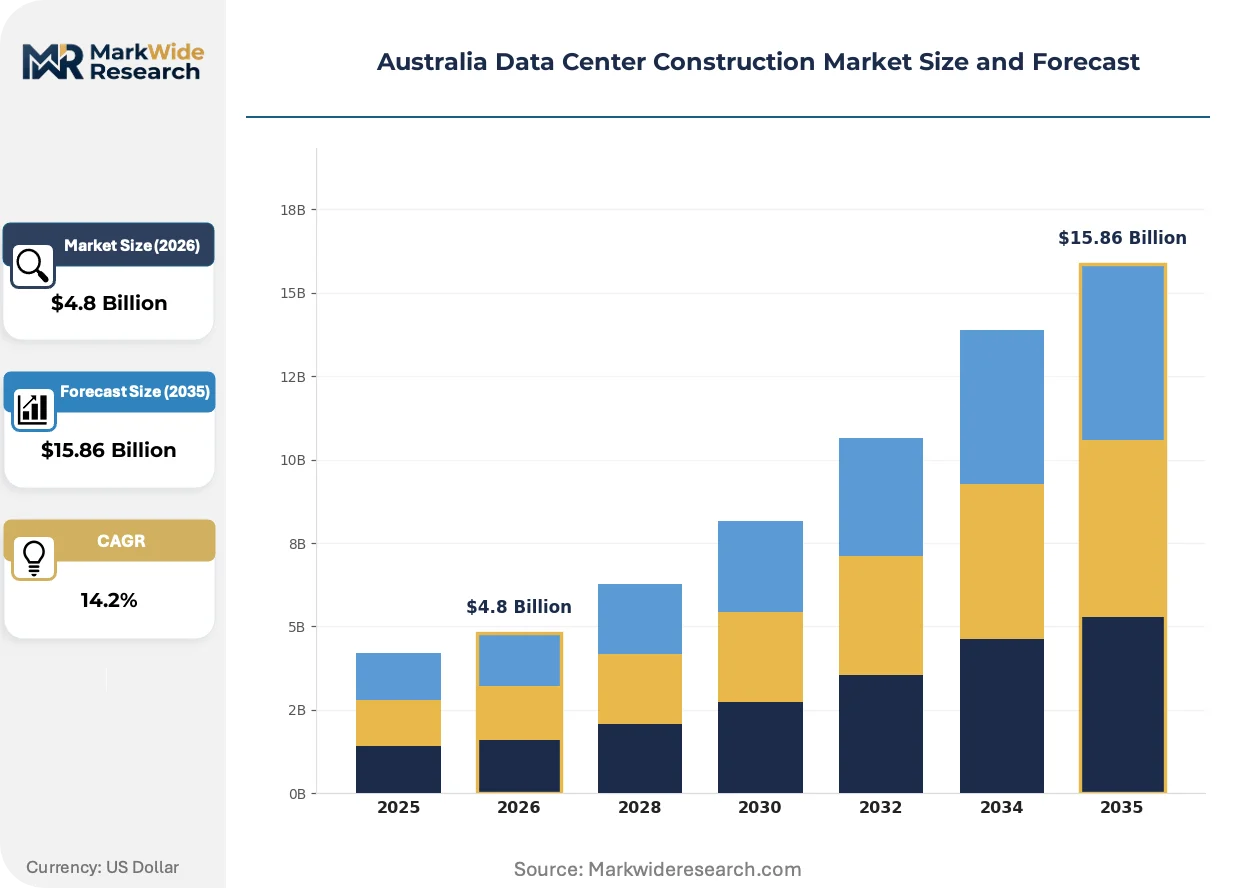
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Colocation, Hyperscale, Edge, Enterprise Technology: Cooling Systems, Power Infrastructure, Networking Equipment, Security Solutions End User: IT Services, Telecom Operators, Government Agencies, Financial Institutions Construction Phase: Planning, Design, Construction, Commissioning |
| Companies Covered | NEXTDC Ltd, AirTrunk Operating Pty Ltd, FDC Construction and Fitout, Multiplex Constructions Pty Ltd, CPB Contractors Pty Ltd, Icon Co, Aurecon Group, Macquarie Telecom Group, John Holland Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Data Center Construction Market Trends and Innovations
Engineering practices are pivoting from conventional build-to-spec toward integrated design-build-operate models that compress handoff friction. This shift reflects hyperscale buyers' demand for single-accountability delivery and faster revenue-ready commissioning.
Immersion cooling is expanding into Australian hyperscale campuses as operators confront 40°C ambient design conditions. Microsoft and Amazon Web Services are piloting dielectric fluid systems in Western Sydney facilities. This technology is expanding into standard specifications for new builds, enabling 100 kW rack densities without mechanical refrigeration.
TGA data residency requirements for electronic health records are mandating onshore primary storage with cryptographic segregation. Healthcare cloud providers must construct dedicated halls with biometric access controls and air-gapped backup systems. This policy is reshaping facility security architecture across Victoria and New South Wales, with operators adding 15-20% capex for compliance-grade hardening.
Enterprise procurement patterns are fragmenting as mid-market buyers reject long-term colocation leases in favor of capacity reservations with monthly flexibility. This behavior is pressuring operators to modularize hall construction into 2-4 MW deployable units. The shift is most visible in Melbourne, where NEXTDC and Equinix are reconfiguring expansion phasing to match consumption-based contracting.
Australia Data Center Construction Market Segmentation
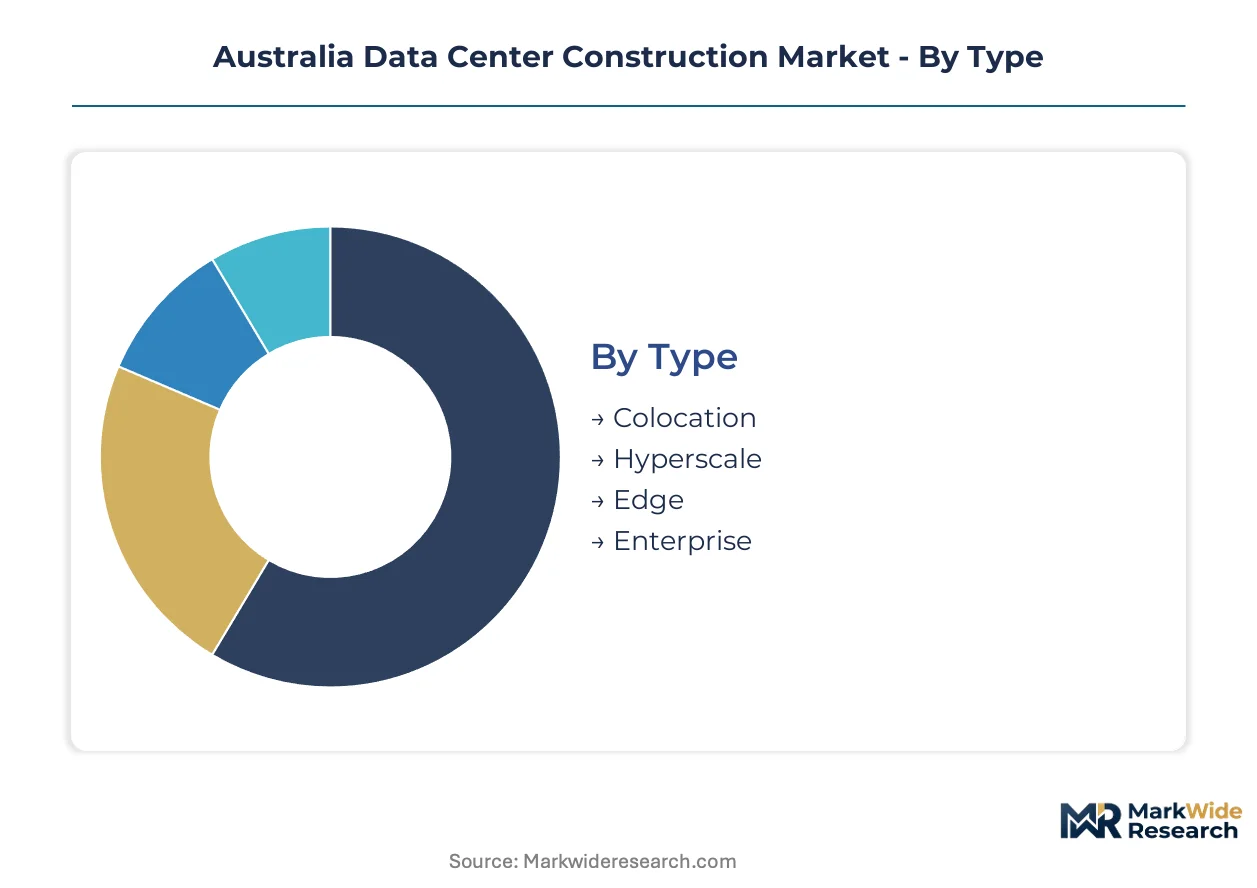
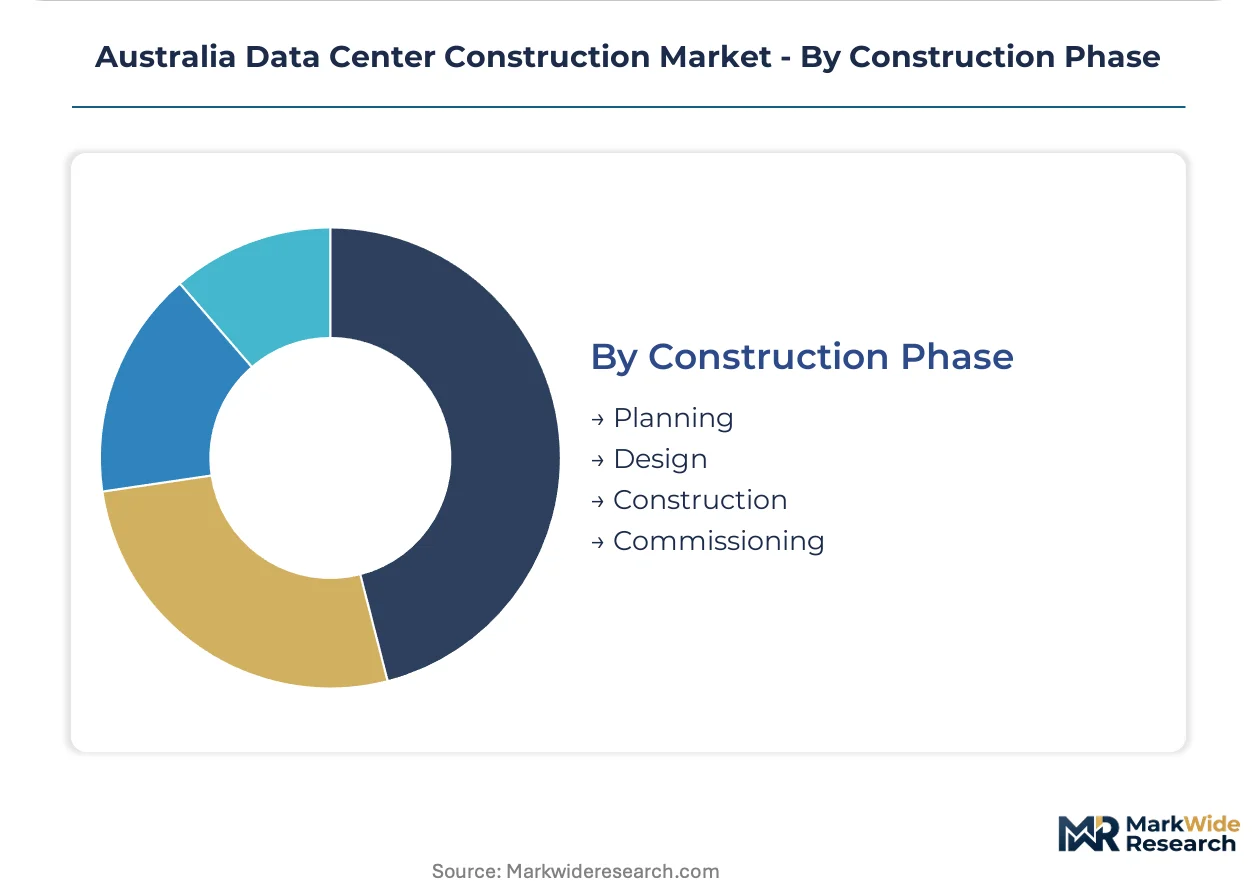
Facility type determines capital intensity and contractor specialization, while construction phase sequencing dictates cash flow timing and risk allocation for Australian developers navigating transmission-constrained sites.
Type:
Buyers select facility scale based on workload sovereignty requirements and power procurement flexibility.
- Hyperscale:Multi-hundred-megawatt campuses with 50+ kW rack densities dominate engineering resource allocation. Western Sydney and Melbourne's west concentrate investment as cloud operators secure firm grid capacity ahead of competitors.
- Colocation:Multi-tenant halls with standardized 10-20 kW racks attract enterprise buyers seeking operational flexibility without capital commitment. NEXTDC and Equinix anchor premium pricing through Tier III+ certification in Sydney and Melbourne.
- Edge:Distributed 1-5 MW facilities address latency-sensitive healthcare and autonomous vehicle workloads. Queensland's Brisbane-Ipswich corridor captures secondary deployment as primary markets saturate.
- Enterprise:Single-occupant builds for banking and government clients emphasize biometric access and air-gapped backup systems. ASIC prudential standards mandate redundant substations, elevating electrical package costs.
Volume sits with Hyperscale; growth tilts toward Edge.
Technology:
Specification choices hinge on ambient thermal conditions and land constraints rather than capital cost minimization.
- Cooling Systems:Direct-to-chip liquid cooling enables 100 kW rack densities without mechanical refrigeration. Microsoft and Amazon Web Services pilot dielectric fluid systems in Western Sydney facilities facing 40°C design conditions.
- Power Infrastructure:High-voltage switchgear and modular UPS systems absorb 35-40% of construction budgets. Copper and aluminum price volatility swings busbar costs 15-30%, eroding fixed-price contract margins.
- Networking Equipment:Structured cabling and fiber termination support 400G+ interconnects between compute halls. Dense fiber counts complicate overhead routing in multi-story Melbourne builds.
- Security Solutions:Biometric access controls and perimeter hardening satisfy Critical Infrastructure Protection Act requirements. TGA data residency mandates drive cryptographic segregation for healthcare workloads.
Capital concentrates in Power Infrastructure; engineering innovation clusters in Cooling Systems.
End User:
Compliance regimes and latency tolerance filter facility selection across buyer categories.
- IT Services:Cloud and managed service providers drive modular hall construction in 2-4 MW deployable units. Monthly capacity reservations replace long-term leases, pressuring phasing flexibility.
- Telecom Operators:5G core and edge computing integration demands distributed low-latency infrastructure. Telstra and Optus prioritize Queensland sites for cost-advantaged expansion.
- Government Agencies:Sovereign cloud mandates under the Critical Infrastructure Protection Act accelerate security clearance timelines. Federal buyers require staff vetting that constrains contractor pools.
- Financial Institutions:ASIC CPS 234 operational resilience audits mandate Tier III+ certification with redundant substations. Major banks concentrate in Sydney and Melbourne for interconnection density.
Procurement volume favors IT Services; compliance complexity peaks with Government Agencies.
Construction Phase:
Timeline compression for grid connection windows reshapes risk allocation between phases.
- Construction:Civil, mechanical, and electrical work proceeds in parallel rather than sequence to accelerate commissioning. Contractor bandwidth constraints amplify cost volatility across hyperscale builds.
- Planning:Site selection filters against AEMO grid reliability assessments and state planning authority noise regulations. EPBC Act biodiversity offsets near Cumberland Plain woodland trigger 12-18 month delays.
- Design:Integrated design-build-operate models replace conventional build-to-spec handoffs. Single-accountability delivery reduces friction between engineering and operations teams.
- Commissioning:Factory-built power modules and cooling skids compress on-site validation windows by 40%. Modular prefabrication shifts quality control to manufacturing environments.
Duration risk concentrates in Planning; margin pressure intensifies through Construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction capacity concentrates in New South Wales and Victoria, where hyperscale operators secure firm grid connections ahead of Queensland and Western Australia. Consumption growth now outpaces build velocity, compressing timelines and amplifying contractor scarcity.
New South Wales
Western Sydney's power zone absorbs the bulk of hyperscale investment as Ausgrid transmission upgrades unlock 500+ MW of firm capacity. The state's planning authority administers noise and environmental regulations that add procedural variance. Facilities cluster in the Western Sydney corridor where NEXTDC and AirTrunk anchor multi-hundred-megawatt campuses.
Victoria
Melbourne's west attracts engineering intensity through land-constrained sites requiring liquid cooling for 50 kW+ rack densities. The Victorian planning framework intersects with ASIC prudential standards for financial institutions, shaping security architecture decisions. Edge deployments accelerate in metropolitan Melbourne for latency-sensitive healthcare workloads under TGA data residency mandates.
Queensland
Brisbane-Ipswich corridor captures secondary campus development as Sydney and Melbourne saturate, drawn by cheaper land and power costs. The state's grid reliability assessments filter viable sites less restrictively than southern jurisdictions. Telstra and Optus prioritize Queensland sites for cost-advantaged 5G core and edge computing expansion.
Western Australia
Perth's isolation creates sovereign cloud demand from resource sector clients requiring data residency without eastern seabed latency penalties. The Australian Energy Market Operator's interconnection studies extend timelines where transmission reinforcement lags. Limited contractor bandwidth concentrates on smaller-scale enterprise builds rather than hyperscale campuses.
South Australia
Adelaide's renewable energy surplus attracts pilot facilities testing off-grid designs, though scale remains constrained by interconnection queues. The state's planning reforms streamline approvals compared to New South Wales and Victoria. Defense and government agencies anchor demand through Critical Infrastructure Protection Act security clearance requirements.
Australia Data Center Construction Market Competitive Landscape
The competitive structure tilts toward integrated design-build-operate specialists capable of compressing handoff friction. Tier-one contractors dominate hyperscale civil and structural packages, while mid-tier specialists capture modular edge deployments. Two strategic archetypes predominate: vertically integrated facility operators with captive construction management, and pure-play engineering firms competing on delivery speed. M&A activity concentrates on MEP contractor acquisitions to secure scarce high-voltage electrical trades, and strategic partnerships between developers and power module fabricators to accelerate commissioning windows.
Among Australia-based specialists, NEXTDC Ltd exemplifies the premium-tier operator archetype through certified carbon-neutral facility portfolios, while AirTrunk Operating Pty Ltd anchors the hyperscale engineering intensity segment with proprietary cooling designs. CPB Contractors Pty Ltd occupies the dominant civil-contractor position for multi-hundred-megawatt campuses. These three entities represent the structural concentration of engineering and contracting resources across the market's highest-capital segments.
| Leading Market Players |
|---|
| NEXTDC Ltd |
| AirTrunk Operating Pty Ltd |
| FDC Construction and Fitout |
| Multiplex Constructions Pty Ltd |
| CPB Contractors Pty Ltd |
| Icon Co |
| Aurecon Group |
| Macquarie Telecom Group |
| John Holland Pty Ltd |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud operators anchor procurement volume and compress contractor margins through fixed-price competition for multi-hundred-megawatt campuses. Their procurement concentration enforces project-based pricing with penalty clauses for grid connection delays, shifting risk downstream to engineering firms.
Pricing Analysis
Margin tightening in mechanical-electrical packages reflects copper and aluminum commodity swings that erode fixed-contract profitability. Three-tier pricing structure across Tier III+ certified, standard Tier II, and uncertified economy facilities separates premium operators like NEXTDC from mid-tier colocation providers. Cost-down pressure on civil and structural work accelerates because hyperscale buyers demand parallel-phase construction to secure finite transmission capacity. Enterprise buyers with ASIC compliance mandates show lowest price sensitivity, while mid-market IT services firms drive hardest negotiation on monthly capacity reservations.
Supply Chain Analysis
Tier III+ certification gates access to hyperscale mechanical-electrical packages, filtering contractor pools to three dominant New South Wales specialists. High-voltage switchgear and modular UPS systems draw from manufacturing concentrated in Germany, China, and the United States. Busbar and cabling inputs rest on copper and aluminum extraction anchored in Chile, Australia, and Indonesia. Single-source vulnerability concentrates in specialized 11 kV+ electrical trades where licensed technicians command wage premiums. Distribution runs through direct developer-contractor relationships with minimal intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia data center construction market operates as a vertical-integration race where captive engineering capability determines who secures finite grid connection windows. Players are pursuing backward integration into modular power module fabrication to compress commissioning timelines.
For Market Incumbents: Deepen captive construction management capability to maintain delivery speed against tightening contractor bandwidth. Secure long-term offtake agreements with high-voltage electrical trades to lock in labor access before wage premiums escalate further. Defend against emerging modular prefabrication specialists by integrating factory-built cooling skid partnerships into standard design-build-operate contracts.
For New Entrants and Emerging Players: The price-point gap between premium Tier III+ certified facilities and uncertified economy builds creates entry space for mid-tier specialists. Target Queensland's Brisbane-Ipswich corridor where cheaper land and power costs reduce capital barriers relative to saturated Sydney and Melbourne markets. Pursue ASIC CPS 234 operational resilience audits as a go-to-market angle to capture financial institution demand for redundant substation architecture.
For Investors and Strategic Acquirers: The window for entry favors MEP contractors with proven hyperscale delivery track records and established high-voltage technician relationships. Long-term viability hinges on exposure to liquid cooling technology transitions as rack densities exceed 50 kW under Australian thermal conditions. Watch for AEMO transmission upgrade announcements as the signal indicating which corridors will unlock firm capacity and concentrate investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Module Fabrication | Factory-built modular UPS and switchgear compress on-site commissioning windows by shifting quality control to manufacturing environments. |
| Liquid Cooling Technology Licensing | Dielectric fluid system partnerships with Microsoft and Amazon Web Services validate designs for 100 kW rack densities in 40°C ambient conditions. |
| High-Voltage Electrical Trades Acquisition | Captive 11 kV+ technician pools secure labor access before wage premiums stretch project budgets beyond fixed-price contract margins. |
| Queensland Corridor Development | Brisbane-Ipswich sites capture secondary hyperscale investment as Ausgrid transmission constraints saturate Western Sydney capacity. |
| ASIC CPS 234 Certification Investment | Tier III+ redundant substation architecture commands premium pricing from major banks concentrated in Sydney and Melbourne. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with data center development executives, EPC contractors, high-voltage electrical trades supervisors, and state planning authority officers combined with AEMO grid reliability assessments, Ausgrid transmission upgrade disclosures, and ASIC prudential standard documentation. Bottom-up project pipeline tracking and top-down construction spend estimates were triangulated to validate market sizing.
Segmentation granularity modeled facility type, construction phase, cooling technology specification, and end-user compliance regime across the projection horizon. CAGRs derived from project-level capital expenditure tracking and contractor capacity utilization rates. Forecast inputs incorporated AEMO interconnection study timelines, EPBC Act biodiversity offset procedural variance, and copper futures price trajectory assumptions.
Underlying measurement precision varies by segment; hyperscale facility tracking carries tighter precision than distributed edge deployments where project disclosure is fragmented. Forecasts reflect assumptions on transmission upgrade completion schedules and state planning reform implementation. A model refresh is warranted upon material change in AEMO grid reliability assessments or Critical Infrastructure Protection Act security clearance timeline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
Austria Data Center Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market
Data Center Infrastructure
Asia-Pacific Data Center Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market