
 Japan E-Commerce Logistics Market | 2026-2036
Japan E-Commerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan E-Commerce Logistics Market Insights
Japan's Work Style Reform Act is decoupling labor-intensive last-mile operations from traditional cost structures, forcing carriers to automate or absorb wage inflation. Yamato Holdings leverages its TA-Q-BIN network density to sustain next-day coverage across all 47 prefectures. Sagawa Express anchors its competitiveness in B2B contract logistics, while Rakuten Logistics differentiates through integration with the Rakuten Ichiba ecosystem.
Japan e-commerce logistics encompasses the physical movement, storage, and fulfillment of goods ordered through digital channels, typically requiring temperature-controlled vehicles for fresh categories and automated sortation hubs processing over 100,000 parcels hourly. Its primary purpose is bridging the gap between online transaction completion and physical product delivery within contracted time windows. Last-mile delivery dominates value capture due to labor scarcity and urban density constraints, while fulfillment services represent the fastest-expanding segment as merchants outsource inventory management. Automated sorting technology leads capital deployment, though IoT solutions are gaining traction for real-time parcel tracking and predictive exception management.
METI enforces logistics efficiency standards under the Act on Rationalization of Energy Use, directly shaping warehouse automation investment timelines and vehicle fleet electrification requirements. JIS standards for packaging recyclability and the country's national pharmaceutical regulator's cold-chain mandates constrain operational design for health and beauty e-commerce. Stakeholders must monitor whether labor-saving robotics deployment outpaces regulatory adaptation, or whether compliance lag opens margin pressure for carriers caught between wage floors and delivery speed guarantees.
Market Dynamics
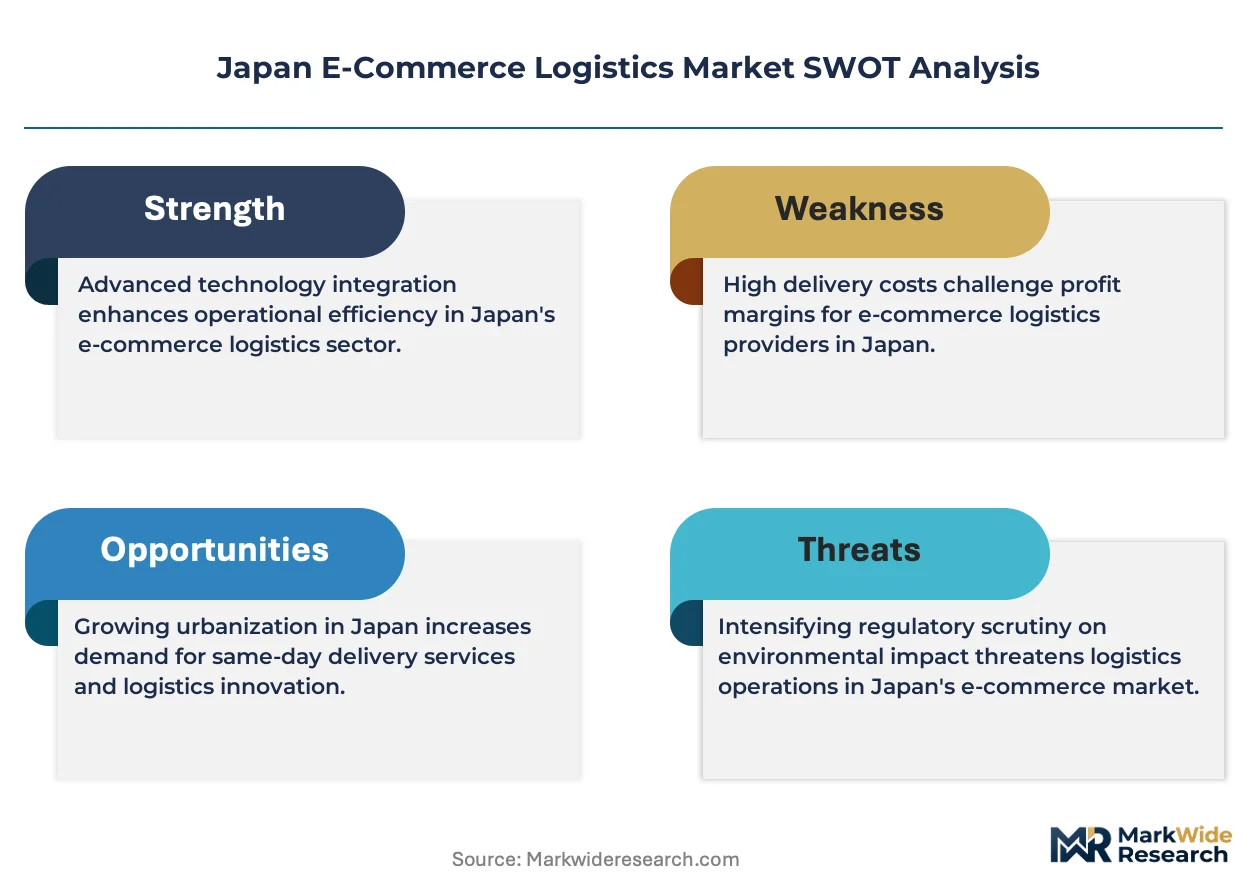
Japan's Work Style Reform Act is compressing delivery windows while simultaneously constraining labor availability, forcing carriers to reengineer fulfillment networks around automation density rather than workforce scale.
Growth Catalysts
- Urban household demand:Grocery and fresh food delivery adoption accelerates in metropolitan zones, requiring temperature-controlled vehicle deployment and micro-fulfillment node expansion.
- METI efficiency mandates:The Act on Rationalization of Energy Use compels warehouse automation investment and fleet electrification timelines, accelerating capital deployment in sortation robotics.
- Platform ecosystem integration:Marketplace operators embed logistics as a native service layer, capturing fulfillment spend previously fragmented across third-party carriers.
Market Restraints
- Labor cost compression:Wage floor escalation under work-style reforms directly inflates per-parcel delivery costs without commensurate productivity gains.
- Greater Tokyo demand concentration:Overreliance on a single metropolitan corridor creates capacity bottlenecks and service degradation risk during peak periods.
- Cold-chain infrastructure gaps:PMDA pharmaceutical distribution standards exceed available certified warehouse capacity, constraining health and beauty e-commerce expansion.
Strategic Opportunities
- Prefecture-tier penetration:Same-day service coverage remains underdeveloped in secondary cities across Hokkaido, Shikoku, and Kyushu, presenting whitespace for hub-and-spoke network extension.
- IoT-5G convergence:Real-time parcel tracking and predictive exception management systems enable dynamic route optimization and customer self-service resolution.
- JIS packaging recyclability standards:Compliance-driven redesign creates differentiation for carriers offering circular-economy fulfillment solutions to sustainability-focused merchants.
Industry Challenges
- Robotics deployment lag:Regulatory adaptation timelines for autonomous vehicle street operation and unmanned warehouse equipment trail technology readiness, delaying labor substitution.
- Legacy system integration:Merchant ERP-to-carrier TMS connectivity requires expensive middleware development, particularly for small and mid-size e-commerce sellers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan E-Commerce Logistics Market |
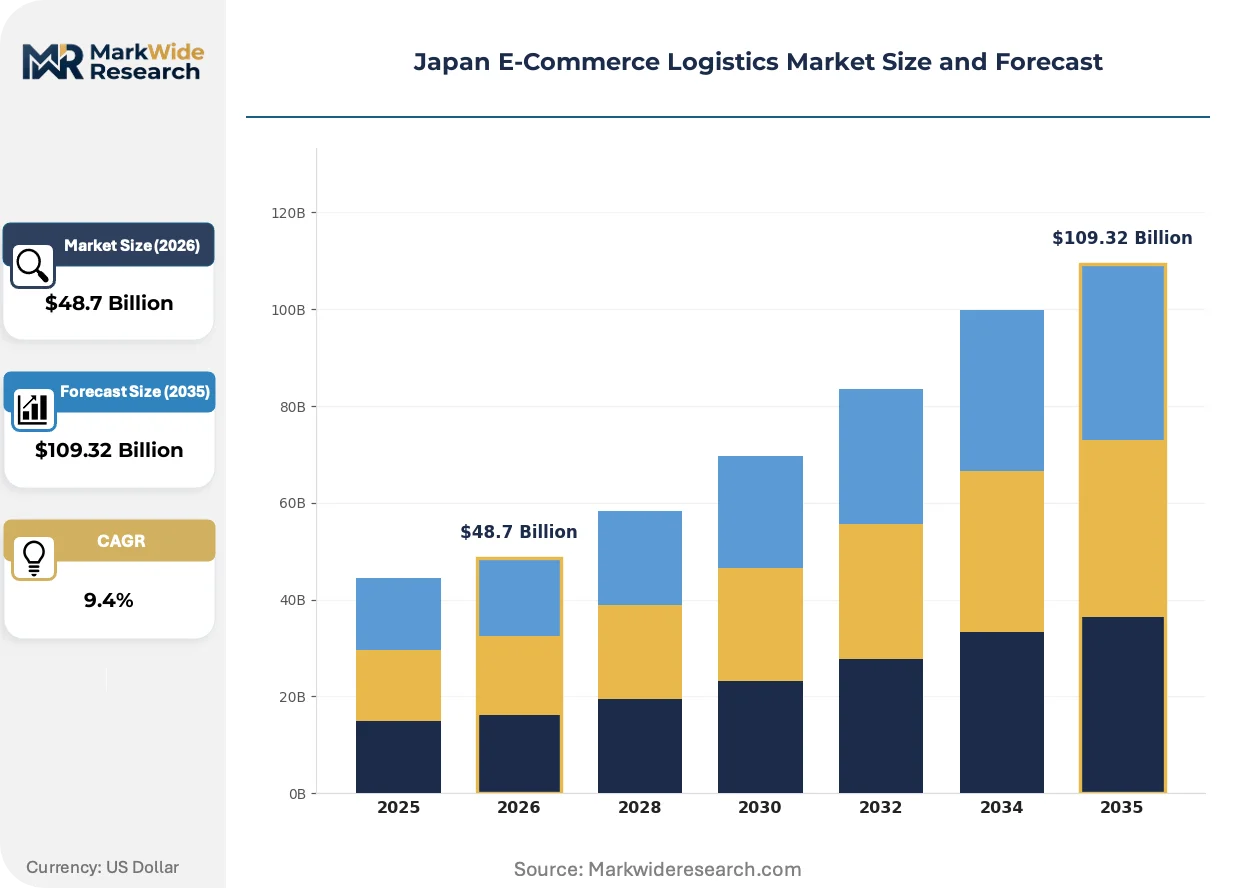
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $109.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Last-Mile Delivery, Warehousing, Fulfillment Services, Returns Management Technology: Automated Sorting, Blockchain, IoT Solutions, Robotics End User: B2C, B2B, C2C, Online Marketplaces Packing Type: Standard Packaging, Custom Packaging, Eco-Friendly Packaging, Durable Packaging |
| Companies Covered | Yamato Holdings, Sagawa Express, Japan Post Holdings, Rakuten Logistics, Seino Holdings, Nippon Express, Amazon Japan, SG Holdings, FedEx Express Japan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan E-Commerce Logistics Market Trends and Innovations
Automation is displacing labor-intensive sortation and delivery processes while regulatory pressure and shifting consumer expectations compress service-level agreements across the fulfillment chain.
Autonomous mobile robots are electrifying warehouse floor operations by automating pick-and-pack workflows in high-throughput facilities. Major e-commerce fulfillment centers deploy AMR fleets to offset labor scarcity under Work Style Reform constraints. This technology is electrifying throughput capacity per square meter while reducing dependency on seasonal workforce scaling.
METI's enforcement of logistics efficiency standards under the Act on Rationalization of Energy Use mandates warehouse automation investment timelines and vehicle fleet electrification requirements. Cold-chain operators face accelerated compliance deadlines for refrigeration emissions reduction. Pharmaceutical and fresh food segments absorb the steepest compliance costs as PMDA cold-chain mandates intersect with energy efficiency rules.
Subscription-based replenishment models are consolidating purchase frequency into predictable delivery patterns, enabling carriers to optimize route density and reduce failed delivery attempts. Urban households increasingly favor scheduled delivery slots over on-demand flexibility. This behavioral shift concentrates demand visibility in the Greater Tokyo Area, where carriers can pre-position inventory closer to consumption nodes.
Japan E-Commerce Logistics Market Segmentation
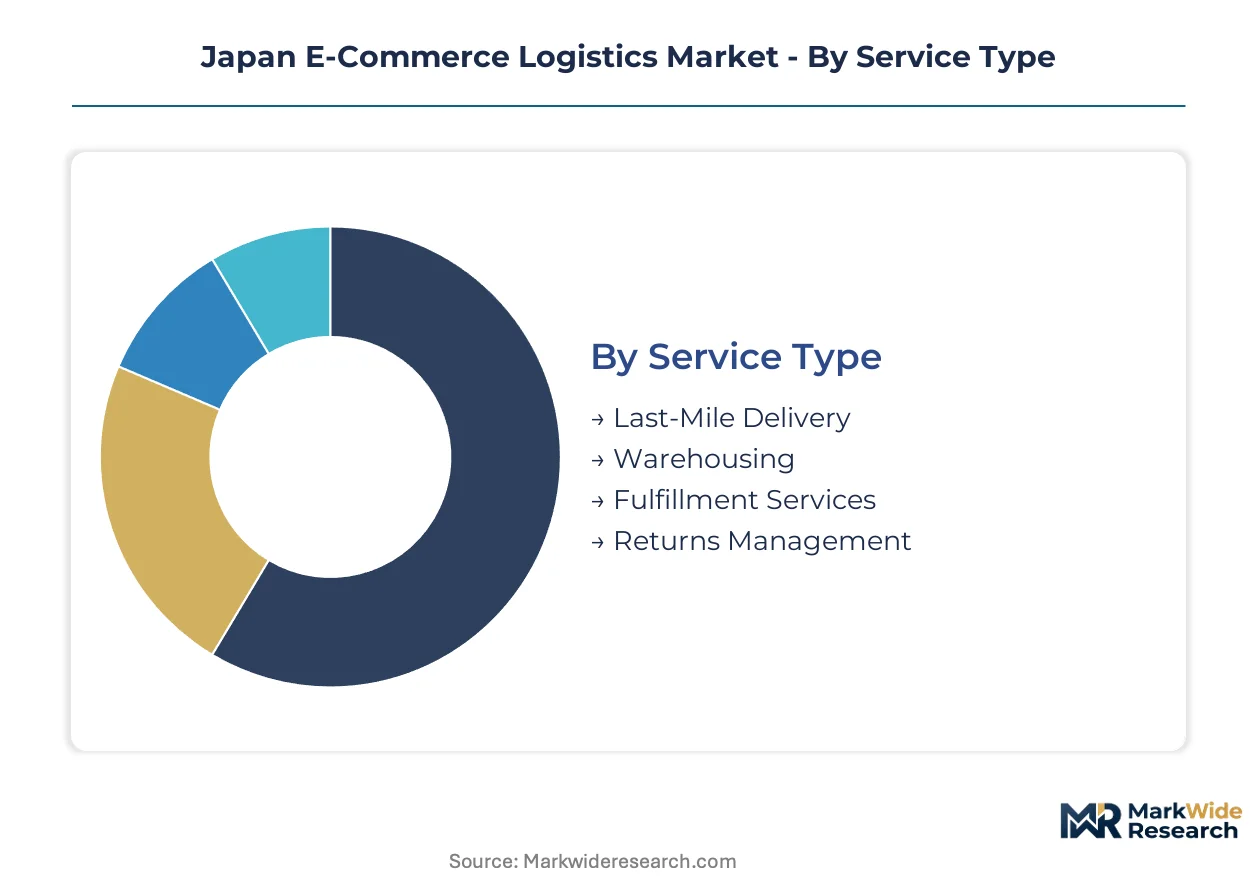
Service differentiation across Japan's e-commerce logistics sector reflects divergent automation investments and labor substitution strategies. Each segment category maps to distinct capital deployment cycles and regulatory compliance burdens under METI efficiency mandates.
Service Type:
Replacement of legacy point-to-point networks with hub-and-spoke automation drives upgrade decisions across carrier portfolios.
- Last-Mile Delivery:Temperature-controlled vehicle fleets and dynamic route optimization systems address compressed delivery windows under Work Style Reform constraints. Greater Tokyo demand concentration forces carriers to pre-position inventory in micro-fulfillment nodes.
- Fulfillment Services:Third-party inventory management absorbs merchant warehousing capex, with automated pick-and-pack workflows offsetting labor scarcity. Subscription replenishment models concentrate demand visibility for route density optimization.
- Warehousing:Multi-tenant facilities deploy AMR fleets for throughput scaling without seasonal workforce expansion.
- Returns Management:Reverse logistics networks integrate inspection and refurbishment workflows for marketplace sellers.
Last-Mile Delivery sits at the top of the volume ranking, with Fulfillment Services climbing the fastest.
Technology:
Cost tier separation between mature automation and emerging digital infrastructure shapes procurement patterns.
- Automated Sorting:High-throughput hubs process parcel volumes exceeding 100,000 units hourly using cross-belt sorters and tilt-tray systems. METI energy efficiency mandates accelerate capital deployment timelines for electrified sortation equipment.
- Robotics:Autonomous mobile robots automate warehouse floor operations under labor availability constraints. Major fulfillment centers deploy AMR fleets to maintain throughput per square meter without workforce scaling.
- IoT Solutions:Real-time parcel tracking and predictive exception management enable dynamic route optimization.
- Blockchain:Distributed ledger applications address pharmaceutical cold-chain provenance requirements under PMDA standards.
Automated Sorting commands the largest installed base, while IoT Solutions gain share fastest through 5G network rollout.
End User:
Customer type determines service-level agreement structures and inventory positioning strategies.
- B2C:Direct-to-consumer fulfillment requires scheduled delivery slot optimization and failed delivery reduction. Urban household grocery adoption drives temperature-controlled last-mile infrastructure investment.
- Online Marketplaces:Platform-native logistics layers capture fulfillment spend previously fragmented across third-party carriers. Rakuten Ichiba integration demonstrates ecosystem-embedded service differentiation.
- B2B:Contract logistics anchors carrier competitiveness in enterprise replenishment and spare parts distribution.
- C2C:Peer-to-peer parcel networks leverage existing carrier density for occasional shipper access.
B2C dominates transaction volume, with Online Marketplaces expanding most quickly through platform consolidation.
Packing Type:
JIS recyclability standards and merchant sustainability commitments reshape material specification decisions.
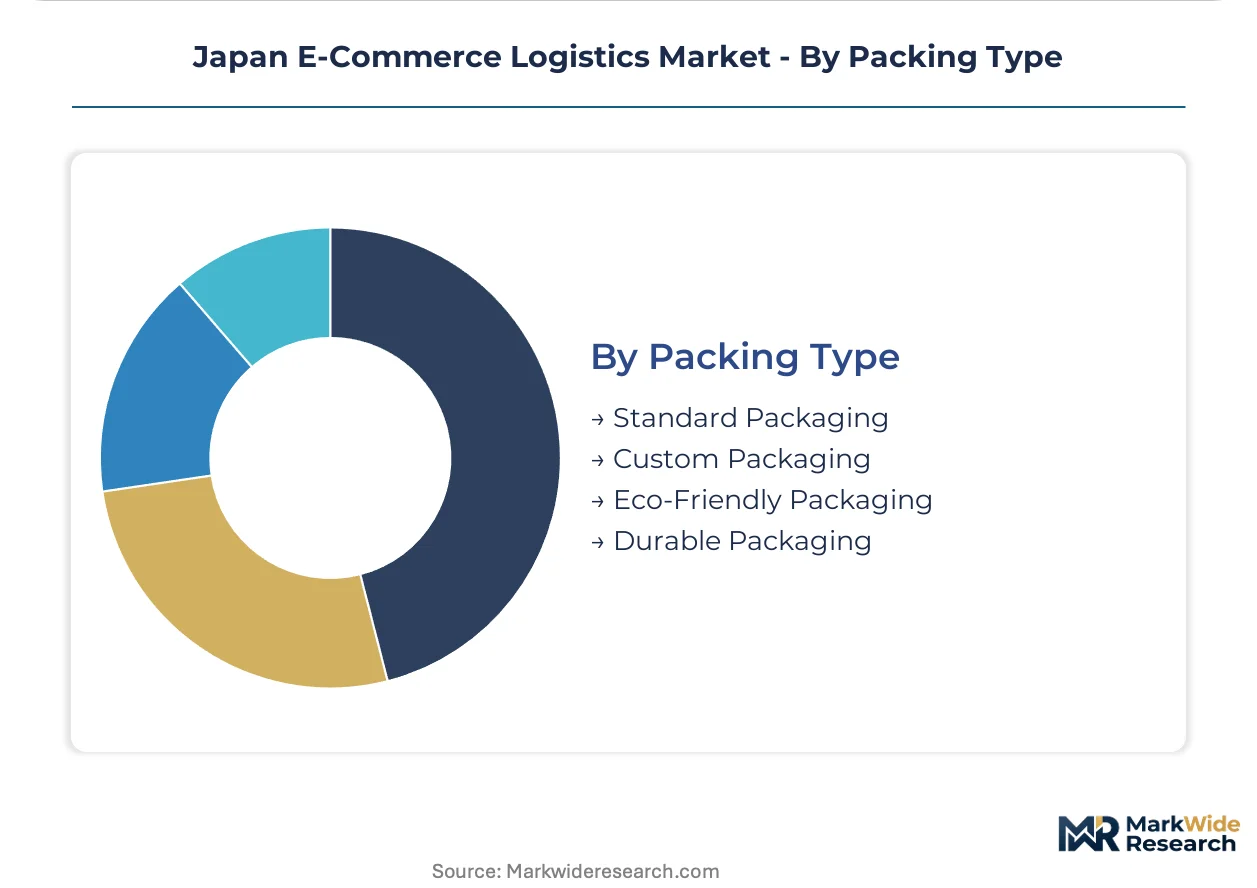
- Eco-Friendly Packaging:Recyclable and biodegradable materials comply with JIS standards for circular-economy fulfillment. Compliance-driven redesign creates carrier differentiation for sustainability-focused merchants in health and beauty segments.
- Custom Packaging:Branded unboxing experiences and product-specific protection drive premium service tiers. Fragile electronics and cosmetics categories demand tailored dimensional specifications.
- Standard Packaging:Generic corrugated solutions serve cost-sensitive high-volume shippers.
- Durable Packaging:Reusable container programs address subscription replenishment model requirements.
Standard Packaging holds the volume lead, with Eco-Friendly Packaging on the steepest expansion trajectory as regulatory deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's logistics workforce concentrates disproportionately in the Greater Tokyo Area, where delivery density and automation investment intensity exceed all other prefectures combined.
Kanto/Tokyo
Same-day and next-day service expectations drive micro-fulfillment node proliferation across Tokyo, Kanagawa, Saitama, and Chiba prefectures. METI's Act on Rationalization of Energy Use mandates warehouse automation timelines that accelerate capital deployment in the capital region. The Tokyo Bay logistics corridor hosts automated sortation hubs processing over 100,000 parcels hourly under compressed delivery windows.
Kansai/Osaka
Osaka Prefecture anchors western Japan's e-commerce fulfillment demand through Rakuten Ichiba ecosystem integration and SME merchant concentration. PMDA cold-chain standards intersect with JIS packaging recyclability mandates, shaping pharmaceutical and health-beauty logistics infrastructure design. The Osaka-Kobe port cluster supports cross-border e-commerce import processing and bonded warehouse expansion.
Chubu/Nagoya
Automotive and precision manufacturing supply chains generate substantial B2B contract logistics demand across Aichi, Gifu, and Shizuoka prefectures. The country's national pharmaceutical regulator enforces distribution standards that exceed available certified warehouse capacity in the region. Nagoya's central geographic position enables hub-and-spoke network extension toward secondary markets.
Kyushu
Underdeveloped same-day service coverage in Fukuoka, Saga, and Kumamoto prefectures presents whitespace for carrier network extension beyond the Tokyo-Osaka corridor. Work Style Reform Act constraints compress labor availability for last-mile operations in regional cities. The Fukuoka metropolitan area demonstrates accelerating grocery and fresh food delivery adoption among urban households.
Hokkaido
Geographic isolation and sparse population density elevate per-parcel delivery costs across Sapporo and secondary cities. Temperature-controlled vehicle deployment faces seasonal operational challenges and extended transit distances. Sapporo's urban core shows emerging demand for subscription-based replenishment models that enable route density optimization.
Japan E-Commerce Logistics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Japan's e-commerce logistics sector. The market structure consolidates around three national carriers with prefecture-level coverage density, while platform-native operators and international entrants fragment niche segments. Strategic archetypes include legacy parcel networks, marketplace-embedded logistics layers, and cross-border specialists. Carriers defend position through automation capex acceleration and micro-fulfillment node placement.
Within the legacy parcel network tier, Yamato Holdings and Sagawa Express exemplify divergent specialization strategies. Yamato leverages its TA-Q-BIN density across all 47 prefectures to sustain next-day coverage commitments. Sagawa anchors competitiveness in B2B contract logistics rather than consumer parcel density. Rakuten Logistics occupies a distinct position as a platform-native operator integrating fulfillment with the Rakuten Ichiba merchant ecosystem.
| Leading Market Players |
|---|
| Yamato Holdings |
| Sagawa Express |
| Japan Post Holdings |
| Rakuten Logistics |
| Seino Holdings |
| Nippon Express |
| Amazon Japan |
| SG Holdings |
| FedEx Express Japan |
| Others |
Pricing and Supply Chain Analysis
Hub-and-spoke automation deployment across Japan's fulfillment networks simultaneously compresses per-parcel handling costs and concentrates carrier bargaining power in the Greater Tokyo corridor. METI-mandated warehouse electrification timelines accelerate capital substitution for labor, reshaping cost structures while locking in scale advantages for automated incumbents.
Pricing Analysis
Bundled fulfillment-plus-delivery contracts dominate enterprise accounts, while unbundled per-parcel transactional pricing serves SME merchants. Three-tier pricing structure across premium temperature-controlled, standard next-day, and economy deferred delivery levels separates service commitments. Price differentiation hinges on delivery speed guarantees and cold-chain certification grade. Pricing pressure stems from Work Style Reform Act wage floor escalation without matching productivity gains. SME merchants exhibit highest price sensitivity; pharmaceutical and fresh food shippers prioritize compliance reliability over cost.
Supply Chain Analysis
Regional distribution centers cluster in the Tokyo Bay corridor, with secondary hubs in Osaka and Nagoya feeding hub-and-spoke extensions. Japan's e-commerce logistics supply chain draws from Chinese automated sortation equipment, South Korean IoT sensor arrays, and domestic AMR manufacturing. Lithium-ion battery cells, cross-belt sorter components, and refrigeration units constitute critical input dependencies. Single-source vulnerability concentrates in precision automation subsystems sourced from German and Swiss suppliers. Distribution runs through carrier-operated micro-fulfillment nodes positioned within two-hour drive radius of demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's e-commerce logistics sector offers margin expansion through automation-driven labor substitution and premium-tier cold-chain service differentiation. Work Style Reform Act constraints compress cost-competitive manual operations while rewarding capital-intensive scale players.
For Market Incumbents: To counter emerging platform-native logistics layers, accelerate AMR fleet deployment in Greater Tokyo micro-fulfillment nodes and secure PMDA-certified cold-chain capacity ahead of pharmaceutical demand inflection. Vertical integration into automated sortation equipment maintenance capabilities reduces dependency on overseas service technicians. For New Entrants and Emerging Players: Marketplace sellers in Rakuten Ichiba's long-tail merchant base represent the most penetrable customer segment, with unmet demand for flexible fulfillment services outside Yamato-Sagawa duopoly coverage. Prefecture-tier same-day coverage gaps in Kyushu and Hokkaido present geographic whitespace. A channel partnership strategy with regional supermarket chains enables grocery delivery network extension without greenfield infrastructure investment. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap carriers with underutilized warehouse footprints and legacy fleet assets ripe for automation retrofit. Long-term viability favors operators with demonstrated PMDA compliance track records and METI energy efficiency certification ahead of tightening enforcement windows. Watch AMR deployment velocity relative to labor cost inflation as the margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Node Expansion | Tokyo Bay corridor density gains enable same-day coverage without workforce scaling. |
| Cold-Chain Certification Investment | PMDA pharmaceutical distribution standards exceed available certified warehouse capacity. |
| AMR Fleet Deployment | Autonomous mobile robots offset Work Style Reform Act labor availability constraints. |
| Platform Integration Partnership | Rakuten Ichiba ecosystem embedding captures merchant fulfillment spend fragmentation. |
| Prefecture-Tier Network Extension | Hokkaido and Kyushu same-day coverage gaps present whitespace for hub-and-spoke buildout. |
Research Methodology
Direct dialogue with carrier operations executives, warehouse automation engineers, METI policy officials, Rakuten Ichiba merchant managers, and pharmaceutical logistics compliance officers grounded qualitative assessment. Secondary validation drew from METI energy efficiency filings, PMDA pharmaceutical distribution registrations, JIS packaging standard revisions, and customs automation equipment import records. Bottom-up parcel volume modeling and top-down e-commerce GMV aggregation enabled cross-triangulation.
Bottom-up carrier capacity utilization data and top-down merchant fulfillment spend estimates anchored the analytical lens across the projection horizon. Segmentation dimensions modeled include service type, technology tier, end-user category, and regional prefecture cluster. CAGRs derived from parcel volume trajectory analysis intersecting with automation capex cycle timing. Forecast inputs incorporated Work Style Reform Act labor cost escalation curves and METI electrification compliance deadlines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to autonomous vehicle street operation regulatory adaptation and AMR technology cost curves. Forecasts reflect documented assumptions regarding e-commerce penetration rates and carrier automation deployment schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
Estonia Freight and Logistics Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
Asean Freight Forwarding Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
United States Digital Freight Forwarding Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
Brazil Freight and Logistics Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
India Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Colombia Third-Party Logistics (3PL) Market
Logistics and Shipping
Turkey Cold Chain Logistics Market
Logistics and Shipping
Halal Logistics Market