
 Courier, Express and Parcel Services Market | 2026-2036
Courier, Express and Parcel Services Market Size, Share, and Industry Trends Forecast 2026-2036
Courier, Express and Parcel Services Market Intelligence
The fleet automation gap is rotating capital toward technology-heavy operators and away from asset-light brokers. DHL Group leverages its European ground hub network to sustain density economics in cross-border parcel flows. FedEx Corporation anchors North American air express capacity through Memphis superhub operations. United Parcel Service differentiates via healthcare-certified cold chain infrastructure across its US distribution footprint.
Courier, express and parcel services encompass time-definite collection, sortation, line-haul transport, and last-mile delivery of envelopes, cartons, and palletized freight, typically operating within service level agreements specifying delivery windows between two hours and five business days. The primary commercial purpose is to provide guaranteed transit times for business-critical documents, e-commerce orders, and just-in-time manufacturing components. Same-day and next-day service categories command premium pricing due to their dependency on dedicated fleet networks and real-time routing algorithms. Air delivery mode carries the highest revenue per piece but faces pressure from ground network densification. E-commerce customer volumes are reshaping sortation infrastructure design toward automated parcel handling at scale.
The US Department of Transportation governs motor carrier safety standards while the FAA regulates commercial drone operations for last-mile delivery trials. The EU Green Deal mandates fleet decarbonization timelines that are forcing parcel operators to electrify urban delivery vehicles across member states. China's MIIT oversees autonomous vehicle testing permits that determine which logistics firms can deploy driverless trucks on designated highway corridors. Stakeholders must monitor regulatory divergence between aviation authorities and surface transport agencies as drone integration accelerates.
Market Dynamics
E-commerce order density is compressing delivery economics toward automated sortation and electrified last-mile fleets, forcing capital reallocation from air networks to ground infrastructure.
Growth Catalysts
- EU Green Deal fleet mandates:Binding decarbonization timelines for urban delivery vehicles are accelerating electrification capex across member states, creating compliant fleet advantages for early movers.
- China's tier-one city clusters:Concentrated consumption in Beijing, Shanghai, and Guangzhou-Shenzhen corridors generates parcel volumes that justify dedicated automated hubs.
- Real-time routing algorithms:Machine learning-driven dispatch systems are reducing empty miles in same-day networks, improving asset utilization for premium service tiers.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing dominance in specific geographies creates input cost volatility for electric fleet conversion programs.
- Aviation slot scarcity:Restricted air cargo capacity at major European hubs limits express network expansion without alternative ground corridor investment.
- Autonomous vehicle permitting fragmentation:Divergent national frameworks for driverless truck deployment prevent standardized cross-border automation rollouts.
Strategic Opportunities
- Healthcare cold chain certification:Temperature-controlled pharmaceutical logistics represents an underpenetrated vertical with premium pricing and regulatory moats.
- Drone integration corridors:Designated low-altitude airspace frameworks in select jurisdictions enable beyond-visual-line-of-sight delivery trials for urgent medical shipments.
- Reverse logistics automation:E-commerce return volumes are outgrowing manual processing capacity, creating white space for automated sortation and refurbishment networks.
Industry Challenges
- Electrical technician scarcity:Fleet electrification programs face hiring gaps for high-voltage maintenance certification, delaying vehicle uptime targets.
- Legacy warehouse management integration:Automated parcel handling systems require costly middleware development to interface with decade-old inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Courier, Express and Parcel Services Market |
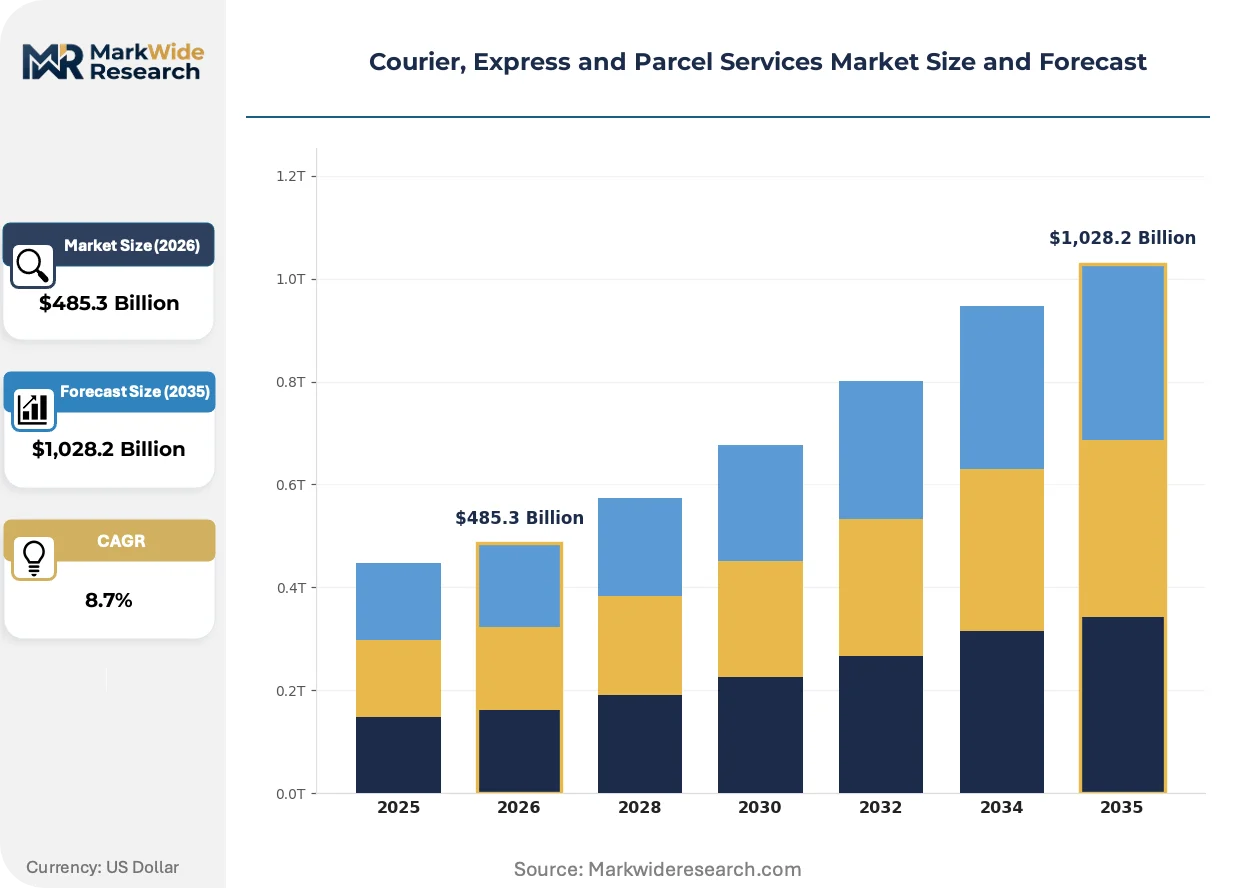
| Market Size in 2026 | $485.3 Billion |
| Market Size in 2035 | $1,028.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same Day, Next Day, International, Scheduled Delivery Mode: Ground, Air, Ocean, Drone Customer Type: Businesses, Individuals, E-commerce, Government Package Size: Small, Medium, Large, Bulk |
| Companies Covered | SF Express, Yamato Holdings, DHL Group, ZTO Express, Japan Post Holdings, FedEx Corporation, Aramex, Blue Dart Express, United Parcel Service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Courier, Express and Parcel Services Market Strategic Shifts & Innovations
Autonomous ground vehicles and predictive logistics platforms are restructuring competitive advantage toward data-intensive operators with captive infrastructure control.
Autonomous delivery robots equipped with LiDAR and computer vision are navigating designated urban zones for last-mile fulfillment. Grocery and quick-commerce platforms in dense European and Asian city centers are deploying these units at pilot scale. This automation is supplanting gig-economy courier pools in high-frequency, short-radius delivery corridors.
The EU Green Deal's binding fleet decarbonization timelines are mandating zero-emission vehicle procurement quotas for urban delivery operators. Parcel carriers are renegotiating municipal access contracts to secure preferential loading zones for electric vans. Last-mile providers with electrified fleets in Germany, France, and the Netherlands are capturing regulatory-compliant market share.
Shippers are consolidating parcel volumes with fewer integrated carriers to secure capacity commitments during peak windows. This buyer concentration is displacing fragmented broker relationships in favor of direct contracts with asset-owning networks. The shift is most pronounced in US and German manufacturing verticals with just-in-time component flows.
Courier, Express and Parcel Services Market Segmentation
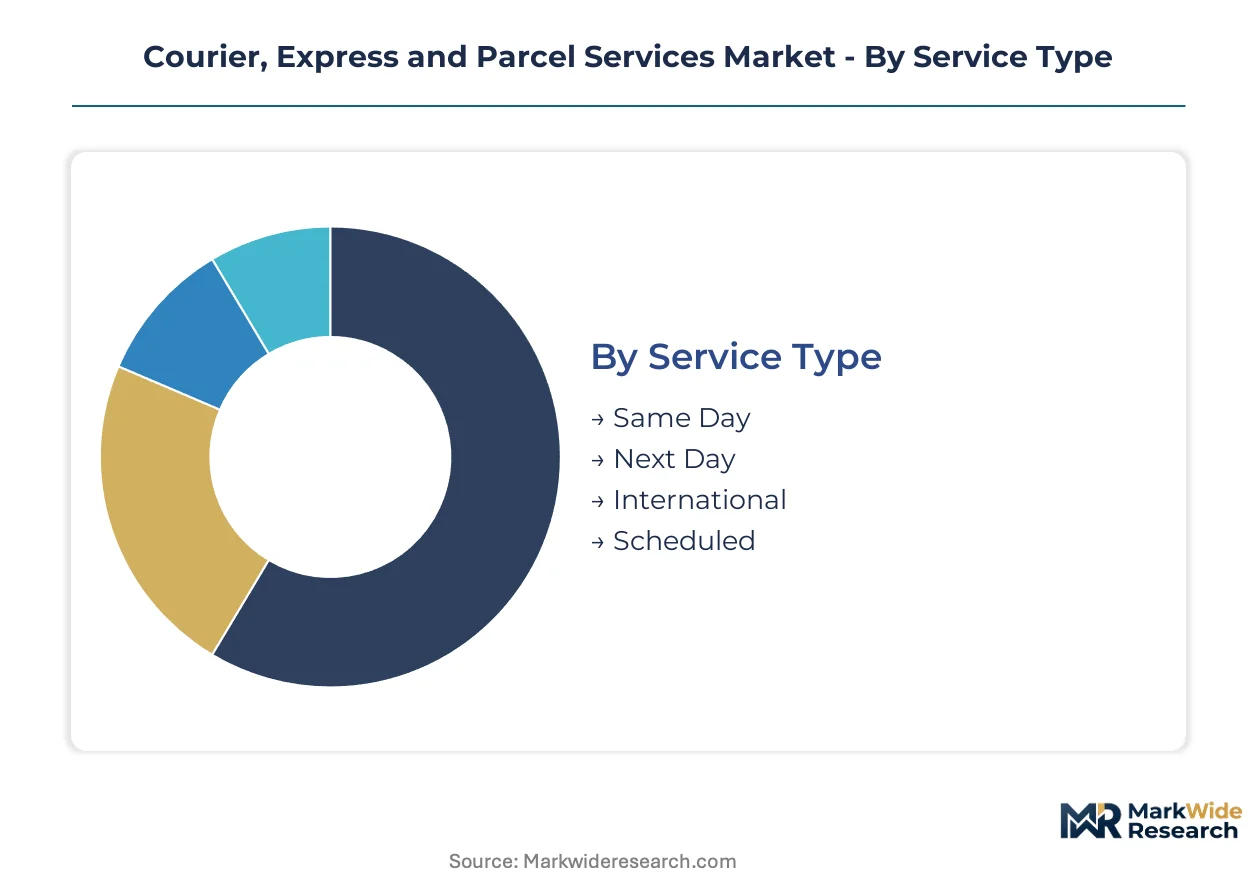
Service differentiation in courier and parcel markets determines capital allocation between air and ground infrastructure. Regulatory frameworks governing delivery timelines and emissions standards shape which segments capture investment priority.
Service Type:
Regulatory differentiation separates time-definite guarantees from flexible scheduling, with EU Green Deal emissions rules tightening fastest on urban same-day networks.
- Same Day:Dedicated fleet networks with real-time routing algorithms compress delivery windows to under six hours. E-commerce platforms in China's tier-one city clusters deploy these services for grocery and quick-commerce fulfillment, though EU urban access restrictions constrain fleet electrification timelines.
- Next Day:Overnight sortation hub operations guarantee morning delivery through line-haul density economics. US pharmaceutical distributors rely on this tier for temperature-controlled regional replenishment, leveraging FDA-validated chain of custody protocols.
- International:Cross-border customs clearance and aviation security screening extend transit windows. Customs bonded warehouse networks in Germany and the Netherlands anchor European import flows.
- Scheduled:Recurring pickup windows with flexible delivery windows reduce per-piece handling costs. Automotive suppliers in Japan's industrial corridors use these contracts for just-in-time component feeds.
Next Day handles the majority of throughput; Same Day is the fastest mover on share.
Delivery Mode:
Cost tier differentiation separates asset-heavy captive networks from brokered capacity, with electrification capex concentrating investment in ground infrastructure.
- Ground:Densified hub-and-spoke road networks carry the highest parcel volumes per route-mile. Automated sortation facilities in Germany and France process cross-border flows under EU Green Deal compliance mandates.
- Air:Memphis and Louisville superhub operations anchor North American express capacity. FAA slot scarcity at major hubs limits network expansion without alternative corridor investment.
- Ocean:Containerized parcel consolidation serves non-urgent international flows. Port automation in Rotterdam and Singapore reduces dwell times for consolidated freight.
- Drone:Beyond-visual-line-of-sight trials operate in designated Swiss and UAE airspace corridors for urgent medical shipments. Low-altitude traffic management frameworks determine deployment scale.
Ground handles the majority of throughput; Drone is climbing the fastest on investment intensity.
Customer Type:
Application differentiation separates volume-contracted B2B flows from fragmented consumer delivery economics.
- Businesses:Just-in-time manufacturing contracts demand guaranteed transit windows with penalty clauses. German automotive suppliers consolidate volumes with integrated carriers to secure peak-season capacity.
- E-commerce:Return volumes are outgrowing manual processing capacity, creating automation demand. China's platform merchants drive parcel density that justifies dedicated automated hubs.
- Individuals:Fragmented residential delivery requires address-level route optimization. Last-mile providers with electrified fleets capture regulatory-compliant municipal access.
- Government:Tendered postal universal service obligations specify geographic coverage mandates. India's Department of Posts maintains rural access networks through public subsidy.
E-commerce handles the majority of throughput; Government is expanding most slowly on deregulation pressure.
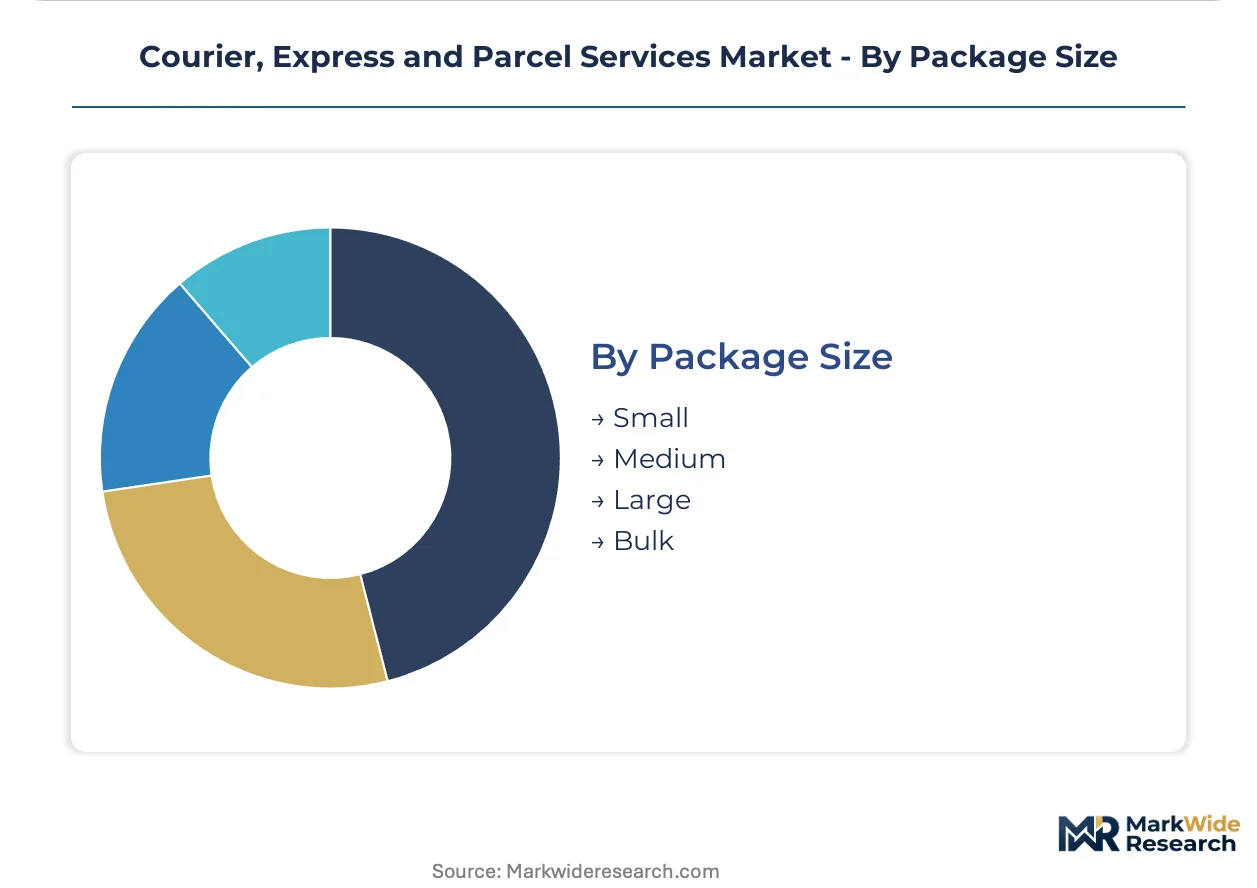
Package Size:
Volume differentiation determines sortation automation requirements, with small parcel standardization enabling the highest handling velocity.
- Small:Standardized envelope and carton dimensions feed automated belt sortation systems. E-commerce order profiles in dense Asian city centers concentrate demand here.
- Medium:Irregular dimensions require semi-automated handling with manual exception processing. Healthcare cold chain certification adds compliance overhead for pharmaceutical cartons.
- Large:Dimensional weight pricing compresses margin on bulky low-density freight. Furniture and appliance verticals drive demand in US suburban corridors.
- Bulk:Palletized flows integrate with LTL and FTL networks rather than parcel sortation. Industrial spare parts distribution uses these channels for scheduled replenishment.
Small handles the majority of throughput; Bulk is gaining share fastest on B2B consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parcel pricing power concentrates in Chinese tier-one corridors where automated hub density justifies premium same-day rates, while European operators absorb EU Green Deal compliance costs that compress urban delivery margins.
United States
E-commerce order density in the Northeast Corridor and California drives automated sortation investment. The FAA regulates commercial drone trials for last-mile delivery in select jurisdictions. Memphis anchors North American air express capacity through superhub operations that process overnight volumes.
Germany
Just-in-time automotive component flows from Bavaria and Baden-Württemberg sustain premium contract logistics demand. The EU Green Deal mandates zero-emission vehicle procurement quotas that accelerate fleet electrification capex. The Rhine-Ruhr corridor hosts automated cross-border hubs processing parcel flows under customs bonded warehouse frameworks.
China
Platform merchants in the Yangtze River Delta and Pearl River Delta generate parcel volumes that justify dedicated automated facilities. The MIIT oversees autonomous vehicle testing permits for driverless truck deployment on designated highway corridors. Beijing-Tianjin-Hebei clusters concentrate same-day fulfillment networks for grocery and quick-commerce verticals.
Japan
Pharmaceutical distributors in the Kanto region rely on temperature-controlled regional replenishment with validated chain of custody protocols. METI standards govern logistics automation investment incentives. The Kansai corridor maintains scheduled replenishment contracts for automotive suppliers feeding just-in-time manufacturing lines.
India
E-commerce penetration in Maharashtra and Karnataka creates last-mile density that attracts electrified fleet deployment. The Department of Posts maintains rural access networks through public subsidy obligations under tendered universal service mandates. The Delhi-NCR corridor concentrates cross-border express flows with customs modernization driving clearance velocity.
Courier, Express and Parcel Services Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated networks commanding premium positioning against asset-light brokers. The market structure concentrates around three to four dominant operators with captive infrastructure, while mid-scale specialists occupy vertical niches. Strategic archetypes include hub-and-spoke integrators, regional last-mile specialists, and platform-captive delivery networks. Competitive moves center on automated sortation capex and electrified fleet conversion to secure regulatory-compliant municipal access.
Among Asia-Pacific-based operators, SF Express and ZTO Express occupy positions within the high-volume automated tier, while DHL Group anchors European cross-border infrastructure. FedEx Corporation and United Parcel Service represent North American integrator archetypes with superhub-dependent network economics.
| Leading Market Players |
|---|
| SF Express |
| Yamato Holdings |
| DHL Group |
| ZTO Express |
| Japan Post Holdings |
| FedEx Corporation |
| Aramex |
| Blue Dart Express |
| United Parcel Service |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with integrated carriers lock in both network access and rate visibility for high-volume shippers, insulating committed volumes from spot-market volatility while exposing non-contracted flows to peak-season surcharges. These agreements concentrate pricing power with asset-owning operators in Germany and China, where automated hub density justifies premium rate cards.
Pricing Analysis
The customization-premium spread separates configured-to-order same-day services from standard next-day delivery, with real-time routing algorithms and dedicated fleet deployment commanding multiples over hub-consolidated flows. Three-tier pricing structure across premium, standard, and economy levels stratifies by transit-time guarantee and value-added service bundling. Cost compression in economy tiers is intensifying because e-commerce platforms are consolidating volumes with fewer carriers to secure capacity commitments. Small and medium enterprises exhibit highest price sensitivity, while pharmaceutical distributors demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive and electronics verticals, while strategic stockpiling persists in pharmaceutical cold chain and seasonal retail corridors to buffer against aviation slot scarcity. Cathode material processing concentrates in China, South Korea, and Japan, creating input cost volatility for electric fleet conversion programs. Lithium-ion battery supply, semiconductor components for autonomous systems, and high-voltage electrical hardware constitute critical dependencies. Single-source vulnerability in cathode chemistry processing threatens electrification timelines. Distribution runs through automated hub-and-spoke networks anchored by Memphis, Leipzig, and Shanghai superhub operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified electrical technicians for high-voltage fleet maintenance is constraining electrification velocity, creating competitive advantage for operators with captive training pipelines and unionized apprenticeship programs.
For Market Incumbents: Fortify hub automation density in China's tier-one corridors to sustain same-day premium pricing against platform-captive delivery networks. Secure EU Green Deal-compliant fleet conversion timelines ahead of binding mandates to capture municipal access advantages. Prioritize backward integration into charging infrastructure and battery leasing to control total cost of ownership. For New Entrants and Emerging Players: Anchor in reverse logistics automation for e-commerce returns processing, where manual capacity constraints outstrip demand growth in European and North American markets. Target healthcare cold chain certification as the most penetrable vertical, leveraging regulatory moats to justify premium positioning. Pursue asset-light partnerships with municipal authorities for drone corridor access rather than building captive ground networks. For Investors and Strategic Acquirers: Regional last-mile specialists with electrified fleet assets and municipal contracts represent the most defensible acquisition archetype against integrated carrier consolidation. Long-term viability hinges on regulatory-compliant infrastructure control rather than brokered capacity aggregation. Monitor autonomous vehicle permitting harmonization across European member states as the critical inflection signal for cross-border automation rollouts.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sortation Hub Deployment | Densifies parcel throughput per labor hour in China's Yangtze River Delta corridors. |
| Electric Fleet Conversion Program | Secures EU Green Deal-compliant municipal access in Germany and the Netherlands. |
| Healthcare Cold Chain Certification | Opens temperature-controlled pharmaceutical verticals with FDA-validated custody protocols. |
| Drone Corridor Partnership | Enables beyond-visual-line-of-sight trials in Swiss and UAE designated airspace frameworks. |
| Reverse Logistics Automation | Captures e-commerce return volumes outpacing manual processing capacity in European markets. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with logistics network planners, fleet operations directors, e-commerce fulfillment executives, and municipal transport regulators; and secondary validation through customs trade statistics, EU Green Deal implementation trackers, FAA drone trial filings, and SEC 10-K disclosures from integrated carriers. Bottom-up volume modeling triangulated against top-down macroeconomic consumption indicators across the projection horizon.
Across the analysis window, forecasts applied service type, delivery mode, customer segment, and package size dimensions alongside regional regulatory cluster differentiation. CAGRs derived from historical volume trajectories, electrification capex deployment curves, and autonomous vehicle permitting velocity. Model inputs incorporated e-commerce penetration rates, automotive just-in-time contract renewal patterns, and pharmaceutical cold chain infrastructure investment flows.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and continued lithium-ion battery supply concentration; material deviation would warrant model refresh. Revision becomes warranted when autonomous vehicle permitting harmonization crosses thresholds enabling standardized cross-border deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
Logistics Automation Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
Air Freight Market
Logistics and Shipping
India Contract Logistics Market
Logistics and Shipping
US FTL Brokerage Market
Logistics and Shipping
First and Last Mile Delivery Market
Logistics and Shipping
Middle East and Africa Courier Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
Australia Mining Logistics Market
Logistics and Shipping
Saudi Arabia Integrated Cold Chain Logistics Market
Logistics and Shipping
Digital Freight Matching Market
Logistics and Shipping
Global Port Logistics Market
Logistics and Shipping
Latin America Contract Logistics Market