
 United States Chartered Air Freight Transport Market | 2026-2036
United States Chartered Air Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
United States Chartered Air Freight Transport Market Insights
Pilot certification pipelines is collapsing across Part 135 operators, constraining fleet expansion for time-critical freight networks. Atlas Air Worldwide Holdings leverages its Boeing 747 freighter dominance to sustain transcontinental heavy-cargo routes. Kalitta Air anchors emergency government charter contracts through its Detroit operational base. Ameriflight specializes in short-haul feeder services, competing for regional airport pairs that trunk carriers bypass.
United States chartered air freight transport involves non-scheduled, contract-based cargo movement via dedicated aircraft where shippers reserve full payload capacity for specific origin-destination pairs, typically operating at 30,000 to 45,000 feet with pressurized cabins maintaining cargo integrity across temperature zones. The service serves industrial supply chains requiring speed, security, or outsized dimensions incompatible with scheduled belly-hold networks. Express service type commands premium rate structures due to guaranteed departure windows and dedicated ground handling, while pharmaceutical end users drive specialized freighter demand for validated cold-chain compartments. Door-to-door delivery mode captures margin pools through integrated trucking coordination, though airport-to-airport retains volume leadership among cost-sensitive automotive shippers.
FAA Part 135 certification governs operational safety and crew rest requirements for on-demand cargo carriers, while TSA Known Shipper programs regulate cargo screening protocols that shape market access for new entrants. EPA emissions standards for aircraft engines are forcing fleet renewal timelines, compressing returns on aging cargo conversions. Stakeholders must monitor crew supply elasticity and conversion feedstock availability before committing incremental freighter capacity.
Market Dynamics
Pilot certification bottlenecks at FAA Part 135 operators are compressing crew availability for on-demand cargo networks, forcing carriers to ration flight hours and defer route expansion despite sustained pharmaceutical and automotive demand.
Growth Catalysts
- Pharmaceutical cold-chain validation:Temperature-controlled compartments meeting FDA Good Distribution Practice standards are commanding dedicated freighter capacity for biologics distribution from Miami and Atlanta hubs.
- EPA emissions compliance timelines:Engine upgrade mandates for cargo conversion aircraft are accelerating fleet renewal programs that favor newer, more efficient chartered platforms over aging scheduled belly-hold alternatives.
- Southeast logistics corridor concentration:Infrastructure investment around Miami International and Hartsfield-Jackson Atlanta is anchoring consolidated charter operations for Latin American trade lanes.
Market Restraints
- Feedstock scarcity for cargo conversions:Narrow-body passenger aircraft availability for freighter modification is tightening as airlines extend lease terms, squeezing conversion pipeline capacity at US MRO facilities.
- Crew supply inelasticity:Part 135 pilot certification throughput cannot scale with route expansion timelines, creating a binding constraint on fleet utilization rates.
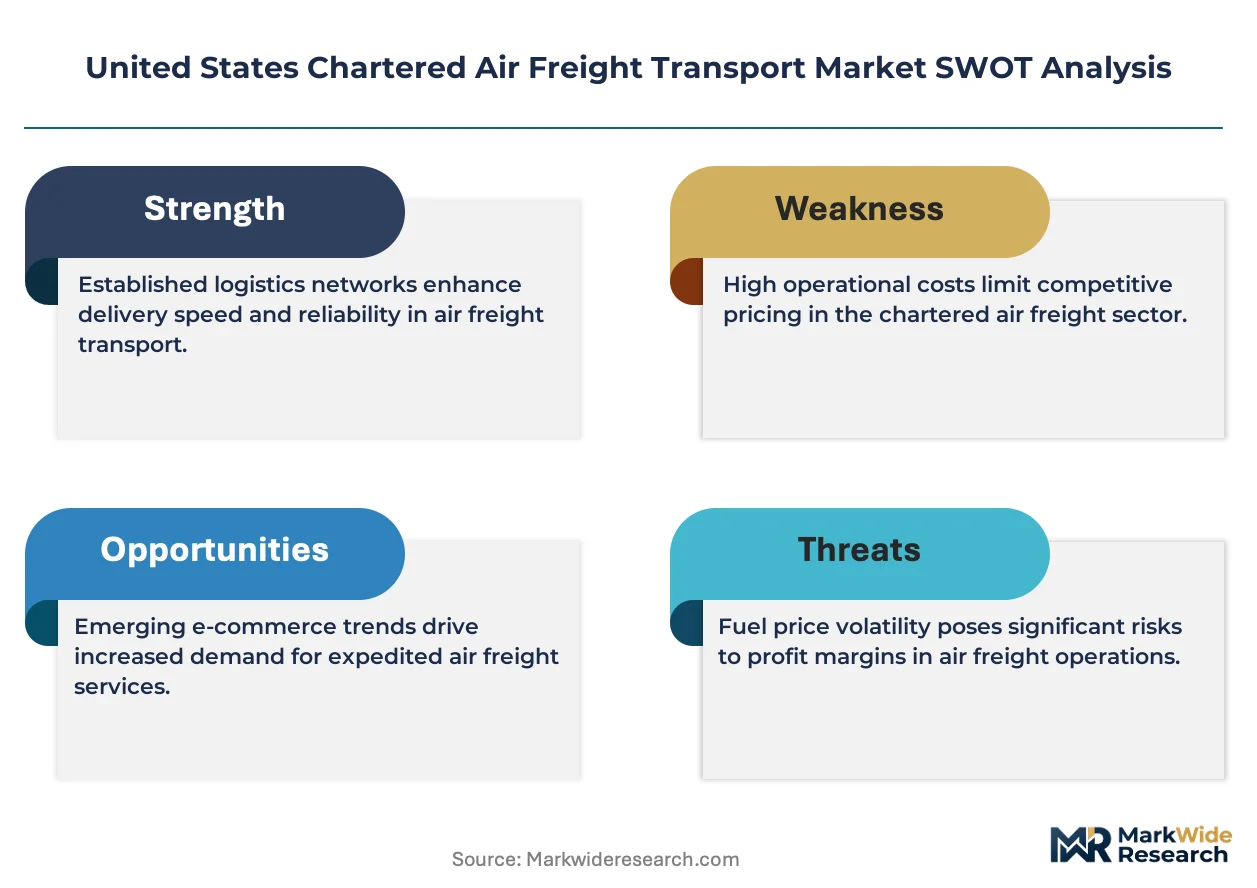
- Jet fuel price volatility:Unhedged fuel exposure erodes margins on ad-hoc charter contracts where fuel surcharge mechanisms lag spot market movements.
Strategic Opportunities
- Alaska and Hawaii lane development:Underpenetrated non-contiguous US states present white-space for dedicated freighter services bypassing scheduled carrier limitations on perishable and high-value goods.
- Integrated door-to-door coordination:Trucking-air-trucking bundled offerings capture margin pools from pharmaceutical distributors seeking single-accountability logistics.
- TSA Known Shipper program expansion:Streamlined security protocols for vetted cargo owners reduce screening delays and enable faster turnaround at secondary airports.
Industry Challenges
- FAA Part 135 certification timelines:Operational approval for new entrants stretches 18-24 months, delaying market entry and capital deployment.
- Legacy ground handling system integration:Charter operators struggle to synchronize with airport cargo terminal IT infrastructure designed for scheduled airline workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Chartered Air Freight Transport Market |
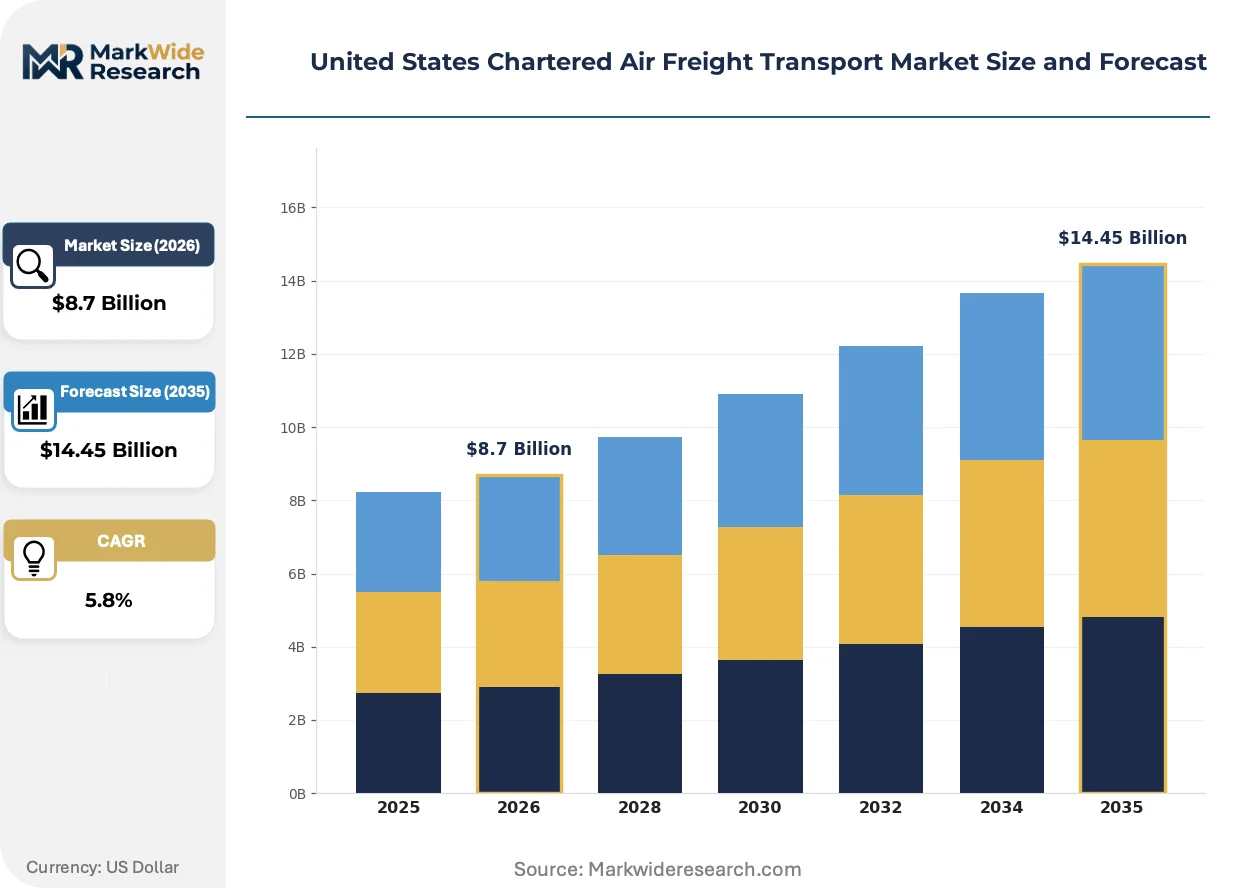
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Demand, Scheduled, Express, Standard End User: Aerospace, E-Commerce, Pharmaceuticals, Automotive Delivery Mode: Door-to-Door, Airport-to-Airport, Hub-to-Hub, Terminal-to-Terminal Aircraft Type: Freighter, Cargo Conversion, Passenger Aircraft, Specialized Aircraft |
| Companies Covered | Wheels Up Partners LLC, World Airways, Inc., Corporate Eagle Management Services, Inc., Miami Air International, Inc., Emery Air, LLC, Atlas Air Worldwide Holdings, Kalitta Air, Polar Air Cargo, Ameriflight, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Chartered Air Freight Transport Market Trends and Innovations
Real-time cargo monitoring systems are compressing insurance premiums and expanding addressable markets for temperature-sensitive freight. Three developments are reconfiguring competitive positioning.
Telematics-enabled environmental sensors are miniaturizing. Pharmaceutical shippers now embed multi-parameter loggers directly within pallet-level packaging, eliminating reliance on aircraft-mounted systems. This distributed architecture is miniaturizing the role of freighter-specific validation infrastructure and opening secondary airports lacking certified cold-chain terminals to chartered pharmaceutical movements.
FAA Part 135 crew rest requirement amendments are tightening duty-time calculations for augmented operations. The revised flight-time limitation schemes are forcing carriers to add relief crew on transcontinental routes previously operated with two-pilot configurations. Express pharmaceutical networks serving the Southeast corridor are responding by consolidating departure banks to maximize crew pairing efficiency.
Automotive shippers are unbundling expedited freight procurement from incumbent forwarder relationships. Tier-1 suppliers now charter direct from asset operators through digital booking platforms, disintermediating traditional air freight intermediaries. This behavior shift is most visible in Michigan-to-Mexico automotive supply chains where production schedule volatility rewards direct carrier relationships.
United States Chartered Air Freight Transport Market Segmentation
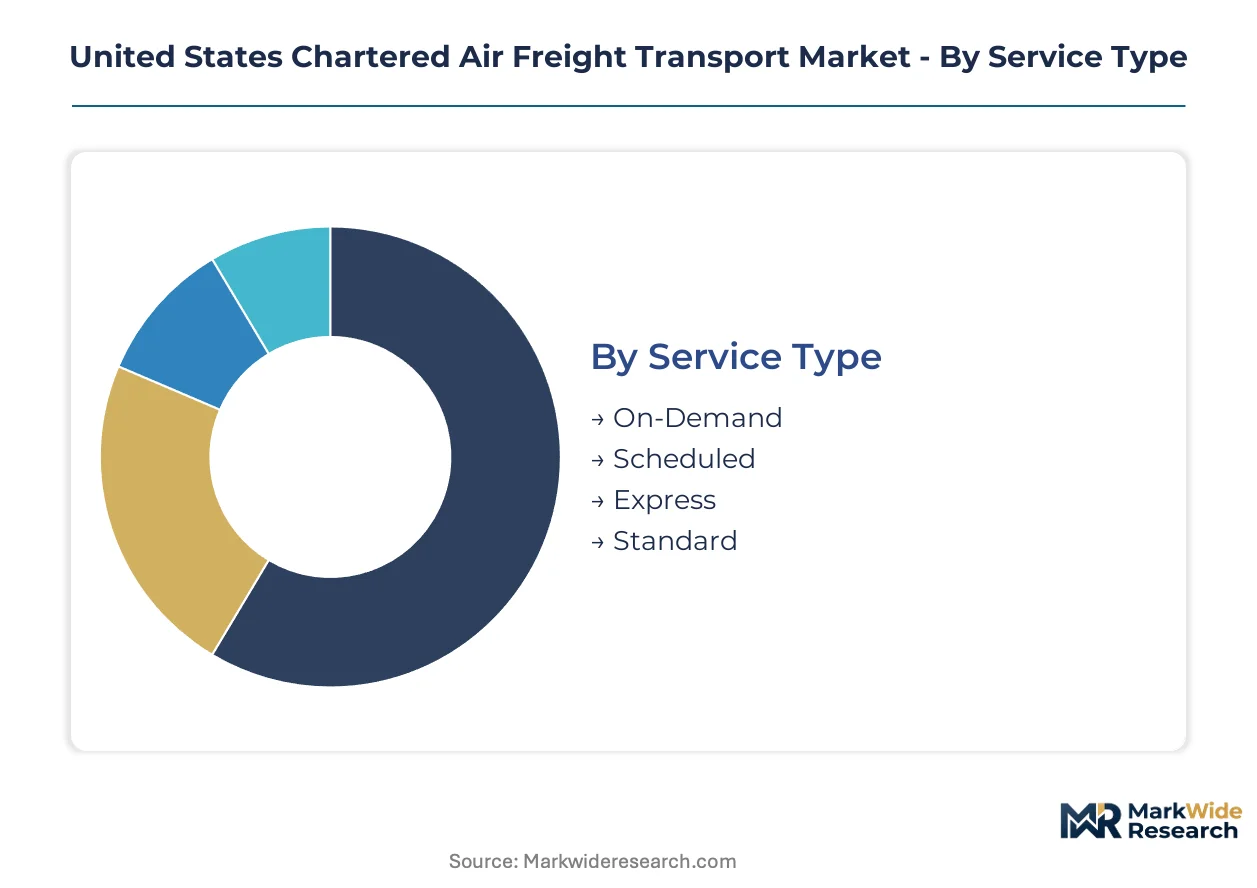
Segmentation reveals how substitution pressures reshape competitive boundaries across chartered air freight. Each dimension exposes where scheduled belly-hold networks, ground transport modes, and alternative logistics providers threaten contract-based cargo capacity.
Service Type:
Scheduled charter faces the stiffest substitution threat from expanding scheduled freighter networks, while on-demand retains protective moats through flexibility premiums.
- On-Demand:Contracted capacity activated per shipment without recurring schedule commitments. Pharmaceutical distributors in Miami and Atlanta corridors rely on this model for unpredictable biologics release schedules where FDA Good Distribution Practice validation cannot tolerate consolidation delays.
- Express:Guaranteed departure windows within defined timeframes command rate premiums. E-commerce fulfillment networks serving Southeast logistics corridors anchor demand here, as Amazon and Walmart direct-sourced charter contracts disintermediate traditional forwarder relationships.
- Scheduled:Recurring route commitments with fixed departure frequencies. Automotive shippers from Michigan to Mexico production facilities favor this for predictable supply chain cadences.
- Standard:Non-expedited charter with flexible departure windows. Cost-sensitive industrial freight from secondary Midwest airports concentrates here.
Standard service anchors the volume base while Express gains share at the steepest rate.
End User:
Cost tier stratification separates validated cold-chain requirements from commodity expedited freight.
- Pharmaceuticals:Temperature-controlled compartments meeting FDA standards for biologics distribution. Miami International and Hartsfield-Jackson Atlanta infrastructure investments concentrate demand from specialty distributors requiring uninterrupted cold chains.
- Automotive:Production-critical parts movement where assembly line stoppage costs dwarf charter premiums. Tier-1 suppliers in Detroit operational zones charter direct from asset operators through digital platforms.
- Aerospace:Oversized engine components and airframe sections incompatible with standard cargo dimensions. Boeing and Airbus supplier networks in Washington state and South Carolina drive specialized freighter demand.
- E-Commerce:Peak-season surge capacity and returns logistics. Amazon Air's insourcing limits third-party charter penetration here.
Automotive shipments dominate current contract value while Pharmaceuticals expands most quickly on cold-chain infrastructure buildouts.
Delivery Mode:
Integration depth determines margin capture, with bundled offerings threatening standalone airport-to-airport providers.
- Door-to-Door:Integrated trucking coordination captures full margin pools. Pharmaceutical distributors seeking single-accountability logistics drive adoption, with ground handling synchronized through real-time cargo monitoring systems.
- Airport-to-Airport:Core charter service without surface transport. Cost-sensitive automotive shippers retain volume leadership here, particularly on Michigan-to-Mexico lanes.
- Hub-to-Hub:Consolidated movements between major cargo terminals. Southeast corridor concentration around Miami and Atlanta favors this mode for Latin American trade lanes.
- Terminal-to-Terminal:Shipper-arranged surface legs at both ends. Secondary airport access where ground handling IT infrastructure lags scheduled airline workflows.
Airport-to-Airport maintains shipment count leadership while Door-to-Door climbs the fastest on pharmaceutical margin capture.
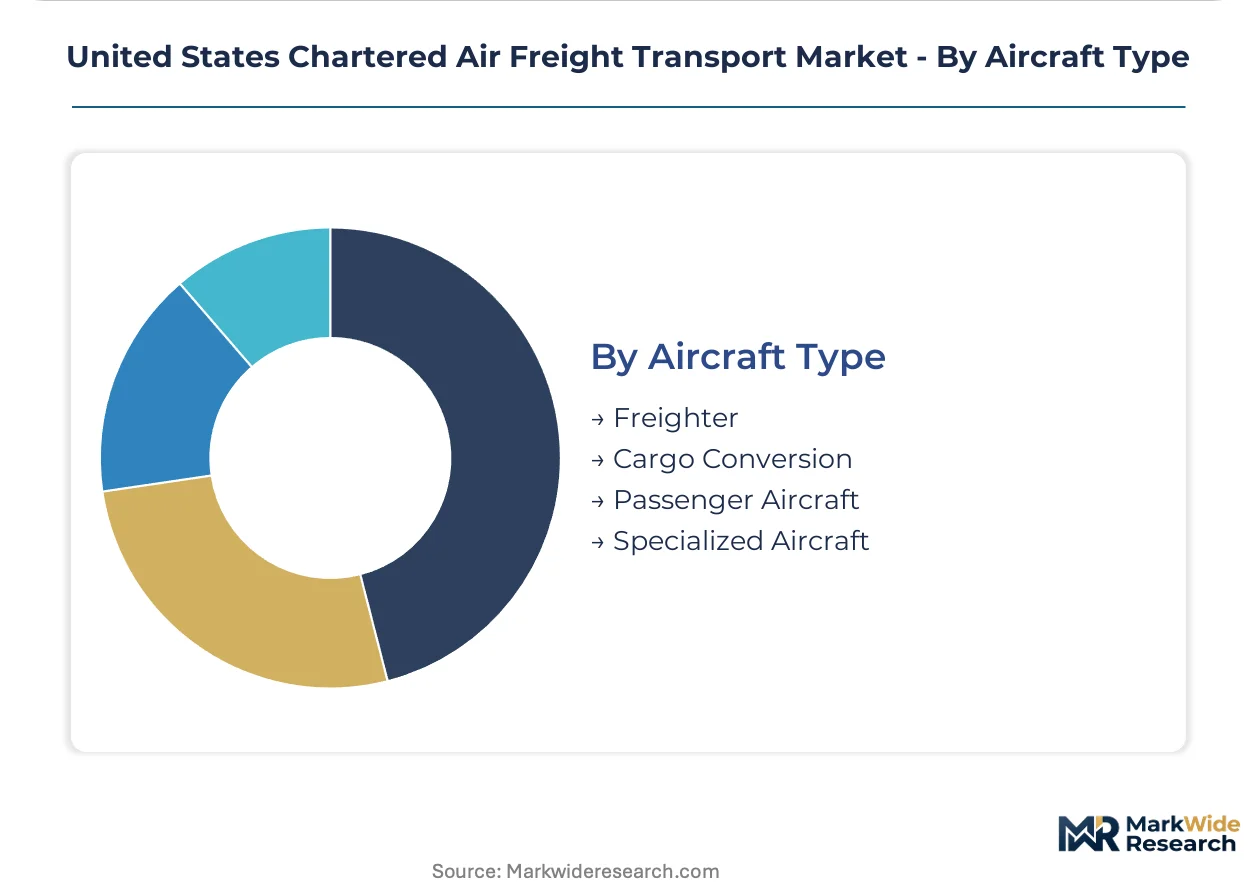
Aircraft Type:
Feedstock availability and EPA emissions compliance timelines stratify fleet economics.
- Freighter:Purpose-built cargo aircraft with nose-loading and main-deck capacity. Atlas Air Worldwide Holdings sustains transcontinental heavy-cargo routes through Boeing 747 freighter dominance.
- Cargo Conversion:Passenger-to-freighter modifications of narrow-body airframes. Feedstock scarcity squeezes conversion pipeline capacity at US MRO facilities as airlines extend lease terms on Boeing 737 and Airbus A320 platforms.
- Passenger Aircraft:Belly-hold utilization on scheduled services. Substitution threat intensifies as passenger fleet recovery expands lower-deck cargo capacity.
- Specialized Aircraft:Outsize cargo platforms including Antonov An-124 and Boeing Dreamlifter. Aerospace engine and airframe movements require this capacity where standard freighter dimensions fail.
Cargo Conversion underpins fleet expansion plans while Specialized Aircraft shows steepest rate gains on aerospace production reshoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA regulations governing Part 135 certification and crew rest requirements anchor operational standards across United States chartered air freight networks, with demand clustering around specific logistics corridors and industrial basins.
Southeast Logistics Corridor
Pharmaceutical cold-chain validation and Latin American trade lanes drive dedicated freighter demand through Miami International and Hartsfield-Jackson Atlanta. TSA Known Shipper programs streamline cargo screening protocols for vetted shippers at these hubs. Infrastructure investment around these airports consolidates charter operations for temperature-controlled biologics distribution.
Midwest Automotive Belt
Production-critical parts movement from Detroit operational zones to Mexico assembly plants sustains scheduled charter contracts. EPA emissions compliance timelines accelerate fleet renewal for carriers serving Michigan-to-Mexico lanes. Digital booking platforms enable Tier-1 suppliers to charter direct from asset operators, bypassing traditional forwarder relationships.
Alaska and Hawaii Lanes
Underpenetrated non-contiguous states present white-space for dedicated freighter services on perishable and high-value goods. FAA Part 135 certification requirements apply uniformly to these routes despite geographic isolation. Anchorage and Honolulu cargo terminals lack the cold-chain infrastructure of mainland hubs, constraining pharmaceutical penetration.
Pacific Northwest Aerospace Cluster
Outsize engine components and airframe sections from Boeing supplier networks drive specialized freighter demand. EPA emissions standards for aircraft engines force fleet renewal timelines that favor newer chartered platforms. Seattle-Tacoma International anchors heavy-cargo movements for production reshoring initiatives.
Southwest Border Region
Cross-border manufacturing integration between Texas and Mexican maquiladoras sustains expedited freight procurement. TSA Known Shipper program participation varies across secondary airports in the region. Laredo and El Paso logistics zones concentrate short-haul feeder services competing for regional airport pairs.
United States Chartered Air Freight Transport Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United States chartered air freight transport market. Consolidated heavy-cargo capacity dominates transcontinental routes while fragmented regional operators compete for short-haul feeder services. Three strategic archetypes define competitive positioning: integrated trunk carriers with freighter fleets, specialized cargo conversion operators, and on-demand Part 135 certificate holders. Dominant competitive moves include fleet renewal programs responding to EPA emissions mandates and direct charter relationships disintermediating traditional forwarders.
Among heavy-cargo specialists, Atlas Air Worldwide Holdings and Kalitta Air occupy positions at opposite ends of the contract spectrum. Atlas exemplifies scale-driven trunk carrier archetypes through Boeing 747 freighter dominance on transcontinental routes. Kalitta anchors emergency government charter contracts through its Detroit operational base. Ameriflight represents the regional feeder archetype, competing for short-haul airport pairs that trunk carriers bypass in the Southeast corridor and Midwest automotive belt.
| Leading Market Players |
|---|
| Wheels Up Partners LLC |
| World Airways, Inc. |
| Corporate Eagle Management Services, Inc. |
| Miami Air International, Inc. |
| Emery Air, LLC |
| Atlas Air Worldwide Holdings |
| Kalitta Air |
| Polar Air Cargo |
| Ameriflight |
| Others |
Pricing and Supply Chain Analysis
Fourteen-day lead times for cargo conversion slots at US MRO facilities concentrate pricing power among carriers with secured feedstock pipelines, while ad-hoc charter buyers absorb spot-rate volatility without contract hedges. This inventory compression at the conversion tier cascades into premium capture for purpose-built freighter operators serving FDA-validated pharmaceutical lanes.
Pricing Analysis
Miami-to-Atlanta corridor spreads exceed Midwest automotive belt premiums by double-digit percentage points, reflecting cold-chain validation costs embedded in Southeast pharmaceutical movements. Three-tier pricing structure across express, scheduled, and standard service levels separates guaranteed departure windows from flexible capacity. Cost compression in standard charter tiers is intensifying because unhedged fuel exposure erodes margins on spot contracts. Automotive shippers from Michigan production zones exhibit highest price sensitivity, while pharmaceutical distributors in Miami corridors accept premium rates for uninterrupted temperature integrity.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive and aerospace supply chains, forcing carriers to maintain surge-ready capacity without guaranteed utilization. Feedstock draws from US passenger airline lease extensions, Israeli MRO conversion specialists, and Chinese narrow-body manufacturing. Boeing 737 and Airbus A320 platform scarcity, engine upgrade mandates, and pilot certification bottlenecks create structural vulnerability. Distribution runs through Southeast corridor hubs at Miami International and Hartsfield-Jackson Atlanta for Latin American trade lanes, with secondary Midwest airports feeding regional feeder networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Part 135 pilot certification throughput collapsing against route expansion timelines creates binding constraints that reshape competitive advantage toward crew retention infrastructure and training pipeline ownership.
For Market Incumbents: Compound fleet renewal advantages by accelerating EPA-compliant engine upgrades before feedstock scarcity worsens, while securing exclusive conversion slot commitments at Detroit and Miami MRO facilities. Digital booking platforms disintermediating traditional forwarders threaten margin capture—respond by integrating proprietary trucking coordination for door-to-door pharmaceutical contracts. For New Entrants and Emerging Players: Anchor in Alaska and Hawaii lanes where scheduled carrier limitations on perishable goods leave white-space for dedicated freighter services. TSA Known Shipper program participation gaps at secondary airports in these non-contiguous states offer fastest penetration path. Pursue integrated ground-handling partnerships rather than airport-to-airport positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from airline parent companies seeking to monetize dormant cargo conversion assets amid lease extension pressures. Long-term viability hinges on crew supply elasticity rather than feedstock access alone. Monitor FAA Part 135 certification timeline compression as inflection signal—approval acceleration would unlock trapped capacity and revalue operator portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Cargo Conversion Slot Securement | Locked MRO capacity at US facilities insulates against Boeing 737 feedstock scarcity. |
| Crew Training Pipeline Investment | Proprietary Part 135 certification programs reduce reliance on FAA throughput bottlenecks. |
| Digital Platform Integration | Direct charter booking disintermediates forwarders on Michigan-to-Mexico automotive lanes. |
| Cold-Chain Infrastructure Partnership | Validated terminal access at Miami International anchors pharmaceutical rate premiums. |
| Door-to-Door Service Bundling | Trucking coordination capture margin pools from distributors seeking single-accountability logistics. |
Research Methodology
A standing panel of Part 135 operations directors, pharmaceutical logistics managers, MRO conversion specialists, and automotive procurement leads provided ongoing calibration against secondary validation from FAA certification databases, EPA emissions filings, TSA Known Shipper program records, and customs trade data. Bottom-up route-level capacity modeling triangulated with top-down fleet economics analysis.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions included service type, end-user industry, delivery mode integration depth, and aircraft platform category. CAGRs derived from fleet renewal timelines, feedstock availability curves, and crew supply elasticity projections. Forecast inputs incorporated pharmaceutical cold-chain validation adoption rates and automotive production reshoring patterns.
Decision-makers should treat outputs as directional under assumptions of stable FAA certification throughput and continued EPA emissions compliance timelines; material deviation would warrant model refresh. Revision becomes warranted when pilot certification pipeline collapse crosses thresholds that force route rationing or when cargo conversion feedstock scarcity triggers MRO capacity reallocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Digital Freight Matching Market
Logistics and Shipping
Mexico Freight Forwarding Market
Logistics and Shipping
South Africa Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
South Africa Third-Party Logistics (3PL) Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Russia 3PL Market
Logistics and Shipping
IoT Spend by Logistics Industry Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
United States Automotive Logistics Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Saudi Arabia Third-Party Logistics (3PL) Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
Empty Container Repositioning Optimization Platforms Market
Logistics and Shipping
United States Digital Freight Forwarding Market
Logistics and Shipping
Automotive Logistics Market