
 Brazil 3PL Market | 2026-2036
Brazil 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil 3PL Market Outlook
Premium cold-chain certification is bifurcating the Brazil 3PL market into compliance-ready operators and commodity players. DHL Supply Chain leverages its European-origin temperature-control protocols to anchor pharmaceutical and food-grade contracts. BBM Logística SA dominates southeastern Brazil through dense depot ownership around São Paulo and Curitiba. JSL SA specializes in heavy-industry project cargo, sustaining margin pools that general freight operators cannot access.
Third-party logistics encompasses outsourced transportation, warehousing, inventory management, and freight coordination executed under contract rather than captive ownership. Cold-chain 3PL requires validated thermal packaging, real-time telemetry, and documented excursion protocols to preserve product integrity across Brazil's climatic zones. Transportation services lead by revenue scale given highway dependence and port congestion, yet integrated solutions capture expanding margin pools as clients outsource end-to-end coordination. E-commerce client types are accelerating fastest, forcing warehouse automation and same-day delivery architectures that reshape fulfillment network design.
ANVISA governs pharmaceutical distribution licensing, while CONTRAN and DENATRAN regulate commercial fleet safety standards and driver hour limits across interstate operations. These frameworks elevate compliance costs but also consolidate demand toward certified operators with documented quality management systems. Stakeholders must monitor pending infrastructure concessions and federal logistics integration programs that could redraw modal competitiveness between road, rail, and coastal shipping corridors.
Market Dynamics
ANVISA's pharmaceutical distribution licensing is compressing the vendor base toward certified cold-chain operators with documented quality management systems, while e-commerce fulfillment demands pull refrigerated and last-mile capabilities toward São Paulo's industrial corridor.
Growth Catalysts
- E-commerce fulfillment acceleration:Same-day delivery mandates from online retailers are forcing warehouse automation investments and micro-fulfillment network expansion across southeastern Brazil.
- ANVISA pharmaceutical rules:Chain-of-custody documentation requirements and validated thermal packaging standards are consolidating demand toward compliance-ready 3PL operators.
- Refrigerated transport infrastructure:Temperature-controlled fleet expansion along BR-116 and BR-101 corridors is opening pharmaceutical and fresh food distribution to previously underserved interior markets.
Market Restraints
- Diesel price volatility:Fuel represents 35-40% of road freight operating costs in Brazil, and Petrobras pricing policy uncertainty compresses margin visibility for asset-heavy operators.
- São Paulo warehouse concentration:Premium industrial land scarcity within the ABC Paulista corridor limits depot network expansion for mid-tier 3PLs without captive real estate.
- Driver hour limits under CONTRAN:Electronic logging device mandates and stricter rest-period enforcement reduce fleet utilization rates versus historical baselines.
Strategic Opportunities
- Northern corridor penetration:Manaus free trade zone pharmaceutical manufacturing is creating demand for ANVISA-certified distribution infrastructure in Amazonas and Pará states.
- Rail-coastal intermodal:Ferrovia Norte-Sul integration with Port of Santos container terminals offers cost arbitrage for bulk chemical and agricultural export cargo.
- Cross-border Mercosur logistics:Argentina and Paraguay manufacturing supply chains are sourcing Brazilian cold-chain operators for temperature-sensitive agricultural machinery components.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems require costly retrofitting to achieve real-time temperature monitoring and excursion alert protocols demanded by pharmaceutical clients.
- Warehouse automation capex:Same-day fulfillment service-level agreements force investments in autonomous mobile robots and goods-to-person systems that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil 3PL Market |
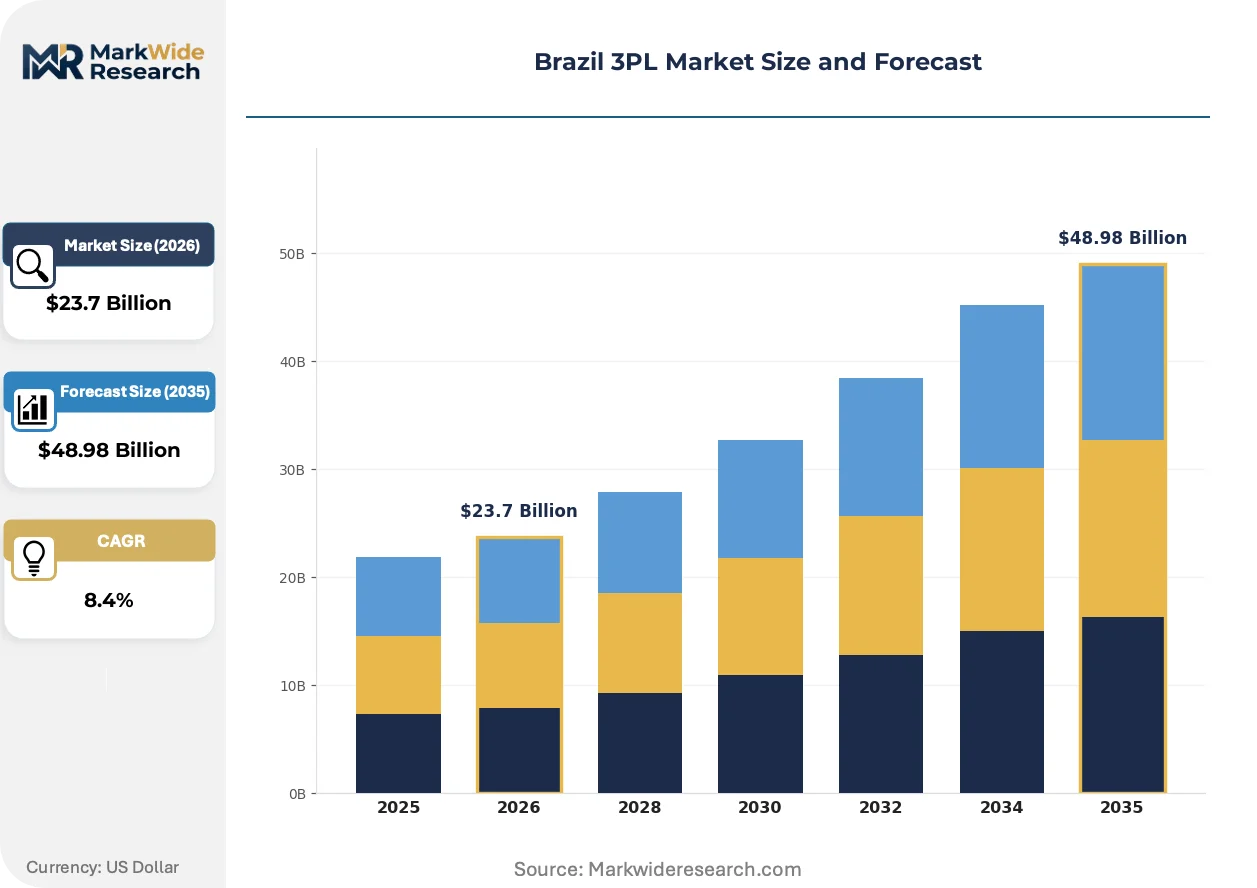
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Integrated Solutions Client Type: E-commerce, Retail, Manufacturing, Healthcare Technology: Cloud-Based Systems, IoT Tracking, WMS Solutions, Automation Tools Distribution Channel: Direct Sales, Online Platforms, Partnerships, Brokers |
| Companies Covered | DHL Supply Chain, A.P. Moller - Maersk Logistics & Services, BBM Logística SA, JSL SA, CEVA Logistics AG, Kuehne + Nagel International AG, C.H. Robinson Worldwide Inc., DSV A/S, Gafor Logistica SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil 3PL Market Strategic Shifts
Digital freight matching and warehouse robotics are restructuring how Brazilian 3PLs allocate capacity, with technology investments increasingly separating integrated solution providers from commodity transport operators.
Blockchain-enabled documentation is decomposing paper-based chain-of-custody processes in pharmaceutical and food-grade logistics. Major supermarket chains and hospital purchasing consortia are mandating distributed-ledger traceability for high-value temperature-sensitive shipments. This technology compression is eliminating smaller operators lacking IT integration budgets from premium contract bidding pools.
ANVISA's updated Good Distribution Practices directive tightens validation requirements for thermal packaging qualification and temperature-mapping protocols in pharmaceutical warehouses. The regulation forces 3PLs to maintain dedicated quality assurance teams and documented deviation investigation procedures. Cold-chain specialists with European-origin certification frameworks are capturing market share from domestic operators retrofitting compliance infrastructure.
Buyer consolidation among large retail pharmacy chains is compressing contract renewal cycles and demanding outcome-based service metrics. Previously discrete warehousing and transport procurement decisions are merging into integrated tenders with penalty clauses for temperature excursions. This behavioral shift is most visible in São Paulo and Rio de Janeiro metropolitan corridors where hospital networks and retail chains command procurement scale.
Brazil 3PL Market Segmentation
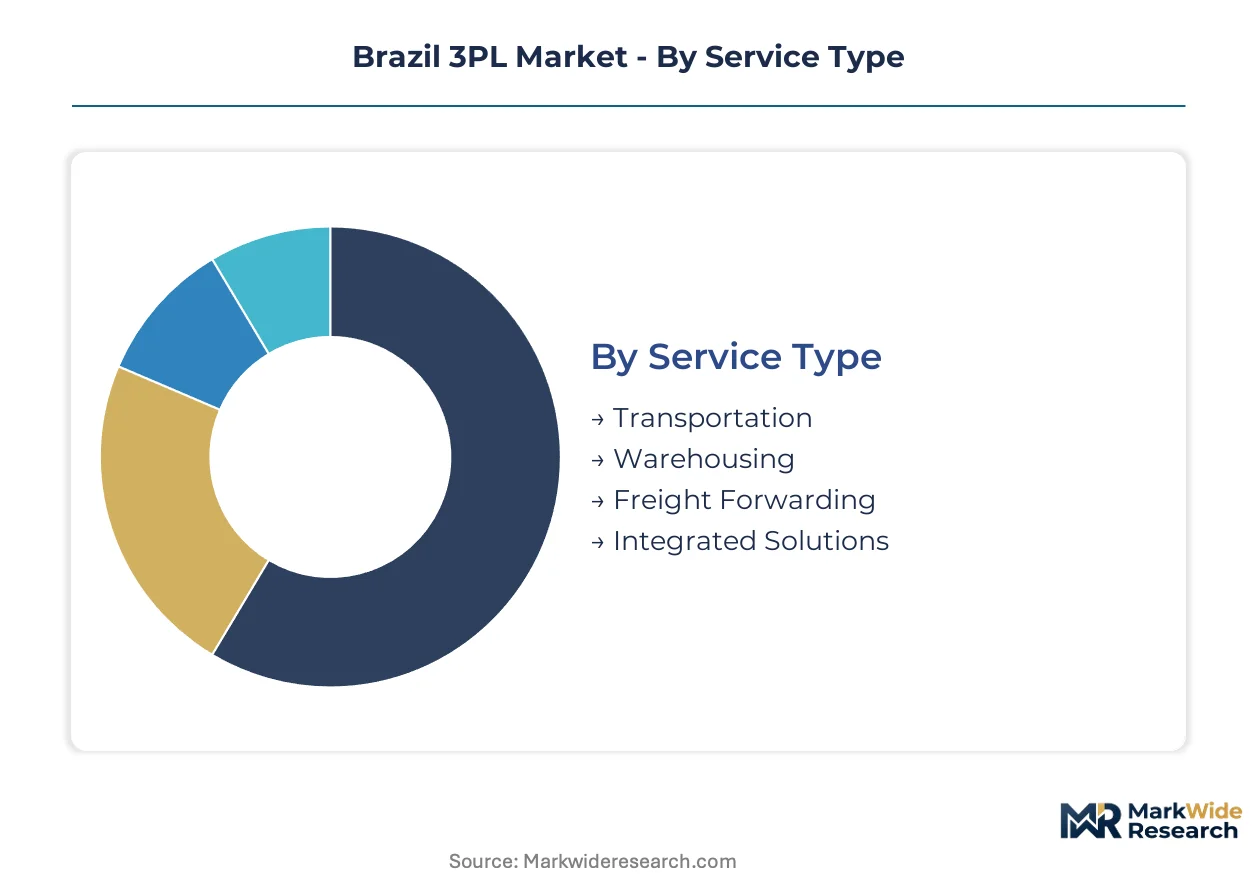
Brazil's 3PL market segments reflect divergent compliance burdens and capital intensity. ANVISA certification requirements split service tiers, while e-commerce velocity reshapes technology adoption curves across client categories.
Service Type:
ANVISA's pharmaceutical licensing creates a hard regulatory boundary between certified cold-chain operators and general freight providers.
- Transportation:Highway-dependent road freight dominates revenue scale given BR-116 and BR-101 corridor density. Diesel price volatility compresses margins for asset-heavy fleets serving interior markets.
- Warehousing:São Paulo's ABC Paulista corridor concentrates premium absorption, with scarcity forcing automation investments for same-day fulfillment mandates. Cold-chain depots require validated thermal mapping and dedicated quality assurance teams.
- Freight Forwarding:Port of Santos congestion sustains demand for customs coordination and modal optimization.
- Integrated Solutions:End-to-end contracts capture expanding margin pools as retail pharmacy chains merge procurement decisions.
Established volume favors Transportation; emerging adoption favors Integrated Solutions.
Client Type:
Procurement consolidation among large buyers is compressing contract structures toward outcome-based metrics with penalty clauses.
- E-commerce:Same-day delivery mandates force micro-fulfillment network expansion and autonomous mobile robot deployment across southeastern Brazil. Warehouse automation capex strains mid-cap balance sheets.
- Retail:Supermarket chains mandate blockchain traceability for temperature-sensitive shipments, eliminating smaller operators from premium bidding pools.
- Manufacturing:Heavy-industry project cargo sustains margin pools that general freight cannot access, particularly around automotive and agricultural machinery supply chains.
- Healthcare:Hospital purchasing consortia demand documented excursion protocols and real-time telemetry, consolidating demand toward European-origin certification frameworks.
Healthcare and E-commerce are climbing the fastest as ANVISA enforcement and delivery velocity reshape vendor selection criteria.
Technology:
Technology investments increasingly separate integrated solution providers from commodity transport operators.
- Cloud-Based Systems:Digital freight matching platforms restructure capacity allocation, reducing empty miles for mid-tier fleets.
- IoT Tracking:Real-time temperature monitoring and excursion alert protocols are mandatory for pharmaceutical contracts, requiring costly legacy fleet retrofitting.
- WMS Solutions:Warehouse management systems coordinate goods-to-person workflows demanded by e-commerce service-level agreements.
- Automation Tools:Autonomous mobile robots and automated sortation systems reshape fulfillment network design in São Paulo's premium industrial zones.
IoT Tracking holds steepest expansion trajectory as ANVISA tightens chain-of-custody documentation requirements.
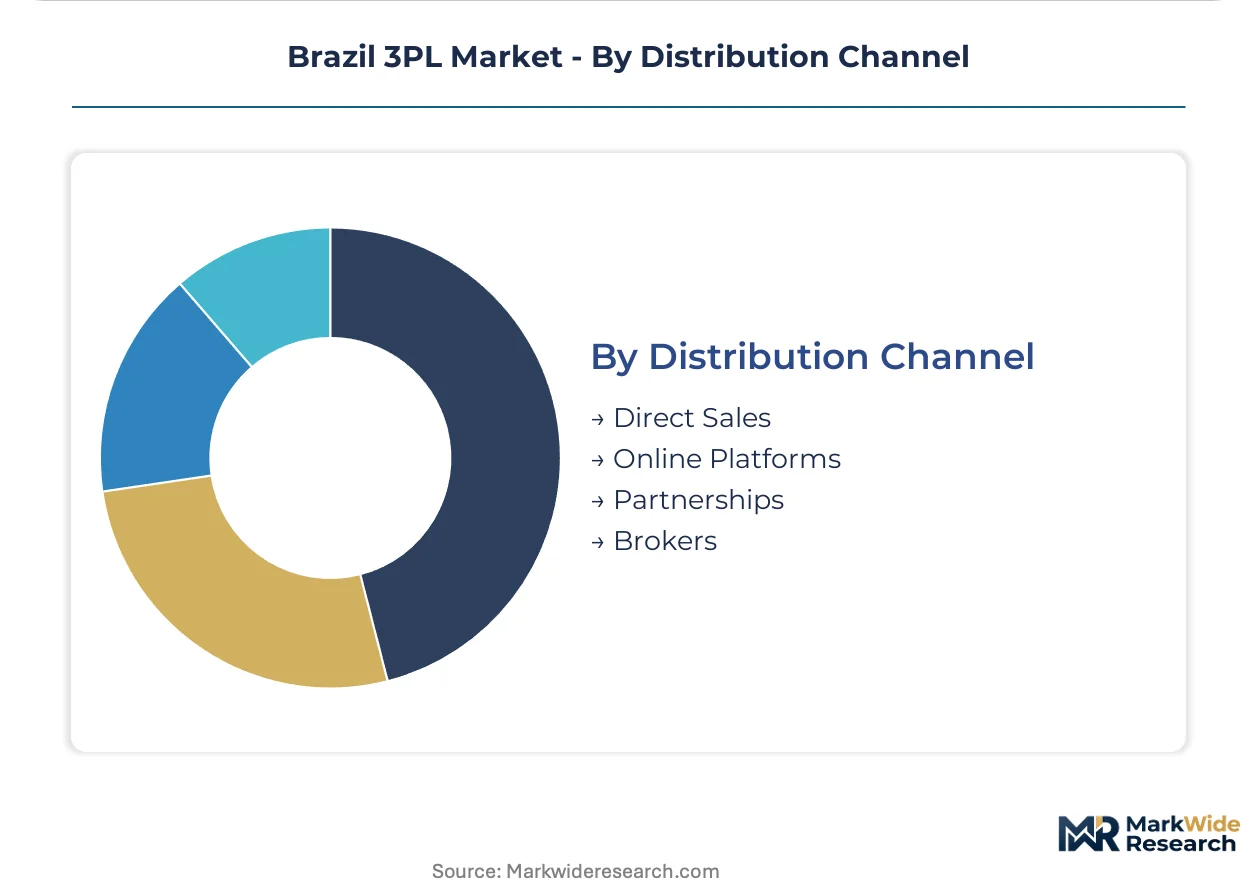
Distribution Channel:
Channel selection reflects customer scale and contract complexity rather than geographic coverage alone.
- Direct Sales:Large retail pharmacy chains and hospital networks procure through integrated tenders combining warehousing and transport.
- Online Platforms:Digital marketplaces match spot freight demand with available capacity, particularly for non-refrigerated cargo.
- Partnerships:Strategic alliances with supermarket chains and manufacturing consortia secure multi-year contracts with volume commitments.
- Brokers:Intermediary networks serve fragmented manufacturing and agricultural clients lacking procurement scale.
Direct Sales commands premium pricing; Online Platforms are gaining share fastest among mid-market shippers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's trade balance tilts toward agricultural and mineral exports, pulling 3PL capacity toward port corridors while import-dependent pharmaceutical and industrial inputs concentrate logistics demand around São Paulo's distribution nodes.
São Paulo
E-commerce fulfillment velocity and ANVISA-certified pharmaceutical distribution dominate demand in the ABC Paulista corridor. The state's environmental licensing agency CETESB enforces cold-chain facility standards. Guarulhos and Barueri warehouse clusters absorb premium industrial land for automated fulfillment centers serving same-delivery mandates.
Rio de Janeiro
Petrochemical and offshore oil equipment logistics sustain project cargo specialists along the Fluminense coast. The state's environmental regulator INEA imposes hazardous materials transport protocols. Duque de Caxias and Itaguaí industrial zones concentrate heavy-industry 3PL contracts tied to Petrobras supply chains.
Minas Gerais
Mining equipment and agricultural machinery distribution networks anchor 3PL demand in the Triângulo Mineiro and Belo Horizonte metro. IBAMA federal environmental oversight affects bulk cargo routing through the state. Uberlândia and Contagem logistics parks serve as consolidation points for interior agricultural supply chains.
Rio Grande do Sul
Meatpacking and soybean export corridors drive refrigerated transport investment along BR-116 and BR-290 highways. The state's agricultural secretariat MAPA coordinates phytosanitary certification for cross-border Mercosur shipments. Porto Alegre and Canoas distribution centers handle temperature-sensitive cargo bound for Uruguayan and Argentine markets.
Paraná
Soybean and poultry export volumes position Paranaguá port logistics as a critical 3PL node. ANVISA's cold-chain rules extend to pharmaceutical imports arriving through the port. Curitiba and Ponta Grossa industrial zones concentrate food-grade warehousing serving southern Brazil's agricultural processing belt.
Brazil 3PL Market Competitive Environment
Concentration sits with European-origin certification frameworks and southeastern depot networks. The vendor base splits between multinational integrated operators with pharmaceutical-grade cold-chain protocols and domestic asset-heavy fleets anchored in São Paulo industrial corridors. Three archetypes dominate: ANVISA-certified pharmaceutical specialists, e-commerce automation leaders, and heavy-industry project cargo operators. Competitive moves center on warehouse automation capex for same-day fulfillment and strategic depot acquisitions around constrained ABC Paulista land.
Among European-origin integrated operators, DHL Supply Chain and Kuehne + Nagel International AG exemplify compliance-ready archetypes with temperature-control protocols. Domestic depot density leaders include BBM Logística SA and JSL SA, representing southeastern network ownership and heavy-industry specialization respectively. These named entities occupy positions reflecting the market's bifurcation between certification-driven pharmaceutical contracts and asset-heavy regional freight consolidation.
| Leading Market Players |
|---|
| DHL Supply Chain |
| A.P. Moller - Maersk Logistics & Services |
| BBM Logística SA |
| JSL SA |
| CEVA Logistics AG |
| Kuehne + Nagel International AG |
| C.H. Robinson Worldwide Inc. |
| DSV A/S |
| Gafor Logistica SA |
| Others |
Value Chain & Pricing Dynamics
Automation capex substitution for labor-intensive warehouse operations simultaneously reshapes supply geography toward São Paulo's premium industrial zones and compresses pricing economics for mid-tier operators lacking balance sheet capacity. This input substitution dynamic concentrates margin capture among capitalized players while forcing commodity 3PLs toward price-competitive regional corridors.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Brazil's 3PL sector. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-certified pharmaceutical operators from general freight providers and spot-market commodity haulers. Price differentiation rests on certification grade and volume scale, with healthcare procurement consortia commanding lowest rates through integrated tender consolidation. Pricing pressure stems from diesel cost volatility transmitted through Petrobras policy uncertainty, squeezing asset-heavy fleets most severely.
Supply Chain Analysis
Port of Santos congestion elevates inbound logistics costs for temperature-controlled pharmaceutical imports and automated warehouse equipment from Germany, China, and the United States. Equipment sourcing draws from European automation vendors for goods-to-person systems and Asian manufacturers for IoT telemetry hardware. Single-source vulnerability concentrates in validated thermal packaging qualification services anchored to São Paulo certification laboratories. Distribution runs through hub-and-spoke networks radiating from ABC Paulista corridor depots to regional consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's 3PL sector operates as a defensive-moat market where ANVISA regulatory entrenchment creates durable switching costs for certified operators. This structural advantage consolidates procurement decisions toward compliance-ready incumbents with documented quality management systems.
For Market Incumbents: Fortify depot network density around constrained São Paulo industrial land through strategic acquisitions before premium real estate exhaustion. Deepen backward integration into captive cold-chain equipment maintenance to offset third-party service margin leakage. ANVISA's tightening Good Distribution Practices directive threatens domestic operators retrofitting compliance infrastructure, favoring European-origin certification frameworks. For New Entrants and Emerging Players: Differentiate on blockchain-enabled chain-of-custody documentation to capture supermarket and hospital purchasing consortia mandating distributed-ledger traceability. Target northern corridor penetration in Amazonas and Pará states where Manaus free trade zone pharmaceutical manufacturing outpaces certified distribution infrastructure. Lead with rail-coastal intermodal cost arbitrage for bulk chemical exporters seeking modal optimization. For Investors and Strategic Acquirers: ANVISA's updated pharmaceutical distribution licensing reshapes the acquisition landscape toward compliance-ready cold-chain specialists with established quality assurance teams. Long-term viability centers on operators with European-origin temperature-control protocols and southeastern depot density capable of serving integrated healthcare tenders. Monitor electronic logging device enforcement under CONTRAN as fleet utilization compression signal.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Investment | Quality management system documentation secures pharmaceutical contract access under tightened Good Distribution Practices. |
| Warehouse Automation Deployment | Autonomous mobile robots enable same-day fulfillment service-level agreements with e-commerce retailers in São Paulo corridor. |
| Northern Corridor Network Expansion | Certified cold-chain depots in Amazonas capture Manaus free trade zone pharmaceutical manufacturing demand. |
| Rail-Coastal Intermodal Integration | Ferrovia Norte-Sul connectivity with Port of Santos reduces bulk chemical export logistics costs. |
| Blockchain Traceability Implementation | Distributed-ledger documentation meets supermarket chain mandates for temperature-sensitive shipment visibility. |
Study Parameters
A spread of perspectives from logistics operations directors, pharmaceutical supply chain managers, ANVISA compliance officers, and e-commerce fulfillment executives converged on the working assumptions driving this analysis. Primary interview insights combined with secondary validation from DENATRAN fleet safety filings, ANVISA regulatory bulletins, customs trade data, and infrastructure concession documents. Bottom-up service-type demand modeling and top-down macroeconomic triangulation anchored volume and value estimates across the projection horizon.
Segmentation dimensions modeled include service type, client category, technology adoption tier, and distribution channel complexity throughout the forecast period. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and infrastructure investment cycles. Forecast inputs incorporated diesel price elasticity coefficients, warehouse automation capex curves, and pharmaceutical cold-chain compliance cost escalators specific to Brazilian regulatory frameworks.
Forecasts assume regulatory continuity in ANVISA pharmaceutical licensing and CONTRAN driver hour enforcement regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Control Towers Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
US Cross-Border Road Freight Transport Market
Logistics and Shipping
Ocean Freight Forwarding Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
Freight Brokerage Market
Logistics and Shipping
Middle East and Africa Freight & Logistics Market
Logistics and Shipping
Tennessee Freight and Logistics Market
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Water Hauling Services Market