
 Australia General Surgical Devices Market | 2026-2036
Australia General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia General Surgical Devices Market Outlook
Aftermarket service revenue for reusable surgical instrument sets is rewriting profit allocation across the value chain. Medtronic leverages its broad service network to capture recurring maintenance contracts. Stryker anchors its position through captive sterilization logistics and tray management programs. Johnson & Johnson competes by extending its DePuy Synthes service footprint into regional hospital clusters.
General surgical devices encompass manually operated and powered instruments, including scalpels, forceps, retractors, and electrosurgical generators, typically manufactured from medical-grade stainless steel or titanium alloys with passivation layers to prevent corrosion; these tools enable tissue manipulation, hemostasis, and wound closure across operative settings. Electrosurgical devices command premium positioning due to energy-delivery precision requirements and disposable accessory attachment rates. Minimal invasive surgery technology leads volume growth as laparoscopic and endoscopic platforms expand procedural applicability beyond traditional open techniques. Sutures retain stable demand through chronic wound closure needs, though synthetic absorbable variants displace natural materials in faster-healing applications.
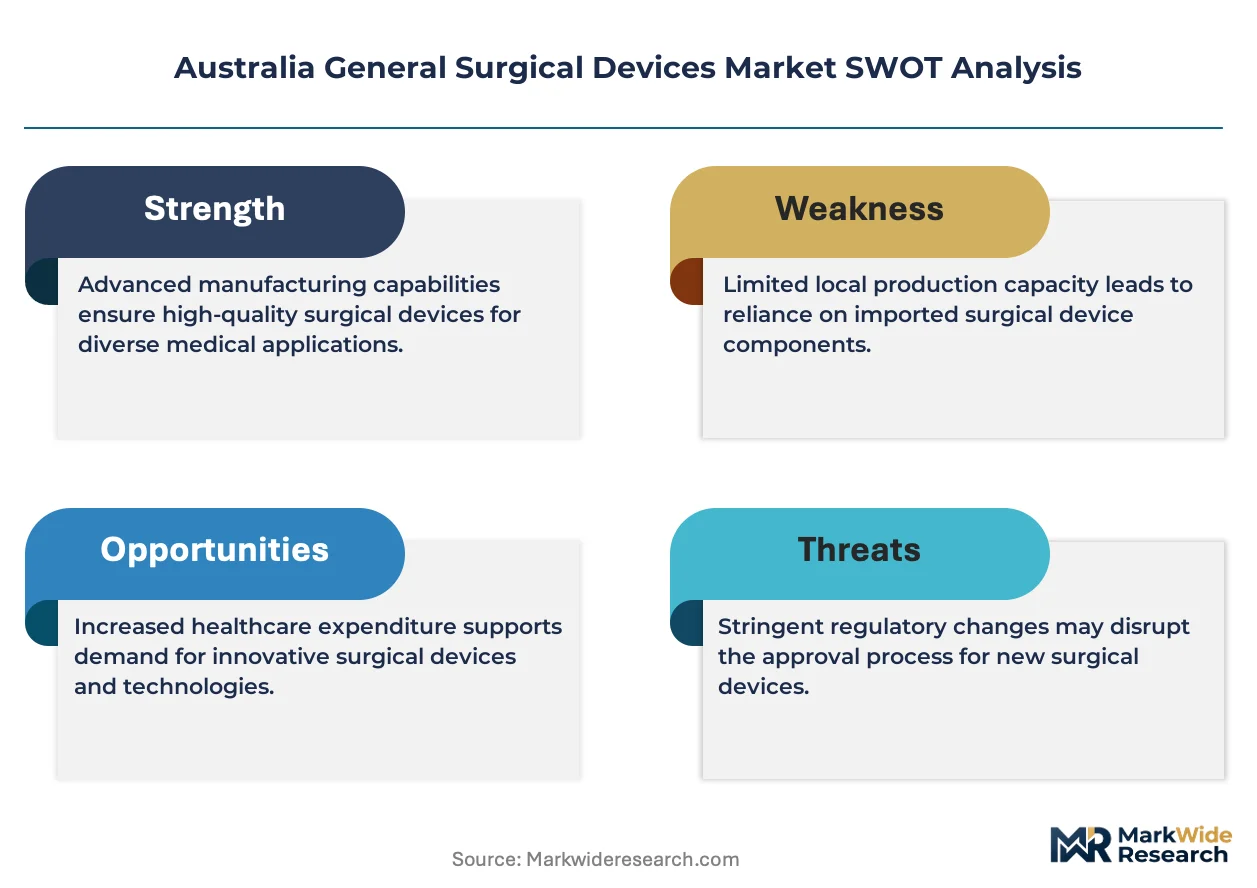
TGA medical device regulations and ISO 13485 quality management standards govern market entry, with TGA's Essential Principles mandating clinical evidence thresholds that filter lower-capability suppliers. The Therapeutic Goods (Medical Devices) Regulations impose post-market surveillance obligations that elevate compliance costs for distributed product portfolios. Stakeholders must monitor TGA's convergence with international medical device regulator forum harmonization timelines to anticipate documentation and audit burden shifts.
Market Dynamics
Ambulatory surgical centers in New South Wales and Victoria are accelerating procedure volumes while TGA tightens device registration pathways, creating a bifurcated demand structure that favors suppliers with established sterilization logistics and regional service networks.
Growth Catalysts
- Laparoscopic platform expansion:Minimally invasive surgery technology extends procedural applicability beyond traditional open techniques, driving instrument set turnover in metropolitan hospital networks.
- TGA Essential Principles alignment:Clinical evidence thresholds mandated by the Therapeutic Goods (Medical Devices) Regulations filter lower-capability suppliers, consolidating procurement toward ISO 13485-certified manufacturers.
- Victoria hospital network procurement:Major public health clusters anchor centralized purchasing agreements that aggregate demand for reusable instrument sets and electrosurgical generators.
Market Restraints
- Titanium alloy input volatility:Medical-grade titanium supply concentrates with limited Australian smelting capacity, exposing manufacturers to import price fluctuations and passivation layer quality variance.
- Post-market surveillance burden:TGA's distributed product portfolio obligations elevate compliance costs disproportionately for mid-tier suppliers lacking dedicated regulatory affairs infrastructure.
- Synthetic suture displacement:Absorbable polymer variants displace natural catgut in faster-healing applications, compressing margins for traditional material suppliers without advanced polymer extrusion capabilities.
Strategic Opportunities
- Western Australia penetration gap:Perth metropolitan and regional hospital procurement remains fragmented relative to eastern seaboard concentration, offering first-mover advantage for integrated service providers.
- Electrosurgical disposable attachment models:Premium positioning through energy-delivery precision requirements enables recurring revenue streams from single-use electrodes and return electrode pads.
- IMDRF harmonization tailwind:TGA convergence with International Medical Device Regulator Forum documentation standards will reduce audit burden duplication for suppliers already certified under FDA or Health Canada pathways.
Industry Challenges
- Sterile processing technician scarcity:Captive sterilization logistics and tray management programs require specialized certification that outpaces vocational training pipeline output in regional Queensland and South Australia.
- Legacy electrosurgical generator integration:Hospital capital replacement cycles lag technology advancement, forcing suppliers to maintain backward compatibility with decade-old energy delivery platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia General Surgical Devices Market |
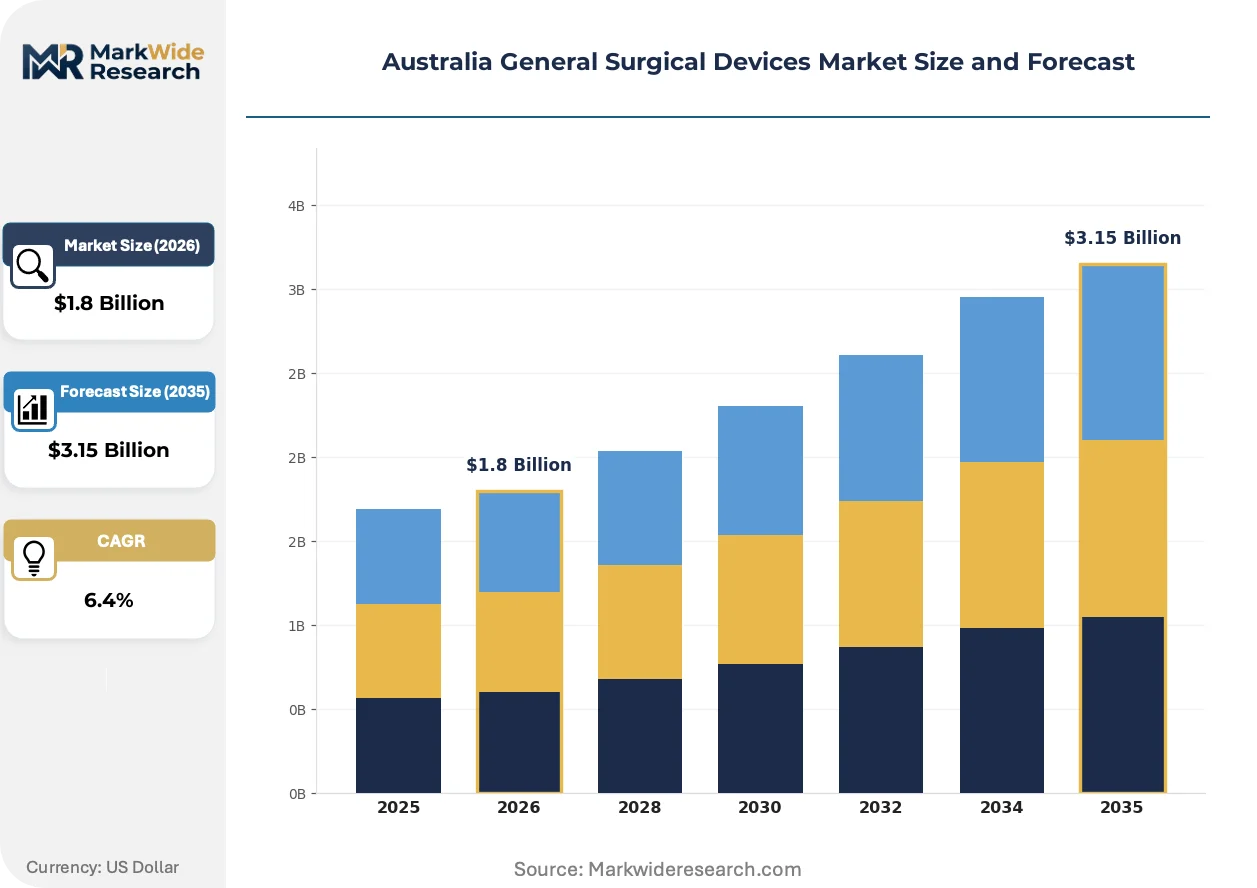
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Sutures, Electrosurgical Devices, Monitoring Equipment End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: General Surgery, Orthopedics, Urology, Gynecology Technology: Minimal Invasive Surgery, Robotic Surgery, Traditional Surgery, Endoscopy |
| Companies Covered | Medtronic, Johnson & Johnson, Boston Scientific Corporation, Stryker, B. Braun, Conmed Corporation, Smith & Nephew, 3M Healthcare, Integra LifeSciences, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia General Surgical Devices Market Strategic Shifts
Device manufacturers are embedding intelligence into conventional instruments while regulatory convergence accelerates documentation standardization, reshaping how surgical tool value chains capture service revenue.
Smart surgical instruments with embedded RFID tracking and usage-cycle monitoring are hybridizing asset management with clinical workflow optimization. Major public hospital networks in Sydney and Melbourne pilot these platforms to reduce instrument set loss and optimize sterilization throughput. The technology is hybridizing hardware sales with subscription-based analytics services that compress traditional capital procurement into operational expenditure models.
TGA's alignment with EU MDR technical documentation requirements is compressing registration preparation timelines for manufacturers seeking dual-market certification. The policy shift forces restructuring of clinical evidence portfolios to satisfy both jurisdictions simultaneously. Electrosurgical device categories face the steepest adaptation burden due to energy-delivery risk classification elevation under harmonized essential principles.
Aftermarket service unbundling is fragmenting traditional device procurement relationships in Queensland regional health districts. Hospitals now separately contract sterilization validation, instrument refurbishment, and tray configuration management rather than accepting bundled manufacturer packages. This pattern concentrates in facilities outside major metropolitan networks where captive logistics programs prove economically unviable.
Australia General Surgical Devices Market Segmentation
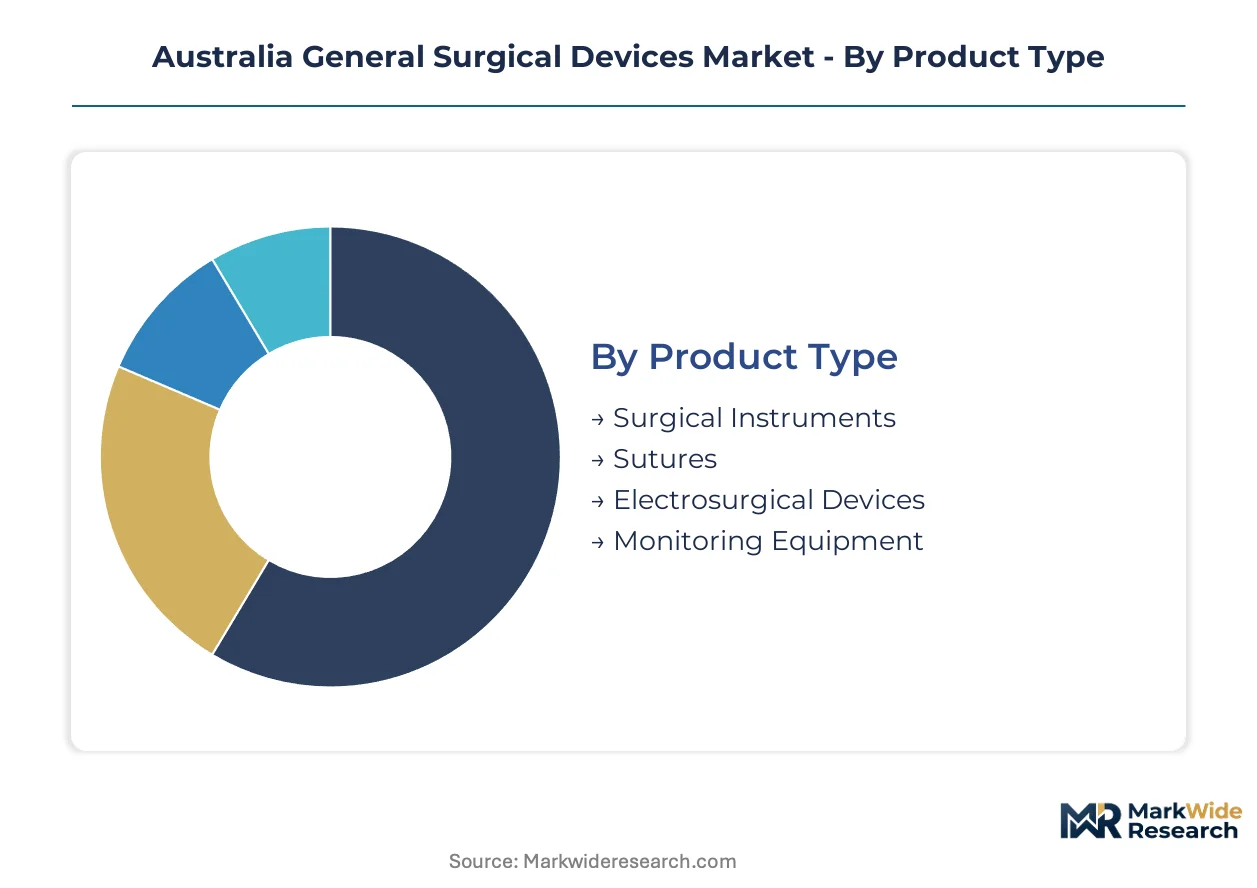
Segmentation of Australia's general surgical devices market reveals distinct procurement patterns across product categories and care settings. TGA regulatory pathways and state-level hospital network structures create divergent demand profiles that suppliers must navigate through targeted certification and service strategies.
Product Type:
Cost tier differentiation separates premium-positioned energy-delivery systems from commodity instrument sets in procurement negotiations.
- Surgical Instruments:Manually operated and powered tools manufactured from medical-grade stainless steel or titanium alloys with passivation layers. Demand concentrates in New South Wales and Victoria where major hospital networks anchor centralized purchasing agreements for reusable instrument sets.
- Sutures:Synthetic absorbable polymers and natural catgut variants for wound closure applications. Chronic wound closure needs in metropolitan Sydney and Melbourne facilities sustain volume, though synthetic materials displace natural variants in faster-healing procedures.
- Electrosurgical Devices:Energy-delivery generators with disposable electrode attachments command premium positioning through precision requirements.
- Monitoring Equipment:Perioperative patient monitoring systems integrate with broader hospital IT infrastructure.
Surgical instruments command the established base. The steepest expansion runs through electrosurgical disposable attachment models.
End User:
Customer type stratification reflects divergent capital intensity and sterilization capability across care delivery settings.
- Hospitals:Major public health clusters in New South Wales and Victoria aggregate demand through centralized procurement frameworks that bundle reusable instrument sets with service contracts.
- Ambulatory Surgical Centers:Freestanding facilities in metropolitan and regional areas accelerate procedure volumes while lacking captive sterilization infrastructure, creating dependency on third-party logistics providers.
- Specialty Clinics:Focused surgical practices concentrate in urban corridors with direct purchasing relationships for procedure-specific instrument configurations.
- Research Institutions:Academic medical centers in Sydney and Melbourne drive early adoption of smart instrument platforms with embedded tracking capabilities.
Hospitals anchor volume concentration. The steepest expansion trajectory belongs to ambulatory surgical centers.
Application:
Procedure volume distribution across surgical specialties determines instrument set turnover rates and technology investment priorities.
- General Surgery:Open and laparoscopic abdominal procedures sustain baseline demand for core instrument sets across all care settings.
- Orthopedics:Joint reconstruction and trauma fixation procedures in Victorian public hospital networks drive specialized retractor and power instrument procurement.
- Urology:Endoscopic and robotic platforms expand procedural applicability beyond traditional open techniques in metropolitan centers.
- Gynecology:Minimally invasive hysterectomy and fertility procedures concentrate in Sydney and Melbourne teaching hospitals with advanced laparoscopic capability.
General surgery maintains the procedural base. The steepest expansion runs through urology as endoscopic platforms proliferate.
Technology:
Maturity gradients separate established open techniques from capital-intensive robotic platforms in hospital capital planning cycles.
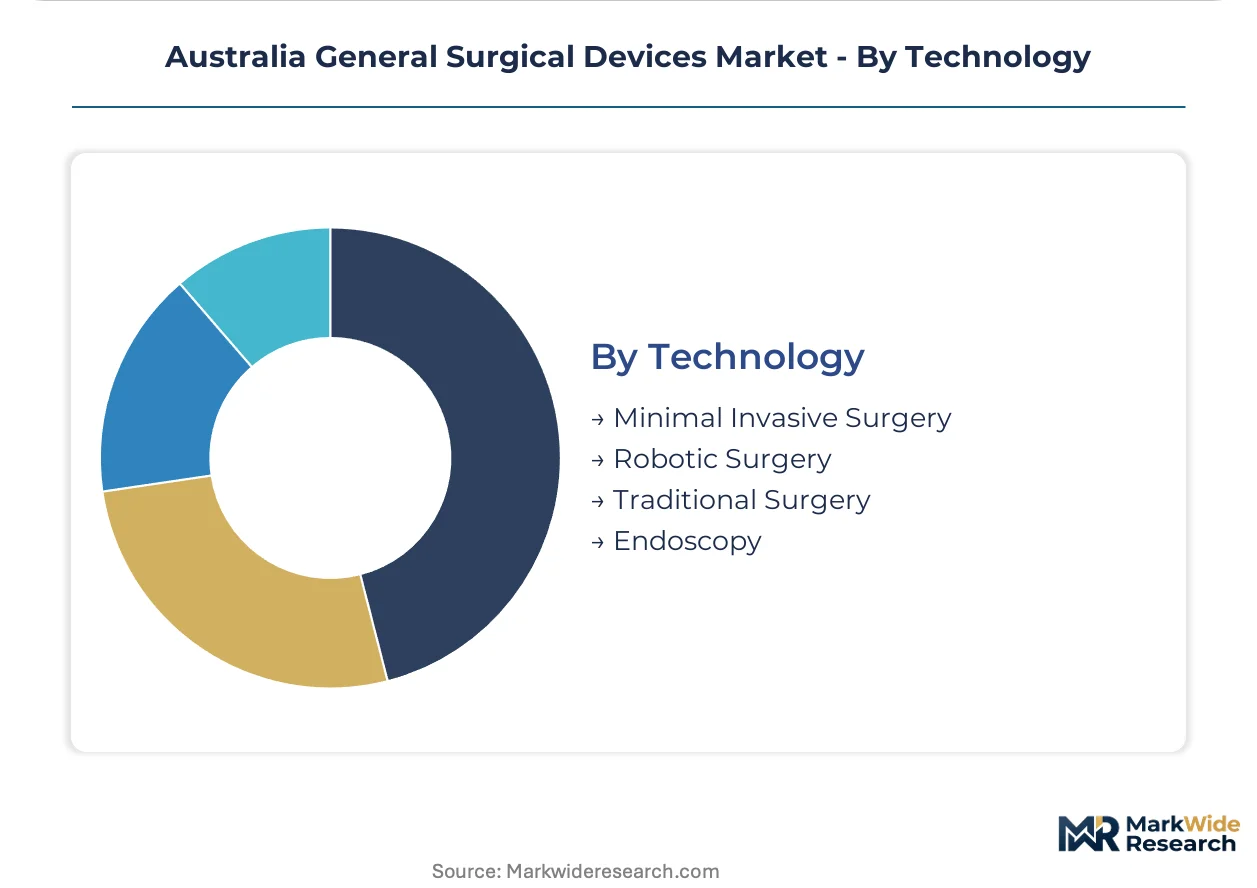
- Minimal Invasive Surgery:Laparoscopic platforms with standardized instrument sets extend procedural applicability beyond traditional open techniques, driving turnover in metropolitan hospital networks.
- Robotic Surgery:Capital-intensive da Vinci and competing systems concentrate in major public and private hospital networks with sufficient procedure volume to justify platform investment.
- Traditional Surgery:Open techniques retain dominance in regional Queensland and South Australia facilities with limited minimally invasive training pipelines.
- Endoscopy:Flexible and rigid endoscopic platforms serve diagnostic and interventional procedures across multiple specialties.
Traditional surgery holds the established volume base. The steepest expansion runs through minimal invasive surgery technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade titanium alloy supply chains and sterilization logistics networks concentrate procurement power in Australia's eastern seaboard states. TGA regulatory harmonization with EU MDR standards is compressing registration timelines for manufacturers targeting multiple jurisdictions simultaneously.
New South Wales
Sydney's major public hospital networks anchor centralized purchasing agreements for reusable instrument sets and electrosurgical generators. TGA Essential Principles compliance requirements filter lower-capability suppliers from state procurement frameworks. The Northern Beaches and Western Sydney hospital clusters are piloting smart instrument platforms with embedded RFID tracking to reduce set loss.
Victoria
Melbourne's teaching hospitals drive adoption of laparoscopic platforms with standardized instrument configurations across multiple surgical specialties. The Therapeutic Goods (Medical Devices) Regulations impose post-market surveillance obligations that elevate compliance costs for distributed product portfolios. Regional health districts in Geelong and Ballarat are unbundling aftermarket services from traditional manufacturer bundles.
Queensland
Brisbane metropolitan facilities accelerate minimally invasive procedure volumes while regional centers retain dominance of traditional open techniques. Sterile processing technician certification requirements outpace vocational training pipeline output in Cairns and Townsville hospital networks. The state's hospital procurement remains fragmented relative to New South Wales and Victoria concentration.
Western Australia
Perth metropolitan hospital procurement lacks the centralized aggregation of eastern seaboard networks, creating first-mover opportunity for integrated service providers. TGA device registration pathways impose clinical evidence thresholds that filter suppliers without dedicated regulatory affairs infrastructure. The Pilbara and Kimberley regional health services depend on third-party sterilization logistics due to limited captive infrastructure.
South Australia
Adelaide's public hospital clusters sustain baseline demand for core surgical instrument sets across general and orthopedic procedures. Post-market surveillance obligations under TGA regulations disproportionately burden mid-tier suppliers serving the state's distributed regional facilities. The Barossa Valley and Fleurieu Peninsula surgical centers are accelerating ambulatory procedure volumes without captive sterilization capability.
Australia General Surgical Devices Market Competitive Environment
Integrated service providers and standalone device manufacturers split the market between bundled procurement relationships and unbundled component sourcing. The vendor base stratifies across three tiers: multinational conglomerates with captive sterilization logistics, mid-tier specialists with regional service networks, and commodity instrument fabricators competing on price. Consolidation pressure is intensifying as TGA compliance costs rise and hospital procurement centralizes.
Among diversified medical technology conglomerates, Medtronic, Stryker, and Johnson & Johnson exemplify the integrated-service archetype that dominates premium procurement channels. These entities occupy positions where recurring maintenance contracts and tray management programs anchor long-term hospital relationships. The competitive dynamic is forcing mid-tier specialists to differentiate through procedure-specific instrument configurations or regional sterilization partnerships rather than capital equipment scale.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Stryker |
| B. Braun |
| Conmed Corporation |
| Smith & Nephew |
| 3M Healthcare |
| Integra LifeSciences |
| Others |
Value Chain & Pricing Dynamics
Medical-grade titanium alloy input volatility determines both the premium-to-economy pricing spread across electrosurgical device tiers and the geographic shape of Australian surgical device supply chains. TGA Essential Principles compliance costs compress margins for mid-tier suppliers while concentrating procurement toward ISO 13485-certified manufacturers with captive sterilization logistics.
Pricing Analysis
TGA Essential Principles dictate the pricing tier structure across Australia's general surgical devices market. Three-tier pricing separates premium electrosurgical generators with disposable attachment models from standard reusable instrument sets and economy-grade suture materials. Price differentiation rests on certification grade and after-sales service bundling rather than raw performance specifications. Cost compression in the economy tier intensifies as synthetic absorbable polymers displace natural catgut without advanced polymer extrusion capabilities. Ambulatory surgical centers exhibit the highest price sensitivity due to limited capital budgets, while major public hospital networks in New South Wales and Victoria prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
Export-control regimes on advanced medical-grade alloys and electrosurgical energy-delivery components limit technology flows into Australian manufacturing. Supply concentrates in Germany, Japan, and the United States for precision electrosurgical generators, while China and India anchor commodity instrument fabrication and suture material production. Raw material dependencies center on medical-grade titanium alloys with passivation layers, synthetic polymer feedstocks, and medical-grade stainless steel. Single-source vulnerability runs through limited Australian smelting capacity for titanium alloy processing. Distribution runs through hospital procurement frameworks, third-party sterilization logistics providers, and direct specialty clinic relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement centralization across New South Wales and Victoria hospital networks is shifting buyer power toward aggregated purchasing agreements that squeeze standalone device manufacturers. This consolidation favors integrated service providers with captive logistics infrastructure.
For Market Incumbents: Insulate recurring revenue streams by deepening tray management program penetration in regional Queensland and South Australia facilities where sterile processing technician scarcity creates dependency on outsourced sterilization logistics. Anchor hospital relationships through backward integration into refurbishment and validation services rather than competing on capital equipment price points. Tighten ISO 13485 certification maintenance to filter mid-tier competitors from state procurement frameworks.
For New Entrants and Emerging Players: Establish a beachhead in Western Australia's fragmented Perth metropolitan and regional hospital procurement environment before eastern seaboard networks fully consolidate. Target ambulatory surgical centers in Adelaide and Brisbane with third-party sterilization logistics partnerships that bypass captive infrastructure requirements. Lead with electrosurgical disposable attachment models that generate recurring revenue without demanding capital-intensive generator platform competition.
For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors vertically integrated service providers with established TGA compliance infrastructure over standalone device fabricators. Acquisition targets should display regional sterilization logistics networks or procedure-specific instrument configuration capabilities. Watch for TGA convergence with EU MDR documentation standards as the signal for accelerated consolidation among mid-tier suppliers lacking dual-market certification capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| TGA Dual-Market Certification Investment | Accelerates EU MDR alignment to capture harmonized documentation benefits for manufacturers. |
| Regional Sterilization Logistics Partnership | Addresses technician scarcity in Queensland and South Australia through outsourced captive infrastructure. |
| Smart Instrument Platform Deployment | Pilots RFID-enabled asset management in Sydney and Melbourne hospital clusters to reduce instrument set loss. |
| Western Australia First-Mover Expansion | Exploits fragmented Perth procurement relative to centralized eastern seaboard networks. |
| Electrosurgical Disposable Attachment Scale-Up | Captures recurring revenue streams from single-use electrodes without capital-intensive generator competition. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and sterilization logistics operators; and secondary validation through TGA device registration databases, hospital procurement contract disclosures, and ISO 13485 certification registries. Bottom-up triangulation across procedure volume estimates and instrument set turnover rates was cross-checked against top-down market sizing derived from state health department capital expenditure disclosures.
Forecast inputs considered product type segmentation across surgical instruments, sutures, electrosurgical devices, and monitoring equipment; end-user stratification between hospitals, ambulatory surgical centers, specialty clinics, and research institutions; and technology tiers spanning traditional, minimally invasive, robotic, and endoscopic platforms. CAGRs were derived from procedure volume elasticity modeling and capital replacement cycle analysis across the projection horizon. Industry-specific inputs included TGA registration pathway timelines and titanium alloy import price volatility indices.
Stress conditions across TGA regulatory harmonization timelines, titanium alloy supply disruptions, and sterile processing technician training pipeline output were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about procedure volume migration toward ambulatory settings and electrosurgical platform adoption curves. Material shifts in TGA-EU MDR convergence schedules or medical-grade alloy export control regimes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
Surgical Monitors Market
Medical Devices
Gastric Electrical Stimulators Market
Medical Devices
Oxygenator Market
Medical Devices
3D Printed Prosthetics Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
Global Microelectronic Medical Implants Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Global Portable Oxygen Concentrators Market