
 AI-enabled Medical Devices Market | 2026-2036
AI-enabled Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
AI-enabled Medical Devices Market Insights
Modular software-hardware bundling is rebalancing hospital procurement economics for AI-enabled medical devices. Siemens Healthineers anchors its competitive stance through proprietary imaging platforms with embedded machine learning inference engines. Medtronic leverages deep clinical data partnerships to sustain algorithm training pipelines across cardiology and diabetes monitoring segments. GE HealthCare differentiates through edge-computing architectures that reduce cloud dependency in acute care settings.
AI-enabled medical devices integrate machine learning, computer vision, or natural language processing into hardware systems for diagnostic, therapeutic, or monitoring functions, typically operating with embedded GPUs or neural processing units that execute inference at the point of care. These devices process patient-specific data to generate clinical decision support, automate image analysis, or enable robotic surgical assistance with sub-millimeter precision. Imaging systems and diagnostic tools command the largest revenue pools due to established reimbursement codes and radiologist workflow integration, while surgical instruments embedding robotics and deep learning represent the fastest-expanding margin segment as hospitals seek to standardize operative outcomes. Patient monitoring devices with predictive analytics are gaining traction in ambulatory settings where telemedicine providers require continuous remote validation.
FDA premarket notification and de novo pathways govern AI-based diagnostic software in the United States, while the EU Medical Device Regulation and AI Act impose conformity requirements on European market access. Japan's PMDA operates a parallel review track for AI-integrated imaging devices that accelerates national health insurance listing. Stakeholders must monitor evolving predicate device criteria and post-market surveillance mandates as regulatory frameworks differentiate between locked and continuously learning algorithms.
Market Dynamics
FDA premarket review pathways are compressing product development timelines while EU AI Act conformity requirements are forcing simultaneous dual-track regulatory investments, creating a structural squeeze on mid-sized device developers.
Growth Catalysts
- EU AI Act MDR convergence:The simultaneous implementation of EU AI Act and Medical Device Regulation is creating harmonized validation frameworks that reduce redundant certification cycles for imaging software developers.
- Diagnostic laboratory automation:High-throughput pathology labs are mandating AI-integrated slide scanners to address pathologist workforce shortages in tertiary care networks.
- Edge inference architectures:Neural processing units embedded directly into ultrasound and endoscopy hardware are eliminating cloud latency for intraoperative decision support.
Market Restraints
- GPU supply concentration:Taiwan-based foundry capacity constraints for specialized AI accelerators are extending lead times for embedded medical device processors.
- Training data access:HIPAA and GDPR interoperability barriers are fragmenting cross-border clinical datasets required for algorithm generalization.
- Locked algorithm predicates:FDA 510(k) pathways favor static algorithm submissions, creating compliance friction for continuously learning diagnostic models.
Strategic Opportunities
- Rural hospital networks:Federally Qualified Health Centers in the United States lack on-site radiology coverage, creating demand for teleradiology platforms with embedded AI triage.
- Atrial fibrillation monitoring:Wearable ECG patches with deep learning arrhythmia detection are penetrating ambulatory cardiology practices previously served by Holter monitors alone.
- Japan PMDA parallel review:The accelerated national health insurance listing track for AI-integrated imaging devices reduces time-to-reimbursement by eight to twelve months versus standard pathways.
Industry Challenges
- Clinical validation workforce:Shortages of biostatisticians with regulatory submission experience are extending pivotal trial design timelines for algorithm developers.
- Legacy PACS integration:Hospital picture archiving systems running decade-old DICOM implementations require expensive middleware development for AI overlay compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-enabled Medical Devices Market |
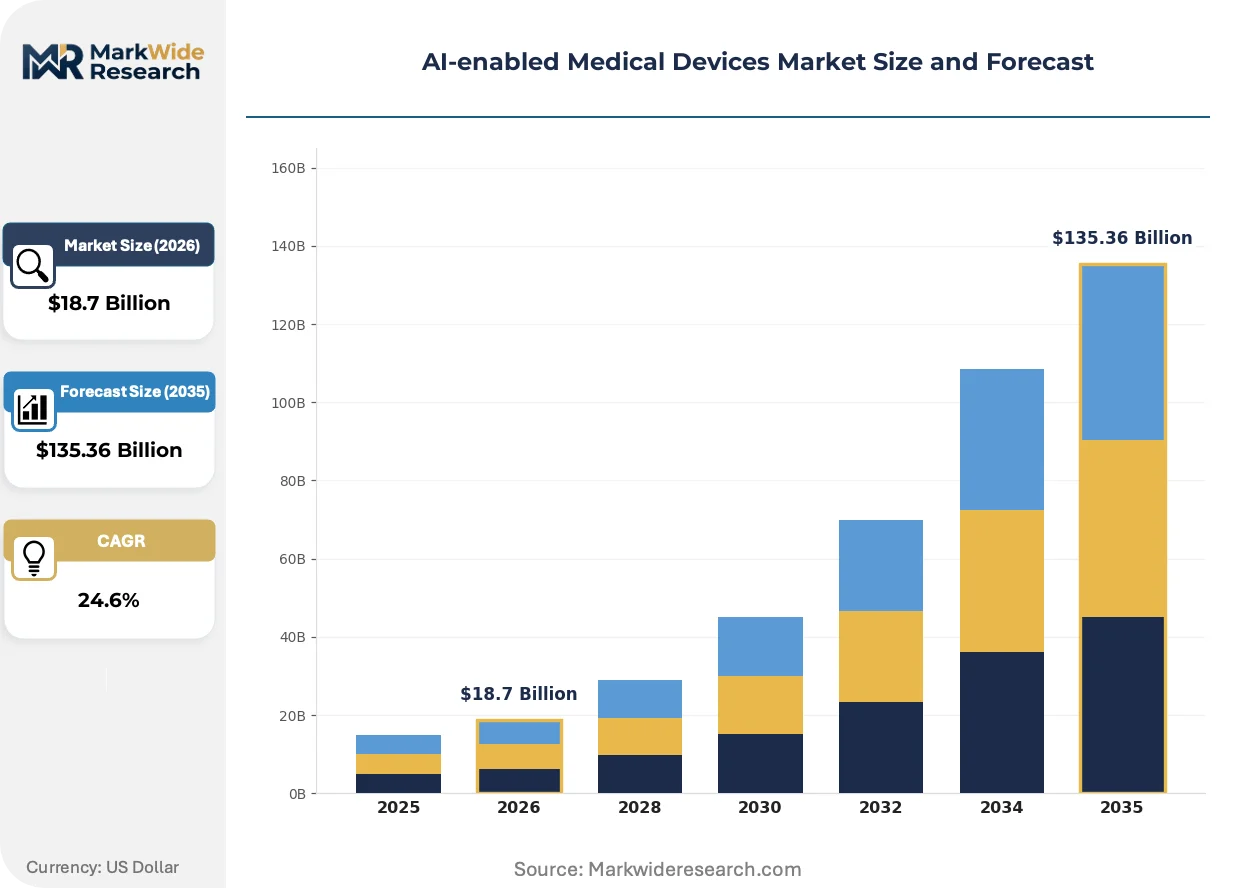
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Diagnostic Tools, Surgical Instruments, Patient Monitoring Devices, Rehabilitation Equipment Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics, Deep Learning Application: Cardiology, Oncology, Neurology, Orthopedics, Respiratory Care End User: Hospitals, Ambulatory Care Centers, Diagnostic Laboratories, Research Institutes, Telemedicine Providers |
| Companies Covered | Medtronic, Siemens Healthineers, GE HealthCare, Koninklijke Philips, Abbott, Intuitive Surgical, Boston Scientific, Stryker, Canon Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-enabled Medical Devices Market Trends and Innovations
Algorithm deployment architectures are pivoting from cloud-centric inference to hybrid edge-cloud models, while regulatory frameworks differentiate locked versus adaptive learning systems.
Federated learning infrastructure is decentralizing model training across institutional boundaries without centralizing protected health information. Academic medical centers in Germany, the United Kingdom, and the United States are deploying cross-hospital collaborative networks that train diagnostic algorithms on distributed datasets. This architecture is decentralizing competitive advantage from proprietary data ownership toward orchestration platform control.
The EU AI Act risk classification system is mandating conformity assessments for high-risk diagnostic software that were previously self-certified under MDR Class IIa pathways. Device manufacturers must now maintain post-market monitoring systems for algorithm drift and performance degradation. Cardiology imaging applications face the steepest compliance burden due to their direct impact on therapeutic decision-making.
Hospital procurement committees are unbundling AI software licenses from hardware maintenance contracts, forcing vendors toward standalone SaaS pricing models. Integrated delivery networks in the United States are negotiating enterprise-wide algorithm subscriptions that span multiple imaging modalities. This purchasing behavior is most pronounced in multi-hospital systems seeking to standardize radiology workflows across acquired community facilities.
AI-enabled Medical Devices Market Segmentation
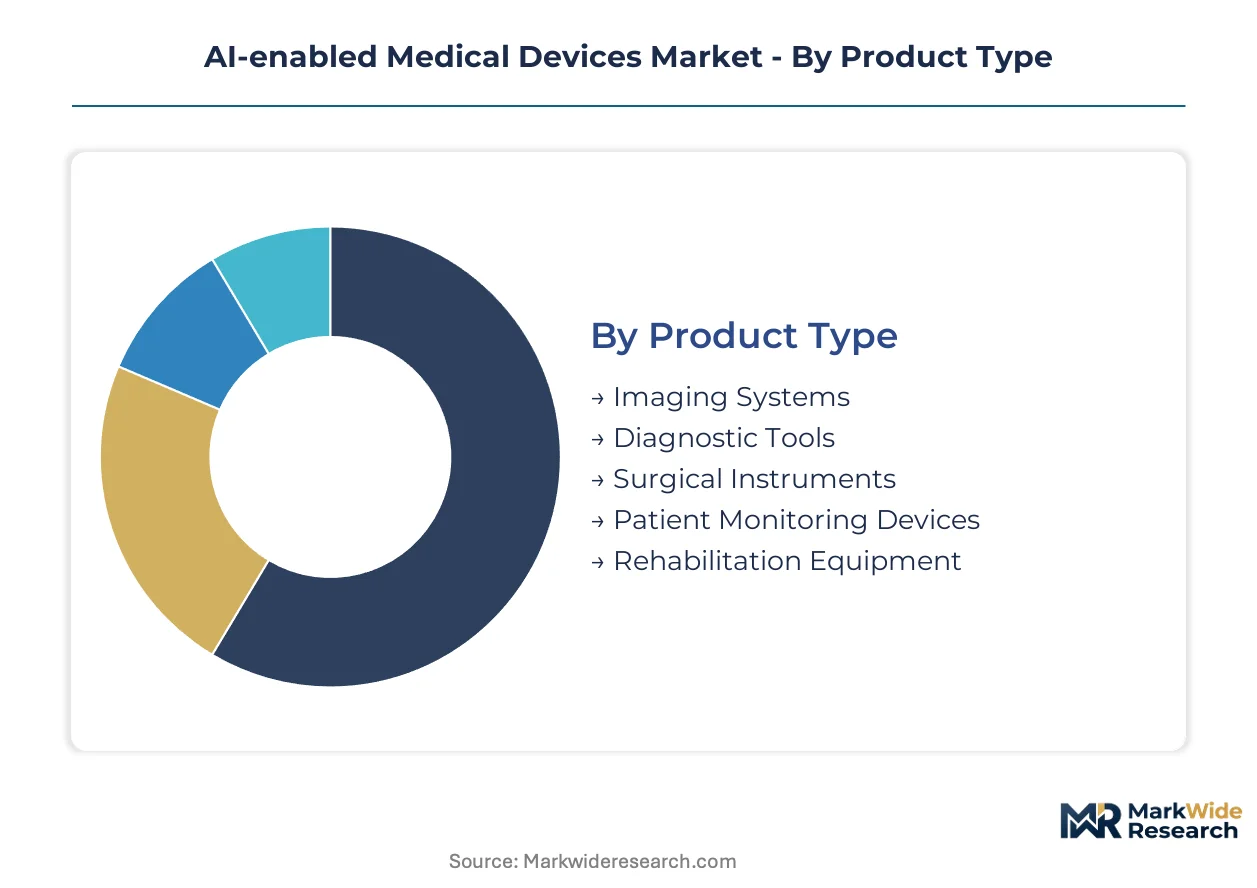
AI-enabled medical devices fragment across four dimensions that determine procurement economics and regulatory pathways. Product type governs hardware-software bundling strategies. Technology selection drives inference architecture decisions. Application focus shapes clinical validation requirements. End user category determines pricing models and distribution channels.
Product Type:
Hospital procurement committees evaluate capital intensity against workflow integration depth when selecting across device categories.
- Imaging Systems:Embedded GPUs execute real-time inference on CT, MRI, and X-ray modalities. Siemens Healthineers and GE HealthCare dominate procurement at German university hospital networks seeking radiologist workload reduction.
- Diagnostic Tools:AI-integrated slide scanners and pathology analyzers process tissue samples with computer vision algorithms. High-throughput laboratories in the United States mandate these systems to address pathologist workforce shortages.
- Surgical Instruments:Robotic platforms with deep learning guidance achieve sub-millimeter precision in operative settings.
- Patient Monitoring Devices:Wearable ECG patches and continuous glucose monitors deploy predictive analytics for ambulatory validation.
- Rehabilitation Equipment:Motion-sensing prosthetics and exoskeletons adapt to patient biomechanics through sensor fusion.
Volume sits with Imaging Systems; growth tilts toward Surgical Instruments.
Technology:
Regulatory frameworks differentiate locked algorithm submissions from continuously learning systems, compressing development timelines for static architectures.
- Machine Learning:Supervised classification algorithms trained on curated clinical datasets generate diagnostic probabilities. FDA 510(k) pathways favor these locked implementations over adaptive alternatives.
- Computer Vision:Convolutional neural networks segment anatomical structures in radiological images. Edge-computing deployments eliminate cloud latency for intraoperative decision support.
- Deep Learning:Multi-layer neural architectures extract patterns from unstructured clinical data.
- Natural Language Processing:Clinical documentation algorithms parse unstructured physician notes into structured diagnostic codes.
- Robotics:Kinematic control systems integrate haptic feedback with predictive trajectory planning.
Deployment concentrates on Machine Learning; regulatory momentum favors Computer Vision.
Application:
Reimbursement code availability and specialist workforce density determine adoption velocity across clinical domains.
- Cardiology:AI-integrated echocardiography and ECG analysis automate ejection fraction calculation and arrhythmia detection. Ambulatory practices in the United States replace Holter monitors with wearable deep learning patches.
- Oncology:Tumor segmentation algorithms quantify treatment response on serial imaging studies. Academic medical centers deploy these tools to standardize multidisciplinary tumor board workflows.
- Neurology:Stroke detection algorithms prioritize CT scan interpretation in emergency departments.
- Orthopedics:Implant sizing algorithms automate preoperative planning from radiographic measurements.
- Respiratory Care:Ventilator weaning prediction models optimize intensive care resource allocation.
Investment flows heaviest into Cardiology; Oncology climbs fastest on precision medicine tailwinds.
End User:
Purchasing authority and technical integration capacity separate institutional buyers across the care continuum.
- Hospitals:Integrated delivery networks negotiate enterprise-wide algorithm subscriptions spanning multiple imaging modalities. United States multi-hospital systems standardize radiology workflows across acquired community facilities.
- Diagnostic Laboratories:High-throughput pathology operations mandate AI-integrated slide scanners. Tertiary care networks in Germany expand procurement to reduce pathologist examination burden.
- Ambulatory Care Centers:Point-of-care ultrasound with embedded inference targets rural access gaps.
- Telemedicine Providers:Remote patient monitoring platforms require continuous algorithm validation for asynchronous diagnosis.
- Research Institutes:Federated learning infrastructure enables cross-institutional model training without centralizing protected health information.
Revenue concentrates at Hospitals; expansion tilts toward Diagnostic Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of AI-enabled medical devices concentrates in Germany, Japan, and the United States where precision manufacturing ecosystems intersect with regulatory validation infrastructure. Consumption spreads across tertiary hospital networks in these markets plus diagnostic laboratory expansions in India and China.
United States
FDA premarket notification pathways compress development timelines for locked algorithm submissions. Federally Qualified Health Centers drive demand for teleradiology platforms with embedded AI triage. Boston and San Francisco anchor venture deployment into surgical robotics and cardiology monitoring segments.
Germany
Siemens Healthineers and university hospital networks build dedicated AI validation centers across Bavaria and Baden-Württemberg. EU AI Act and MDR convergence creates harmonized certification frameworks for imaging software developers. Erlangen and Munich cluster embedded GPU manufacturing for CT and MRI inference engines.
Japan
PMDA parallel review tracks accelerate national health insurance listing by eight to twelve months versus standard pathways. METI funding targets edge-computing architectures for intraoperative decision support. Tokyo and Osaka metropolitan hospitals standardize AI-integrated echocardiography procurement.
China
NMPA regulatory pathways for AI-based diagnostic software reshape product development timelines for domestic developers. Tertiary hospital networks in Beijing and Shanghai expand procurement of pathology analyzers with computer vision algorithms. Yangtze River Delta manufacturing clusters scale neural processing unit production for ultrasound hardware.
India
CDSCO regulatory harmonization efforts align with ISO standards for imported imaging systems. Diagnostic laboratory chains in Maharashtra and Karnataka mandate AI-integrated slide scanners to address pathologist workforce shortages. Hyderabad and Bengaluru clusters develop middleware for legacy PACS integration.
AI-enabled Medical Devices Market Competitive Landscape
The competitive structure tilts toward diversified medtech conglomerates with captive imaging platforms and embedded machine learning inference engines. Three archetypes dominate: integrated imaging system vendors bundling hardware-software stacks, surgical robotics specialists deploying deep learning guidance, and diagnostic tool developers targeting high-throughput laboratory automation. M&A activity concentrates on algorithm startups with FDA-cleared predicates, while strategic partnerships secure exclusive clinical data access for training pipeline continuity.
Among diversified conglomerates, Medtronic, Siemens Healthineers, and GE HealthCare occupy positions spanning cardiology monitoring, diagnostic imaging, and edge-computing architectures respectively. Medtronic represents the clinical data partnership archetype through deep algorithm training relationships across therapeutic segments. Siemens Healthineers exemplifies proprietary platform control with embedded inference engines anchoring radiologist workflow integration. GE HealthCare sits within the edge-computing specialization, reducing cloud dependency for acute care settings through hardware-embedded neural processing.
| Leading Market Players |
|---|
| Medtronic |
| Siemens Healthineers |
| GE HealthCare |
| Koninklijke Philips |
| Abbott |
| Intuitive Surgical |
| Boston Scientific |
| Stryker |
| Canon Medical Systems |
| Others |
Pricing and Supply Chain Analysis
Edge-computing migration in ultrasound and endoscopy hardware is compressing cloud infrastructure costs while concentrating GPU and neural processing unit procurement leverage among Taiwan-based foundry customers. This technology shift simultaneously elevates upfront device premiums and locks hospital buyers into long-term service dependencies.
Pricing Analysis
Margin tightening in mid-tier imaging systems reflects unbundling of AI software licenses from hardware maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA predicate tier and radiologist workflow integration depth. Cost-down pressure on standalone SaaS subscriptions accelerates because integrated delivery networks negotiate enterprise-wide algorithm volumes. Federally Qualified Health Centers exhibit highest price sensitivity; German university hospital networks show lowest due to dedicated AI validation center funding.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale hospital network demand while distributor relationships serve mid-sized ambulatory chains. GPU and neural processing unit fabrication concentrates in Taiwan, South Korea, and Japan. Embedded medical device processors draw from specialized AI accelerator foundry capacity constrained by consumer electronics demand. Single-source vulnerability in Taiwan-based wafer supply creates procurement risk. Distribution runs through authorized medtech distributors with FDA establishment registration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI-enabled medical devices market functions as a cost-of-compliance arena where EU AI Act conformity assessments erect barrier-to-entry moats favoring incumbents with established post-market surveillance infrastructure.
For Market Incumbents: Lock in radiologist workflow integration through proprietary PACS middleware development, defending against cloud-native diagnostic startups. Deepen clinical data partnerships with academic medical centers to sustain algorithm training pipeline continuity. Prioritize FDA 510(k) predicate accumulation to accelerate regulatory pathways for adjacent modalities. For New Entrants and Emerging Players: Enter via Federally Qualified Health Center teleradiology platforms where radiologist coverage gaps create immediate AI triage demand. Target rural hospital networks in the United States with point-of-care ultrasound embedding neural processing units. Pursue software-only SaaS pricing to bypass capital-intensive hardware certification cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified medtech conglomerates seeking FDA-cleared algorithm predicates. Long-term viability hinges on orchestration platform control within federated learning networks rather than proprietary data ownership. Watch Japan PMDA parallel review track expansion as inflection signal for accelerated reimbursement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Locked algorithm predicates accelerate 510(k) clearance for imaging software developers. |
| Hospital System Partnership | Exclusive clinical data access secures training pipeline continuity for cardiology algorithms. |
| Software Companion Development | SaaS unbundling from hardware captures recurring revenue from integrated delivery networks. |
| CE Marking Pathway | EU AI Act high-risk conformity assessments open premium pricing for compliant diagnostics. |
| Reimbursement Strategy | Japan PMDA parallel review reduces time-to-reimbursement for AI-integrated echocardiography. |
Research Methodology
Independent corroboration across hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork with Siemens Healthineers and GE HealthCare procurement stakeholders intersects with secondary validation from FDA 510(k) databases, EU MDR notified body records, and hospital procurement databases. Bottom-up algorithm deployment estimates triangulate against top-down imaging system shipment data.
Comparable-period anchoring to historical FDA clearance volumes and reimbursement code expansions establishes the forecast baseline across the analysis window. Segmentation modeling incorporates product type, technology architecture, clinical application, and end-user purchasing authority. CAGR derivation rests on neural processing unit penetration curves and radiologist workforce shortage projections. Federated learning infrastructure deployment and EU AI Act implementation timelines feed scenario weighting.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Taiwan foundry capacity constraints and HIPAA-GDPR interoperability barriers. Projections reflect assumptions regarding locked versus continuously learning algorithm regulatory differentiation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Devices Market
Medical Devices
Mediastinoscope Market
Medical Devices
Global Vein Finders Market
Medical Devices
US Nurse Call Systems Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Non-Magnetic Wheelchair Market
Medical Devices
US Medical Bionic Implants & Artificial Organs Market
Medical Devices
EMG Biosensors Market
Medical Devices
Non-Invasive Pulse Oximeter Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Point of Care Ultrasound Systems Market
Medical Devices
South Africa General Surgical Devices Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Aortic Cannula Systems Market
Medical Devices
Thyroid Ablation Devices Market