
 Oman Transportation Infrastructure Construction Market | 2026-2036
Oman Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Transportation Infrastructure Construction Market Analytics
Premium-grade concrete specifications for marine-exposed bridge decks is unwinding traditional procurement patterns across Oman. Bechtel leverages its experience on complex port infrastructure to secure design-build contracts for coastal resilience projects. Galfar Engineering and Contracting SAOG anchors the domestic contractor landscape through its integrated quarry-to-pavement operations across northern Oman. STRABAG SE competes on European-standard tunneling methodologies adapted to Oman's fractured limestone geology.
Oman transportation infrastructure construction encompasses the planning, engineering, and physical assembly of roadway, bridge, tunnel, and railway systems using asphalt, concrete, steel, and aggregate materials, typically designed for 50-100 year service lives under extreme thermal cycling and salt-laden coastal exposure. Its primary purpose is to enable freight logistics, passenger mobility, and economic zone connectivity across a 309,500-square-kilometer territory with low population density. Roadway projects dominate current award volumes, reflecting government prioritization of last-mile industrial connectivity over intercity rail. Sustainable materials adoption within concrete and asphalt segments is expanding fastest, driven by carbon-reduction mandates embedded in public tender evaluations. Smart traffic management technology remains nascent but carries concentrated margin pools where bundled with long-term operations contracts.
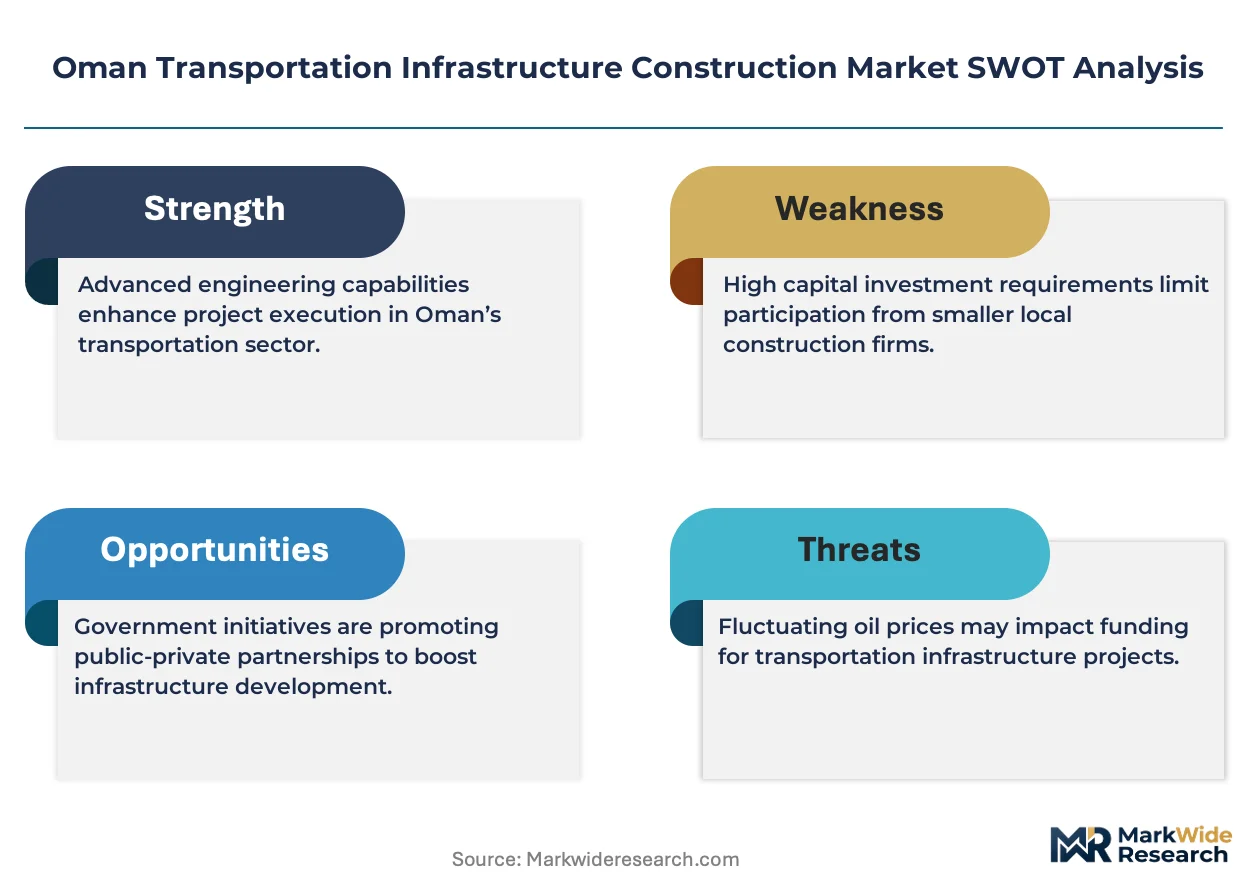
The Ministry of Transport, Communications and Information Technology and the Ministry of Housing and Urban Planning jointly enforce construction standards that mandate seismic resilience ratings and environmental impact assessments for projects exceeding specified thresholds. Oman Vision 2040 implementation directives require infrastructure procurements to incorporate local content requirements and workforce development provisions, reshaping contractor qualification criteria. Stakeholders must monitor how evolving green building certification alignment with international frameworks affects material sourcing decisions and subcontractor tier eligibility.
Market Dynamics
The Ministry of Transport, Communications and Information Technology's carbon-reduction mandates embedded in public tender evaluations are compressing material procurement cycles and disqualifying traditional concrete suppliers across Oman's coastal corridor.
Growth Catalysts
- Duqm Special Economic Zone expansion:Integrated road-rail-bridge networks are attracting state-backed developers to the Batinah coastal corridor. Industrial zone connectivity requirements are accelerating project awards.
- Oman Vision 2040 local content mandates:Infrastructure procurements now incorporate workforce development provisions that reshape contractor qualification criteria. Domestic quarry-to-pavement operations gain preferential status.
- Premium-grade marine concrete specifications:Updated building codes for salt-laden coastal exposure are unwinding traditional procurement patterns. Contractors with coastal resilience experience secure design-build contracts.
Market Restraints
- Limestone geology complexity:Fractured subsurface conditions across northern Oman require specialized European-standard tunneling methodologies. Adaptation costs constrain contractor entry.
- Aggregate supply concentration:Domestic quarry operations anchor the northern governorates, leaving southern regions dependent on extended haul distances. Transportation costs inflate project budgets.
- Seismic resilience retrofit requirements:Joint Ministry standards mandate upgraded ratings for existing infrastructure. Compliance timelines delay new project initiations.
Strategic Opportunities
- Smart traffic management bundling:Nascent technology adoption carries concentrated margin pools where combined with long-term operations contracts. State developers seek integrated service providers.
- Sustainable asphalt innovation:Carbon-reduction mandates are expanding fastest in materials segments. Recycled content specifications create white space for specialized mix producers.
- Al Wusta governorate connectivity gaps:Low population density territories require freight logistics solutions. Last-mile industrial roads present underpenetrated award volumes.
Industry Challenges
- Extreme thermal cycling certification:50-100 year service life specifications demand accelerated durability testing protocols. Laboratory capacity constraints extend pre-qualification timelines.
- Subcontractor tier eligibility:Green building certification alignment with international frameworks affects material sourcing decisions. Domestic suppliers face documentation gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Transportation Infrastructure Construction Market |
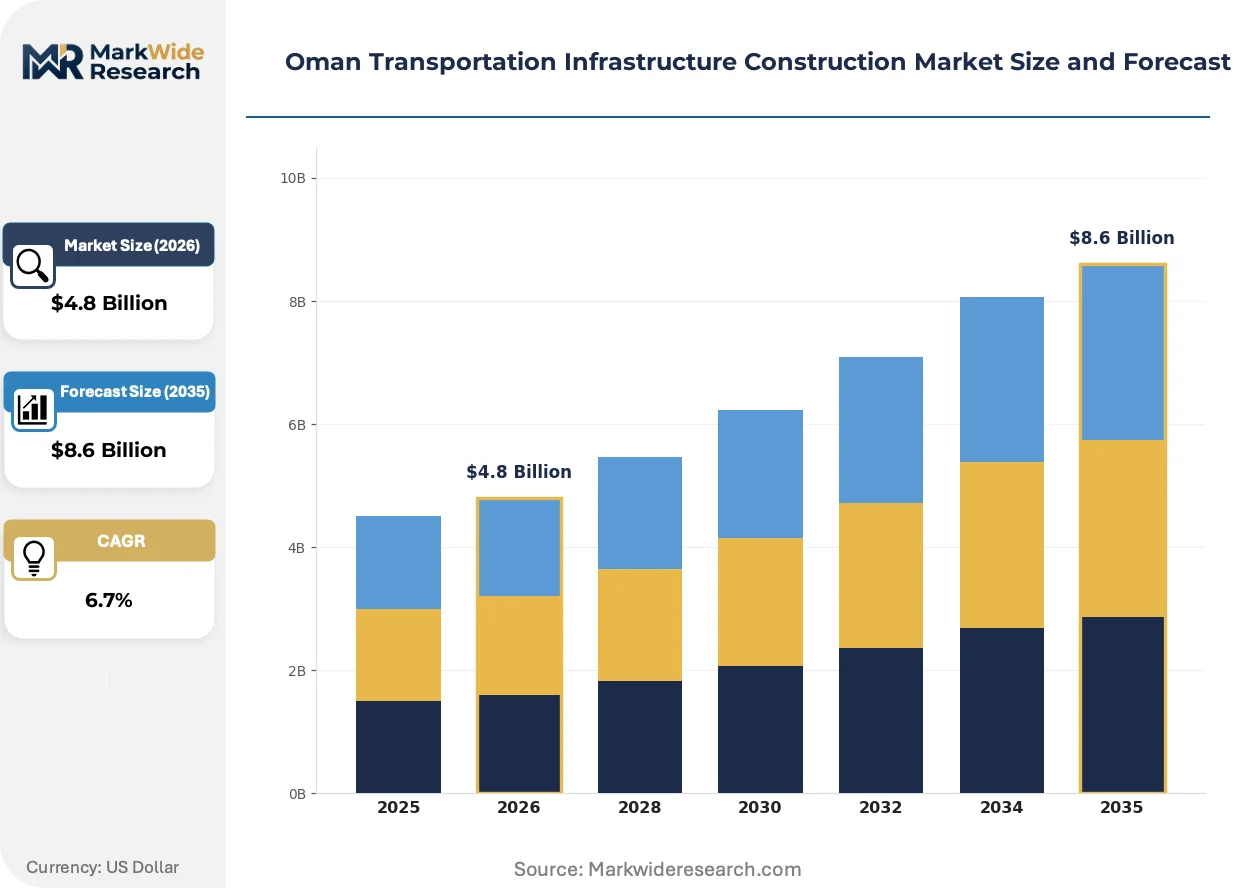
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roadway, Bridge, Tunnel, Railway Material: Asphalt, Concrete, Steel, Aggregate Technology: Smart Traffic Management, Construction Robotics, Sustainable Materials, Geospatial Analysis End User: Government, Contractors, Civil Engineers, Private Developers |
| Companies Covered | Bechtel, Consolidated Contractors Company, Galfar Engineering and Contracting SAOG, Hill International, STFA Group, Desert Line Group, Khalid Bin Ahmed & Sons LLC, Doğuş Construction, STRABAG SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Transportation Infrastructure Construction Market Evolving Landscape
Sensor-embedded infrastructure monitoring systems are compressing maintenance cycles and enabling predictive intervention across Oman's highway networks. Material science advances and regulatory stringency are converging to reshape competitive positioning.
Self-healing concrete formulations containing bacterial spores and microcapsulated healing agents are penetrating bridge deck specifications. The Ministry of Transport, Communications and Information Technology is mandating their inclusion in marine-exposed structures. This technology is miniaturizing repair intervention requirements and extending inspection intervals for critical coastal crossings.
Oman Vision 2040 implementation directives now require environmental impact assessments for projects exceeding specified investment thresholds. The Ministry of Housing and Urban Planning enforces these through joint construction standards. Contractors are restructuring pre-bid teams to integrate sustainability certification expertise.
Design-build-operate-maintain contracts are displacing traditional lump-sum awards for major corridor projects. State-backed developers in the Batinah region are bundling 15-20 year service obligations with initial construction. This compresses contractor selection criteria toward balance sheet strength and asset management capabilities rather than construction cost alone.
Oman Transportation Infrastructure Construction Market Segmentation
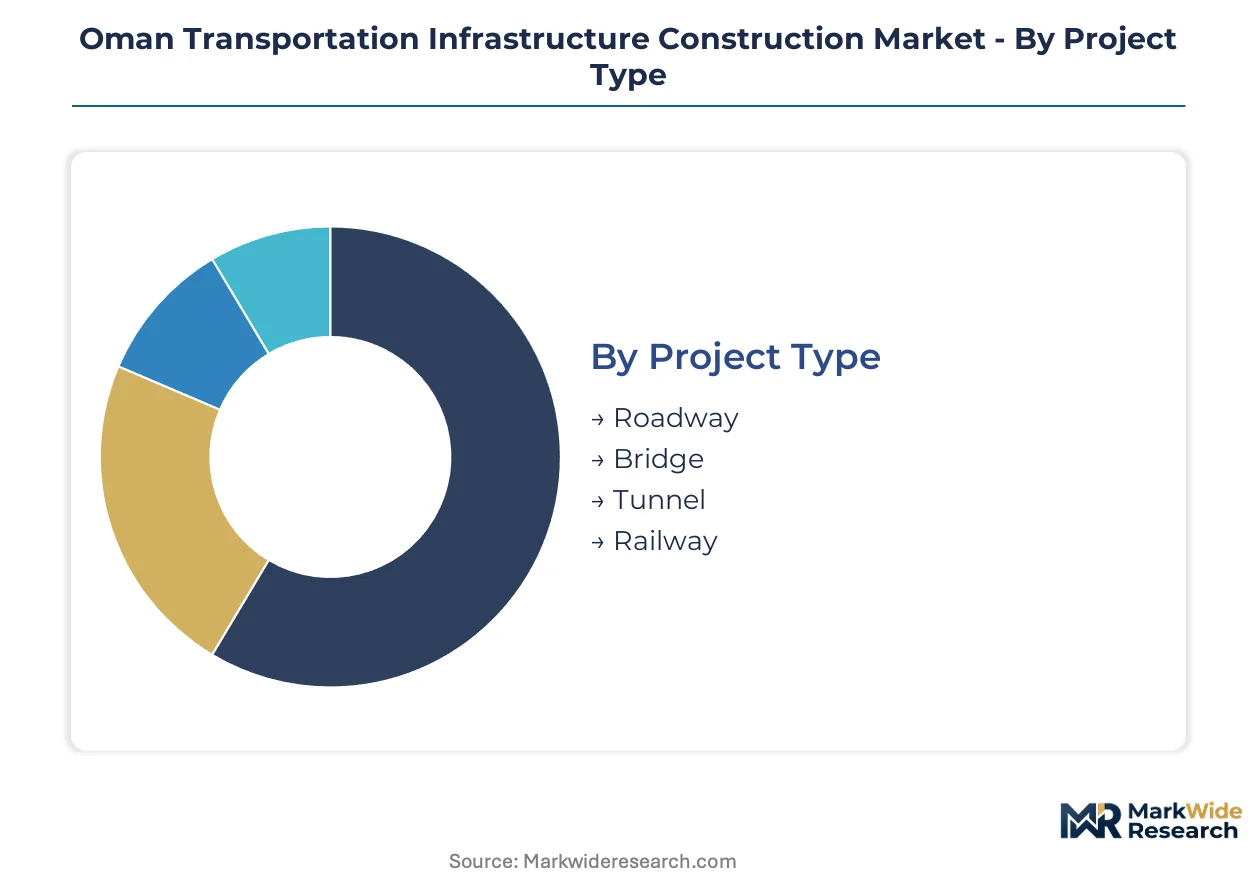
Segmentation reveals how Oman transportation infrastructure construction procurement channels fragment across project scale, material specifications, and technology adoption maturity. Understanding these divisions exposes where contractor qualification criteria tighten and where margin pools concentrate.
Project Type:
Roadway construction faces the strongest substitution pressure from railway alternatives as Oman Vision 2040 prioritizes freight corridor efficiency over highway expansion.
- Roadway:Asphalt and concrete pavement systems designed for 50-100 year service lives under extreme thermal cycling. Demand concentrates in the Batinah coastal corridor and Duqm Special Economic Zone last-mile connectivity, driven by industrial zone logistics requirements and Ministry of Transport procurement prioritization.
- Bridge:Marine-exposed reinforced concrete and steel superstructures requiring salt-laden corrosion resistance. Award volumes cluster along coastal freight corridors where wadi crossings and port access links demand elevated spans, constrained by updated seismic resilience mandates from joint Ministry standards.
- Tunnel:Fractured limestone excavation using European-standard methodologies adapted to northern Oman geology. Specialized contractors command premium positioning where mountain crossings shorten corridor distances.
- Railway:Integrated road-rail-bridge networks for freight logistics across low-density territories. Nascent segment awaiting major capital commitment beyond feasibility studies.
Roadway anchors the volume base while bridge gains share at the steepest rate.
Material:
Cost tier stratification separates premium-grade marine specifications from standard inland applications, with carbon-reduction mandates reshaping procurement eligibility.
- Concrete:Portland cement-based formulations with bacterial spore and microcapsulated healing agents for self-healing properties. Premium grades penetrate bridge deck specifications under Ministry mandates for marine-exposed structures, displacing traditional suppliers lacking durability certification.
- Asphalt:Bituminous binders with recycled content specifications expanding fastest under carbon-reduction tender evaluations. Sustainable mix innovation creates white space for specialized producers in coastal corridor projects.
- Steel:Reinforcing bar and structural sections for bridge superstructures and tunnel support systems. Import dependency constrains domestic availability for seismic-grade specifications.
- Aggregate:Crushed limestone and gabbro from northern governorate quarries. Supply concentration leaves southern regions exposed to extended haul distances and transportation cost inflation.
Concrete dominates award volumes while sustainable asphalt climbs the fastest.
Technology:
Application maturity varies sharply, with bundled long-term operations contracts determining where technology margins concentrate.
- Smart Traffic Management:Sensor-embedded monitoring systems enabling predictive intervention across highway networks. Nascent adoption carries concentrated margin pools where state developers bundle 15-20 year service obligations with construction.
- Sustainable Materials:Recycled content and low-carbon formulations aligned with Oman Vision 2040 environmental impact thresholds. Fastest-expanding technology segment driven by public tender evaluation criteria.
- Construction Robotics:Automated earthmoving and paving equipment for precision grading and compaction. Limited penetration constrained by workforce development provisions favoring local labor content.
- Geospatial Analysis:LiDAR and drone-based survey for fractured limestone tunnel alignment. Specialized service tier supporting pre-feasibility and design phases.
Sustainable materials anchors procurement mandates while smart traffic management expands most quickly.
End User:
Customer type determines contract structure, with design-build-operate-maintain awards displacing traditional lump-sum arrangements for state-backed corridors.
- Government:Ministry of Transport, Communications and Information Technology and Ministry of Housing and Urban Planning as primary procuring entities. Joint standards enforcement and carbon-reduction mandates reshape contractor qualification.
- Contractors:Design-build and construction management firms executing physical assembly. Balance sheet strength and asset management capabilities now outweigh construction cost in selection criteria.
- Civil Engineers:Technical advisory and sustainability certification expertise integrated into pre-bid teams. Required for environmental impact assessment compliance on threshold-exceeding projects.
- Private Developers:Industrial zone and special economic zone stakeholders requiring last-mile connectivity. Secondary volume relative to state-led procurement.
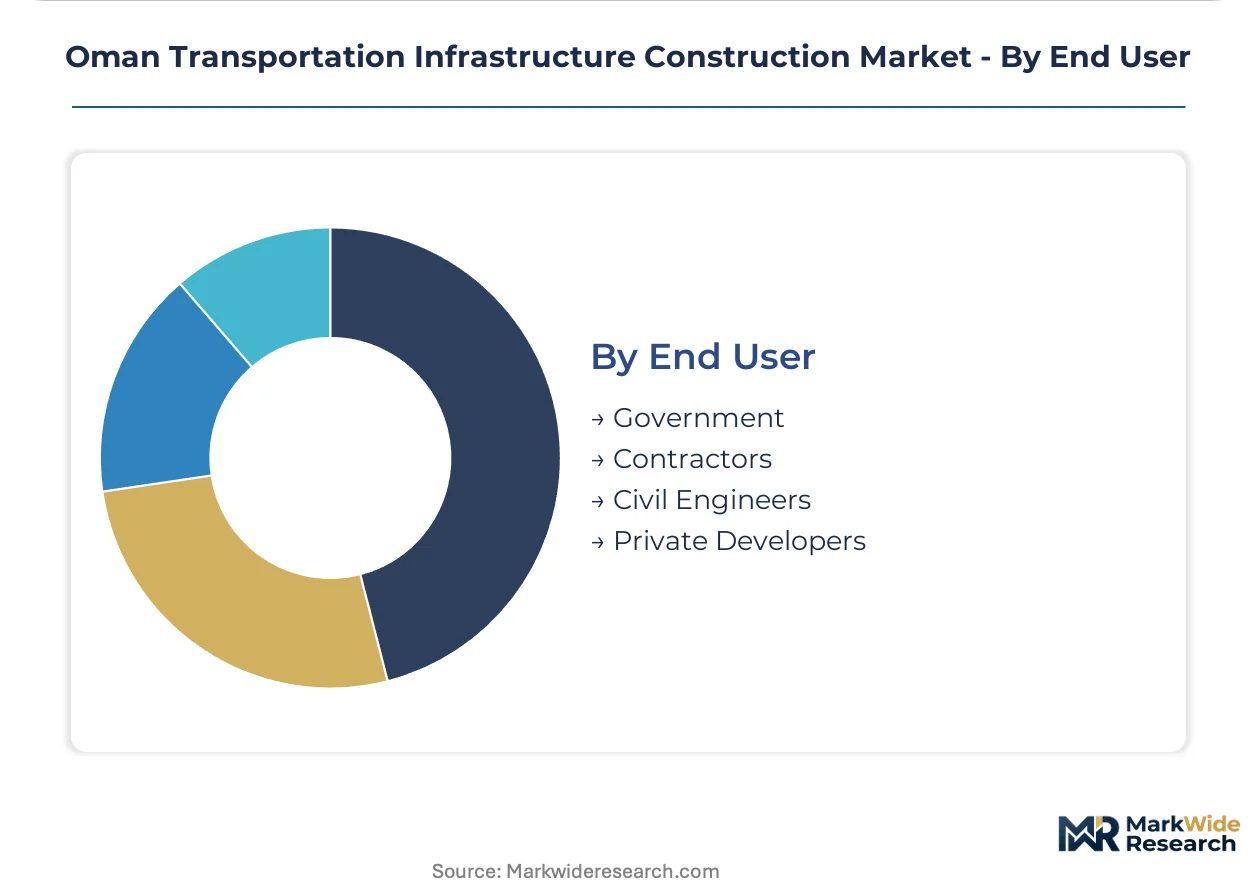
Government procurement anchors the award pipeline while contractors face the steepest qualification restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oman's transportation infrastructure construction sector exhibits pronounced regional variation, with project awards clustering where industrial zones and export corridors demand integrated connectivity solutions. The Ministry of Transport, Communications and Information Technology directs procurement toward governorates serving maritime trade gateways.
Muscat Governorate
Port Sultan Qaboos modernization and container terminal expansion drive bridge and roadway awards along the capital's coastal corridor. Joint Ministry standards enforce seismic resilience ratings for all threshold-exceeding projects. The Seeb-Muttrah industrial cluster concentrates design-build contracts for last-mile freight connectivity.
Al Batinah North and South
Sohar Port hinterland development and the Batinah coastal highway upgrade anchor the highest award volumes nationwide. Oman Vision 2040 local content mandates reshape contractor qualification, privileging domestic quarry-to-pavement operations. The Sohar Industrial City zone generates sustained demand for heavy-haul roadway specifications.
Al Wusta Governorate
Duqm Special Economic Zone expansion commands integrated road-rail-bridge networks across this sparsely populated territory. Carbon-reduction mandates embedded in public tender evaluations compress material procurement cycles. The Duqm port and refinery complex attracts state-backed developers seeking bundled long-term operations contracts.
Dhofar Governorate
Salalah Port connectivity improvements and cross-border freight corridors to Yemen drive selective project awards. Aggregate supply concentration in northern governorates inflates transportation costs for southern construction budgets. The Salalah Free Zone generates intermittent demand for industrial access roads.
Ad Dakhiliyah Governorate
Mountain crossing tunnels and wadi-spanning bridges dominate this interior region's project pipeline. Fractured limestone geology requires specialized European-standard tunneling methodologies. The Nizwa-Bahla corridor exemplifies where shortened route distances justify premium construction techniques.
Oman Transportation Infrastructure Construction Market Competitive Landscape
Concentration sits with integrated domestic contractors possessing captive aggregate supply and state-backed developers leveraging international design-build expertise. The vendor base stratifies across three tiers: global engineering firms executing complex port and marine infrastructure, regional specialists adapting European methodologies to local geology, and domestic quarry-integrated operators capturing volume-driven roadway awards. Competitive dynamics center on design-build-operate-maintain contract conversion and sustainability certification integration into pre-bid teams.
Within the global engineering tier, Bechtel represents design-build capability for coastal resilience projects, while STRABAG SE occupies a position among European-standard tunneling specialists. Galfar Engineering and Contracting SAOG anchors the domestic integrated tier, exemplifying quarry-to-pavement vertical control that Oman Vision 2040 local content mandates privilege.
| Leading Market Players |
|---|
| Bechtel |
| Consolidated Contractors Company |
| Galfar Engineering and Contracting SAOG |
| Hill International |
| STFA Group |
| Desert Line Group |
| Khalid Bin Ahmed & Sons LLC |
| Doğuş Construction |
| STRABAG SE |
| Others |
Value Network & Pricing Analysis
Premium-grade marine concrete specifications replacing standard inland formulations are simultaneously shifting aggregate sourcing toward northern governorate quarries and compressing margins for contractors lacking durability certification. This substitution dynamic concentrates procurement power with domestic quarry-integrated operators while disqualifying traditional suppliers from coastal corridor awards.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across Oman's transportation infrastructure sector. Three-tier pricing stratification separates premium marine-grade concrete certified for salt-laden exposure from standard highway specifications and economy-grade inland applications. Cost compression in standard-tier awards is intensifying because carbon-reduction mandates embedded in Ministry of Transport tender evaluations disqualify uncertified suppliers. State-backed developers exhibit lowest price sensitivity due to long-term operations contract bundling, while private industrial zone stakeholders remain most cost-conscious on last-mile connectivity projects.
Supply Chain Analysis
Strategic stockpiling of limestone aggregate dominates contractor inventory strategy across northern Oman, where quarry-integrated operators maintain captive supply buffers against haul-distance inflation. Domestic production draws from Al Batinah North and South governorates, with import dependency for seismic-grade steel reinforcing bar creating single-source vulnerability from South Korean and Japanese mills. Distribution runs through state-backed developer procurement portals for major corridor projects, supplemented by direct contractor-quarry relationships for volume-driven roadway awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's transportation infrastructure sector is approaching a platform-economics inflection where design-build-operate-maintain contract structures reward ecosystem orchestration over pure construction capability. Interoperability between smart traffic management systems and long-term asset monitoring platforms is reshaping competitive boundaries.
For Market Incumbents: Shield core quarry-to-pavement operations by securing exclusive aggregate supply agreements with northern governorate license holders before Oman Vision 2040 local content mandates tighten further. Invest in bacterial spore concrete certification to defend against Bechtel-led coastal resilience entrants displacing traditional marine suppliers.
For New Entrants and Emerging Players: Anchor in Al Wusta governorate connectivity gaps where Duqm Special Economic Zone expansion generates underpenetrated award volumes for freight logistics solutions. Target sustainable asphalt innovation as the fastest-expanding materials segment, leveraging recycled content specifications to bypass incumbent concrete dominance.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with European tunneling specialists possessing STRABAG SE-equivalent fractured limestone methodologies but lacking Omani joint venture structures. Monitor Ministry of Transport carbon-reduction mandate enforcement intensity as the inflection signal determining whether sustainable materials certification becomes table stakes or competitive differentiator.
| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build-Operate-Maintain Contract Conversion | Bundles 15-20 year service obligations with construction, favoring balance sheet strength over cost alone. |
| Backward Integration into Aggregate Supply | Captive quarry operations gain preferential status under Oman Vision 2040 local content mandates. |
| Self-Healing Concrete Certification Investment | Ministry mandates for marine-exposed structures displace traditional suppliers lacking bacterial spore expertise. |
| Smart Traffic Management Platform Development | Nascent adoption carries concentrated margins where bundled with long-term operations contracts. |
| Sustainable Asphalt Mix Innovation | Recycled content specifications create white space for specialized producers in carbon-reduction tender evaluations. |
Research Methodology
Desk research of Ministry of Transport procurement databases, Oman Vision 2040 implementation directives, and joint Ministry construction standards preceded structured interviews with project directors at state-backed developers, quarry operations managers, and design-build contract specialists. Secondary validation drew from tender award records, environmental impact assessment filings, and contractor pre-qualification documentation. Bottom-up project pipeline enumeration triangulated against top-down governorate-level investment allocation data.
Variance decomposition across project type, material specification, and technology adoption maturity shaped the analytical framework over the projection horizon. Modeled segmentation dimensions encompass roadway-bridge-tunnel-railway categories, concrete-asphalt-steel-aggregate material tiers, and smart-sustainable-robotic-geospatial technology clusters. CAGRs were derived from weighted award volume trajectories incorporating Duqm Special Economic Zone expansion timelines and Ministry mandate implementation phases.
Decision-makers should treat outputs as directional under assumptions of sustained Oman Vision 2040 capital commitment and stable limestone quarry licensing; material deviation would warrant model refresh. Revision becomes warranted when carbon-reduction mandate enforcement intensity crosses thresholds that fundamentally restructure contractor eligibility criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
Qatar Transportation Infrastructure Construction Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
Thailand Data Center Construction Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market