
 EV Taxi Market | 2026-2036
EV Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
EV Taxi Market Foresight
China's battery-swapping corridor along the Yangtze River Delta is fragmenting as local governments compete for fleet operator investment. BYD Motor Corp. leverages integrated cell-to-pack manufacturing to sustain cost leadership across taxi-spec sedans. Didi Chuxing Technology Co. anchors network density through proprietary charging partnerships in tier-one cities. Tesla Inc. competes on software-defined fleet management tools that optimize utilization rates.
An EV taxi is a battery-electric passenger vehicle purpose-built or retrofitted for commercial ride-for-hire service, typically operating with a minimum range of 300 kilometers and DC fast-charging compatibility to sustain two-shift daily duty cycles. Its primary purpose is to transport paying passengers under regulated fare structures while eliminating tailpipe emissions in high-traffic urban corridors. Sedan configurations dominate current fleet procurement due to lower per-kilometer operating costs, though SUV variants are capturing premium ride-hailing segments where passenger capacity commands rate multiples. Wireless charging infrastructure remains nascent but holds structural promise for curbside taxi ranks where plug-in dwell time erodes driver earnings.
China's MIIT enforces NEV penetration quotas that mandate electric shares in fleet registrations, while India's FAME scheme and state-level EV policies subsidize commercial charging hubs for taxi operators. The EU Green Deal and F-Gas Regulation indirectly shape demand by accelerating municipal zero-emission zone designations that exclude internal-combustion taxis. Stakeholders must monitor how battery passport requirements and carbon border adjustments restructure fleet financing and residual value calculations.
Market Dynamics
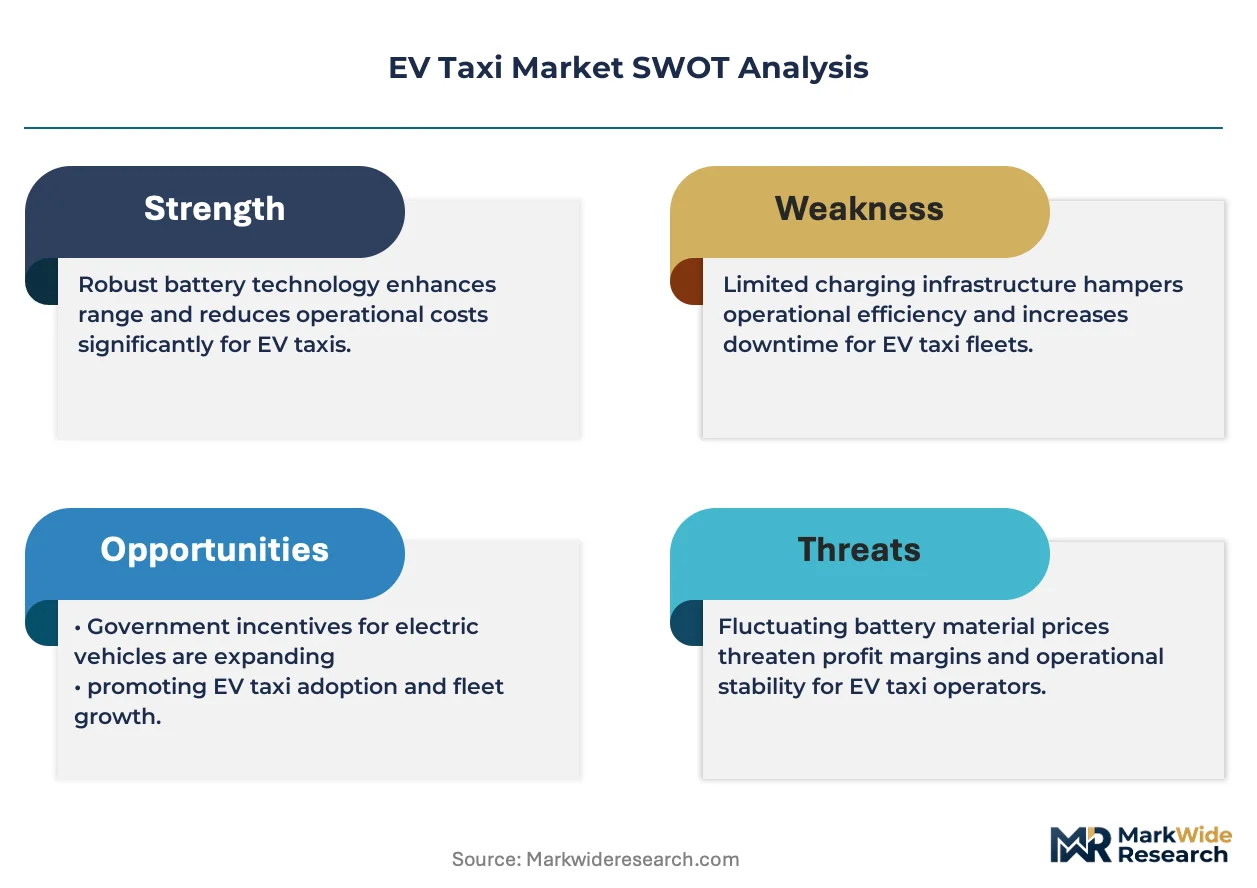
Battery-swapping infrastructure deployment is compressing fleet downtime and reshaping operator economics across high-density metropolitan corridors. This shift is forcing charging network operators to recalibrate asset-light strategies against capital-intensive swapping station buildouts.
Growth Catalysts
- China's NEV Mandate:MIIT penetration quotas compel fleet operators to electrify vehicle registrations, creating guaranteed demand pull for taxi-spec electric sedans in tier-one cities.
- FAME Scheme Subsidies:India's commercial charging hub incentives reduce upfront infrastructure capex for fleet electrification in Delhi, Mumbai, and Bangalore metropolitan regions.
- Cell-to-Pack Manufacturing:Integrated battery production architectures are slashing pack-level costs and enabling OEMs to hit fleet procurement price thresholds faster than modular designs.
Market Restraints
- Lithium Price Volatility:Cathode material cost swings transmit directly to battery pack pricing, squeezing fleet operator margins during procurement cycles.
- Charging Infrastructure Concentration:Urban real estate scarcity in Shenzhen and Shanghai limits curbside fast-charging siting, creating queue bottlenecks during shift changes.
- Residual Value Uncertainty:Battery degradation curves and second-life market immaturity depress used EV taxi valuations, elevating total cost of ownership calculations.
Strategic Opportunities
- Southeast Asian Megacities:Jakarta, Bangkok, and Ho Chi Minh City remain underpenetrated for electric fleet conversion, offering first-mover positioning before air quality mandates tighten.
- Wireless Inductive Charging:Curbside taxi rank deployment eliminates plug-in dwell time, enabling continuous revenue generation during passenger loading intervals.
- EU Green Deal ZEZ Designations:Municipal zero-emission zone rollouts in London, Paris, and Amsterdam will exclude internal-combustion taxis, forcing accelerated fleet turnover.
Industry Challenges
- High-Voltage Technician Scarcity:Fleet maintenance depots face recruitment gaps for certified EV powertrain specialists, extending vehicle downtime during repair cycles.
- Multi-Standard Charging Interoperability:Fragmented connector protocols and payment systems across China's GB/T, Europe's CCS2, and India's evolving standards complicate cross-border fleet operations.
- DC Fast-Charging Grid Integration:Distribution network capacity constraints in dense urban districts require utility-side transformer upgrades that delay station commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Taxi Market |
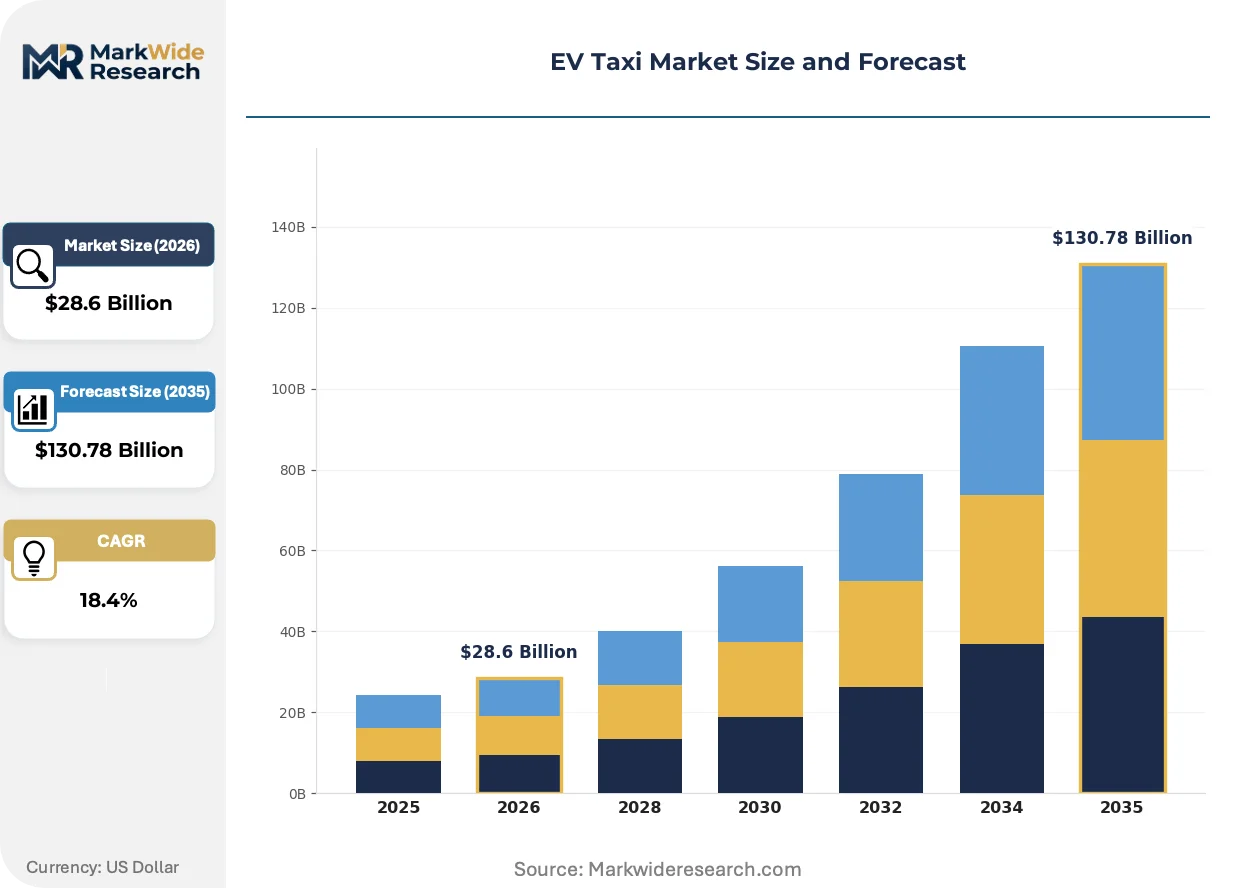
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $130.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Van, Hatchback Charging Infrastructure: Fast Charging Stations, Standard Charging Points, Wireless Charging, Home Charging Solutions Business Model: Ride-Hailing, Fleet Services, Government Contracts, Private Hires Customer Segment: Corporate Clients, Tourists, Local Residents, Ride-sharing Users |
| Companies Covered | Didi Chuxing Technology Co., BMW AG, BYD Motor Corp., BAIC Group, Lyft Inc., Tesla Inc., Nissan Motor Co. Ltd., Grab Holdings Ltd., Uber Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Taxi Market Shifts & Advancements
Software-defined fleet management tools are displacing legacy dispatch systems, enabling real-time utilization optimization and predictive maintenance scheduling. These capabilities are compressing the competitive gap between asset-heavy operators and platform-mediated fleet aggregators.
Solid-state battery chemistry is hybridizing with conventional lithium-ion architectures in pilot taxi fleets, offering faster charging tolerance and extended cycle life for high-utilization duty patterns. Operators in Japan's Kanto region are testing these packs for 24-hour continuous operation models. The technology is hybridizing total cost of ownership calculations by reducing battery replacement frequency and enabling thinner thermal management systems.
The EU F-Gas Regulation is accelerating refrigerant phase-down timelines for vehicle HVAC systems, compelling OEMs to redesign thermal management for CO2-based heat pumps. This industrial consequence elevates component costs but extends real-world range in extreme climate conditions. Taxi fleets in Nordic municipalities are responding by prioritizing cold-weather validated battery chemistries in procurement specifications.
Aggregated fleet purchasing consortia are displacing single-operator procurement negotiations, concentrating buyer power and forcing OEMs to standardize service-level agreements across multi-city deployments. This channel consolidation is most visible in India's state-level taxi operator associations, which now negotiate battery warranty terms and charging infrastructure bundles as unified blocks rather than fragmented municipal contracts.
EV Taxi Market Segmentation
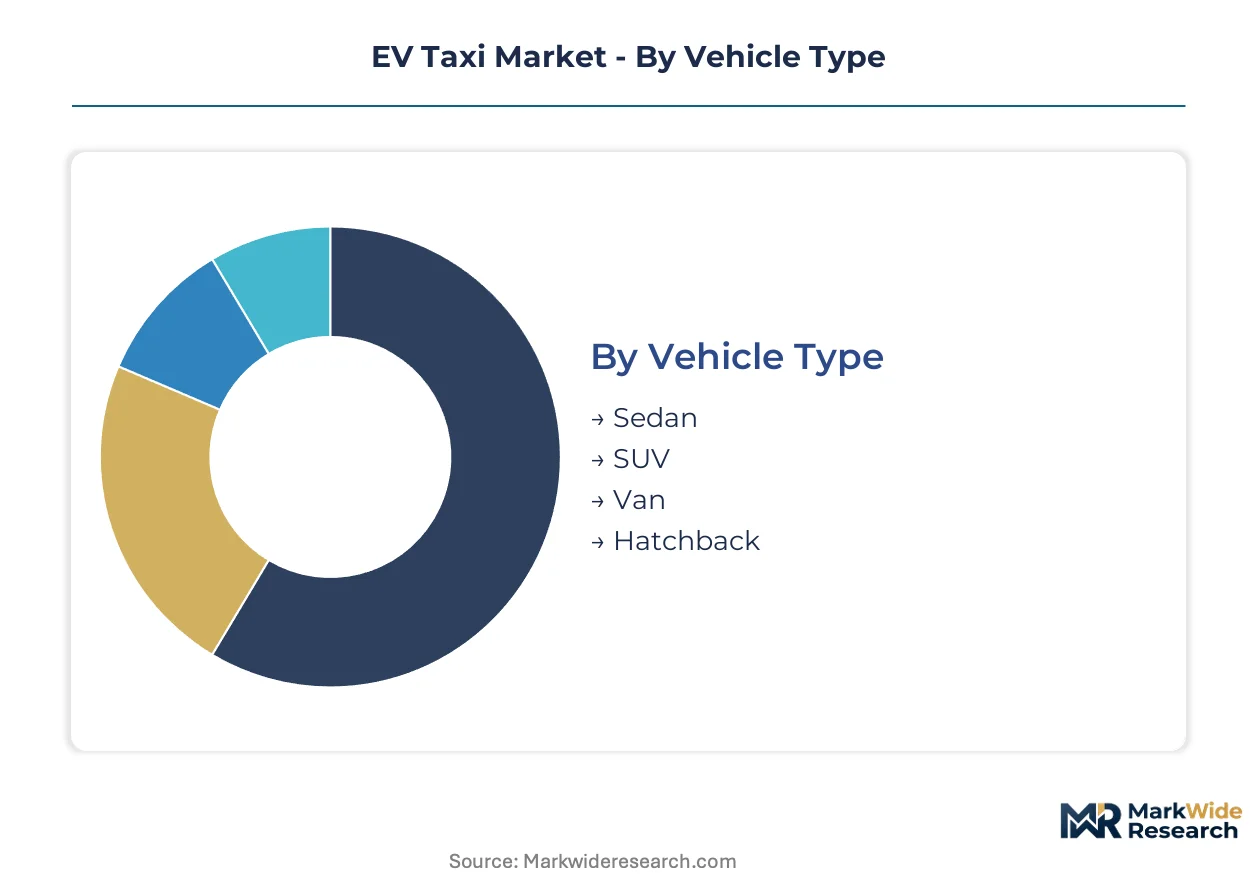
Segmentation in the EV taxi market reveals how operational requirements, infrastructure access, and customer economics fragment procurement patterns across fleet operators. Understanding these divides exposes where battery-swapping economics, charging network density, and regulatory compliance reshape vehicle selection and business model viability.
Vehicle Type:
Sedans dominate procurement volumes for cost-sensitive urban duty cycles, while SUVs and vans capture premium and specialized use cases where passenger capacity or luggage volume commands rate premiums.
- Sedan:Purpose-built electric sedans with 300-400 kilometer range and cell-to-pack battery architectures minimize per-kilometer operating costs for two-shift daily operations. Fleet operators in Shenzhen and Shanghai concentrate procurement here due to MIIT efficiency mandates and lower insurance classifications.
- SUV:Seven-seat configurations with enhanced thermal management systems serve airport transfers and premium ride-hailing tiers where passenger volume justifies 15-25% higher per-kilometer rates. Demand clusters in Beijing and Dubai where corporate account travel policies prioritize vehicle class.
- Van:Wheelchair-accessible and cargo-optimized variants support paratransit contracts and luggage-heavy airport routes requiring 500+ liter storage capacity.
- Hatchback:Compact urban runabouts with sub-4.2 meter lengths exploit narrow European street widths and congestion zone exemptions in London and Paris.
Established volume favors sedan procurement; emerging adoption favors SUV configurations as premium ride-hailing segments expand.
Charging Infrastructure:
Infrastructure segmentation tracks how fleet operators balance capital intensity against vehicle utilization, with swapping and wireless systems displacing conventional plug-in models where dwell time costs dominate.
- Fast Charging Stations:DC 150kW+ installations enable 30-minute recharge windows during driver shift changes, though grid connection delays and transformer upgrade costs constrain deployment in dense urban districts like Manhattan and central Tokyo.
- Standard Charging Points:AC 7-22kW units serve overnight depot charging for fleet operators with dedicated parking facilities, minimizing demand charges but requiring 6-8 hour dwell periods.
- Wireless Charging:Inductive pads at taxi ranks eliminate plug-in delays, with pilot deployments in Oslo and Milton Keynes testing continuous revenue generation during passenger loading.
- Home Charging Solutions:Subsidized residential wallbox installations support driver-owned vehicles in hybrid fleet models, though apartment dweller access remains limited in high-rise cities like Hong Kong and Singapore.
Asset-heavy operators favor fast charging station networks; platform-mediated aggregators gain flexibility through standard charging point and home charging combinations.
Business Model:
Business model selection determines fleet ownership structure, driver employment status, and regulatory compliance burden across municipal jurisdictions with divergent permit allocation systems.
- Ride-Hailing:App-mediated dispatch platforms optimize utilization through dynamic pricing algorithms and pooled ride matching, concentrating in markets where Didi Chuxing and Uber hold operating licenses.
- Fleet Services:Asset-heavy operators like BYD's leasing subsidiaries bundle vehicle, maintenance, and charging access into per-kilometer contracts, reducing driver capital barriers.
- Government Contracts:Municipal paratransit and civil servant transport tenders mandate wheelchair accessibility and fixed-route reliability, with 8-10 year contract terms stabilizing revenue visibility.
- Private Hires:Pre-booked executive car services command 2-3x metered taxi rates for airport and corporate travel, prioritizing vehicle age and cleanliness over pure cost minimization.
Platform scale favors ride-hailing expansion; regulatory stability favors government contract anchoring for capital-intensive fleet services.
Customer Segment:
Customer segmentation maps how fare sensitivity, trip purpose, and booking behavior fragment demand across payment willingness and service quality expectations.
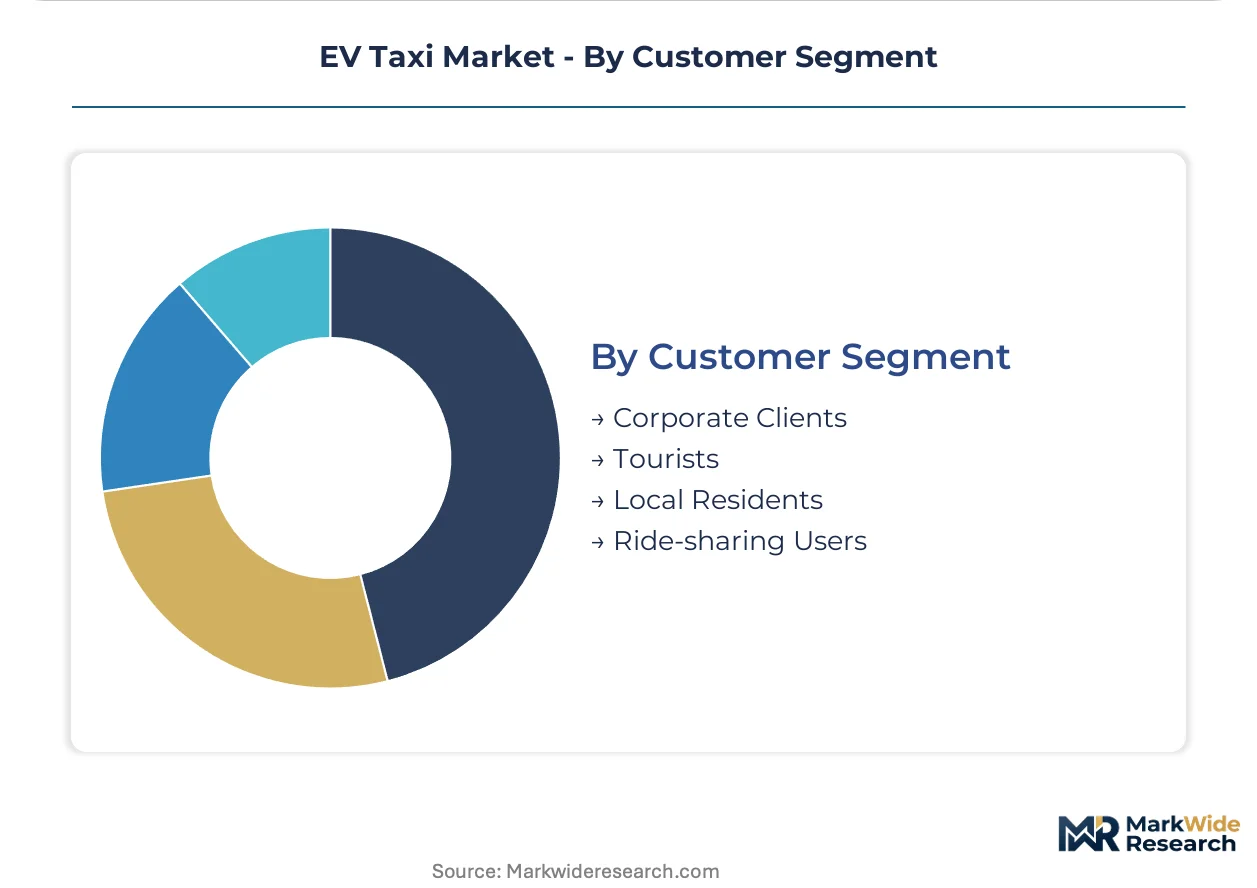
- Corporate Clients:Centralized billing arrangements and sustainability reporting requirements drive procurement of certified zero-emission fleets for employee ground transport, with ESG disclosure mandates accelerating conversion timelines.
- Tourists:Price-inelastic demand for airport transfers and sightseeing routes tolerates premium vehicle classes where luggage capacity and English-language driver apps reduce friction.
- Local Residents:Recurring commute and errand trips exhibit high price elasticity, concentrating on lowest-cost sedan options and shared ride acceptance.
- Ride-sharing Users:Pooled trip acceptance trades time cost against fare reduction, requiring vehicles with partitioned seating and enhanced HVAC filtration in post-pandemic specifications.
Margin stability favors corporate client contracting; volume expansion favors ride-sharing user acquisition in price-sensitive emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT penetration quotas and NEV mandates in China anchor fleet electrification momentum, compressing total cost of ownership calculations for commercial operators across high-density metropolitan corridors. Battery-swapping infrastructure deployment and cell-to-pack manufacturing scale are reshaping procurement economics in tier-one cities. Regulatory fragmentation across municipal jurisdictions creates divergent compliance burdens for cross-border fleet operators.
China
Didi Chuxing's network density and proprietary charging partnerships dominate ride-hailing electrification in Shenzhen and Shanghai. MIIT enforces fleet registration quotas that mandate electric vehicle shares, guaranteeing demand pull for taxi-spec sedans. The Yangtze River Delta battery-swapping corridor fragments as local governments compete for fleet operator investment.
India
FAME scheme subsidies reduce commercial charging hub capex for operators in Delhi, Mumbai, and Bangalore metropolitan regions. State-level EV policies diverge in incentive intensity, creating arbitrage opportunities for fleet registration across Maharashtra, Karnataka, and Telangana. Aggregated purchasing consortia among state taxi associations now negotiate battery warranties and infrastructure bundles as unified blocks.
United States
California's Advanced Clean Cars II regulation accelerates zero-emission fleet turnover in Los Angeles and San Francisco metropolitan areas. NHTSA safety standards and EPA tailpipe regulations shape vehicle certification timelines for commercial operators. Tesla's software-defined fleet management tools optimize utilization rates for ride-hailing platforms competing on driver earnings retention.
Germany
KBA type-approval requirements and EU Green Deal zero-emission zone designations force accelerated ICE taxi phase-out in Berlin, Hamburg, and Munich. The F-Gas Regulation compels HVAC system redesigns for CO2-based heat pumps, elevating component costs but extending cold-weather range. BMW AG leverages premium fleet positioning for corporate account segments prioritizing vehicle class over pure cost minimization.
United Kingdom
Transport for London's zero-emission zone mandates exclude internal-combustion taxis from central operating areas, compressing fleet turnover timelines. The CSRD disclosure requirements drive corporate procurement of certified zero-emission fleets for employee ground transport. LEVC and BYD compete for black cab replacement contracts with wheelchair-accessible electric configurations.
EV Taxi Market Competitive Landscape
Platform-mediated aggregators and integrated OEM-leasing subsidiaries split the market between asset-light dispatch optimization and capital-intensive fleet ownership models. Vertical integration into battery manufacturing and swapping infrastructure is compressing procurement costs for scale operators while fragmenting competitive positioning for pure-play charging networks. Two strategic archetypes dominate: technology-first platform operators optimizing utilization algorithms, and manufacturing-integrated fleet service providers bundling vehicle, maintenance, and energy access. Dominant competitive moves include proprietary charging infrastructure partnerships and aggregated fleet purchasing consortia displacing single-operator negotiations.
Among China-based manufacturing-integrated operators, BYD Motor Corp. and BAIC Group exemplify the fleet-service archetype through captive battery production and swapping station deployment. Didi Chuxing Technology Co. occupies the platform-aggregator position, leveraging network density in tier-one cities to anchor driver supply. Tesla Inc. represents the technology-differentiated entrant, competing on software-defined fleet management tools rather than manufacturing scale or network effects.
| Leading Market Players |
|---|
| Didi Chuxing Technology Co. |
| BMW AG |
| BYD Motor Corp. |
| BAIC Group |
| Lyft Inc. |
| Tesla Inc. |
| Nissan Motor Co. Ltd. |
| Grab Holdings Ltd. |
| Uber Technologies Inc. |
| Others |
Supply & Pricing Matrix
The Shanghai-Shenzhen freight corridor's lithium carbonate transport costs cascade through cell-to-pack manufacturing economics, compressing procurement margins for fleet operators in tier-one cities while amplifying price differentiation between battery-swapping and fast-charging service tiers.
Pricing Analysis
Per-kilometer rate spreads between Shenzhen and Jakarta exceed 40 percent, reflecting divergent electricity tariffs and driver earnings floors. Three-tier pricing structure across premium SUV, standard sedan, and economy hatchback segments tracks battery capacity and thermal management specifications. Pricing pressure stems from lithium cathode volatility transmitting directly to pack-level procurement costs. Aggregated fleet consortia exhibit lowest price sensitivity due to unified bargaining power, whereas single-operator owner-drivers face acute margin compression.
Supply Chain Analysis
CATL and BYD's in-house cell production anchor capacity concentration across China's Yangtze River Delta and Pearl River Delta manufacturing clusters. Cell-to-pack architectures draw from lithium carbonate, nickel sulfate, and copper foil feedstocks sourced from Chilean mines and Indonesian processing facilities. Single-source vulnerability concentrates around cathode precursor supply from integrated Chinese refiners. Distribution runs through OEM-direct fleet leasing subsidiaries and state-level taxi association procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV taxi deployment sits in early-cycle expansion, with MIIT fleet electrification quotas and EU zero-emission zone mandates accelerating penetration curves ahead of pure cost parity.
For Market Incumbents: Insulate service revenue streams from hardware margin erosion by deepening captive battery-swapping infrastructure in tier-one corridors. BYD and Didi Chuxing's integrated leasing models demonstrate how backward integration into cell manufacturing defends against lithium price volatility. Prioritize certification investment for EU battery passport compliance before 2027 regulatory deadlines tighten. For New Entrants and Emerging Players: Establish a beachhead in Jakarta, Bangkok, and Ho Chi Minh City's underpenetrated fleet conversion markets before air quality mandates replicate China's MIIT framework. Wireless inductive charging pilots at curbside taxi ranks offer differentiation against incumbent plug-in networks. Target government paratransit contracts with wheelchair-accessible van configurations where 8-10 year terms stabilize revenue visibility. For Investors and Strategic Acquirers: EU F-Gas Regulation and CSRD disclosure requirements reshape the acquisition landscape toward fleet operators with certified zero-emission vehicle pools and auditable carbon accounting. Long-term viability centers on software-defined fleet management capabilities rather than pure vehicle asset scale. Watch for state-level taxi association consolidation in India as aggregated purchasing consortia concentrate buyer power and force OEM service-level standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and BYD's cell-to-pack output secures volume allocation for Didi Chuxing's tier-one fleet expansion. |
| Charging Infrastructure Partnership | Proprietary fast-charging station networks in Shenzhen and Shanghai anchor driver retention against platform competitors. |
| Software-Defined Vehicle Investment | Tesla's fleet management tools optimize utilization rates for ride-hailing platforms competing on earnings retention. |
| Geographic Manufacturing Footprint | India's FAME-subsidized commercial charging hubs reduce capex barriers for Delhi and Mumbai operators. |
| Platform Integration | Aggregated purchasing consortia among state taxi associations standardize battery warranty terms across multi-city deployments. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, charging infrastructure developers, municipal transport regulators, and OEM platform engineers and refined through secondary validation across MIIT policy filings, EU Green Deal implementation documents, FAME scheme disbursement records, and vehicle registration databases. Bottom-up triangulation of fleet deployment data against top-down regulatory mandate tracking anchored volume estimates.
Demand-supply balance framing integrated vehicle procurement cycles, driver earnings optimization, and charging network commissioning timelines across the analysis window. Segmentation dimensions modeled include vehicle class, charging infrastructure type, business model archetype, and regional regulatory cluster. CAGRs derived from deployment trajectory analysis incorporating MIIT quota enforcement intensity and zero-emission zone rollout schedules.
Sensitivities concentrate around lithium carbonate price volatility, grid connection delays for DC fast-charging stations, and battery degradation curve assumptions affecting residual value calculations. Quarterly review of cathode material spot prices, municipal charging permit issuance rates, and fleet operator consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Car Battery Chargers Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
EV Platform Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
Spain Solar E-Bike Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
Electric Vehicle Air Conditioning Market