
 India Sustainable Home Decor Market | 2026-2036
India Sustainable Home Decor Market Size, Share, and Industry Trends Forecast 2026-2036
India Sustainable Home Decor Market Insights
Multi-source artisan networks is hardening as the dominant procurement architecture for sustainable home decor in India. Scrapshala leverages upcycled material streams from Varanasi's craft belt to sustain its product pipeline. Thenga anchors its competitive position through direct partnerships with Kerala coir and bamboo collectives.
India sustainable home decor encompasses furnishings and interior objects manufactured from renewable, recycled, or low-impact materials meeting cradle-to-cradle or comparable lifecycle standards, with bamboo and jute composites requiring moisture content below 12% for dimensional stability in tropical climates. Furniture and textiles together constitute the volume core, with decorative accessories representing the fastest margin expansion zone as gifting occasions multiply. Organic cotton and recycled wood command premium positioning in mid-range and luxury tiers where certification transparency directly influences purchase conversion.
BIS eco-labeling standards, the CDSCO framework for toxin thresholds in surface coatings, and state-level plastic waste management rules collectively shape product compliance costs and market access thresholds for imported sustainable materials. The PLI scheme for textile and bamboo product manufacturing is redirecting capital toward domestic processing capacity. Stakeholders must monitor evolving state implementation schedules for extended producer responsibility mandates to calibrate inventory and sourcing commitments.
Market Dynamics
Artisanal craft technology and BIS eco-labeling mandates are compressing the gap between premium certification and mass-market accessibility across Indian sustainable home decor. This dual pressure is forcing domestic manufacturers to rebuild material sourcing and quality assurance infrastructure from the ground up.
Growth Catalysts
- PLI scheme for bamboo and textile manufacturing:Capital subsidies are accelerating domestic processing capacity for jute composites and coir derivatives, reducing import dependency for raw material inputs.
- Urban household toxin awareness:Conscious consumer clusters in Bengaluru and Mumbai are driving demand for CDSCO-compliant surface coatings and formaldehyde-free furnishings in premium residential segments.
- Artisan network digitization:Direct-to-maker platforms are collapsing traditional multi-layer distribution for Kerala bamboo and Varanasi upcycled crafts, improving artisan margins and traceability.
Market Restraints
- Bamboo moisture volatility:Tropical humidity fluctuations above 12% moisture content trigger dimensional instability in jute-bamboo composites, requiring climate-controlled warehousing that elevates working capital needs.
- Import certification friction:DGFT documentation requirements for recycled wood and organic cotton inputs create 6-8 week customs delays, compressing seasonal inventory turns for festive gifting cycles.
- Artisan supply fragmentation:Kerala coir collectives and Karnataka weaving clusters operate at sub-scale volumes, forcing brands to maintain 15-20 parallel supplier relationships for SKU coverage.
Strategic Opportunities
- Tier-2 city penetration:Hyderabad and Pune conscious consumer clusters remain underpenetrated for certified sustainable interiors, offering first-mover positioning ahead of organized retail expansion.
- BIS eco-labeling tailwind:Mandatory state-level extended producer responsibility schedules will advantage early-certified manufacturers with preferred supplier status in government housing projects.
- Digital-native gifting channels:Corporate sustainability mandates are electrifying demand for certified decor in employee onboarding and Diwali gifting, bypassing traditional furniture retail entirely.
Industry Challenges
- Certification timeline compression:Cradle-to-cradle and BIS concurrent audits require 14-18 month validation cycles, misaligning with fast-fashion interior trend velocities.
- Legacy finishing skill scarcity:Water-based lacquer and natural dye application expertise concentrates in aging artisan populations across Tamil Nadu and West Bengal, constraining quality-scaled production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Sustainable Home Decor Market |
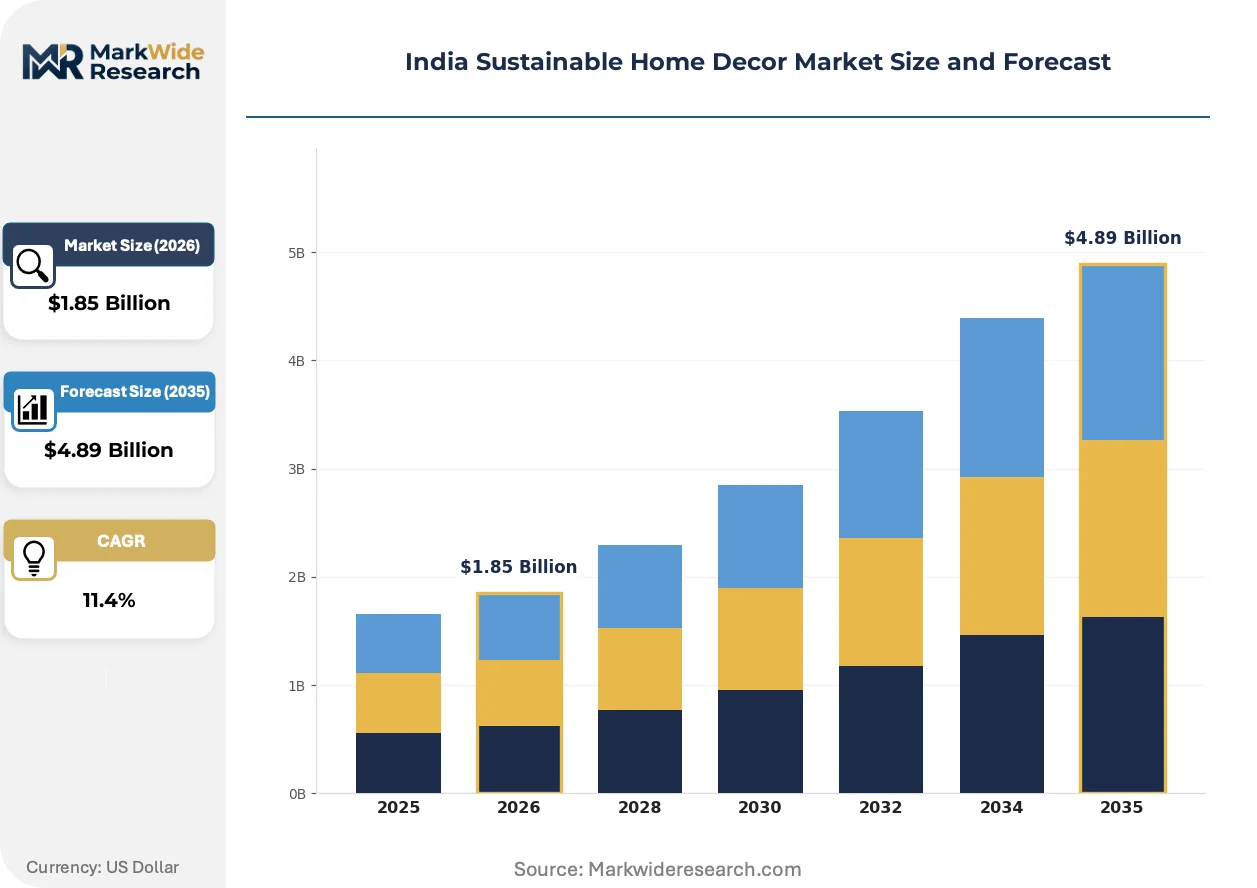
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furniture, Textiles, Lighting, Decorative Accessories Material: Bamboo, Recycled Wood, Organic Cotton, Jute End User: Households, Hotels, Restaurants, Offices Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Lukka Chuppi, Scrapshala, Byora Homes, Thenga, The Good Route, Greendigo, Saanjh, The Mango Tree, Hohmgrain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Sustainable Home Decor Market Trends and Innovations
Material science convergence with traditional craft techniques is collapsing the durability gap between sustainable and conventional home decor. This shift is redrawing competitive boundaries around certification transparency rather than price positioning alone.
Low-VOC bio-resin infusion technology is electrifying structural integrity in bamboo furniture manufacturing. Premium residential developers in Mumbai and Delhi NCR are specifying these composites for high-humidity coastal and monsoon-exposed installations. The technology is compressing warranty differential between sustainable and engineered wood products from 5 years to parity.
BIS eco-labeling standards for furniture and textiles are hardening compliance thresholds for formaldehyde emissions and heavy metal content in surface coatings. Domestic manufacturers face 20-30% testing cost elevation to maintain market access. Maharashtra and Karnataka state procurement guidelines now mandate BIS certification for sustainable decor in government-funded housing schemes.
Corporate gifting buyers are consolidating purchase authority under chief sustainability officers, displacing decentralized HR procurement for employee and client decor programs. Direct brand partnerships are replacing aggregator platforms for volume orders above 500 units. This concentration is most visible in Bengaluru's technology sector and Mumbai's financial services verticals.
India Sustainable Home Decor Market Segmentation
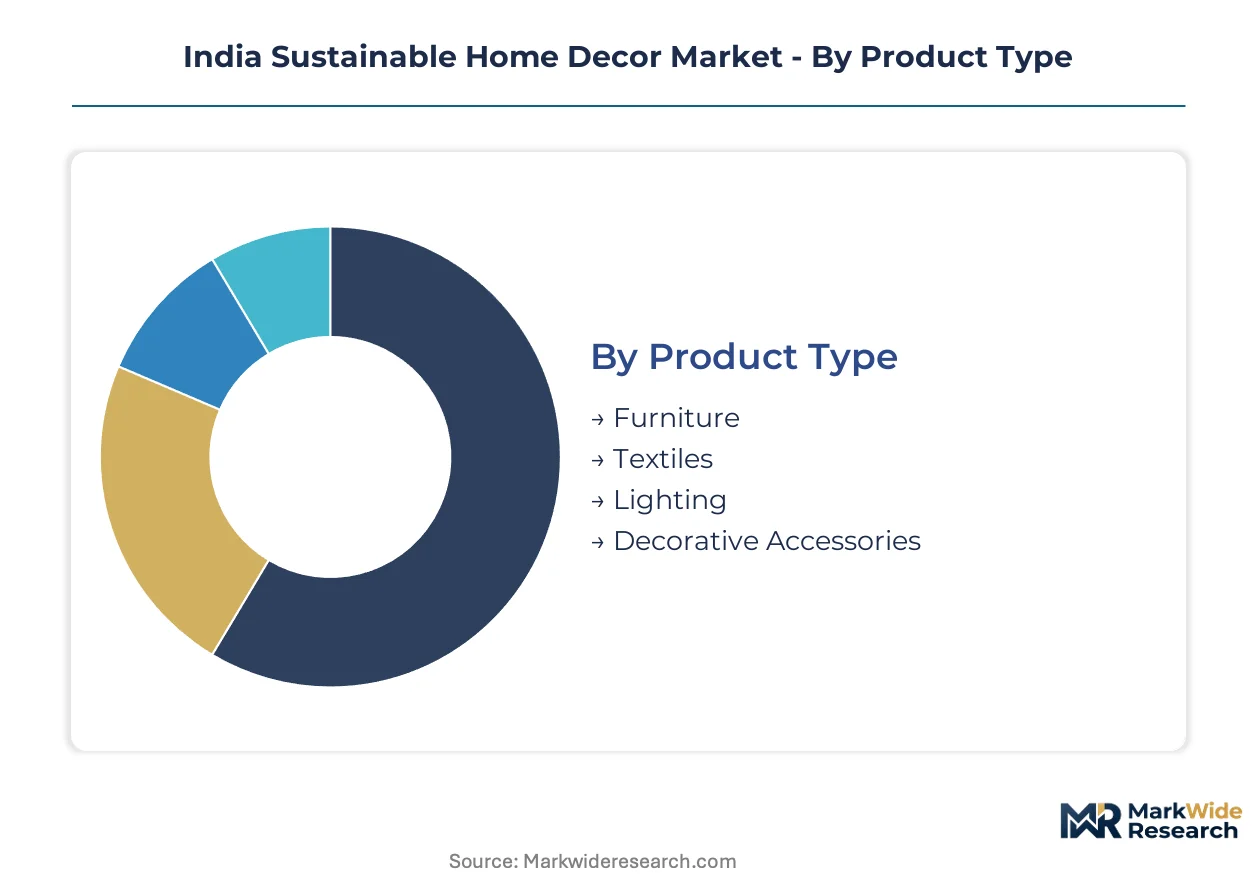
Segmentation in India's sustainable home decor market reveals how certification requirements, climate specifications, and procurement authority distribute differently across product categories and buyer types. Understanding these fault lines enables manufacturers to calibrate compliance investment against addressable revenue pools.
Product Type:
Bamboo bio-resin infusion and low-VOC finishing specifications create divergent durability profiles across furniture versus decorative categories.
- Furniture:Structural pieces manufactured from jute-bamboo composites with moisture content below 12% require climate-controlled warehousing through monsoon cycles. Maharashtra and Karnataka residential developers specify these for toxin-free interiors in premium apartment fit-outs.
- Textiles:Organic cotton and natural dye applications face finishing skill scarcity concentrated in aging Tamil Nadu and West Bengal artisan populations. CDSCO-compliant surface coating mandates elevate testing costs for bedding and upholstery destined for Bengaluru conscious consumer clusters.
- Lighting:Bamboo and recycled wood fixtures with BIS electrical safety certification capture corporate gifting procurement authority now consolidated under chief sustainability officers.
- Decorative Accessories:Upcycled craft items from Varanasi and Kerala coir derivatives dominate Diwali gifting channels with fastest margin expansion as volume orders exceed 500 units.
Furniture leads on scale; Decorative Accessories leads on momentum.
Material:
Raw material procurement architecture determines compliance cost structure and climate resilience for finished goods.
- Bamboo:PLI scheme subsidies accelerate domestic processing capacity for bio-resin infused structural composites. Tropical humidity fluctuations above 12% moisture content trigger dimensional instability, forcing climate-controlled inventory management.
- Recycled Wood:DGFT documentation requirements create 6-8 week customs delays for imported inputs, compressing seasonal inventory turns for festive gifting cycles in Mumbai and Delhi NCR.
- Organic Cotton:Certification transparency directly influences purchase conversion in mid-range and luxury tiers where Maharashtra conscious consumer clusters demand cradle-to-cradle validation.
- Jute:Kerala coir collectives operate at sub-scale volumes, forcing brands to maintain parallel supplier relationships for SKU coverage across textiles and composite furniture.
Bamboo leads on scale; Recycled Wood faces the steepest supply friction.
End User:
Procurement authority concentration and sustainability mandate penetration vary sharply across residential and commercial buyer types.
- Households:Urban toxin awareness in Bengaluru and Mumbai drives demand for formaldehyde-free furnishings in premium residential segments with direct-to-maker platform adoption.
- Hotels:Premium hospitality developers in coastal Maharashtra specify low-VOC bio-resin bamboo composites for high-humidity installations with warranty parity to engineered wood.
- Restaurants:FSSAI-adjacent hygiene expectations intersect with CDSCO surface coating compliance for tabletops and seating in Mumbai and Hyderabad food service fit-outs.
- Offices:Corporate sustainability mandates electrify certified decor demand for employee onboarding programs, bypassing traditional furniture retail entirely in Bengaluru technology sector.
Households lead on scale; Offices lead on procurement authority consolidation.
Price Tier:
Certification cost recovery and margin structure stratify across economy through luxury positioning.
- Economy:Mass-market accessibility compressed by BIS eco-labeling mandates forces domestic manufacturers to rebuild quality assurance infrastructure from artisan network foundations.
- Mid-range:Three-tier pricing structure separates BIS-certified from uncertified offerings as Maharashtra and Karnataka state procurement guidelines mandate certification for government-funded housing schemes.
- Premium:Organic cotton and recycled wood command positioning where certification transparency directly influences purchase conversion among Mumbai conscious consumer clusters.
- Luxury:Cradle-to-cradle concurrent audits require 14-18 month validation cycles, misaligning with fast-fashion interior trend velocities but securing preferred supplier status.
Premium leads on margin expansion; Economy faces the steepest compliance cost compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's conscious consumer clusters in Mumbai and Pune anchor India's sustainable home decor demand, with state procurement guidelines now mandating BIS certification for government-funded housing schemes.
Maharashtra
Mumbai's premium residential developers specify low-VOC bio-resin bamboo composites for toxin-free apartment fit-outs. The state's extended producer responsibility mandates under plastic waste management rules advantage early-certified manufacturers. Pune's emerging conscious consumer clusters remain underpenetrated for certified sustainable interiors.
Karnataka
Bengaluru's technology sector electrifies corporate gifting demand for certified decor in employee onboarding programs. The state's PLI scheme implementation for bamboo manufacturing redirects capital toward domestic processing capacity. Artisan network digitization platforms collapse traditional distribution layers for Karnataka weaving clusters.
Kerala
Coir collectives supply sub-scale volumes of jute derivatives to national sustainable furniture brands. The state's direct-to-maker platform adoption improves artisan margins and traceability for bamboo and coir products. Kochi's coastal humidity necessitates climate-controlled warehousing for moisture-sensitive composites.
Tamil Nadu
Aging artisan populations in Chennai and Madurai concentrate scarce water-based lacquer and natural dye application expertise. CDSCO-compliant surface coating mandates elevate testing costs for textiles destined for national markets. The state's organic cotton finishing infrastructure faces quality-scaled production constraints.
West Bengal
Kolkata's craft belt supplies upcycled material streams to national sustainable decor brands. The state's jute processing heritage supports composite furniture manufacturing for tropical climate specifications. Artisan skill scarcity in traditional finishing techniques constrains expansion of certified product lines.
India Sustainable Home Decor Market Competitive Landscape
Global sustainable furniture majors compete with regional Indian champions across certification transparency and artisan network depth. The vendor base organizes into three tiers: BIS-certified domestic manufacturers, direct-to-maker platforms with traceable supply chains, and import-dependent premium retailers. Two strategic archetypes dominate—multi-source artisan aggregators and vertically integrated craft-technology specialists. Competitive moves concentrate on geographic expansion into underpenetrated Tier-2 cities and backward integration into raw material processing.
Among Kerala and Varanasi-based fabricators, Thenga and Scrapshala exemplify the direct-artisan-partnership archetype. Thenga anchors its position through coir and bamboo collective relationships, while Scrapshala occupies a position within the upcycled craft segment. Lukka Chuppi represents the design-forward urban consumer targeting approach. These three occupy distinct positioning vectors rather than direct price competition.
| Leading Market Players |
|---|
| Lukka Chuppi |
| Scrapshala |
| Byora Homes |
| Thenga |
| The Good Route |
| Greendigo |
| Saanjh |
| The Mango Tree |
| Hohmgrain |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between BIS-certified and uncertified sustainable home decor compresses margin structures at the economy tier while amplifying pricing power for cradle-to-cradle validated manufacturers. This divergence manifests in procurement contract terms for Maharashtra government housing schemes and inventory carrying costs for climate-controlled bamboo warehousing.
Pricing Analysis
Input-cost pass-through from CDSCO-compliant surface coating mandates and extended producer responsibility compliance elevates base manufacturing costs by 20-30% for domestic producers. Three-tier pricing structure across premium, standard, and economy levels separates certified from uncertified offerings, with certification transparency and artisan provenance as primary price differentiation drivers. Pricing pressure stems from DGFT documentation friction on recycled wood imports, compressing seasonal inventory turns. Economy-tier buyers exhibit highest price sensitivity, while corporate gifting procurement under chief sustainability officers shows lowest elasticity.
Supply Chain Analysis
Reverse-logistics flows for upcycled craft items from Varanasi and refurbishment networks for bamboo furniture create secondary material streams that reduce virgin input dependence. Geographic supply concentrates in Kerala for coir derivatives, Karnataka for weaving clusters, and Maharashtra for premium residential fit-out demand. Raw material dependencies rest on jute-bamboo composites, organic cotton, and bio-resin infusion chemicals. Single-source vulnerability runs through aging Tamil Nadu artisan populations for water-based lacquer finishing. Distribution runs through direct-to-maker platforms collapsing traditional multi-layer structures for Kerala and Varanasi craft networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India sustainable home decor represents a late-cycle quality story where toxin-awareness among Bengaluru and Mumbai urban households redirects procurement authority toward certification-transparent suppliers. This demand-shift toward premium specifications hardens compliance thresholds as competitive moats.
For Market Incumbents: Cement market position through backward integration into Kerala coir processing and Karnataka bamboo bio-resin manufacturing to offset import dependency. Threats from DGFT documentation delays on recycled wood inputs demand captive supply chain development. Certification investment in concurrent BIS and cradle-to-cradle audits secures preferred supplier status in Maharashtra government housing schemes. For New Entrants and Emerging Players: Digital-native gifting platforms with corporate sustainability officer direct relationships offer a technology-first wedge into bypassed traditional furniture retail. Pune and Hyderabad conscious consumer clusters present underpenetrated white-space for certified sustainable interiors. Artisan network digitization enables traceability-based go-to-market positioning against fragmented incumbent supply bases. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated craft-technology specialists controlling both bio-resin infusion capability and direct artisan collective relationships. Long-term viability frames around certification infrastructure ownership rather than brand equity alone. Acquisition targets should demonstrate Kerala or Karnataka supply base control with BIS audit completion. Monitor PLI scheme disbursement velocity for bamboo manufacturing as inflection indicator for domestic processing capacity scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coir Processing | Kerala collective partnerships secure jute composite supply for tropical climate specifications. |
| BIS Eco-Labeling Certification Investment | Maharashtra government housing mandates create preferred supplier access for early certifiers. |
| Direct-to-Maker Platform Development | Artisan digitization collapses distribution layers and improves traceability for corporate gifting. |
| Bio-Resin Infusion Capacity Expansion | Climate-controlled composite manufacturing addresses monsoon-exposed installation demand. |
| Tier-2 City Distribution Partnership | Pune and Hyderabad retail expansion captures first-mover positioning ahead of organized entrants. |
Research Methodology
Coverage spans Maharashtra, Karnataka, Kerala, Tamil Nadu, and West Bengal, with primary inputs from each regional craft cluster. The analysis combines structured interviews with sustainable furniture brand founders, Kerala coir collective coordinators, Karnataka weaving cluster leaders, and Maharashtra premium residential developers with secondary validation from BIS certification databases, CDSCO surface coating compliance filings, and PLI scheme implementation schedules. Customs records from DGFT and state-level extended producer responsibility notifications provide trade flow triangulation against bottom-up artisan network mapping.
Granularity-level modeling disaggregates volume and value across product type, material composition, end-user category, and price tier dimensions throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs include PLI scheme capital subsidy disbursement trajectories for bamboo processing capacity and BIS eco-labeling adoption curves among Maharashtra and Karnataka manufacturers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to artisan skill scarcity in Tamil Nadu water-based lacquer application and DGFT documentation requirement modifications. Forecasts reflect assumptions on PLI scheme continuity and state-level extended producer responsibility implementation schedules without policy reversal. Practitioners should monitor BIS audit queue lengths and monsoon-season moisture content volatility in bamboo composites for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
US Bamboos Market
Homecare and Decor
United Kingdom Resilient Floor Covering Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
Smart Bed Mattress Market
Homecare and Decor
Bulletin Board Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Curtains and Window Blinds Market
Homecare and Decor
Global Decorative Panels Market
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
Bamboo Panels Market
Homecare and Decor
Builders and Cabinet Hardware Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Digital Printed Wallpaper Market
Homecare and Decor
Balcony Accessories Market