
 Builders and Cabinet Hardware Market | 2026-2036
Builders and Cabinet Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Builders and Cabinet Hardware Market Analysis
Home center and pro-dealer distribution is rewriting how builders and cabinet hardware reaches end users. ASSA ABLOY AB leverages its master key systems to dominate commercial specification channels. Stanley Black & Decker sustains broad SKU coverage across power tool adjacencies and fastening categories. Allegion plc anchors its position in electronic access control, extending hardware into smart building ecosystems.
Builders and cabinet hardware encompasses mechanical and electromechanical fixtures—including hinges rated for cycle life, corrosion-resistant drawer slides, and ANSI/BHMA-graded door hardware—manufactured through stamping, die-casting, and precision machining processes to enable functional opening, closing, and securing of architectural enclosures. Door hardware commands the deepest specification relationships with architects and facilities managers, while drawer hardware competes heavily on load capacity and soft-close mechanisms. Metal materials, particularly zinc and stainless steel alloys, carry premium positioning in commercial and institutional applications where durability certifications govern procurement.
The EPA enforces lead-safe renovation standards that filter product eligibility for residential contractors, while ANSI and BHMA publish performance grades that architects embed directly into construction specifications. China's GB standards and the EU's REACH restrictions on heavy metal content further constrain material choices for exporters. Stakeholders must monitor how electrification of locks and access systems redraws the boundary between traditional hardware and building automation procurement channels.
Market Dynamics
Residential renovation cycles in North America are compressing replacement timelines for mechanical hardware, while electrification of access systems redraws procurement boundaries between traditional suppliers and building automation vendors. The EPA's Lead Renovation, Repair and Painting Rule continues filtering contractor eligibility and product specifications.
Growth Catalysts
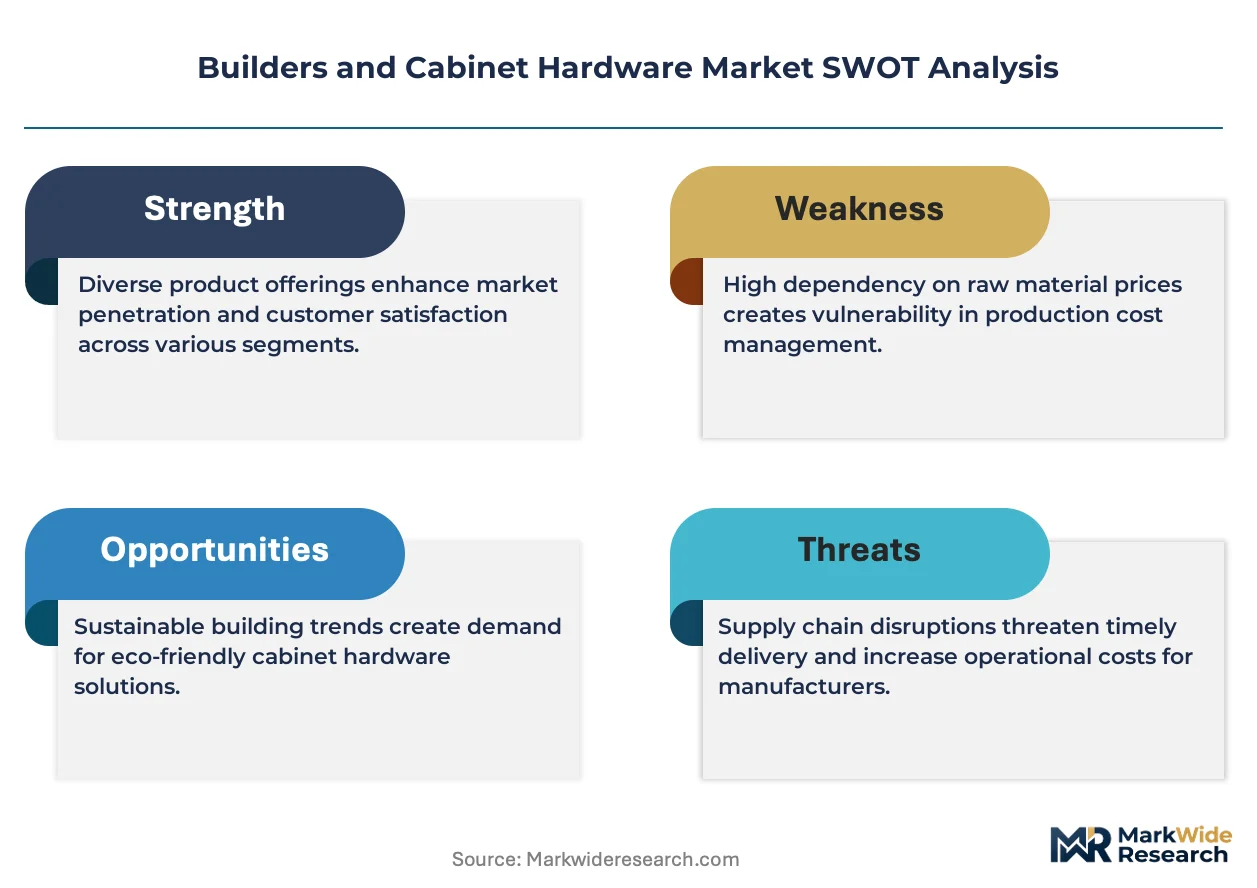
- EPA Lead-Safe Compliance Mandates:Contractors must use certified renovators and lead-safe work practices on pre-1978 housing, accelerating hardware replacement demand as older fixtures are disturbed and upgraded.
- Smart Building Integration:Electronic access control systems are penetrating commercial and multi-family residential projects, expanding hardware into connected building ecosystems.
- Guangdong Manufacturing Cluster Scale:China's concentrated production base supplies global OEMs with die-cast zinc and precision-machined components at scale, lowering input costs for branded assemblers.
Market Restraints
- Zinc Alloy Price Volatility:Die-cast zinc remains the dominant material for premium residential and commercial hardware, exposing margins to London Metal Exchange price swings.
- Single-Region Supply Concentration:Guangdong province hosts over 60 percent of global cabinet hardware stamping capacity, creating vulnerability to regional logistics disruptions or trade policy shifts.
- ANSI/BHMA Certification Barriers:Third-party testing for cycle life, corrosion resistance, and fire ratings adds 12-18 month lead times for new product introductions.
Strategic Opportunities
- India Residential Construction Expansion:Urban housing stock growth and rising middle-class homeownership are creating first-time demand for soft-close drawer systems and modular cabinet fittings.
- Biometric-Electromechanical Convergence:Fingerprint and facial recognition modules are integrating with mortise locks and exit devices, opening specification channels in high-security commercial verticals.
- Direct-to-Contractor Digital Platforms:Pro-dealer e-commerce portals are bypassing traditional two-step distribution, capturing margin and transaction data from renovation contractors.
Industry Challenges
- Electromechanical Engineering Talent Scarcity:Traditional mechanical hardware manufacturers face recruitment gaps for firmware developers and IoT security specialists.
- Legacy System Integration Complexity:Retrofitting electronic access control into existing mortise preparations requires custom mounting adapters, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Builders and Cabinet Hardware Market |
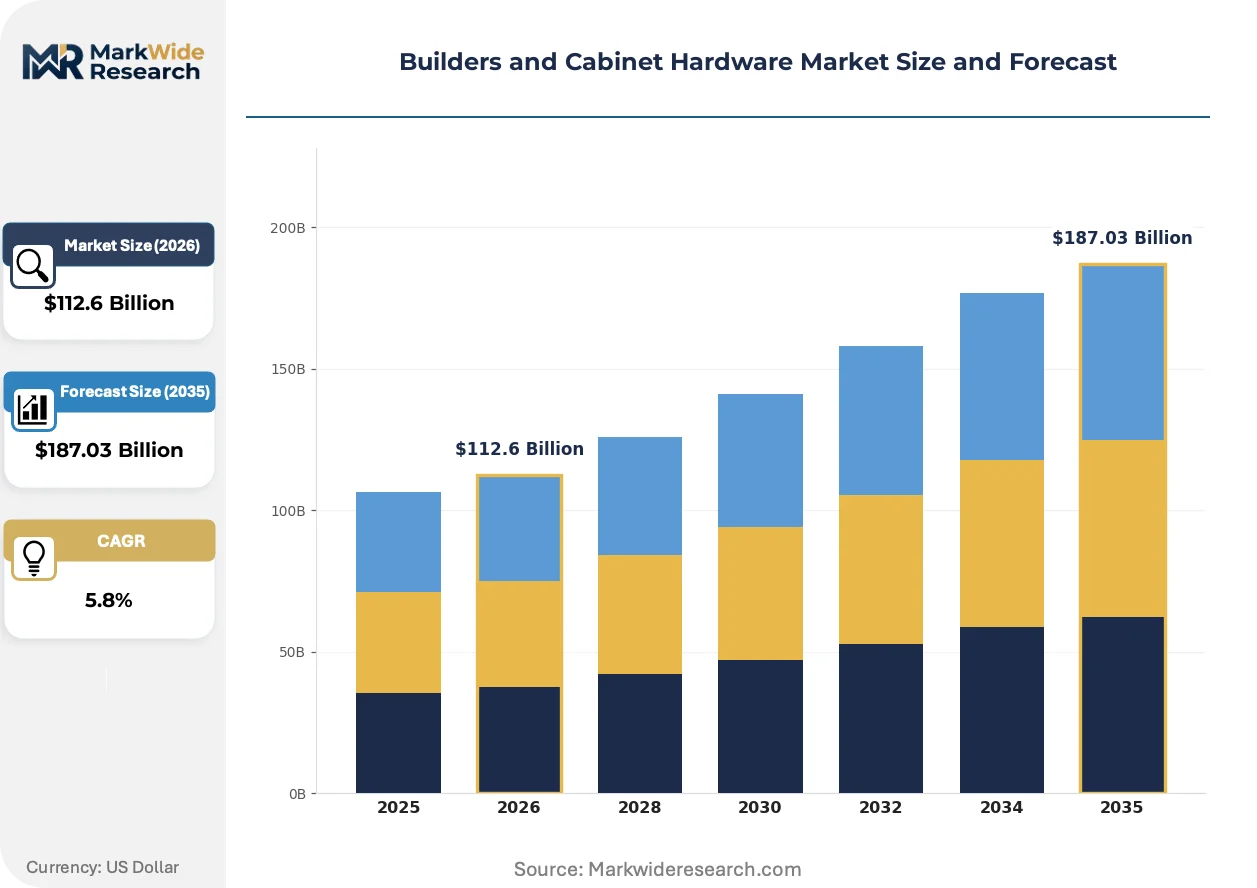
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $187.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Door Hardware, Drawer Hardware, Hinges Material: Wood, Metal, Plastic, Composite Application: Residential, Commercial, Industrial, DIY Projects Distribution Channel: Online Retail, Hardware Stores, wholesalers, Distributors |
| Companies Covered | Schlage, Dormakaba Group, ASSA ABLOY AB, HAGER COMPANIES, Rockwood Manufacturing Company, Allegion plc, Ashland Hardware Systems, CompX International, Stanley Black & Decker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Builders and Cabinet Hardware Market Emerging Trajectories
Electrification is dissolving the historical boundary between mechanical hardware and building automation, forcing suppliers to develop dual competencies in precision metalworking and embedded systems engineering.
Bluetooth-enabled smart locks with smartphone credentialing are rendering obsolete traditional keyed entry systems in multi-family residential and hospitality verticals. Property managers in Class-A apartment developments are adopting mobile access at 40 percent annual replacement rates. This shift is compressing specification influence from master locksmiths toward IT directors and building automation integrators.
REACH restrictions on hexavalent chromium and cadmium plating are forcing European manufacturers to migrate toward trivalent chrome and PVD finishes. The regulation is elevating coating costs by 15-25 percent while extending qualification timelines for export products. German and Italian hardware brands are responding by consolidating finishing operations in-house to control compliance documentation.
Renovation contractors are consolidating purchasing through integrated pro-dealer platforms that bundle hardware with complementary categories. This behavior is disintermediating traditional two-step distributors in North American metropolitan markets. The shift is most visible in Sun Belt states where residential turnover and investor-driven flipping activity concentrate demand.
Builders and Cabinet Hardware Market Segmentation
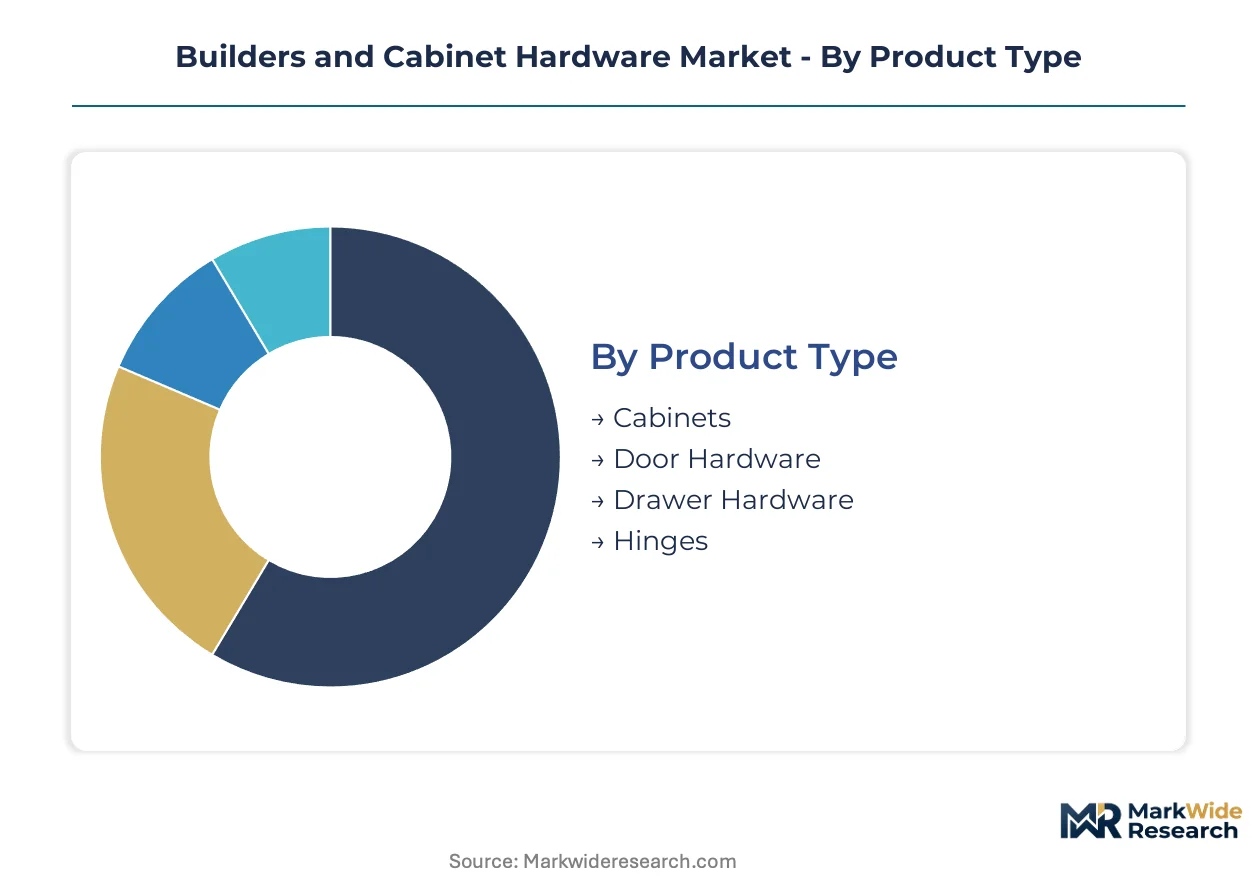
Builders and cabinet hardware serves distinct performance requirements across residential renovation, commercial specification, and industrial maintenance. Material selection and distribution channel strategy vary sharply between cost-sensitive DIY replacement and architect-grade commercial projects.
Product Type:
Mechanical fixtures span load-bearing structural elements to aesthetic finishing components, each carrying different specification authority and replacement cycles.
- Door Hardware:ANSI/BHMA-graded mortise locks, exit devices, and closers govern commercial building code compliance. Facilities managers in Class-A office developments drive electrification toward mobile credentialing systems.
- Cabinets:Modular box systems with standardized hinge boring patterns dominate kitchen and bath renovation. North American residential contractors specify soft-close hinge integration at accelerating rates during whole-room gut renovations.
- Drawer Hardware:Ball-bearing slides rated for dynamic load capacity compete on cycle life and silent operation.
- Hinges:Butt, concealed, and European cup variants serve furniture, architectural, and specialty enclosure applications.
Established volume favors cabinets; emerging adoption favors door hardware.
Material:
Raw material selection traces directly to durability certification requirements and finish longevity in target end-use environments.
- Metal:Zinc die-cast alloys dominate premium residential and commercial hardware for plating adhesion and corrosion resistance. REACH restrictions on hexavalent chromium are forcing migration toward trivalent chrome and PVD finishes in European export markets.
- Wood:Solid hardwood and veneer-wrapped substrates serve traditional furniture and high-end architectural millwork where grain matching and staining compatibility govern procurement.
- Plastic:Glass-reinforced nylon and ABS polymers capture economy-tier consumer hardware through injection molding scale.
- Composite:Engineered wood products and mineral-composite materials bridge cost and performance for mid-market cabinetry.
Metal commands specification premium; plastic captures replacement volume.
Application:
End-use context determines cycle life requirements, code compliance layers, and procurement decision-maker identity.
- Residential:Single-family and multi-family housing drives hinge and slide replacement during kitchen and bath renovation. EPA Lead Renovation, Repair and Painting Rule compliance filters contractor eligibility for pre-1978 housing work.
- Commercial:Office, hospitality, and healthcare facilities specify BHMA-certified hardware for fire rating and accessibility compliance. Smart building integration is shifting procurement influence toward IT directors.
- Industrial:Heavy-duty enclosures and equipment cabinetry require corrosion-resistant hardware for manufacturing environments.
- DIY Projects:Homeowner self-installation concentrates in big-box retail channels with lower cycle life expectations.
Residential replacement generates recurring revenue; commercial specification builds brand equity.
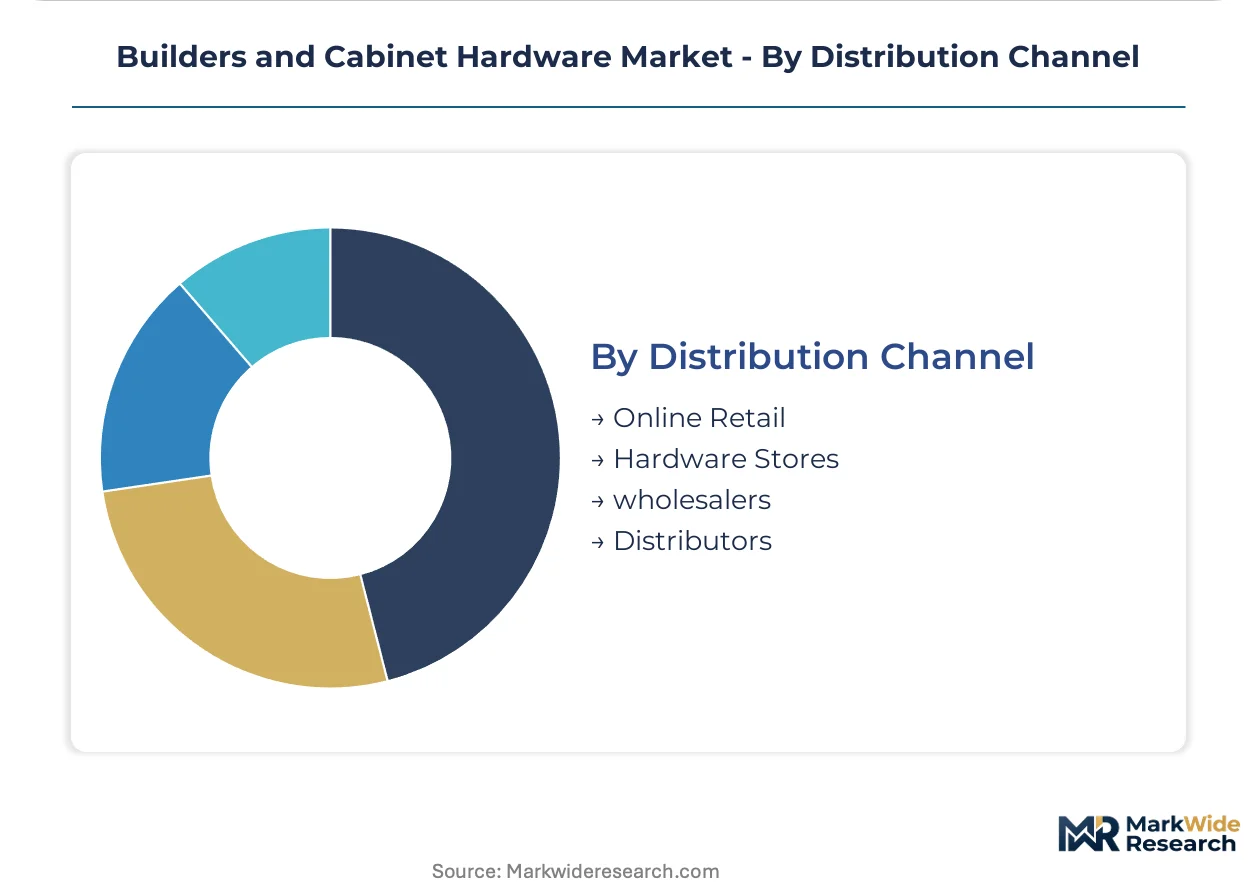
Distribution Channel:
Channel structure determines margin capture, technical support requirements, and customer data access for suppliers.
- Hardware Stores:Home center chains and independent dealers provide immediate availability and contractor credit terms. Pro-dealer platforms are consolidating purchasing power among renovation contractors in Sun Belt metropolitan markets.
- Online Retail:E-commerce portals capture DIY consumers and small contractors through search-optimized SKU breadth. Direct-to-contractor digital platforms are bypassing traditional two-step distribution.
- Wholesalers:Regional building material distributors bundle hardware with lumber and millwork for production homebuilders.
- Distributors:Specialty distributors serve commercial specification channels with submittal support and master keying services.
Hardware stores defend contractor loyalty; online retail gains DIY share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shenzhen anchors Guangdong province's manufacturing dominance, moving precision-machined hardware components to North American and European distribution hubs. Container throughput through this corridor directly shapes inventory cycles for branded assemblers.
United States
Sun Belt metropolitan markets concentrate renovation contractor purchasing through integrated pro-dealer platforms. The EPA's Lead Renovation, Repair and Painting Rule filters contractor eligibility for pre-1978 housing work, accelerating hardware replacement demand. Dallas-Fort Worth and Atlanta distribution centers serve as consolidation points for Southeast and Southwest residential construction supply chains.
China
Guangdong province hosts die-cast zinc and precision-machined component manufacturing at scale for global OEM supply. GB standards govern domestic product certification while REACH-aligned export requirements constrain plating chemistry for European-bound shipments. Foshan and Dongguan industrial clusters specialize in soft-close hinge and drawer slide production.
Germany
Architect-grade commercial specification channels concentrate in Baden-Württemberg and North Rhine-Westphalia industrial regions. ECHA REACH restrictions on hexavalent chromium and cadmium plating force migration toward trivalent chrome and PVD finishes. Stuttgart-area finishing operations consolidate in-house to control compliance documentation for export markets.
India
Urban housing stock expansion in Maharashtra and Karnataka generates first-time demand for modular cabinet fittings and soft-close drawer systems. BIS certification requirements for imported hardware components create compliance barriers for unbranded suppliers. Mumbai and Bangalore construction markets drive specification upgrading among mid-tier residential developers.
Japan
High-density multi-family residential in Tokyo and Osaka prefectures accelerates adoption of electronic access control with mobile credentialing. METI energy efficiency guidelines influence smart building integration specifications for commercial developments. Nagoya-area industrial suppliers serve precision machining requirements for premium architectural hardware.
Builders and Cabinet Hardware Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in die-casting and precision machining. The vendor base organizes around three tiers: multinational specification platforms with master keying and access control integration, regional branded assemblers sourcing from Guangdong clusters, and unbranded commodity stampers serving home center private label. Consolidation pressure concentrates among mid-tier players lacking either scale economies or specialist certification authority. Dominant competitive moves include backward integration into captive zinc die-casting capacity and strategic partnerships with building automation integrators.
Among specification-platform operators, ASSA ABLOY AB and Allegion plc anchor the electronic access control tier, while Stanley Black & Decker occupies a position spanning power tool adjacencies and fastening categories. These three represent the dominant archetypes: access integration platforms, diversified tool-and-fastening conglomerates, and commercial specification specialists.
| Leading Market Players |
|---|
| Schlage |
| Dormakaba Group |
| ASSA ABLOY AB |
| HAGER COMPANIES |
| Rockwood Manufacturing Company |
| Allegion plc |
| Ashland Hardware Systems |
| CompX International |
| Stanley Black & Decker |
| Others |
Supply Flow & Price Mechanics
The Shenzhen-Ningbo maritime corridor carries die-cast zinc components and precision-machined hardware assemblies from Guangdong clusters to North American distribution hubs, with freight rate volatility transmitting directly into landed cost spreads between premium branded hardware and unbranded commodity alternatives. Container availability constraints on this lane compress margins for mid-tier assemblers lacking long-term ocean freight contracts, while pro-dealer platforms capture price transparency gains that erode traditional distributor markups.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction dynamics, with ANSI/BHMA Grade 1 certification and zinc alloy purity separating premium architectural specification from economy DIY retail. Price differentiation hinges on cycle life certification and plating chemistry compliance, with REACH-aligned trivalent chrome finishes commanding 15-25 percent premiums over hexavalent chrome legacy products. Pricing pressure stems from Guangdong manufacturing scale lowering input costs for branded assemblers, compressing margin capture among regional distributors. DIY homeowners exhibit highest price sensitivity, while facilities managers in Class-A commercial developments prioritize lifecycle cost over unit price.
Supply Chain Analysis
London Metal Exchange zinc ingot pricing and stainless steel coil availability anchor upstream feedstock cost structures for die-casting and stamping operations. Manufacturing concentrates in China, Italy, and Germany, with Guangdong province hosting over sixty percent of global cabinet hardware stamping capacity. Raw material dependencies span zinc alloys, steel substrates, and electroplating chemistry. Single-region supply concentration creates vulnerability to regional logistics disruptions or trade policy shifts. Distribution runs through home center chains, pro-dealer platforms, and specialty distributors serving commercial specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware-as-a-service models are displacing pure product transactions, with master keying systems and electronic access credential management generating recurring revenue streams that expand faster than mechanical hardware replacement cycles. Subscription-based facility management contracts bundle hardware refresh with software maintenance, capturing lifetime value from commercial property portfolios.
For Market Incumbents: Build certification authority moats by accelerating ANSI/BHMA Grade 1 product introductions and in-housing REACH-compliant plating operations to control compliance documentation. Consolidate captive zinc die-casting capacity to defend margin position against Guangdong cost advantages. Invest firmware development capabilities to counter building automation vendors encroaching on specification influence.
For New Entrants and Emerging Players: India's Maharashtra and Karnataka urban housing markets offer underpenetrated white-space for modular cabinet fittings and soft-close drawer systems among first-time middle-class homeowners. Bypass traditional two-step distribution through direct-to-contractor digital platforms bundling hardware with installation support. Target BIS certification gaps among unbranded importers to establish quality positioning.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with neglected hardware divisions lacking smart building integration capabilities. Five-to-ten year viability favors platforms combining mechanical precision with embedded systems engineering. Monitor pro-dealer platform consolidation rates in Sun Belt metropolitan markets as inflection indicator for distribution channel power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Die-Casting | Captive supply of precision-machined components insulates margins from London Metal Exchange volatility. |
| Smart Building Platform Partnership | Electronic access control integration with Allegion and ASSA ABLOY ecosystems penetrates IT director specification channels. |
| REACH-Compliant Plating Investment | In-house trivalent chrome and PVD finishing operations control European export compliance documentation. |
| Pro-Dealer Digital Platform Launch | Direct contractor relationships in Dallas-Fort Worth and Atlanta bypass traditional distributor markups. |
| India Distribution Infrastructure Buildout | Mumbai and Bangalore logistics nodes capture urban housing stock expansion in Maharashtra and Karnataka. |
Methodological Framework
A spread of perspectives from hardware manufacturing executives, pro-dealer platform operators, facilities managers at Class-A commercial developments, and renovation contractors converged on the working assumptions underlying demand projections. Primary interviews with specification architects and EPA-certified renovation contractors were cross-referenced against secondary validation from customs trade data, ANSI/BHMA certification registries, and SEC filings of publicly traded hardware platforms. Bottom-up SKU-level demand modeling and top-down construction spending allocation were triangulated to anchor volume estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, with residential renovation cycle timing, commercial construction starts, and smart building adoption curves serving as primary demand drivers. Segmentation dimensions modeled included product type, material grade, application context, and distribution channel strategy. CAGRs were derived from regression analysis against historical replacement patterns and forward construction indicators, incorporating zinc price elasticity and certification timeline constraints as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by building automation vendors or sudden REACH enforcement escalations would shift outcomes beyond modeled ranges. Cross-checking against Dodge Construction Network residential renovation indices and American Institute of Architects billings data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
United States Wall Covering and Wall Decor Market
Homecare and Decor
Asia-Pacific Decorative Laminates Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
US Bamboos Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
US Wallpaper Market
Homecare and Decor
Bookends Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
Door Handles Market
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
Europe Decorative Laminates Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
Bamboo Panels Market
Homecare and Decor
Wall Art Market