
 Terracotta Pots Market | 2026-2036
Terracotta Pots Market Size, Share, and Industry Trends Forecast 2026-2036
Terracotta Pots Market Insights
Vietnam's artisan manufacturing belt is reconfiguring supply dynamics for handcrafted terracotta vessels. Campania International leverages its Italian design heritage to sustain premium positioning across North American garden retail. Bergs Potter anchors European demand through Danish aesthetic codes and frost-resistant formulations. Xiamen Roommu Horticulture Co., Ltd. competes on scale, operating integrated kilns that control clay preparation through finished export packaging.
Terracotta pots are unglazed or minimally glazed ceramic vessels fired from refined earthenware clay at temperatures between 900°C and 1100°C, prized for porosity that balances root aeration against moisture retention in horticultural applications. The planter segment dominates volume, though garden decor commands disproportionate margin pools through artisanal finishing and limited production runs. Landscape designers represent the fastest-growing end user category, as commercial and residential projects specify custom-finished vessels in hardscape plans. Online retailers now challenge brick-and-mortar stores in customer acquisition efficiency, though garden centers retain conversion advantages for bulk commercial orders.
EPA guidelines on kiln emissions shape manufacturing investments for US-bound production, while REACH and CE marking govern material safety and import access across European Union member states. BIS certification requirements in India create compliance barriers for unorganized sector producers seeking organized retail placement. Stakeholders must monitor evolving carbon accounting rules for ceramic firing processes, as scope-three disclosure obligations begin penetrating procurement criteria for large-scale landscaping contracts.
Market Dynamics
REACH compliance in the European Union is forcing manufacturers to abandon lead-based glazes and requalify entire clay sourcing networks, compressing margins for uncertified producers while rewarding those with vertically controlled supply chains.
Growth Catalysts
- Landscape designer procurement:Commercial and residential hardscape projects now specify custom-finished vessels as signature elements, pulling volume through specification rather than retail channels.
- REACH lead-free mandates:The European Union's chemical safety framework is eliminating non-compliant competitors and creating premium positioning for certified producers with documented supply chain transparency.
- Binh Duong artisan clustering:Vietnam's concentrated craft manufacturing belt achieves kiln efficiency and design flexibility that dispersed production cannot replicate.
Market Restraints
- Natural gas price volatility:Kiln firing costs swing with energy markets, compressing margins for producers without long-term fuel contracts or biomass alternatives.
- Single-province supply concentration:Vietnam's Binh Duong province hosts disproportionate handcrafted capacity, exposing buyers to weather, labor, and logistics disruptions in one geography.
- Frost resistance limitations:Traditional porous formulations crack in freeze-thaw cycles, excluding terracotta from northern climates without costly additive modifications.
Strategic Opportunities
- Indian organized retail penetration:BIS certification requirements have kept artisan producers out of modern trade, creating first-mover advantage for compliant entrants into garden center and e-commerce channels.
- Carbon accounting integration:Scope-three disclosure obligations in large landscaping contracts reward producers with measured, verifiable firing emissions data.
- Direct-to-consumer brand building:Digital-native labels bypass wholesale markups by sourcing directly from Binh Duong clusters, capturing margin pools previously retained by importers.
Industry Challenges
- Master craftsperson scarcity:Hand-throwing and traditional glaze formulation skills are aging out of the workforce faster than training programs replace them.
- Multi-jurisdiction certification timelines:Simultaneous EPA, REACH, and BIS compliance requires parallel testing protocols that extend product launch cycles by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terracotta Pots Market |
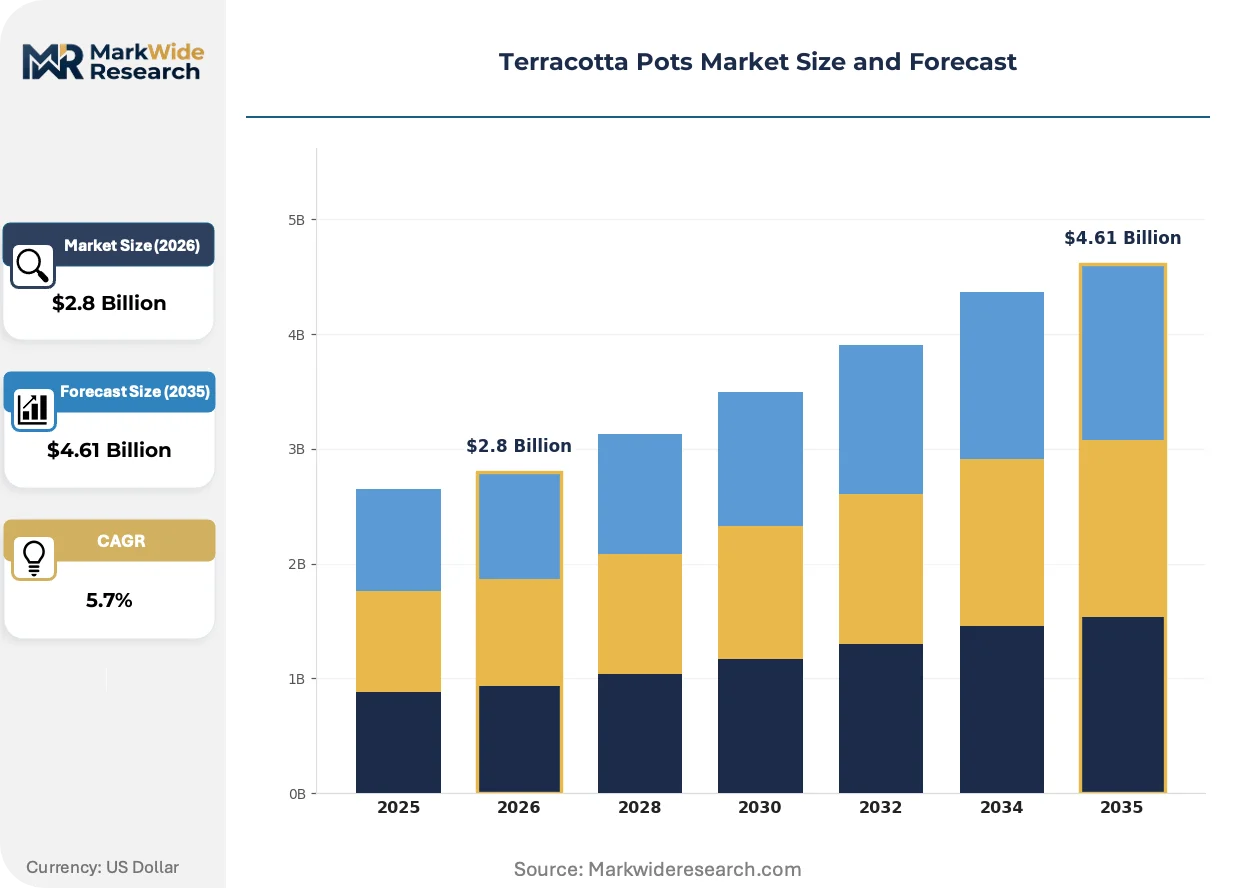
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Planters, Bowls, Garden Decor, Accessories Application: Indoor Use, Outdoor Gardening, Landscaping, Home Decor End User: Retail Consumers, Nursery Operators, Landscape Designers, Wholesale Distributors Distribution Channel: Online Retailers, Brick-and-Mortar Stores, Garden Centers, Direct Sales |
| Companies Covered | Ceramo Company, Campania International, Bergs Potter, Hawkins New York, Xiamen Roommu Horticulture Co., Ltd., The Terracotta Pot Company, The Pottery Patch, West Elm, Tuscan Imports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terracotta Pots Market Trends and Innovations
Formulation chemistry and distribution architecture are the twin levers reshaping competitive position, with regulatory pressure on material safety converging with channel fragmentation to reward producers who control both laboratory and logistics.
Low-temperature salt glazing is migrating from studio pottery to scaled horticultural production. This technique fuses sodium vapor to clay surfaces at 1100°C rather than 1200°C, cutting fuel consumption. Landscape contractors in Germany and the Netherlands are specifying salt-glazed vessels for municipal projects. The process is migrating from artisan demonstration to industrial kiln scheduling, compressing the cost gap between studio and factory output.
EPA kiln emission standards are tightening particulate and NOx limits for ceramics production serving the US market. Manufacturers must install baghouse filtration or regenerative thermal oxidizers, adding capital intensity. Producers with captive Vietnamese or Portuguese facilities are consolidating US-bound volume through upgraded lines while maintaining legacy capacity for less regulated destinations.
Online retailers now capture customer acquisition for terracotta vessels through visual search and garden design content, though garden centers retain conversion for bulk commercial orders. The disintermediation is most visible in North American residential landscaping, where designers discover products digitally but negotiate pricing through established wholesale relationships. This hybrid path is compressing traditional importer margins while rewarding brands with direct factory relationships and domestic warehousing.
Terracotta Pots Market Segmentation
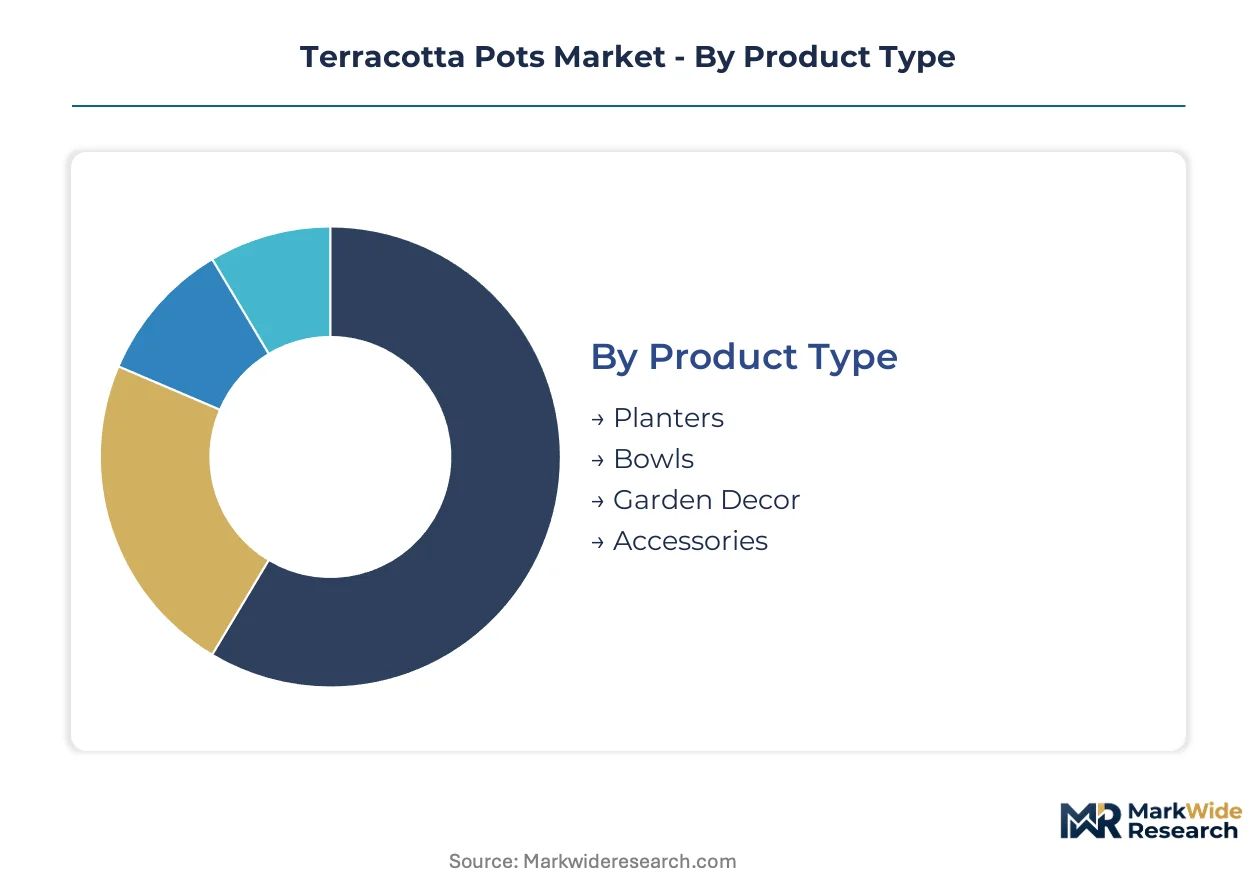
Segmentation in terracotta pots reveals how procurement channels, end-use specifications, and distribution economics fragment what appears as a commodity category. Understanding these divides exposes where margin pools concentrate and which customer relationships command pricing power.
Product Type:
Cost tiers separate utilitarian vessels from decorative objects, with firing temperature and finishing labor driving the wedge between production economics.
- Planters:Standard cylindrical and tapered vessels fired at 900-1100°C with minimal surface treatment. Nursery operators in Vietnam's Binh Duong province specify these in 40-foot container volumes for North American garden center replenishment.
- Bowls:Wide-mouthed, shallow-profile containers demanding precise clay consistency to prevent warping during firing. Landscape designers in Germany and the Netherlands are specifying salt-glazed bowls for municipal hardscape installations.
- Garden Decor:Sculptural and ornamental pieces with applied relief work, custom patinas, or limited-edition glazes. Artisans command 3-5x unit premiums over functional equivalents through direct-to-consumer channels.
- Accessories:Saucers, pot feet, and drainage components typically bundled with premium vessel sales or sold as replacement parts.
Planters hold installed capacity. Garden Decor is rotating up the share rankings.
Application:
Volume concentration tracks climate exposure and frost-risk tolerance, with geographic latitude determining specification intensity.
- Indoor Use:Climate-controlled environments permit traditional porous formulations without freeze-thaw additives. Retail consumers in North American and European urban apartments drive replacement cycles through seasonal redecorating.
- Outdoor Gardening:Residential patio and balcony applications requiring frost-resistant formulations for northern latitudes. REACH-compliant lead-free glazes are mandatory for European Union market access.
- Landscaping:Commercial and residential hardscape integration with specification-driven procurement. Landscape designers represent the steepest expansion trajectory as custom-finished vessels become signature project elements.
- Home Decor:Interior styling applications where aesthetic finish supersedes horticultural function. Danish and Italian design codes anchor premium positioning in this segment.
Outdoor Gardening holds installed capacity. Landscaping is rotating up the share rankings.
End User:
Customer type determines whether procurement flows through wholesale intermediaries or bypasses them for direct factory relationships.
- Retail Consumers:Individual purchasers acquiring single units or small sets through digital channels or garden centers. Visual search and content marketing now dominate discovery for this segment.
- Nursery Operators:Commercial growers requiring volume consistency and root-zone porosity specifications. These buyers negotiate annual contracts with Vietnamese clusters for containerized shipping.
- Landscape Designers:Specification professionals embedding vessels in hardscape plans. This segment is climbing the fastest as designers pull volume through project-based procurement rather than retail channels.
- Wholesale Distributors:Traditional importers and regional wholesalers managing inventory and logistics for garden center networks. Margin compression from direct-to-consumer brands is eroding their role in premium segments.
Nursery Operators hold installed capacity. Landscape Designers is rotating up the share rankings.
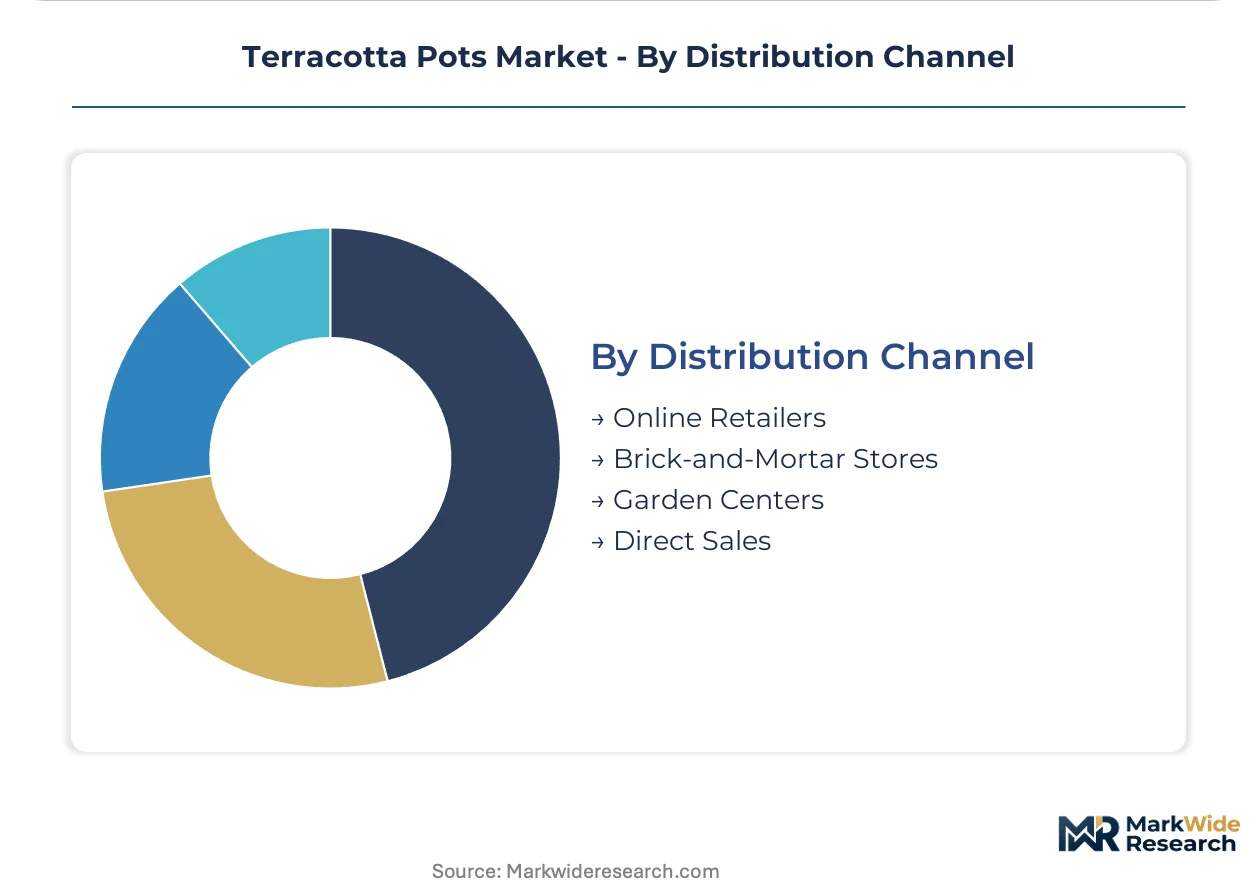
Distribution Channel:
Channel selection determines whether customer acquisition or order conversion dominates the commercial equation.
- Online Retailers:Digital-native platforms capturing discovery through visual search and garden design content. These channels excel at customer acquisition but struggle with bulk commercial order fulfillment.
- Brick-and-Mortar Stores:General merchandise and home improvement retailers with seasonal garden center displays. Foot traffic dependency creates inventory risk for slow-moving artisan pieces.
- Garden Centers:Specialized horticultural retailers retaining conversion advantages for bulk commercial orders. Landscape designers negotiate pricing through established wholesale relationships here.
- Direct Sales:Factory-direct relationships between Binh Duong artisan clusters and North American direct-to-consumer brands. This channel compresses traditional importer margins while capturing previously retained markups.
Garden Centers hold installed capacity. Direct Sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Binh Duong province in Vietnam concentrates handcrafted terracotta manufacturing capacity, with artisan clusters supplying both European and North American demand channels. This geographic concentration shapes procurement patterns and exposes buyers to single-source risks.
United States
Landscape designers in California and Florida drive specification-driven demand for custom-finished vessels in residential hardscape projects. EPA kiln emission standards tighten particulate and NOx limits for ceramics production, forcing facility upgrades. Texas and Arizona host distribution hubs that warehouse Vietnamese imports for domestic fulfillment.
Germany
Municipal landscaping contracts in North Rhine-Westphalia specify salt-glazed terracotta bowls for public hardscape installations. REACH mandates eliminate lead-based glazes from EU market access, favoring certified producers with documented supply chain transparency. Bavaria's garden center networks anchor wholesale procurement for central European distribution.
Vietnam
Binh Duong province's artisan belt achieves kiln efficiency and design flexibility through concentrated craft manufacturing. The country's export-oriented ceramics sector benefits from trade agreements with European and North American markets. Ho Chi Minh City logistics corridors containerize finished goods for direct-to-consumer brands bypassing traditional importers.
Italy
Design heritage anchors premium positioning for Italian-branded vessels in North American garden retail. Tuscany and Umbria maintain traditional throwing and glazing techniques for limited-production decorative pieces. Campania International leverages this aesthetic coding to sustain margin premiums against scaled Asian competition.
Denmark
Frost-resistant formulations from Danish producers penetrate northern European climates where traditional porous terracotta fails. Bergs Potter anchors demand through minimalist aesthetic codes and technical specifications for freeze-thaw durability. Copenhagen design influence extends through Scandinavian retail networks into German and Dutch markets.
Terracotta Pots Market Competitive Landscape
Design-heritage specialists and scale-driven manufacturers split the market into distinct competitive arenas. The vendor base clusters around three strategic archetypes: artisan-cluster sourcers with direct factory relationships, European design houses leveraging aesthetic premiumization, and integrated kiln operators controlling clay preparation through export packaging. Consolidation pressures favor players with captive Vietnamese supply or certified REACH compliance, while margin compression erodes traditional importer-distributor roles.
Among North American design-forward retailers, Hawkins New York and West Elm occupy positions that bridge artisan sourcing with domestic brand building. Campania International exemplifies the European heritage archetype, translating Italian aesthetic codes into premium garden retail placement. Xiamen Roommu Horticulture Co., Ltd. represents the integrated manufacturing tier with captive kiln capacity and export logistics control.
| Leading Market Players |
|---|
| Ceramo Company |
| Campania International |
| Bergs Potter |
| Hawkins New York |
| Xiamen Roommu Horticulture Co., Ltd. |
| The Terracotta Pot Company |
| The Pottery Patch |
| West Elm |
| Tuscan Imports |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Vietnam's Binh Duong artisan belt compresses supplier pricing power while REACH compliance investments elevate entry barriers for uncertified competitors. Kiln utilization rates below optimal thresholds force producers into volume discounting for North American garden center contracts, while certified suppliers capture premium positioning in European direct-to-consumer channels.
Pricing Analysis
REACH dictates the pricing tier structure across European Union market access, separating certified lead-free glaze producers from excluded competitors. Three-tier pricing stratifies across artisan-limited garden decor, frost-resistant landscape specifications, and standard planter volumes. Cost compression in utility-grade planters intensifies because Binh Duong cluster competition erodes margins. Nursery operators exhibit highest price sensitivity through annual contract negotiations, while landscape designers accept premiums for custom-finished signature vessels.
Supply Chain Analysis
Export-control regimes on ceramic kiln technology limit Vietnamese producers from accessing advanced emission-control equipment without European licensing. Supply concentrates in Vietnam, Italy, and Denmark, with Binh Duong hosting disproportionate handcrafted capacity. Production draws from refined earthenware clay deposits, natural gas firing inputs, and lead-free glaze formulations. Single-province vulnerability exposes buyers to weather and logistics disruptions in one geography. Distribution runs through direct factory relationships, garden center wholesale networks, and digital-native brand channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The terracotta pots market is recovering from cyclical lows as residential landscaping investment rebounds from pandemic-era project deferrals. Specification-driven procurement from landscape designers is rotating volume through project channels rather than retail replenishment cycles.
For Market Incumbents: Insulate margin pools by deepening backward integration into Binh Duong kiln capacity and accelerating REACH certification documentation for European garden center placement. Direct-to-consumer brand entrants threaten traditional importer markups; captive Vietnamese supply relationships and domestic warehousing infrastructure defend pricing power against disintermediation pressure.
For New Entrants and Emerging Players: Establish a beachhead in India's organized retail channels where BIS certification barriers have excluded artisan competitors from modern trade penetration. Salt-glazed municipal landscaping specifications in Germany and the Netherlands represent the most penetrable application segment. A go-to-market angle through carbon-accounting disclosure for scope-three procurement criteria differentiates against incumbent opacity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EPA-compliant kiln retrofit requirements for US-bound production. Long-term viability favors vertically integrated operators with captive Vietnamese supply and certified European market access. Acquisition targets should demonstrate documented supply chain transparency and frost-resistant formulation capabilities. The signal to watch is natural gas contract coverage duration as fuel price volatility reshapes producer economics.
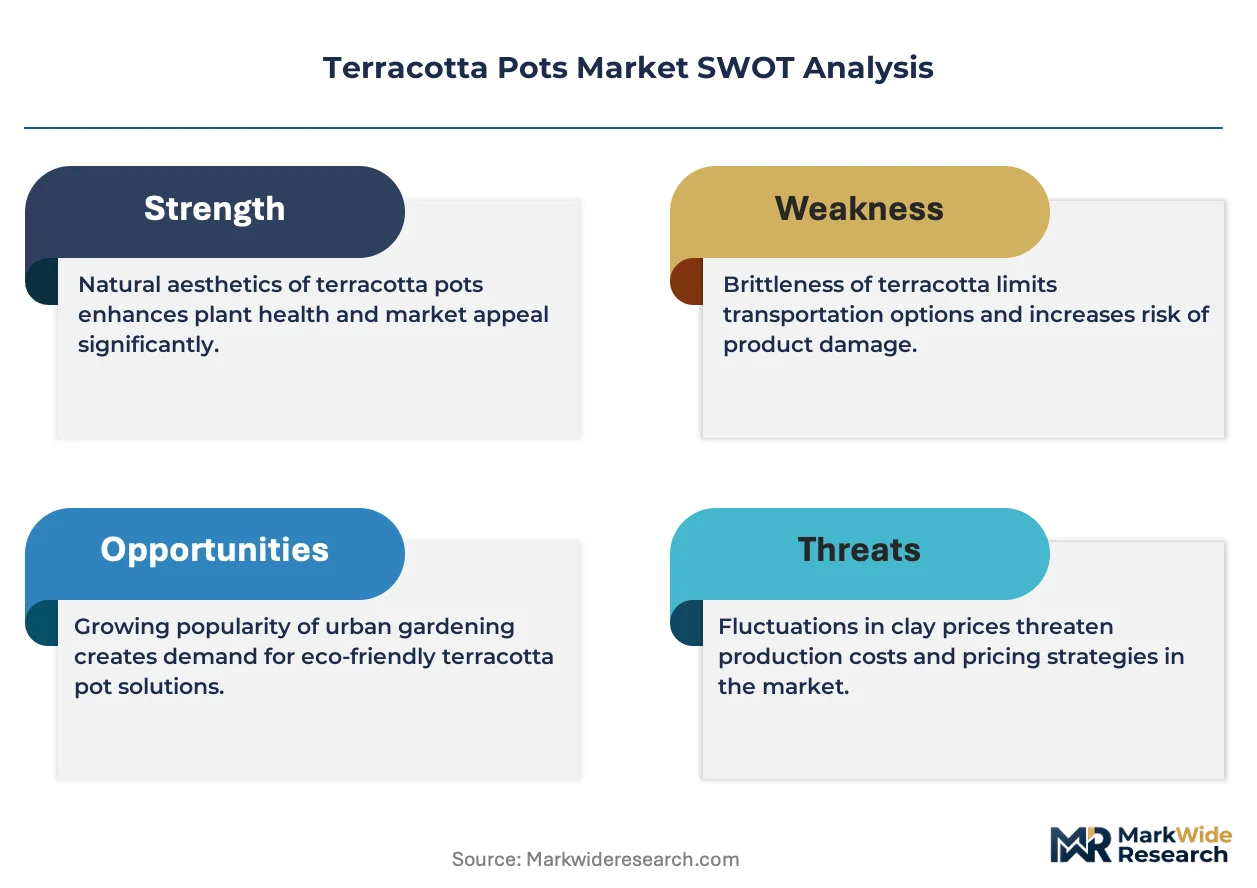
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Investment | Lead-free glaze documentation unlocks European Union garden center and direct-to-consumer channel access. |
| Backward Integration into Binh Duong Kiln Capacity | Captive Vietnamese supply compresses unit costs and insulates against importer margin erosion. |
| Salt-Glazed Product Line Expansion | Low-temperature municipal specifications in Germany and Netherlands open specification-driven procurement volume. |
| Carbon Accounting Disclosure Program | Measured firing emissions data satisfies scope-three requirements in large landscaping contracts. |
| Direct-to-Consumer Brand Launch | Digital-native channels bypass wholesale markups and capture margin pools from traditional importers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with landscape designers, nursery procurement managers, Binh Duong artisan cluster representatives, and European garden center category buyers. Secondary validation drew from EPA kiln emission filings, REACH compliance registries, Vietnamese customs export data, and horticultural trade association publications. Bottom-up volume estimates from producer capacity and top-down demand calibration from end-user specification trends were triangulated for convergence.
Calibration against historical shipment data and disclosed capacity utilization rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application climate exposure, end-user procurement channel, and distribution architecture. CAGRs were derived from regression analysis of volume drivers against macroeconomic indicators and regulatory implementation timelines. Forecast inputs incorporated natural gas price scenarios and artisan labor availability projections from vocational training program data.
Sensitivities concentrate around energy price volatility, Binh Duong logistics disruptions, and REACH enforcement intensity variations across member states. Forecasts reflect documented assumptions on kiln efficiency improvements and certification adoption curves. Material shifts in EPA emission standards implementation or Vietnamese trade agreement terms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Wall Covering and Wall Decor Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
United States Decorative Laminates Market
Homecare and Decor
Middle East and Africa Christmas Tree Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
Corner Pads Market
Homecare and Decor
France Steam Rooms Market
Homecare and Decor
Wall Art Market
Homecare and Decor
Smart Curtain Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
Global Decorative Laminates Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
Door Handles Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
India Interior Design Market
Homecare and Decor
US Mattress Bases Market