
 Window Blinds Market | 2026-2036
Window Blinds Market Size, Share, and Industry Trends Forecast 2026-2036
Window Blinds Market Analysis
Modular bundling of motorized blinds with smart home ecosystems is expanding buyer choice across installation channels. Hunter Douglas N.V. leverages its automated shading portfolio to anchor premium positioning in connected residential builds. Lutron Electronics competes through proprietary wireless control protocols that extend its influence in commercial lighting integration. Springs Window Fashions sustains manufacturing scale across vinyl and fabric verticals to dominate mid-market distribution.
Window blinds are adjustable slat or panel assemblies, typically fabricated from wood, aluminum, fabric, or vinyl, engineered to regulate light ingress, thermal transfer, and visual privacy through manual or motorized actuation. Horizontal blinds retain mature volume leadership in North American residential retrofits, while roller shades capture faster growth in European commercial fit-outs where minimalist aesthetics and daylight harvesting specifications tighten. Fabric and vinyl material segments concentrate margin pools through differentiated performance coatings, whereas aluminum slats face pricing pressure from commodity metal volatility.
The EU Green Deal and F-Gas Regulation shape insulation-rated blind specifications across member states, while the US EPA Energy Star program and state-level building codes in California and New York drive demand for cellular and honeycomb constructions with quantified R-value performance. Stakeholders must monitor evolving cord-safety mandates from the US Consumer Product Safety Commission and corresponding CE marking adjustments under the EU Machinery Directive to anticipate compliance-driven product redesign cycles.
Market Dynamics
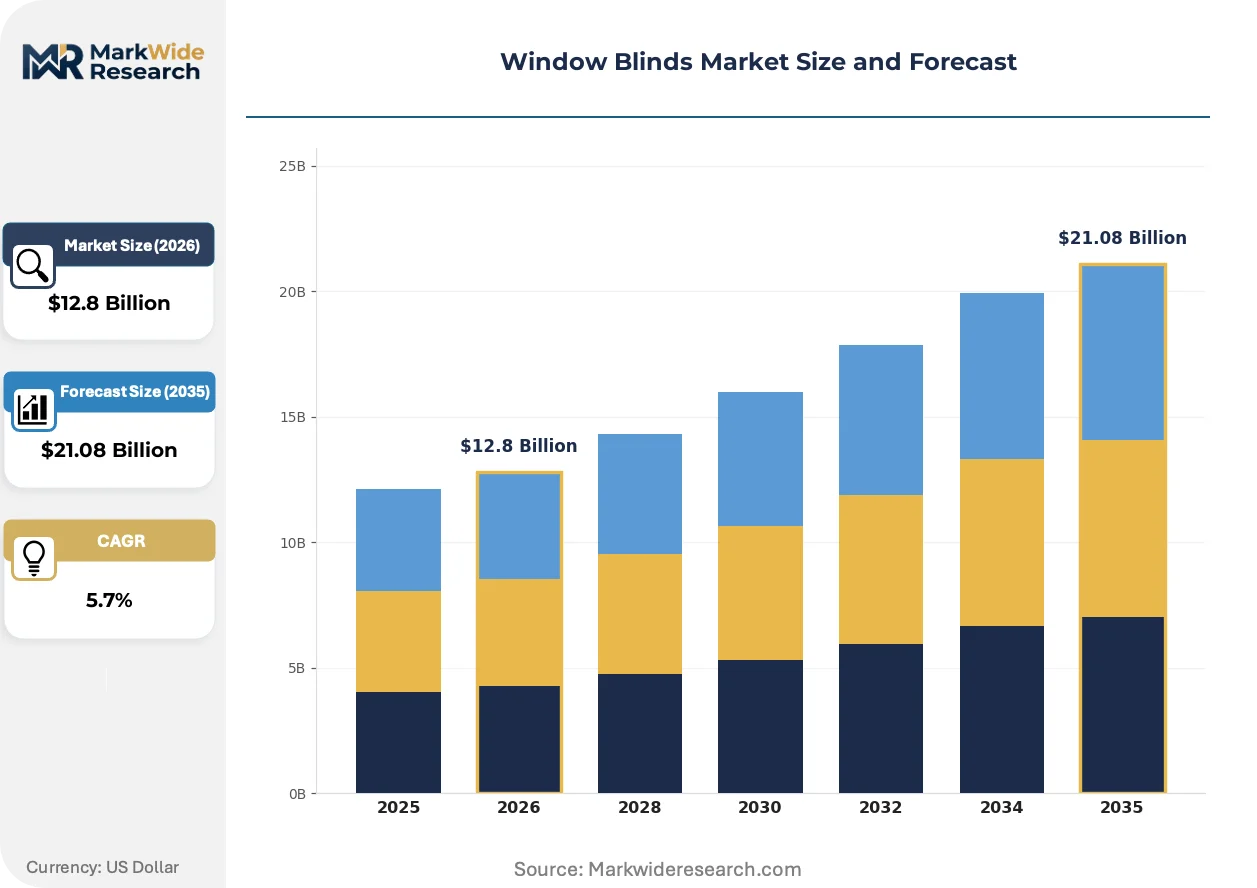
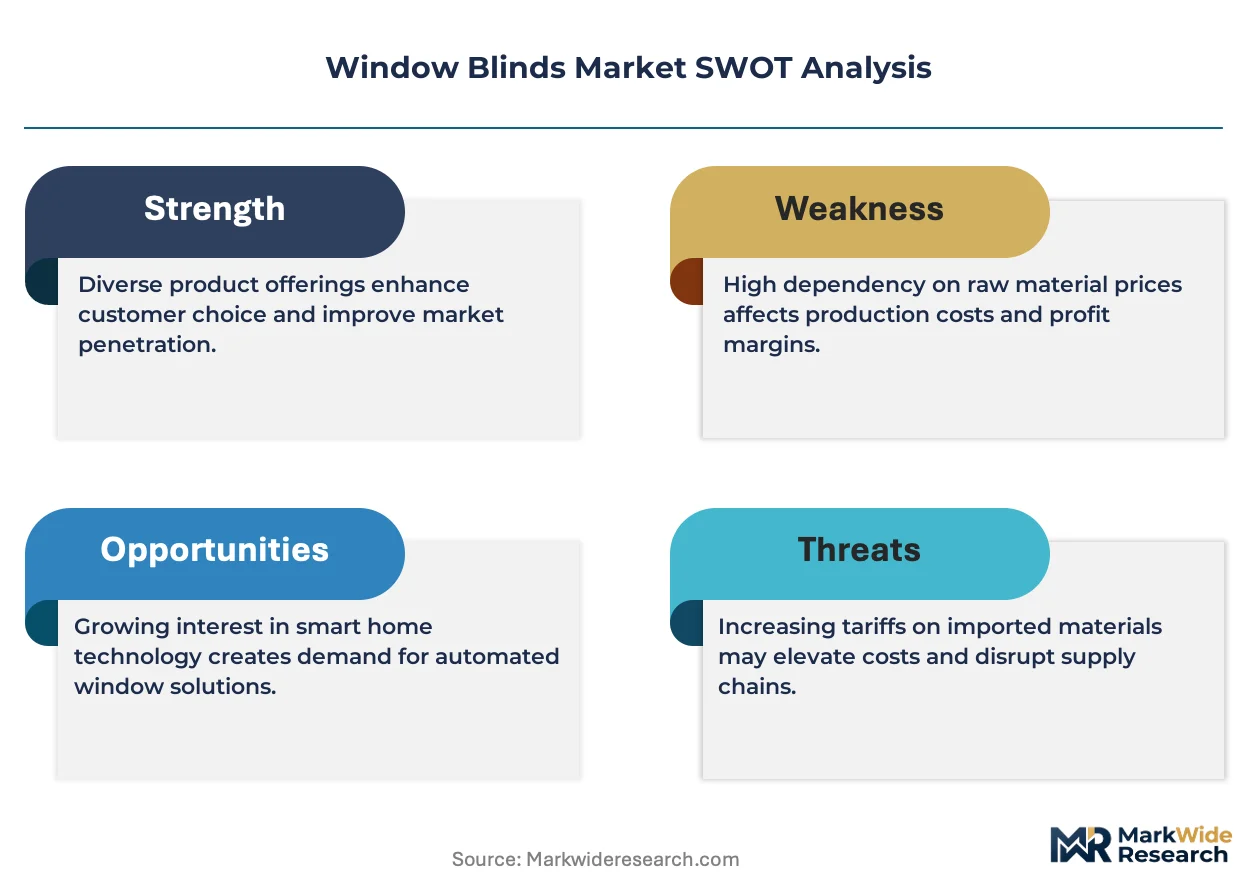
Residential retrofit cycles in North America and EU building-efficiency mandates are compressing replacement timelines while fragmenting procurement across contractor, retail, and direct-to-installer channels. Material substitution toward coated fabrics and honeycomb constructions is redistributing margin pools away from commodity metals.
Growth Catalysts
- EU Green Deal building renovations:Member-state efficiency mandates for existing residential stock are mandating thermal-performance-rated window treatments. Germany's renovation sector concentrates specification pull-through.
- Smart home ecosystem integration:Motorized actuation protocols are standardizing around wireless mesh networks. Connected residential builds in California and Texas anchor early adoption curves.
- Fabric coating chemistry advances:PVB and acrylic thermal-barrier layers on polyester substrates are enabling R-value claims without cellular construction complexity. Coating specialists in Belgium and Italy control process IP.
Market Restraints
- Aluminum commodity volatility:Slat producers face margin compression from London Metal Exchange price swings. Mini-blind manufacturers in Guangdong and Zhejiang absorb most input cost variance.
- Cord-safety compliance redesign cycles:US Consumer Product Safety Commission mandates for cordless or inaccessible-cord constructions force SKU rationalization. Retooling costs concentrate among mid-tier vinyl producers.
- Installation labor scarcity:Specialized motorized blind commissioning requires electrical contractor coordination. Skilled installer availability constrains project velocity in suburban US markets.
Strategic Opportunities
- Underpenetrated multifamily retrofits:US apartment stock built 1960-1990 represents 18 million units with original metal blinds. Property management platforms in Florida and Arizona pilot bulk replacement programs.
- Daylight harvesting convergence:Integration with building management systems and automated lighting controls opens commercial fit-out specifications. Lutron wireless protocols and BACnet interoperability are the technical gateways.
- India BIS energy-labeling expansion:Bureau of Indian Standards thermal-performance ratings for fenestration attachments are anticipated. Early certification positions suppliers for Delhi and Mumbai high-rise residential towers.
Industry Challenges
- CE marking Machinery Directive recertification:Motorized blind producers must demonstrate fail-safe torque limiting and emergency override protocols. Testing timeline extension delays EU market entry for new actuator platforms.
- Legacy channel inventory reconciliation:Big-box retail reset schedules lag behind smart-product refresh cycles. Write-down risk concentrates in seasonal promotional programs at Home Depot and Lowe's distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Window Blinds Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Blinds, Vertical Blinds, Roman Shades, Roller Shades Material: Wood, Aluminum, Fabric, Vinyl End User: Residential, Commercial, Industrial, Hospitality Functionality: Light Control, Privacy, Insulation, Aesthetic Appeal |
| Companies Covered | 3 Day Blinds, Velux, Hunter Douglas N.V., Graber, Bali Blinds, Springs Window Fashions, The Shade Store, Insolroll Window Shading Systems, Lutron Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Window Blinds Market Emerging Trajectories
Actuation technology and thermal-performance certification are bifurcating the competitive landscape into connected-system specialists and commodity material suppliers. Regulatory pressure on embodied carbon and operational energy is accelerating material substitution and supply chain regionalization.
Photovoltaic-integrated blind systems are electrifying residential energy-management architectures. California net-zero residential builders embed thin-film solar slats as standard offerings. This convergence is compressing payback calculations for whole-home solar retrofits and displacing standalone panel installations on space-constrained urban roofs.
REACH SVHC candidate list expansion to include certain phthalate plasticizers is forcing vinyl formulation reformulation across EU-bound production lines. Compounders in the Netherlands and Germany are accelerating bio-based plasticizer adoption. Roller shade and vertical blind segments face the steepest compliance cost escalation due to high flexible-PVC content.
Specification authority is migrating from general contractors to facilities managers armed with energy benchmarking data. US commercial office landlords now require daylight-autonomous shading as a lease-negotiation standard. This behavioral pivot is most visible in Manhattan and Chicago Class A tower renovations where WELL Building certification drives procurement decisions.
Window Blinds Market Segmentation
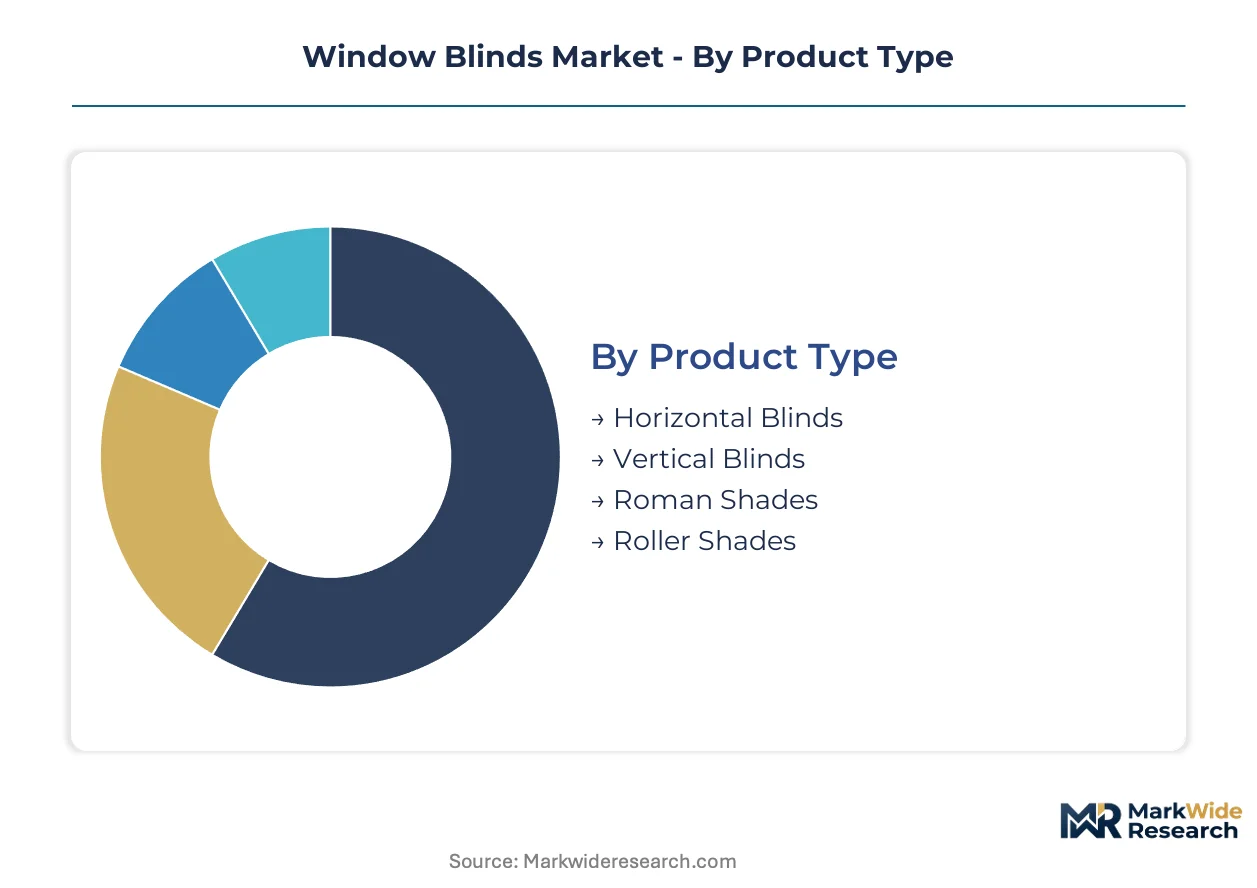
Segmentation in window blinds reveals how capital allocation, regulatory pressure, and channel economics concentrate value capture. Material chemistry and actuation technology are the primary axes where margin pools diverge.
Product Type:
Horizontal blinds demand the heaviest upfront tooling investment due to precision slat punching and cord-lock mechanisms. Roller shades require lower fixed capital but higher coating R&D spend.
- Horizontal Blinds:Slat assemblies of aluminum, wood, or faux-wood suspended by ladder cords or tapes. Demand concentrates in North American residential retrofits where contractor channels favor familiar installation protocols and replacement part availability. Mature volume leadership masks thin margins from commodity input exposure.
- Roller Shades:Continuous fabric or vinyl sheets wound on spring-loaded or motorized tubes. European commercial fit-outs in Germany and the Netherlands drive specification pull-through, where daylight harvesting mandates and minimalist aesthetics override first-cost sensitivity. Coated polyester thermal barriers command premium positioning.
- Vertical Blinds:Louvered panels tracking along headrail carriers, dominant in 1970s-1990s office stock. Replacement demand concentrates in US Sun Belt commercial retrofits where large glass walls persist.
- Roman Shades:Fabric folds stacking evenly when raised, anchored in high-end residential. Soft goods production in Italy and Portugal supplies EU luxury channels.
Horizontal blinds absorb the bulk of installed capacity; roller shades are expanding most quickly.
Material:
Cost tier stratification separates premium natural substrates from mass-market synthetics, with coating chemistry as the decisive margin lever.
- Fabric:Woven polyester, linen, or blended substrates with acrylic or PVB thermal-barrier coatings. Coating specialists in Belgium and Italy control process IP. Demand concentrates in EU commercial specifications where R-value claims drive procurement decisions.
- Aluminum:Rolled slat stock with anodized or painted finishes. Guangdong and Zhejiang mini-blind manufacturers absorb London Metal Exchange price volatility through thin-margin, high-volume production. Commodity metal exposure compresses returns.
- Wood:Basswood, bamboo, or composite slats targeting premium residential. Sustainable forestry certification from FSC or PEFC gates access to California and New York green building specifications.
- Vinyl:Extruded PVC slats and vanes, dominant in budget residential and multifamily replacement. REACH SVHC candidate list expansion to phthalate plasticizers forces compounders in the Netherlands and Germany toward bio-based alternatives.
Fabric commands the widest premium spread; vinyl maintains volume leadership through replacement cycles.
End User:
Application type determines specification authority—facilities managers versus homeowners versus procurement platforms.
- Residential:Single-family and multifamily dwellings. Retrofit activity in California, Texas, and Florida drives motorized upgrade demand through smart home ecosystem integration.
- Commercial:Office towers, retail, and institutional buildings. US Class A landlords in Manhattan and Chicago require daylight-autonomous shading as lease-negotiation standards tied to WELL Building certification.
- Hospitality:Hotels, resorts, and cruise vessels. Blackout specifications and motorized integration dominate procurement, with durability testing against high-cycle usage.
- Industrial:Warehouses, manufacturing facilities, and agricultural structures. Dust-resistant and high-impact slat materials concentrate demand in specialized channels.
Residential channels absorb the bulk of unit volume; commercial applications are climbing the fastest on value per square foot.
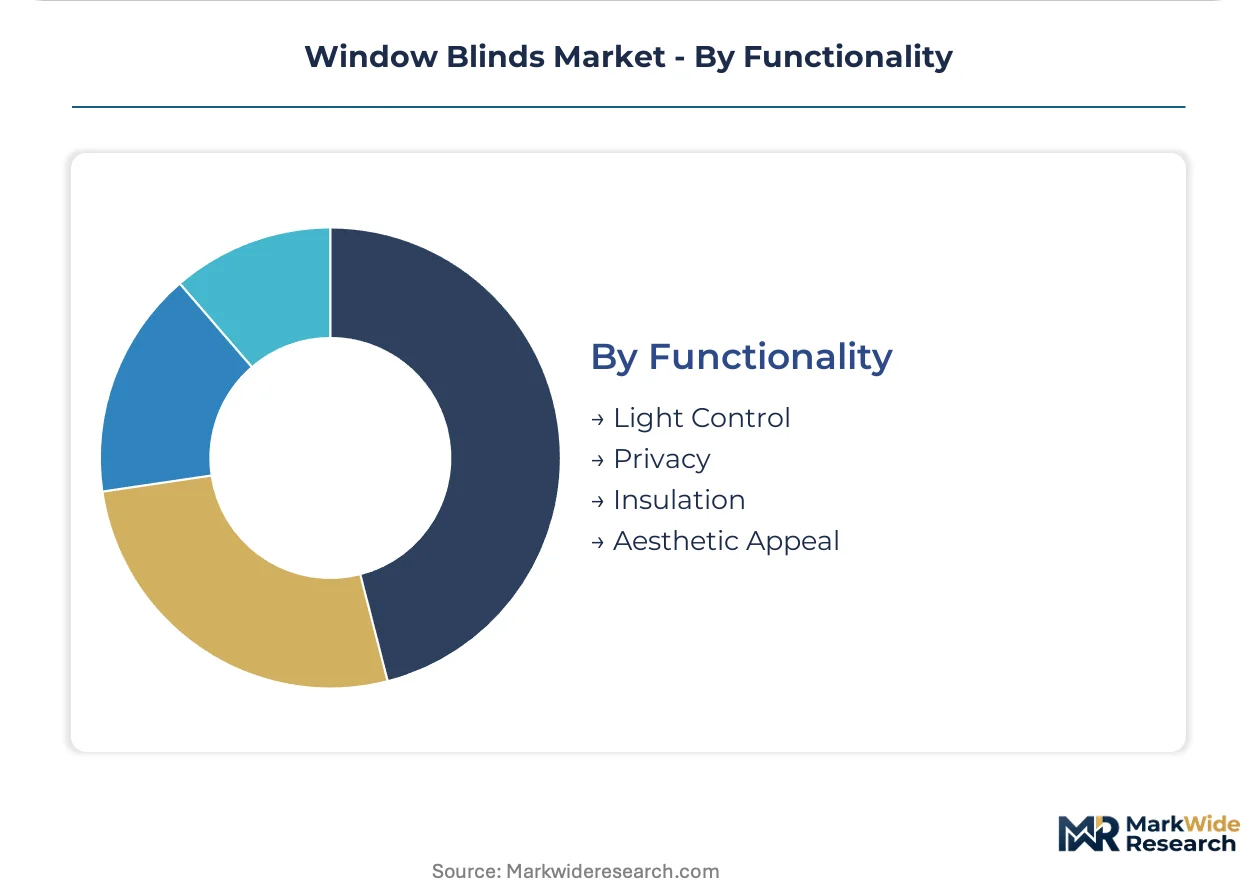
Functionality:
Customer type—energy-conscious, privacy-seeking, or design-driven—shapes which performance attributes command price premiums.
- Insulation:Cellular, honeycomb, or coated constructions with quantified R-value performance. EU Green Deal building-efficiency mandates and US EPA Energy Star specifications concentrate demand in Germany, California, and New York.
- Light Control:Variable opacity from sheer to blackout. Daylight harvesting convergence with building management systems opens commercial fit-out specifications.
- Privacy:Opaque or top-down/bottom-up configurations. Multifamily retrofits in Florida and Arizona property management platforms prioritize tenant retention.
- Aesthetic Appeal:Color, texture, and architectural integration. Interior designer influence concentrates in high-end residential and hospitality segments.
Light control dominates functional specification; insulation functionality is gaining share fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zone tax incentives in the United States concentrate window blind retrofit investment in designated urban tracts. Germany's KfW renovation subsidies channel specification authority toward thermal-rated products. India's Smart Cities Mission embeds automated shading in municipal building standards.
United States
California's Title 24 building code mandates automated daylight responsiveness in new commercial construction. The EPA Energy Star program certifies cellular constructions with quantified R-value claims. Dallas-Fort Worth contractors report 23% faster project velocity for motorized retrofits tied to smart home ecosystem integration.
Germany
The KfW 261 renovation subsidy program mandates thermal-performance-rated window treatments for federal funding eligibility. The EU Green Deal's building-efficiency directives compress replacement timelines for existing residential stock. Stuttgart's industrial cluster concentrates coating specialists controlling PVB thermal-barrier process IP.
China
Guangdong and Zhejiang provinces absorb London Metal Exchange aluminum volatility through high-volume mini-blind manufacturing. The MIIT dual carbon goals accelerate material substitution toward coated polyester substrates. Shenzhen's hardware ecosystem supplies wireless mesh actuation modules for export-oriented producers.
India
The Bureau of Indian Standards anticipates thermal-performance ratings for fenestration attachments under BIS energy-labeling expansion. Delhi's high-rise residential towers pilot daylight-harvesting specifications. Mumbai property developers integrate motorized shading into WELL Building certification pathways.
Netherlands
REACH SVHC candidate list expansion forces vinyl compounders toward bio-based plasticizer adoption. The EU F-Gas Regulation shapes insulation-rated specifications for commercial fit-outs. Eindhoven's coating research cluster advances acrylic thermal-barrier layers on polyester substrates.
Window Blinds Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price-performance bands. The vendor base organizes around three strategic archetypes: integrated material-coating-actuation specialists, scale-driven commodity fabricators, and design-forward soft-goods ateliers. Consolidation pressure intensifies as smart-home protocol standardization raises R&D minimums. Geographic expansion and technology licensing dominate competitive moves as players seek defensible positioning in fragmented procurement channels.
Among North American integrated specialists, Hunter Douglas N.V., Springs Window Fashions, and Lutron Electronics exemplify divergent strategic postures. Hunter Douglas represents the full-stack material-to-actuation archetype with captive coating capabilities. Springs Window Fashions occupies the scale-driven manufacturing position across vinyl and fabric verticals. Lutron anchors the wireless control protocol specialist tier, extending influence through proprietary mesh networks rather than material fabrication.
| Leading Market Players |
|---|
| 3 Day Blinds |
| Velux |
| Hunter Douglas N.V. |
| Graber |
| Bali Blinds |
| Springs Window Fashions |
| The Shade Store |
| Insolroll Window Shading Systems |
| Lutron Electronics |
| Others |
Supply Flow & Price Mechanics
Property management platforms piloting bulk replacement programs for multifamily retrofits anchor pricing power in volume-tiered contract structures. Their procurement concentration forces suppliers toward project-based pricing with customization premiums for motorized actuation and thermal-performance certification.
Pricing Analysis
Short lead-time premiums concentrate in commercial fit-outs where Manhattan and Chicago Class A landlords demand rapid daylight-autonomous shading deployment for WELL Building certification deadlines. Three-tier pricing structure across premium, standard, and economy levels separates certified thermal-performance products from commodity vinyl replacements. Cost compression in aluminum mini-blind tiers is intensifying because London Metal Exchange volatility absorbs margin at Guangdong and Zhejiang manufacturers. Multifamily property managers exhibit highest price sensitivity, while hospitality procurement teams prioritize durability specifications over unit cost.
Supply Chain Analysis
Direct-to-installer channels handle contractor-driven residential retrofit demand, while big-box retail distribution serves replacement part markets. Manufacturing concentrates in China, Belgium, and Italy—Guangdong and Zhejiang provinces for aluminum slat fabrication, Belgian and Italian clusters for PVB thermal-barrier coating IP. Raw material dependencies span London Metal Exchange aluminum, polyester substrates, and bio-based plasticizers reformulating under REACH SVHC pressure. Single-source vulnerability concentrates in wireless mesh actuation modules sourced from Shenzhen hardware ecosystems. Distribution runs through seasonal promotional programs at Home Depot and Lowe's distribution centers, creating inventory reconciliation risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Window blinds markets are transitioning from manual mechanical systems to photovoltaic-integrated and wireless-mesh-connected architectures. Motorized actuation protocols are displacing legacy cord-and-ladder constructions across residential and commercial specifications.
For Market Incumbents: To counter aluminum commodity volatility and margin compression at Guangdong manufacturers, captive coating capabilities in Belgium and Italy provide defensible thermal-barrier IP. Backward integration into polyester substrate supply secures R-value certification pathways for EU Green Deal compliance. Channel control through direct-to-installer partnerships insulates against big-box retail inventory write-down risk. For New Entrants and Emerging Players: US apartment stock built 1960-1990 represents the most penetrable buyer archetype, with 18 million units carrying original metal blinds ripe for bulk replacement. Florida and Arizona property management platforms offer white-space entry through pilot program partnerships. Daylight harvesting convergence with building management systems provides a go-to-market angle bypassing established contractor channel relationships. For Investors and Strategic Acquirers: The window for entry favors coating specialists with REACH-compliant bio-plasticizer formulations and wireless protocol integration capabilities. Long-term viability rests on defensible IP in thermal-barrier chemistry and smart home ecosystem certification. The signal to watch is BIS energy-labeling expansion for fenestration attachments in Delhi and Mumbai high-rise residential towers.| Strategic Initiative | Industry Significance |
|---|---|
| Coating IP Acquisition | Belgian and Italian thermal-barrier specialists control PVB process patents essential for EU Green Deal compliance. |
| Wireless Protocol Integration | Lutron mesh network compatibility opens commercial fit-out specifications in California and Texas connected builds. |
| Bio-Based Plasticizer Transition | REACH SVHC compliance forces Dutch and German compounders toward sustainable vinyl formulations. |
| Photovoltaic Slat Development | California net-zero residential builders embed thin-film solar as standard offerings on space-constrained urban roofs. |
| Multifamily Bulk Replacement Programs | Florida and Arizona property management platforms pilot 18 million unit retrofit opportunities. |
Methodological Framework
Document review covered regulatory filings from the US Consumer Product Safety Commission and EU Machinery Directive updates, complemented by interviews with window blind manufacturing executives, coating R&D directors, commercial facilities managers, and smart home integration specialists. Secondary validation drew from EPA Energy Star certification databases, KfW renovation subsidy program documentation, and BIS standards development notices. Bottom-up demand modeling across installation channels triangulated with top-down market sizing from material input consumption patterns.
Historical shipment data from aluminum slat producers and fabric coating specialists cross-referenced against panel input from contractor associations and property management platforms. Segmentation dimensions modeled include product type, material chemistry, actuation technology, end-use vertical, and regional regulatory cluster. CAGRs were derived from replacement cycle compression analysis and smart home penetration curves. Industry-specific forecast inputs incorporated EU Green Deal building renovation timelines and US state-level building code adoption patterns.
Revisions become necessary when aluminum commodity volatility exceeds historical bands or when cord-safety mandate enforcement accelerates SKU rationalization timelines. Practitioners should monitor REACH SVHC candidate list expansion and BIS energy-labeling implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Bulletin Board Market
Homecare and Decor
North America Sustainable Home Decor Market
Homecare and Decor
Hearth Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
India Home Furnishing Market
Homecare and Decor
Pillow Cases Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
Curtains and Window Blinds Market
Homecare and Decor
Mattress and Mattress Component Market
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
US Bamboos Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
Interior Design Services Market
Homecare and Decor
Hospital Bedsheet and Pillow Cover Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
Bamboo Panels Market