
 Wall Covering and Wall Decor Market | 2026-2036
Wall Covering and Wall Decor Market Size, Share, and Industry Trends Forecast 2026-2036
Wall Covering and Wall Decor Market Insights
GREENGUARD Gold certification is bifurcating the supplier base into specification-grade and mass-market tiers. York Wallcoverings leverages its archival design library and domestic manufacturing to sustain premium positioning in North American hospitality channels. Asian Paints anchors its wall covering portfolio with integrated paint-and-texture systems that dominate India's branded home improvement retail. Sangetsu Corporation specializes in vinyl sheet and fabric-backed products, competing on fire-resistance ratings for Japanese commercial interiors.
Wall covering and wall decor encompasses surface treatments and ornamental elements applied to interior vertical planes, including paper-backed vinyl substrates with grammage ranging from 200–400 g/m², woven textile hangings, and engineered wood panels with tongue-and-groove mounting systems, serving functions from moisture protection to acoustic modulation and spatial branding. Wallpaper and wall panels command the deepest specification value pools in commercial and hospitality applications where fire-rated and scrubbable surfaces carry premium positioning. Paints in vinyl and low-sheen formulations remain the volume anchor across residential renovation, while fabric and metal materials occupy niche luxury and feature-wall segments with higher per-square-meter economics but constrained repeat purchase frequency.
FDA indirect food-contact surface guidelines, EPA VOC emissions standards under TSCA Title VI, and REACH SVHC restrictions on phthalate plasticizers collectively constrain adhesive and substrate formulations, pushing manufacturers toward water-based systems and bio-sourced polymers. ECHA's expanding candidate list for restricted substances is accelerating substitution cycles in European supply chains, while China's GB standards on interior decoration material harmful substance limits enforce parallel compliance investments for export-oriented producers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and qualify for green building certification schemes that increasingly govern project specification authority.
Market Dynamics
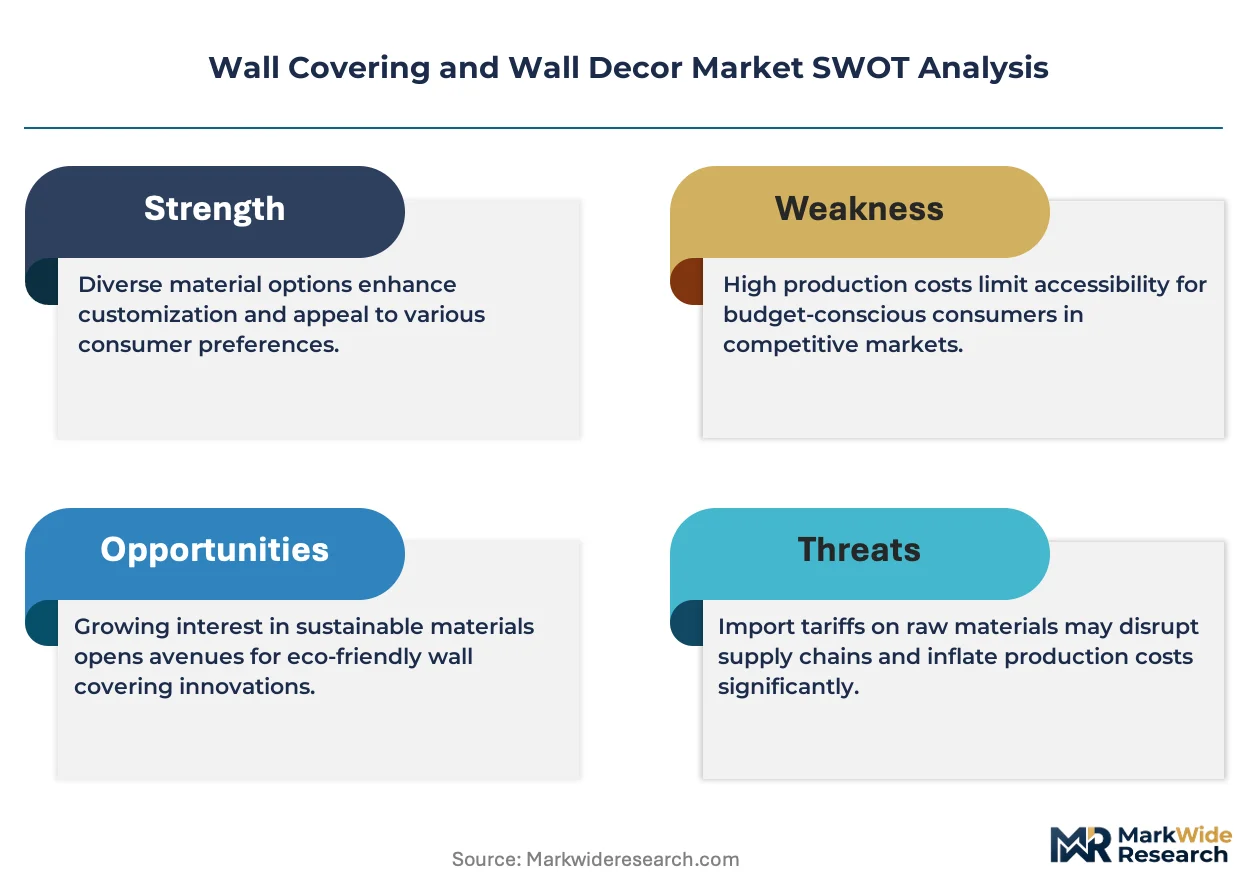
Hospitality sector renovation cycles are compressing specification timelines while GREENGUARD Gold certification bifurcates supplier tiers into specification-grade and mass-market camps. REACH SVHC restrictions and EPA VOC emissions standards under TSCA Title VI are forcing simultaneous compliance investments across multiple jurisdictions.
Growth Catalysts
- Low-VOC mandate expansion:EPA TSCA Title VI and evolving state-level regulations in California and New York are disqualifying solvent-based adhesive systems from commercial projects.
- China urban residential modernization:Tier-one city commercial fit-out acceleration and residential stock upgrades are concentrating demand for premium vinyl sheet and fabric-backed wall coverings.
- Fire-resistance specification:Japanese commercial interiors under METI building codes are mandating Class A fire-rated substrates for hospitality and healthcare verticals.
Market Restraints
- Phthalate plasticizer substitution costs:REACH restrictions on SVHC-listed plasticizers are forcing reformulation of vinyl substrates with bio-sourced alternatives at 15-25% cost premiums.
- Raw material concentration:PVC resin and titanium dioxide pigment supply clusters in China and the US Gulf Coast create geographic vulnerability to energy price shocks.
- Installation skill scarcity:Commercial-grade wall covering application requires certified installers for seam matching and pattern alignment, with training pipelines lagging demand in North America and Europe.
Strategic Opportunities
- India branded retail expansion:Integrated paint-and-texture systems are capturing share in organized home improvement retail as Asian Paints and competitors build out specification capabilities.
- Acoustic modulation demand:Open-plan office and hospitality designs are specifying fabric-wrapped panels and perforated wood systems for noise control.
- E-commerce specification channels:Digital sample ordering and AR visualization tools are disintermediating traditional distributor relationships for residential renovation projects.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel GREENGUARD Gold, Cradle to Cradle, and BREEAM qualification processes extend product launch cycles by 8-14 months.
- Legacy inventory stranding risk:ECHA's expanding candidate list for restricted substances threatens existing adhesive and substrate stockpiles in European distribution channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wall Covering and Wall Decor Market |
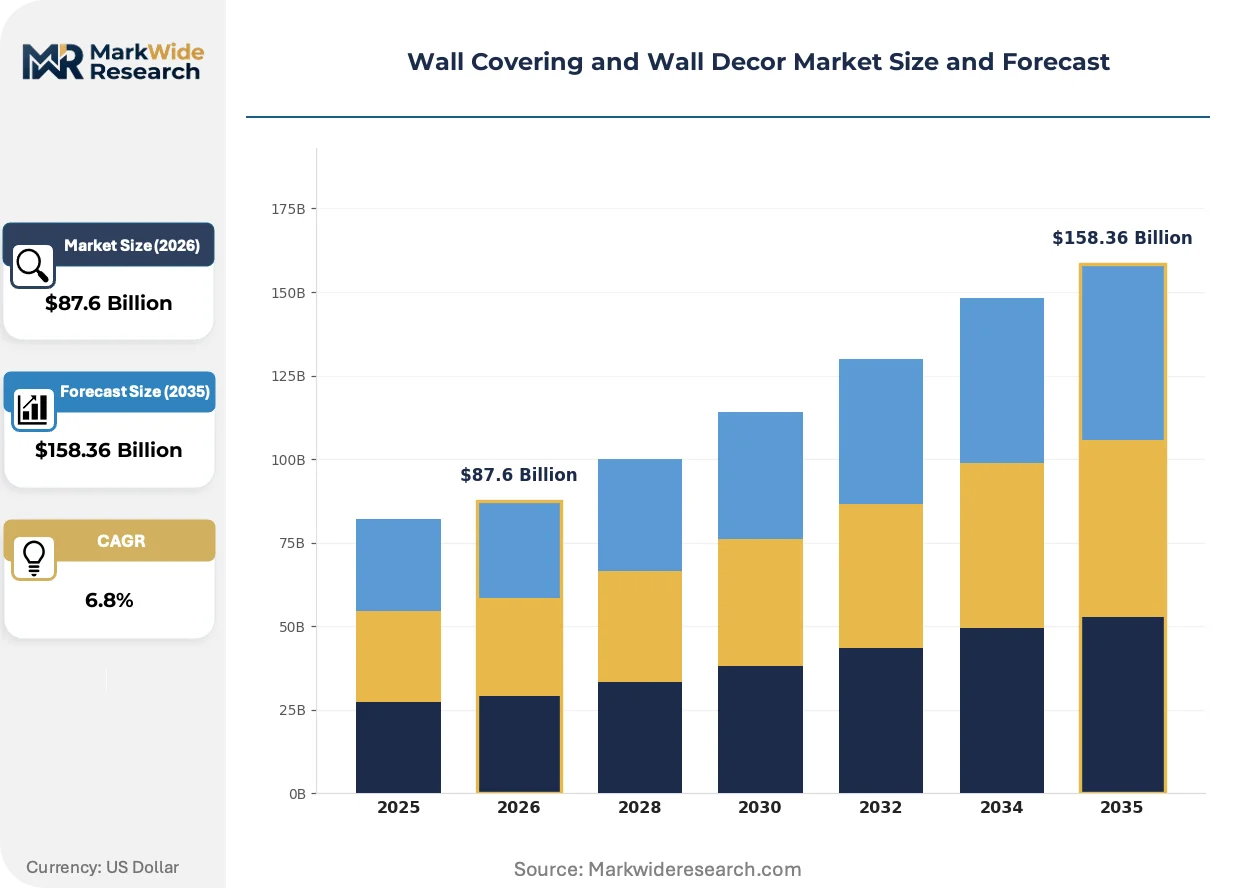
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wallpaper, Wall Panels, Paints, Tapestries Material: Vinyl, Fabric, Wood, Metal Application: Residential, Commercial, Hospitality, Retail Style: Traditional, Modern, Rustic, Minimalist |
| Companies Covered | York Wallcoverings, Brewster Home Fashions, Asian Paints, A.S. Création Tapeten, F. Schumacher & Co., Sangetsu Corporation, Wallquest, Grandeco, Osborne & Little, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wall Covering and Wall Decor Market Trends and Innovations
Digital printing and bio-based polymer development are compressing traditional manufacturing scale advantages while enabling mass customization. Specification authority is migrating from general contractors to sustainability consultants and facilities managers with direct certification requirements.
Digital inkjet printing on vinyl and non-woven substrates is fragmenting the economics of short-run custom wallpaper production. Boutique hospitality brands and corporate identity programs are adopting digitally printed murals at batch sizes below 500 square meters. This technology is fragmenting the historical volume advantage of gravure-printed stock patterns and enabling regional design studios to compete with established manufacturers.
REACH SVHC candidate list expansion is accelerating substitution cycles for phthalate plasticizers and flame retardants in European supply chains. Manufacturers are reformulating adhesive systems with water-based chemistries and bio-sourced polyurethane binders to maintain market access. Vinyl sheet products for healthcare and hospitality applications face the most intensive compliance pressure as ECHA reviews additional substance restrictions.
Facilities managers are consolidating specification authority through green building certification mandates. LEED v4.1 and WELL Building Standard procurement criteria are elevating indoor air quality testing above aesthetic preference in commercial projects. This shift is most visible in North American corporate headquarters and healthcare construction, where certification-driven vendor qualification is narrowing approved supplier lists.
Wall Covering and Wall Decor Market Segmentation
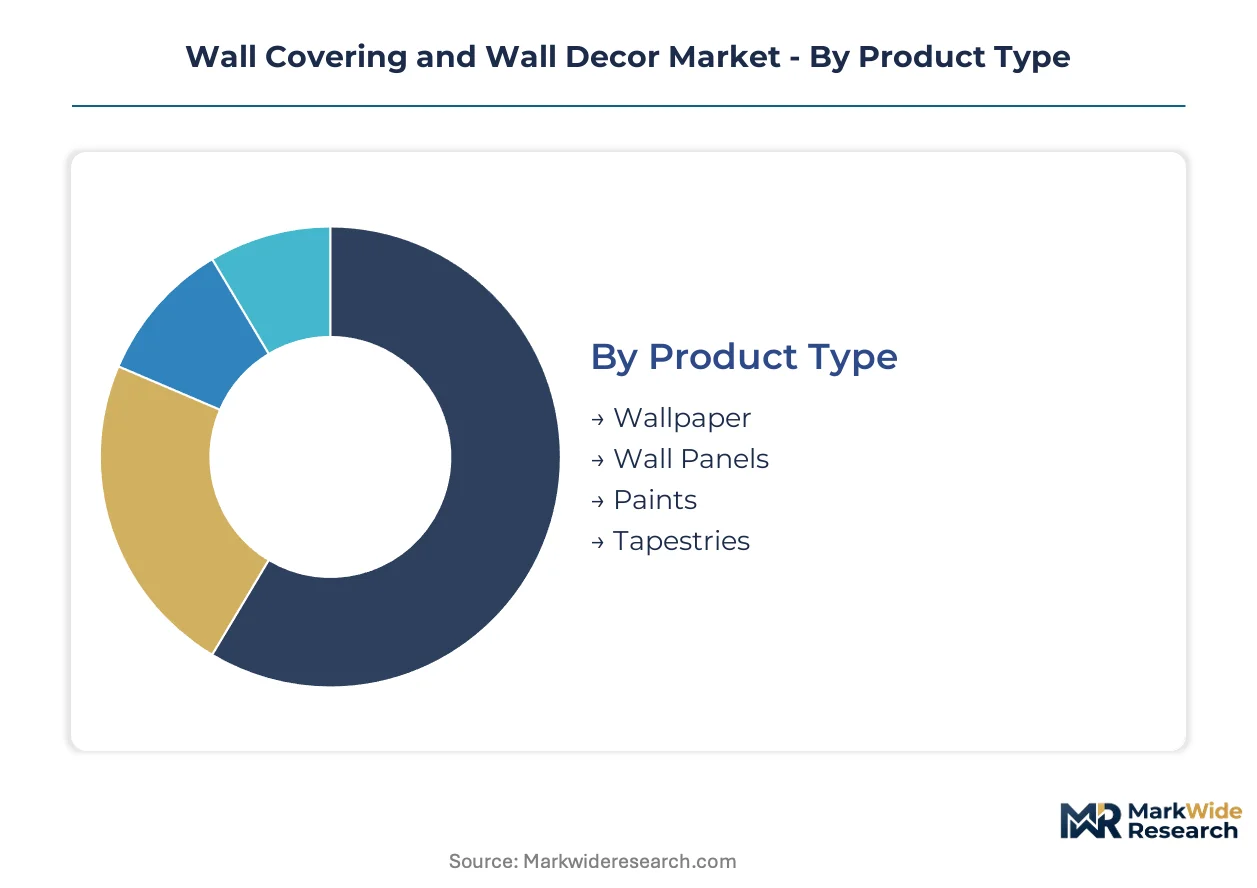
Wall covering procurement channels diverge sharply between specification-grade commercial projects and mass-market residential renovation. Understanding these route-to-market differences determines which segments command premium positioning versus volume scale.
Product Type:
Channel-mix dynamics separate stock-keeping units for retail distributors from made-to-order specification workflows for commercial contractors.
- Wallpaper:Paper-backed and non-woven substrates with grammage ranging from 200–400 g/m² serve hospitality renovation cycles where pattern matching and seam alignment require certified installer networks. Demand concentrates in China as tier-one city commercial fit-out activity accelerates and residential stock modernizes, with digital inkjet printing enabling short-run custom production below 500 square meters.
- Wall Panels:Engineered wood and fabric-wrapped systems with tongue-and-groove mounting deliver acoustic modulation and fire-rated surface protection for open-plan offices and healthcare construction. Japanese commercial interiors under METI building codes are mandating Class A fire-rated substrates, compressing specification timelines for compliant suppliers.
- Paints:Vinyl and low-sheen formulations anchor residential renovation volume through organized home improvement retail and e-commerce channels.
- Tapestries:Woven textile hangings occupy niche luxury segments with higher per-square-meter economics but constrained repeat purchase frequency in residential feature-wall applications.
By volume, Paints leads. By growth pace, Wall Panels is climbing the fastest.
Material:
Cost-tier stratification separates specification-grade certified materials from mass-market alternatives facing regulatory displacement.
- Vinyl:PVC resin-based sheet and fabric-backed products dominate commercial hospitality and healthcare applications where scrubbability and fire-resistance ratings carry premium positioning. REACH SVHC restrictions on phthalate plasticizers are forcing reformulation with bio-sourced alternatives at 15-25% cost premiums, threatening existing European inventory.
- Fabric:Woven textile and fabric-wrapped panels serve acoustic modulation demand in open-plan office and hospitality designs, with noise control specifications migrating from aesthetic preference to mandatory building performance criteria.
- Wood:Engineered panels with perforated surface treatments combine spatial branding with sound absorption for corporate headquarters and boutique hospitality.
- Metal:Architectural metal wall coverings occupy constrained luxury segments where material scarcity and fabrication complexity limit volume scaling.
By installed value, Vinyl commands the largest share. By regulatory pressure, Fabric is gaining specification momentum fastest.
Application:
Customer-type differences separate cyclical renovation demand from new construction specifications with diverging certification requirements.
- Residential:Urban stock modernization in China and India drives demand for integrated paint-and-texture systems through branded retail expansion, with e-commerce sample ordering and AR visualization tools disintermediating traditional distributor relationships.
- Commercial:Corporate headquarters construction under LEED v4.1 and WELL Building Standard procurement criteria elevates indoor air quality testing above aesthetic preference, narrowing approved supplier lists to GREENGUARD Gold certified vendors.
- Hospitality:Renovation cycles compress specification timelines while bifurcating supplier tiers into specification-grade and mass-market camps based on fire-rated and scrubbable surface requirements.
- Retail:Branded environment rollouts specify digitally printed murals for corporate identity programs at batch sizes incompatible with gravure-printed stock economics.
By project count, Residential dominates. By specification value per square meter, Hospitality is expanding most quickly.
Style:
Maturity-stage variation separates established pattern libraries from emerging design language adoption curves.
- Traditional:Archival design libraries sustain premium positioning in North American hospitality channels where heritage aesthetics command specification loyalty.
- Modern:Clean-line minimalism dominates corporate headquarters and healthcare construction where maintenance protocols favor scrubbable surfaces over ornamental complexity.
- Rustic:Reclaimed wood and distressed texture systems serve boutique hospitality differentiation in secondary markets.
- Minimalist:Reduced-pattern vinyl and low-sheen paint formulations align with WELL Building Standard emphasis on visual calm and material transparency.
By specification frequency, Modern leads. By share gain, Minimalist is advancing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific wall covering distribution, handling bulk PVC resin imports and finished vinyl sheet exports that supply tier-one city commercial fit-out markets across China and neighboring economies.
China
Tier-one city commercial fit-out acceleration and residential stock modernization concentrate demand for premium vinyl sheet and fabric-backed wall coverings. GB standards on interior decoration material harmful substance limits enforce compliance investments for domestic producers and export-oriented manufacturers. The Yangtze River Delta manufacturing cluster around Shanghai supplies specification-grade substrates to hospitality renovation projects.
United States
Hospitality sector renovation cycles amplify specification-grade purchases through certified installer networks serving pattern-matching requirements. EPA VOC emissions standards under TSCA Title VI disqualify solvent-based adhesive systems from commercial projects. Domestic manufacturing in the Southeast and Mid-Atlantic regions supports York Wallcoverings' archival design library positioning.
Germany
REACH SVHC restrictions on phthalate plasticizers force reformulation of vinyl substrates with bio-sourced alternatives at cost premiums. ECHA's expanding candidate list for restricted substances accelerates substitution cycles in European supply chains. The North Rhine-Westphalia industrial corridor hosts adhesive and substrate producers navigating multi-jurisdiction certification timelines.
India
Urban residential stock upgrades drive demand for integrated paint-and-texture systems through organized home improvement retail expansion. BIS standards on interior decoration materials create parallel compliance frameworks for domestic and imported products. The Maharashtra-Gujarat manufacturing belt anchors Asian Paints' distribution infrastructure for branded wall covering portfolios.
Japan
METI building codes mandate Class A fire-rated substrates for hospitality and healthcare verticals, compressing specification timelines for compliant suppliers. JIS standards on interior finish materials govern commercial project procurement. The Kansai region around Osaka concentrates vinyl sheet and fabric-backed production for fire-resistance-rated applications.
Wall Covering and Wall Decor Market Competitive Landscape
Listed leaders compete with private specialists across certification-grade positioning, with public companies leveraging capital markets for compliance investments while family-owned firms exploit archival design libraries and regional installer relationships. The supplier base bifurcates into specification-grade and mass-market tiers based on GREENGUARD Gold certification status. Three archetypes dominate: integrated paint-and-texture system providers, archival design houses with domestic manufacturing, and vinyl sheet specialists competing on fire-resistance ratings. Competitive moves center on digital printing technology licensing and backward integration into substrate production.
Within the archival design tier, York Wallcoverings and F. Schumacher & Co. exemplify heritage positioning through pattern library depth and North American hospitality channel relationships. Asian Paints anchors the integrated system archetype in South Asian markets. Sangetsu Corporation occupies the fire-resistance specialization vector for Japanese commercial interiors.
| Leading Market Players |
|---|
| York Wallcoverings |
| Brewster Home Fashions |
| Asian Paints |
| A.S. Création Tapeten |
| F. Schumacher & Co. |
| Sangetsu Corporation |
| Wallquest |
| Grandeco |
| Osborne & Little |
| Others |
Pricing and Supply Chain Analysis
GREENGUARD Gold certification gates supplier qualification while simultaneously enabling price premiums of 15-25% above mass-market alternatives. This bifurcation concentrates pricing power among specification-grade manufacturers who have absorbed compliance costs, while mass-market producers face margin compression from reformulation mandates.
Pricing Analysis
Volume-discount tiering structures separate project-based commercial contracts from retail distributor pricing. Three-tier pricing stratifies across specification-grade certified, standard commercial, and economy residential levels, with differentiation driven by fire-resistance ratings and scrubbability performance. Cost compression in economy tiers intensifies as Chinese producers expand vinyl sheet capacity. Residential renovation buyers exhibit highest price sensitivity, while hospitality procurement teams prioritize lifecycle durability over unit cost.
Supply Chain Analysis
Inventory lead-times stretch 8-14 months for multi-jurisdiction certification processes, compressing working capital cycles for reformulation investments. PVC resin and titanium dioxide pigment supply draws from China and the US Gulf Coast, creating geographic vulnerability to energy price volatility. Water-based adhesive systems and bio-sourced polyurethane binders now dominate European formulation pipelines. Distribution runs through certified installer networks for commercial specification-grade products, while mass-market channels leverage home improvement retail and direct e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates acquisition opportunities as certification requirements splinter the supplier base into specialty niches. Digital printing technology and bio-based polymer development are enabling regional design studios to compete with established manufacturers.
For Market Incumbents: Shield specification-grade positioning by deepening backward integration into substrate production and securing archival design library exclusives. Accelerate GREENGUARD Gold certification across product lines before ECHA expands SVHC restrictions. Prioritize captive supply of fire-rated vinyl sheet to defend hospitality channel relationships against Asian competitors.
For New Entrants and Emerging Players: Lead with acoustic modulation specialization targeting open-plan office retrofits in tier-one Chinese cities. White-space exists in fabric-wrapped panel systems for WELL Building Standard projects. Pursue digital printing partnerships with boutique hospitality brands seeking sub-500 square meter custom mural production.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital printing-enabled production lines, reducing barriers to entry in custom wallpaper segments. Five-to-ten year viability favors targets with established certified installer networks and hospitality specification relationships. Monitor ECHA SVHC candidate list expansion velocity as inflection indicator for stranded inventory risk and substitution cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive PVC resin supply insulates York Wallcoverings from Gulf Coast energy price volatility. |
| GREENGUARD Gold Certification Program | Full portfolio qualification narrows approved supplier lists for LEED v4.1 corporate headquarters projects. |
| Digital Printing Technology Licensing | Inkjet systems enable Asian Paints to capture short-run custom demand below gravure economic thresholds. |
| Certified Installer Network Expansion | Pattern-matching capability scarcity in North America supports premium positioning for Sangetsu Corporation. |
| Bio-Sourced Polymer Reformulation | Water-based adhesive systems maintain European market access under REACH SVHC restrictions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, hospitality procurement databases, and green building certification registries. Interviews with specification-grade manufacturers, certified installer network managers, hospitality procurement directors, and facilities managers informed demand-side validation. Secondary sources included EPA TSCA Title VI filings, ECHA SVHC candidate list updates, and GB standards documentation. Bottom-up product-level estimates triangulated against top-down sector spending analysis.
Segmentation dimensions modeled include product type, material substrate, application vertical, and style category across the projection horizon. CAGRs derive from installed base turnover rates, renovation cycle frequencies, and regulatory compliance investment trajectories. Forecast inputs incorporated tier-one city commercial fit-out pipelines, hospitality renovation backlogs, and evolving low-VOC mandate adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or accelerated substitution timelines would require recalibration. Forecasts reflect assumptions regarding certification timeline stability and raw material supply continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Window Covering Market
Homecare and Decor
Europe Flower Pots and Planters Market
Homecare and Decor
Smart Bed Mattress Market
Homecare and Decor
Global Homeware Market
Homecare and Decor
Flush Door Market
Homecare and Decor
Removable Wallpaper Market
Homecare and Decor
Home Decor Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Window Blinds Market
Homecare and Decor
Online Home Decor Market
Homecare and Decor
China Sustainable Home Decor Market
Homecare and Decor
New Zealand Window Covering Market
Homecare and Decor
India Interior Design Market
Homecare and Decor
Soundproof Curtains Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
Saudi Arabia Interior Design Market