
 Curtains and Window Blinds Market | 2026-2036
Curtains and Window Blinds Market Size, Share, and Industry Trends Forecast 2026-2036
Curtains and Window Blinds Market Analysis
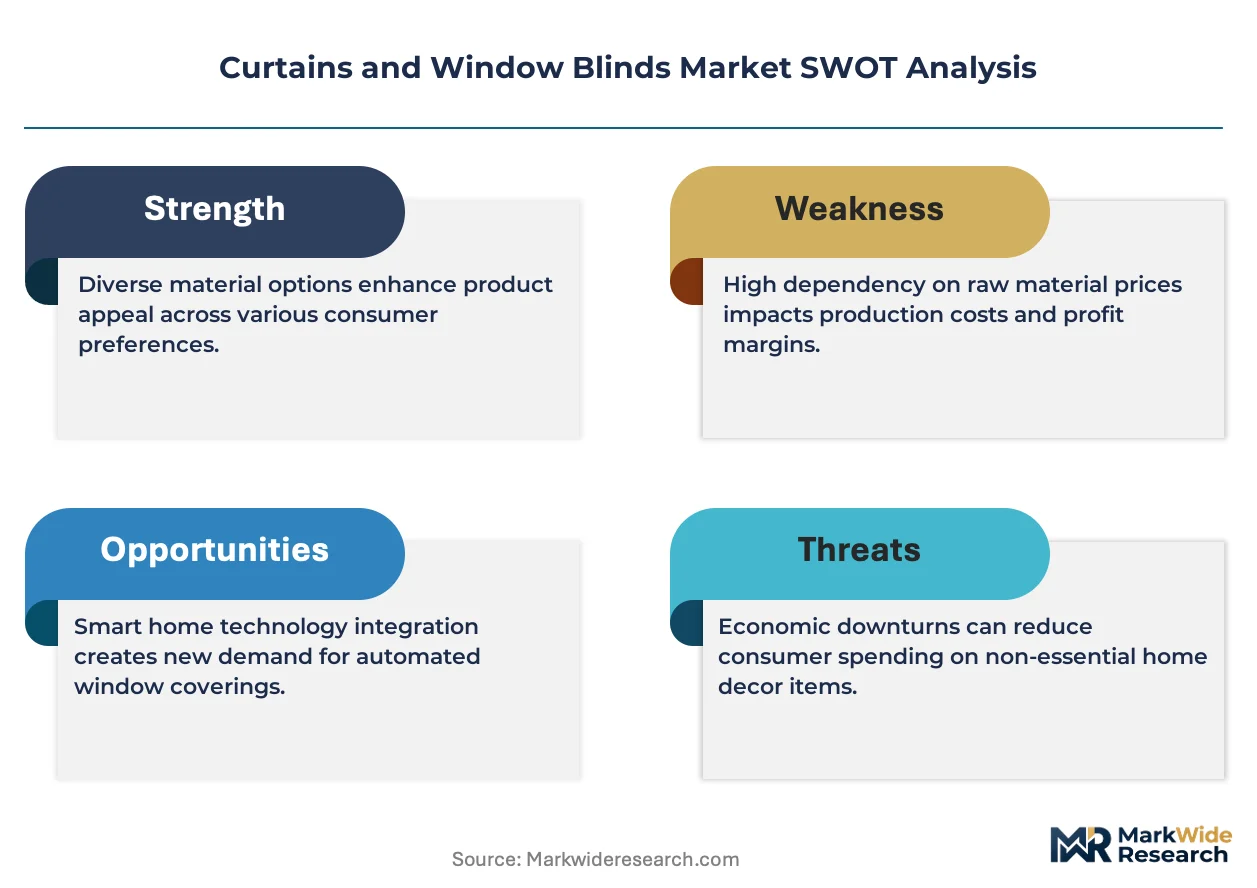
Software-defined light management is broadening what window treatment vendors monetize beyond physical hardware. Hunter Douglas N.V. leverages its PowerView automation ecosystem to sustain recurring engagement after initial installation. Lutron Electronics anchors premium positioning through proprietary shading control protocols that integrate with whole-home systems. Springs Window Fashions LLC competes on manufacturing scale across multiple price tiers.
Curtains and window blinds comprise textile or slatted assemblies engineered to modulate light transmission, thermal transfer, and visual privacy through adjustable opacity mechanisms, with specifications typically spanning 0.5 mm to 3 mm material thickness and UV-blocking coefficients up to 99 percent. Roller blinds and vertical blinds command the largest installed base in commercial retrofit applications, while Roman blinds capture disproportionate margin in the hospitality segment where acoustic lining requirements elevate unit economics. Cotton and linen materials face substitution pressure from recycled polyester blends as sustainability procurement standards tighten across European commercial building portfolios.
The EU Green Deal and REACH chemical standards constrain fabric treatment chemistries available to manufacturers serving European markets, while the US EPA indoor air quality guidelines influence low-VOC adhesive specifications for residential installations. The US Federal Trade Commission's Green Guides shape how recyclability and energy-saving claims appear on product labeling. Stakeholders must monitor how building certification schemes such as LEED and BREEAM evolve their daylighting and thermal performance criteria, as these rating systems increasingly determine specification authority in large commercial projects.
Market Dynamics
Software-defined light management systems are compressing replacement cycles while EU Green Deal thermal performance mandates force fabric chemistry reinvention across European supply chains.
Growth Catalysts
- EU Green Deal building efficiency directives:Thermally insulating fabric specifications are becoming mandatory in renovation-intensive housing stocks, pulling demand toward high-performance material categories.
- Residential retrofit activity in urban condominiums:Accelerated replacement cycles in Germany's renovation-intensive housing stock are concentrating volume in premium fabric segments.
- Recycled polyester blend substitution:Sustainability procurement standards across European commercial building portfolios are displacing cotton and linen in specification authority.
Market Restraints
- REACH chemical standard constraints:Fabric treatment chemistries available to European manufacturers face regulatory friction that limits coating performance options.
- Aluminum slat supply concentration:Raw material sourcing for venetian blind hardware concentrates in specific extrusion geographies, creating input cost volatility exposure.
- Manual-to-automated switching costs:Legacy installed bases in commercial buildings create technical limitation barriers for full-building automation retrofits.
Strategic Opportunities
- PowerView-type automation ecosystems:Recurring revenue platforms are expanding into residential aftermarket service contracts beyond initial hardware installation.
- Hospitality acoustic lining specifications:Roman blind categories with enhanced sound dampening are capturing disproportionate margin in hotel renovation pipelines.
- LEED and BREEAM daylighting criteria evolution:Certification scheme updates are creating specification authority shifts toward vendors with documented thermal performance data.
Industry Challenges
- Low-VOC adhesive compliance timelines:US EPA indoor air quality guidelines for residential installations are extending product certification cycles.
- Whole-home system integration complexity:Proprietary shading control protocols require specialized commissioning skills that outpace installer training pipelines.
- FTC Green Guides claim substantiation:Recyclability and energy-saving labeling requirements are forcing documentation system investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curtains and Window Blinds Market |
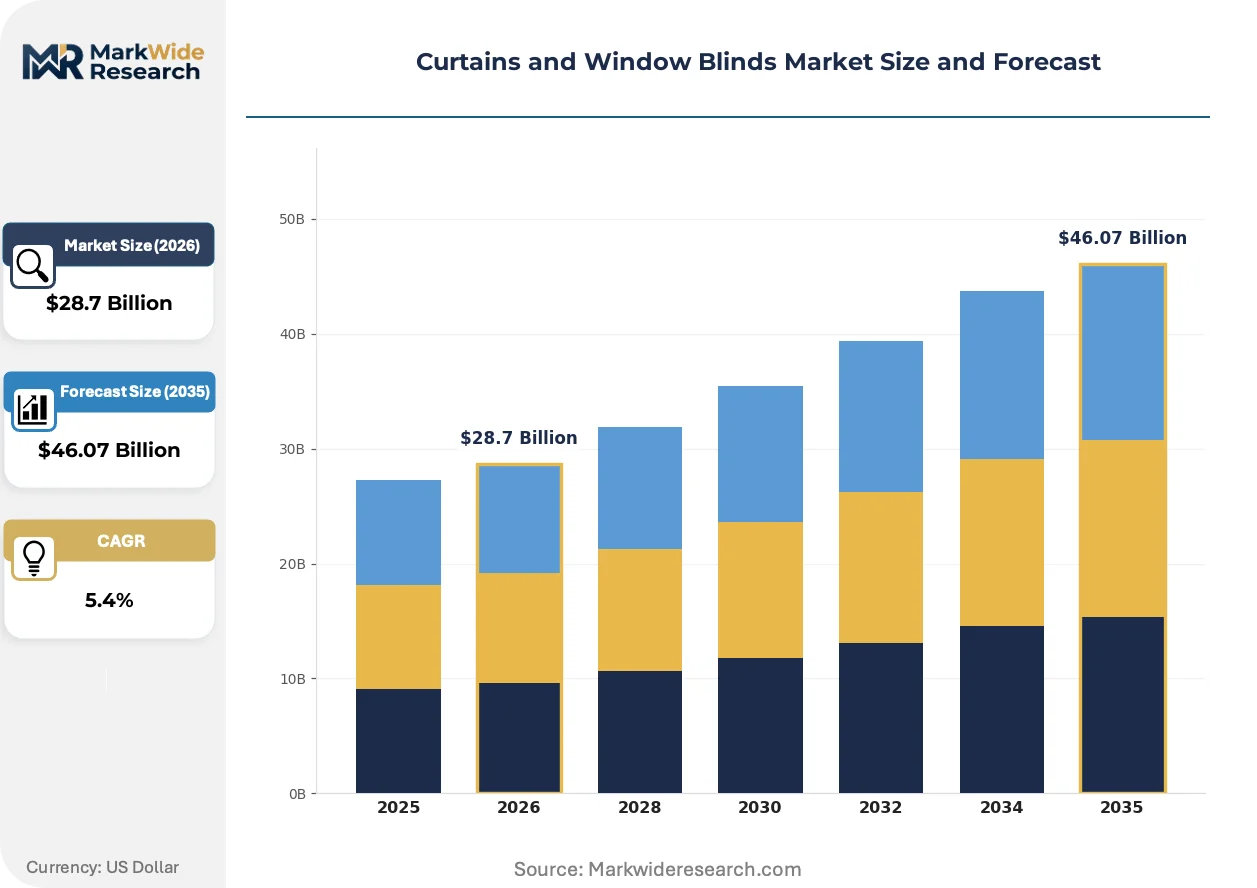
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $46.07 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Blinds, Roman Blinds, Vertical Blinds, Curtains Material: Cotton, Polyester, Vinyl, Linen Application: Residential, Commercial, Hospitality, Automotive Style: Modern, Traditional, Transitional, Rustic |
| Companies Covered | Hunter Douglas N.V., Somfy Systems Inc., Lutron Electronics, Springs Window Fashions LLC, Nien Made Enterprise Co., Ltd., IKEA Group, Velux Group, MechoShade Systems, LLC, Griesser AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curtains and Window Blinds Market Emerging Trajectories
Digital control layers are redefining what window treatment vendors monetize, while material science advances and procurement model evolution reshape competitive differentiation.
Photovoltaic-integrated blind systems are expanding into commercial building envelopes where BIPV mandates drive specification. Facility managers in Nordic markets are piloting these for grid-interactive load management. The technology is expanding into thermal storage applications that shift HVAC peak demand.
REACH Annex XVII restricted substance lists are constraining flame-retardant chemistries in contract textiles. Manufacturers serving European commercial portfolios are reformulating coating stacks to maintain NFPA 701 compliance without halogenated additives. Hospitality and healthcare verticals face the steepest substitution timelines.
Direct-to-installer digital platforms are compressing traditional wholesale distribution layers. Independent blind contractors in North American metropolitan markets are sourcing customized dimensions through API-connected fabrication networks. Specification authority is migrating toward installers with in-house measurement automation capabilities.
Curtains and Window Blinds Market Segmentation
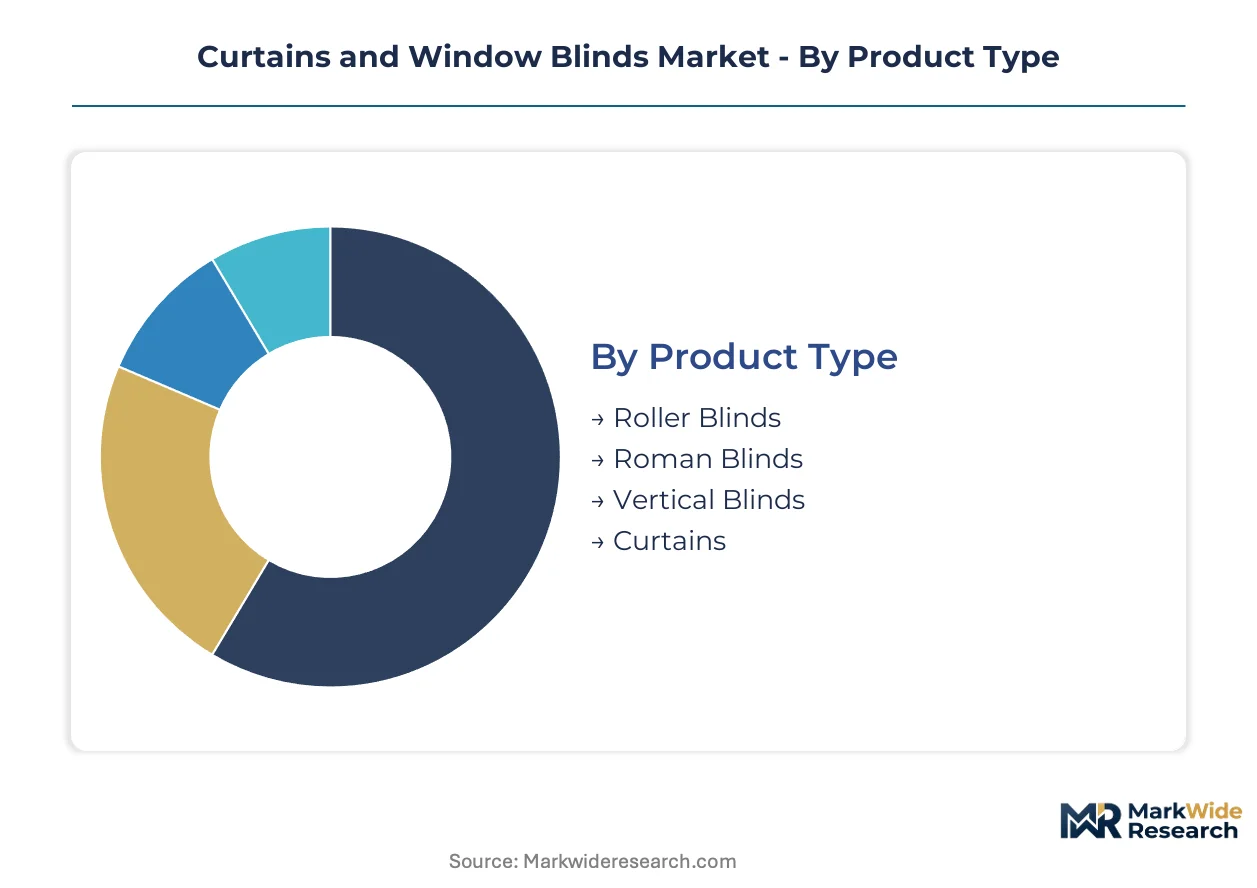
Specification authority in window treatments fragments across performance requirements, aesthetic positioning, and installation complexity. Buyers prioritize light modulation precision in commercial settings while residential decisions weight thermal efficiency and automation compatibility.
Product Type:
Commercial retrofit intensity and automation readiness drive specification splits across institutional buyers.
- Roller Blinds:Fabric-wrapped aluminum tubes with spring or chain drive mechanisms deliver precise opacity control in 0-100% gradations. Germany's renovation-intensive condominium stock concentrates replacement volume here, with EU Green Deal thermal mandates pulling specification toward insulating triple-weave constructions.
- Vertical Blinds:Rotating louver systems suspended from overhead tracks dominate large-format glazing in office and healthcare settings. Slat widths of 89mm to 127mm accommodate varying daylighting requirements under LEED daylight autonomy criteria.
- Roman Blinds:Soft-fold fabric assemblies with internal batten structures command premium positioning in hospitality acoustic specifications. Hotel renovation pipelines in Nordic markets specify these for sound dampening compliance.
- Curtains:Drapery panels with heading tape or grommet suspension serve residential and heritage commercial installations where aesthetic warmth outweighs automation priority.
Volume sits with Roller Blinds; growth tilts toward Roman Blinds.
Material:
Sustainability procurement standards and chemical compliance timelines reshape raw material authority across European supply chains.
- Polyester:Recycled PET filament constructions with UV-stabilized coatings now displace natural fibers in contract textile specifications. REACH Annex XVII constraints on flame-retardant chemistries favor inherently fire-resistant synthetic weaves in hospitality and healthcare verticals.
- Cotton:Natural cellulose fibers face substitution pressure as BREEAM-compliant building portfolios mandate recycled content thresholds. Organic certification premiums persist in residential premium segments.
- Vinyl:PVC-based slat and sheet materials offer moisture resistance and cleanability for healthcare and food-service installations.
- Linen:Bast fiber constructions retain specification in heritage hospitality and residential luxury tiers despite higher care requirements.
Procurement weight favors Polyester; specification cachet remains with Linen.
Application:
End-use performance requirements diverge sharply on automation integration, acoustic treatment, and regulatory compliance burden.
- Commercial:Office and institutional installations prioritize daylight harvesting integration with building management systems. BIPV mandates in Nordic markets are piloting photovoltaic-integrated blind systems for grid-interactive load management.
- Residential:Urban condominium retrofits concentrate volume in Germany, with PowerView-type automation ecosystems expanding into aftermarket service contracts.
- Hospitality:Hotel renovation pipelines specify Roman blinds with acoustic lining for guest room sound dampening, capturing disproportionate margin through performance tiering.
- Automotive:Precision-cut roller assemblies for sunroof and rear glazing applications serve OEM and aftermarket channels with distinct thermal performance requirements.
Commercial commands installed base scale; Hospitality delivers margin expansion.
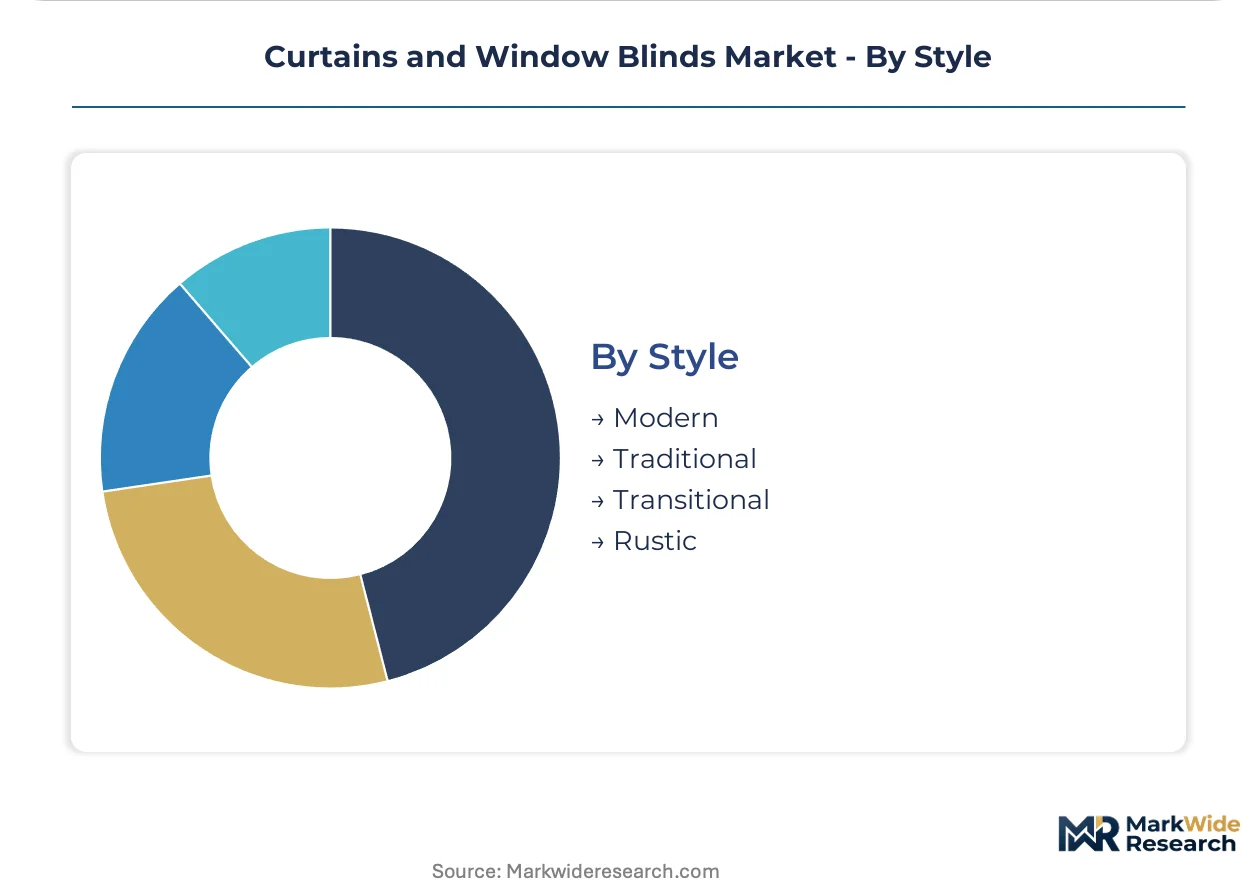
Style:
Aesthetic positioning stratifies across generational buyer preferences and architectural context matching.
- Modern:Minimalist lines, concealed hardware, and neutral palettes align with contemporary residential and commercial interiors. Automation integration is assumed at specification.
- Traditional:Ornate heading treatments, decorative finials, and patterned fabrics serve heritage building renovations and established residential demographics.
- Transitional:Hybrid approaches blending clean lines with warm materials capture renovation markets seeking updated aesthetics without full modernist commitment.
- Rustic:Natural textures, exposed hardware, and earth-tone palettes align with rural hospitality and residential segments emphasizing organic material authenticity.
Modern leads specification frequency; Transitional gains renovation share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr metropolitan corridor anchors renovation-intensive demand for thermally insulating window treatments under EU Green Deal mandates. Urban condominium retrofits in Düsseldorf and Cologne concentrate replacement volume for motorized roller systems. The analysis spans five national markets where building efficiency regulations and housing stock age reshape procurement patterns.
Germany
Renovation-intensive housing stock in North Rhine-Westphalia and Bavaria drives replacement cycles for triple-weave insulating fabrics. The EU Green Deal's building efficiency directives mandate thermal performance thresholds in retrofit applications. Stuttgart's industrial fabric cluster supplies high-performance coated textiles to domestic and neighboring markets.
United States
Urban condominium retrofits in Chicago and New York Metro accelerate smart shading adoption with whole-home automation integration. The EPA's indoor air quality guidelines enforce low-VOC adhesive specifications for residential installations. Dallas-Fort Worth's distribution hub serves the Sun Belt's commercial daylight harvesting retrofit pipeline.
China
Commercial building envelope upgrades in Shanghai and Shenzhen incorporate photovoltaic-integrated blind systems under dual carbon goals. GB standards for building energy efficiency tighten thermal performance requirements for curtain wall applications. The Yangtze River Delta manufacturing belt supplies precision aluminum extrusion hardware to domestic and export markets.
Netherlands
LEED and BREEAM-certified commercial portfolios in Amsterdam and Rotterdam specify recycled polyester contract textiles. REACH Annex XVII constraints on flame-retardant chemistries push reformulation of coating stacks for hospitality verticals. The Eindhoven region's smart building technology cluster pilots grid-interactive shading for peak demand management.
Japan
Hotel renovation pipelines in Tokyo and Osaka specify Roman blinds with acoustic lining for guest room sound dampening. METI's building energy efficiency standards tighten daylighting performance criteria for commercial retrofits. The Kansai region's textile manufacturers supply high-end natural fiber treatments to domestic hospitality chains.
Curtains and Window Blinds Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across distinct supply chain positions. Integrated fabricators with captive extrusion and coating capabilities face pressure from specialized automation system developers. Three archetypes dominate: full-stack manufacturers controlling material through distribution, automation technology licensors monetizing recurring software engagement, and scale-oriented assemblers competing on cost across price tiers. Consolidation pressures intensify through strategic partnerships between hardware fabricators and smart home platform operators, while geographic expansion into renovation-intensive European markets accelerates.
Within the automation-technology tier, Hunter Douglas N.V. and Somfy Systems Inc. exemplify platform-centric positioning through proprietary control ecosystems. Lutron Electronics anchors premium-tier specification authority through whole-home integration protocols. Springs Window Fashions LLC occupies the scale-driven manufacturing archetype with multi-tier pricing coverage. Nien Made Enterprise Co., Ltd. represents Asian-based integrated production serving export markets. Griesser AG and MechoShade Systems, LLC sit within specialized commercial-project specification channels. IKEA Group exemplifies mass-market retail distribution reach. Velux Group anchors building-integrated daylighting system positioning.
| Leading Market Players |
|---|
| Hunter Douglas N.V. |
| Somfy Systems Inc. |
| Lutron Electronics |
| Springs Window Fashions LLC |
| Nien Made Enterprise Co., Ltd. |
| IKEA Group |
| Velux Group |
| MechoShade Systems, LLC |
| Griesser AG |
| Others |
Supply Flow & Price Mechanics
Backward integration into aluminum extrusion and coated textile production anchors pricing power for full-stack manufacturers serving EU Green Deal retrofit mandates. Captive control over triple-weave insulating fabric and precision hardware components insulates integrated producers from raw material volatility while enabling premium positioning in Germany's renovation-intensive condominium market.
Pricing Analysis
Margin tightening in standard-grade roller blind tiers traces to recycled polyester filament oversupply and direct-to-installer platform compression. Three-tier pricing structure across premium, standard, and economy levels separates PowerView-automation-enabled systems from basic chain-drive mechanisms, with certification tiering under LEED and BREEAM daylighting criteria adding further differentiation. Cost-down pressure on economy segments accelerates because Asian-scale assemblers compete on volume across export markets. Commercial project buyers exhibit lowest price sensitivity due to specification authority residing with architects and facility managers, while independent residential contractors face acute margin compression from digital platform disintermediation.
Supply Chain Analysis
EU Green Deal domestic-content preferences for renovation-intensive housing stocks are reshaping sourcing patterns toward European extrusion and coating clusters. Aluminum slat hardware concentrates in China's Yangtze River Delta precision manufacturing belt, Germany's Stuttgart industrial fabric cluster, and Taiwan's specialty metalworking regions. Raw material dependencies span high-grade aluminum billet, UV-stabilized PET filament, and low-VOC adhesive formulations. Single-source vulnerability sits with REACH-compliant flame-retardant chemistry suppliers facing Annex XVII reformulation timelines. Distribution runs through direct-to-installer digital platforms compressing traditional wholesale layers, with API-connected fabrication networks enabling customized dimension sourcing for North American metropolitan contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal thermal performance mandates and REACH chemical compliance timelines are forcing sub-scale fabricators toward exit or acquisition, consolidating specification authority around integrated producers with captive R&D and certification documentation capabilities.
For Market Incumbents: Hedge against recycled polyester blend commoditization by deepening captive coating capabilities for NFPA 701-compliant contract textiles without halogenated additives. Secure backward integration into aluminum extrusion through strategic partnerships with Yangtze River Delta hardware suppliers, insulating margin position from tariff exposure and input cost volatility. Prioritize certification investment in BREEAM and LEED thermal performance documentation to capture specification authority in commercial daylight harvesting retrofits. For New Entrants and Emerging Players: Photovoltaic-integrated blind technology offers a technology-first wedge into Nordic commercial building envelope upgrades under BIPV mandates and grid-interactive load management pilots. Target hospitality acoustic lining specifications in Tokyo and Osaka hotel renovation pipelines, where Roman blind performance tiering captures disproportionate margin. Pursue direct-to-installer digital platform partnerships with API-connected fabrication networks as the primary go-to-market angle, bypassing traditional wholesale distribution layers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by smart home platform operators seeking hardware fabricators with PowerView-type automation ecosystems and recurring revenue service contract infrastructure. Long-term viability favors vertically integrated producers with REACH-compliant chemistry stacks and documented thermal performance data across the projection horizon. Watch Nordic BIPV mandate expansion velocity as the critical inflection signal for photovoltaic-integrated blind system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Chemistry Reformulation | Reformulation of flame-retardant coating stacks without halogenated additives maintains NFPA 701 access for hospitality and healthcare verticals. |
| PowerView-Type Automation Ecosystem Expansion | Recurring revenue platforms extend into residential aftermarket service contracts beyond initial hardware installation in urban condominium retrofits. |
| Direct-to-Installer Digital Platform Integration | API-connected fabrication networks compress wholesale distribution layers and migrate specification authority toward measurement-automation-capable contractors. |
| Photovoltaic-Integrated Blind System Development | BIPV mandate compliance in Nordic markets enables grid-interactive load management and thermal storage applications shifting HVAC peak demand. |
| LEED/BREEAM Certification Documentation Investment | Documented thermal performance data captures specification authority in large commercial projects where rating systems determine vendor selection. |
Methodological Framework
Independent corroboration across fabric treatment chemistry suppliers, aluminum extrusion specialists, and smart home platform developers underwrites the qualitative findings in this study. Primary interviews with facility managers specifying daylight harvesting systems, independent blind contractors adopting digital platforms, and hospitality procurement directors evaluating acoustic performance tiers combined with secondary validation from EU Green Deal regulatory filings, REACH Annex XVII substance restriction updates, and BREEAM daylighting criteria documentation. Bottom-up channel checks across Germany's Rhine-Ruhr metropolitan corridor renovation activity and top-down building stock age analysis triangulate volume estimates.
Rate-of-change decomposition across product type, material composition, application vertical, and style positioning frames the analytical approach over the projection horizon. Segmentation dimensions modeled include roller blind versus Roman blind versus vertical blind categories, recycled polyester versus natural fiber material splits, commercial versus residential versus hospitality application end-uses, and modern versus traditional versus transitional style archetypes. CAGRs derive from replacement cycle acceleration in Germany's renovation-intensive housing stock, EU Green Deal thermal mandate compliance timelines, and smart shading automation penetration curves. Industry-specific forecast inputs incorporate REACH chemical reformulation completion schedules and BIPV mandate rollout velocity in Nordic markets.
Several conditions sit outside the modeled scope, including potential aluminum tariff regime changes, unforeseen REACH substance restriction additions, and smart home protocol standardization outcomes. Forecasts reflect documented assumptions regarding retrofit incentive continuity and certification scheme criteria evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
Stained Glass Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
Japan Sustainable Home Decor Market
Homecare and Decor
Saudi Arabia Interior Design Market
Homecare and Decor
Europe Decorative Laminates Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Mattress Pads Market
Homecare and Decor
Corner Pads Market
Homecare and Decor
Door Handles Market
Homecare and Decor
Europe Commercial Blinds and Shades Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
Christmas Tree Market
Homecare and Decor
Vinyl Wallpaper Market
Homecare and Decor
Asia-Pacific Decor Paper Market