
 US Bamboos Market | 2026-2036
US Bamboos Market Size, Share, and Industry Trends Forecast 2026-2036
US Bamboos Market Insights
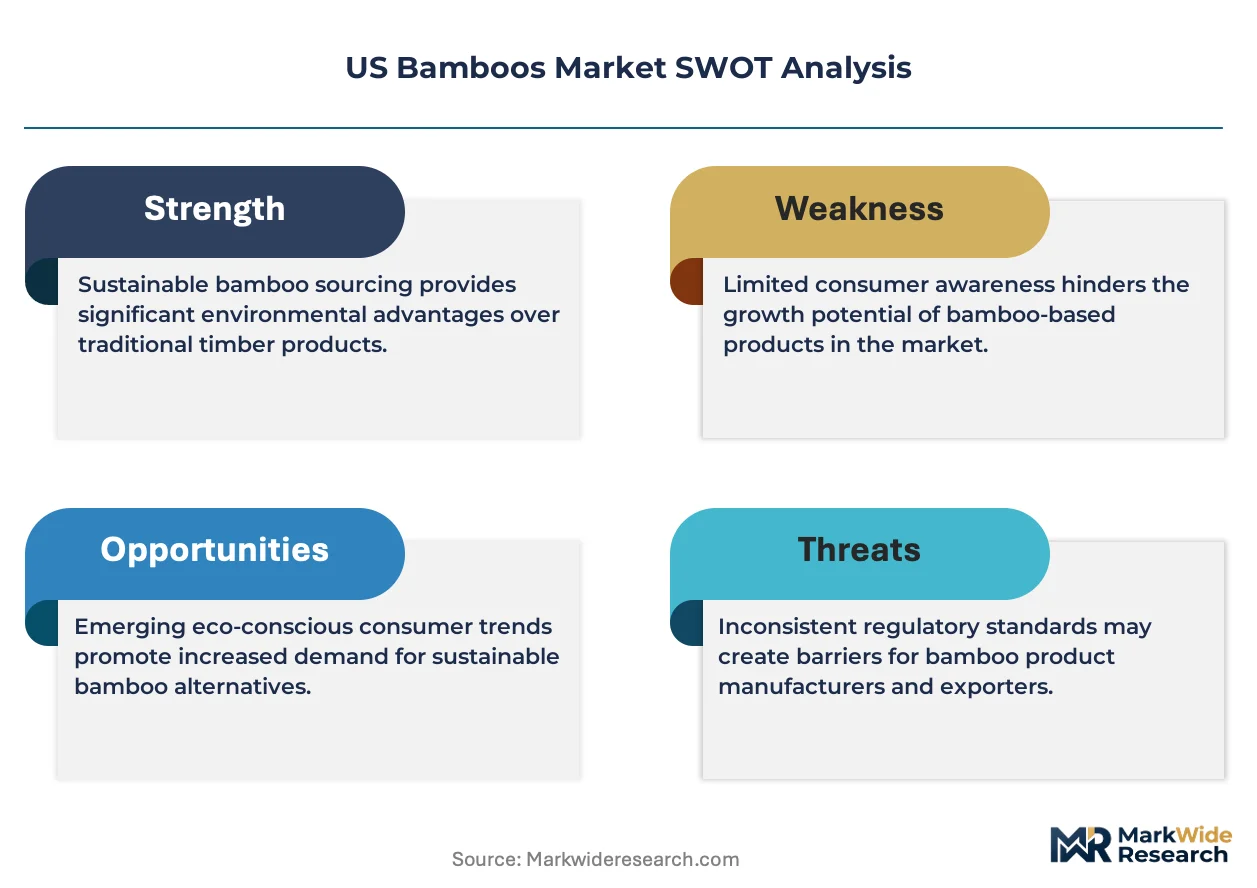
Southeast Asian plantation capacity is narrowing the raw material cost advantage that historically favored imported tropical hardwoods. Cali Bamboo leverages vertical integration from fiber sourcing through finished flooring to control quality consistency and delivery timelines. Smith & Fong Co. anchors its position in the architectural specification channel with FSC-certified products and extensive testing documentation. EcoTimber Inc. differentiates through specialty dimensional lumber grades targeting custom furniture makers and high-end interior millwork.
Bamboos are giant woody grasses in the subfamily Bambusoideae, characterized by hollow culms with node-based segmentation, lignin content of 23-32%, and tensile strength comparable to mild steel in fiber form. The material serves industrial and commercial markets as a rapidly renewable substitute for timber, petroleum-based composites, and cotton fiber in applications requiring structural integrity, aesthetic grain patterns, or cellulose feedstock. Bamboo flooring commands the largest product type position due to established installation familiarity and performance warranties, while bamboo pulp represents the fastest-expanding category as paper manufacturers seek alternatives to virgin softwood fiber. Construction applications dominate volume consumption, though interior design channels capture superior margin pools through custom fabrication and designer-specified installations.
The USDA Biopreferred Program, EPA TSCA Title VI formaldehyde emission standards, and state-level California Air Resources Board (CARB) Phase 2 compliance requirements collectively shape product certification pathways and market access for bamboo building materials. OSHA workplace safety standards for dust exposure during bamboo processing operations influence manufacturing location decisions and capital equipment investments. Stakeholders must monitor evolving building code amendments at the municipal level, where jurisdictions including Austin, Portland, and Miami-Dade are piloting expanded structural bamboo approvals that could unlock commercial-scale demand.
Market Dynamics
US bamboo demand pivots on municipal building code amendments that are gradually unlocking structural applications previously reserved for timber and steel, with California, Texas, and Florida leading adoption curves through amended residential construction standards.
Growth Catalysts
- USDA Biopreferred Program:Federal procurement preferences for rapidly renewable materials are accelerating certification requirements among contractors supplying government buildings and infrastructure projects.
- California Air Resources Board Phase 2:Stringent formaldehyde emission standards are favoring bamboo products that demonstrate compliance through third-party testing documentation.
- Engineered bamboo flooring:Residential construction contractors are expanding specification of cross-laminated bamboo panels for load-bearing applications in multi-family housing developments.
Market Restraints
- Raw material cost volatility:Southeast Asian plantation capacity fluctuations are narrowing the historical cost advantage over imported tropical hardwoods.
- Technical limitation:Hollow culm geometry and node-based segmentation restrict dimensional lumber grades suitable for heavy structural engineering without adhesive lamination.
- Substitution threat:Mass timber products including cross-laminated timber and glulam beams compete directly for the same green building certification credits.
Strategic Opportunities
- Austin building code pilot:Municipal-level structural bamboo approvals in Texas are creating precedent for commercial-scale demand expansion beyond residential flooring.
- Bamboo pulp convergence:Paper manufacturers seeking alternatives to virgin softwood fiber are driving capacity investment in cellulose extraction from bamboo fiber.
- Interior design channel innovation:Custom fabrication partnerships with high-end millwork shops are capturing superior margin pools through designer-specified installations.
Industry Challenges
- OSHA dust exposure compliance:Workplace safety standards for bamboo processing operations are forcing capital equipment investments in extraction and ventilation systems.
- FSC certification timeline:Chain-of-custody documentation requirements from plantation through finished product are extending procurement cycles for architectural specification wins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Bamboos Market |
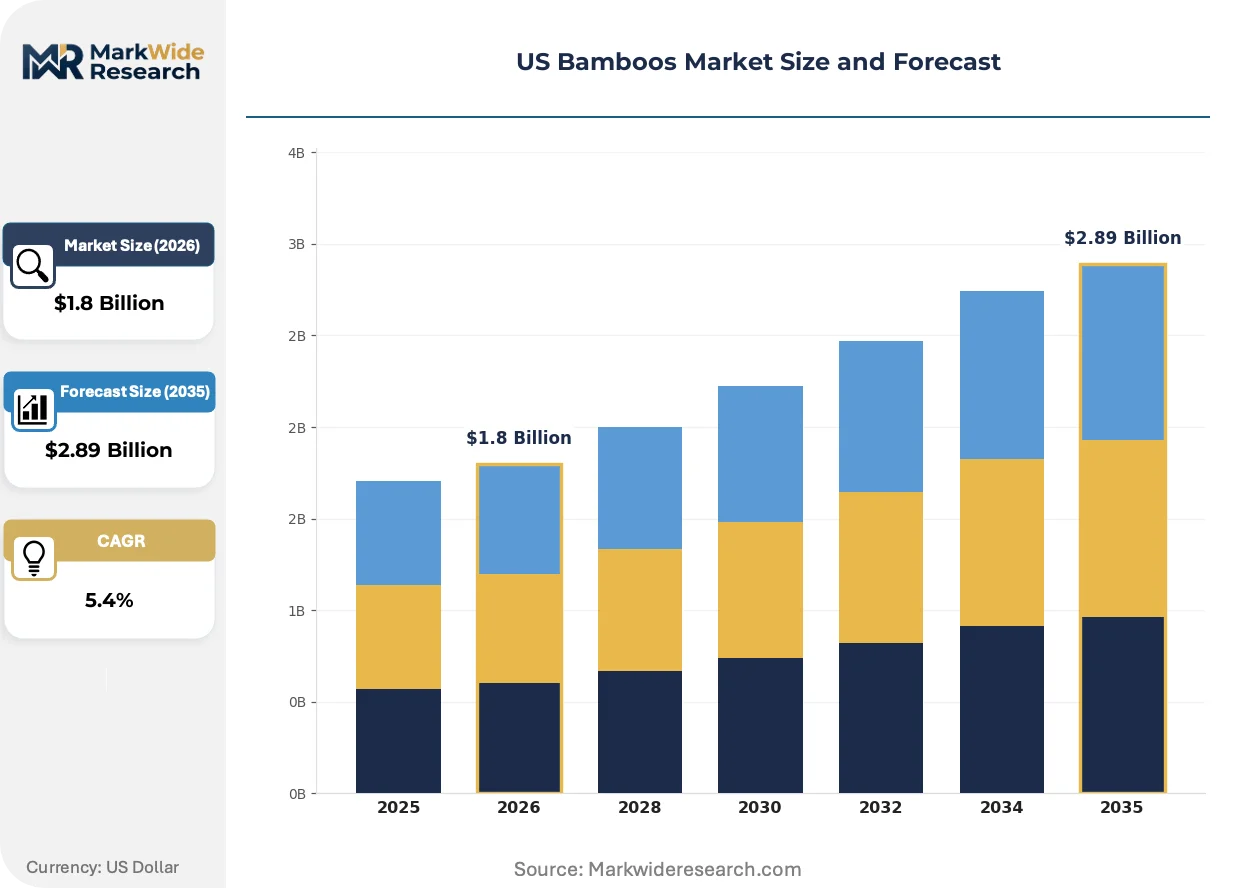
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bamboo Flooring, Bamboo Furniture, Bamboo Pulp, Bamboo Textiles Application: Construction, Interior Design, Paper Manufacturing, Fiber Production End User: Architects, Manufacturers, Retailers, Homeowners Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Bamboo Living, Bamboo Supply Co, EcoTimber Inc., EcoPlanet Bamboo Group LLC, Eldorado Bambu, Smith & Fong Co., Cali Bamboo, Higuera Hardwoods LLC, TIMIOS Trading LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Bamboos Market Trends and Innovations
Digital specification tools and computational design software are compressing the traditional architect-to-contractor material selection cycle for structural bamboo systems.
Cross-laminated bamboo panel manufacturing is virtualizing the structural performance gap between grass-based materials and conventional timber framing. Multi-family housing developers in Portland and Miami-Dade are specifying these panels for mid-rise construction. The technology is virtualizing legacy supply relationships that historically favored dimensional lumber distributors.
EPA TSCA Title VI formaldehyde emission standards are tightening documentation requirements for composite wood products including bamboo flooring and panel substrates. Manufacturers must now maintain third-party certification through accredited laboratories. California-based suppliers face the most stringent enforcement, driving consolidation among testing-capable producers.
Architect specification behavior is rotating toward performance-warranted structural systems with documented fire ratings and seismic testing. Design-build firms are displacing traditional bid-spec procurement for commercial projects. This shift concentrates most visibly in Austin and Portland where municipal green building incentives reward renewable material substitution.
US Bamboos Market Segmentation
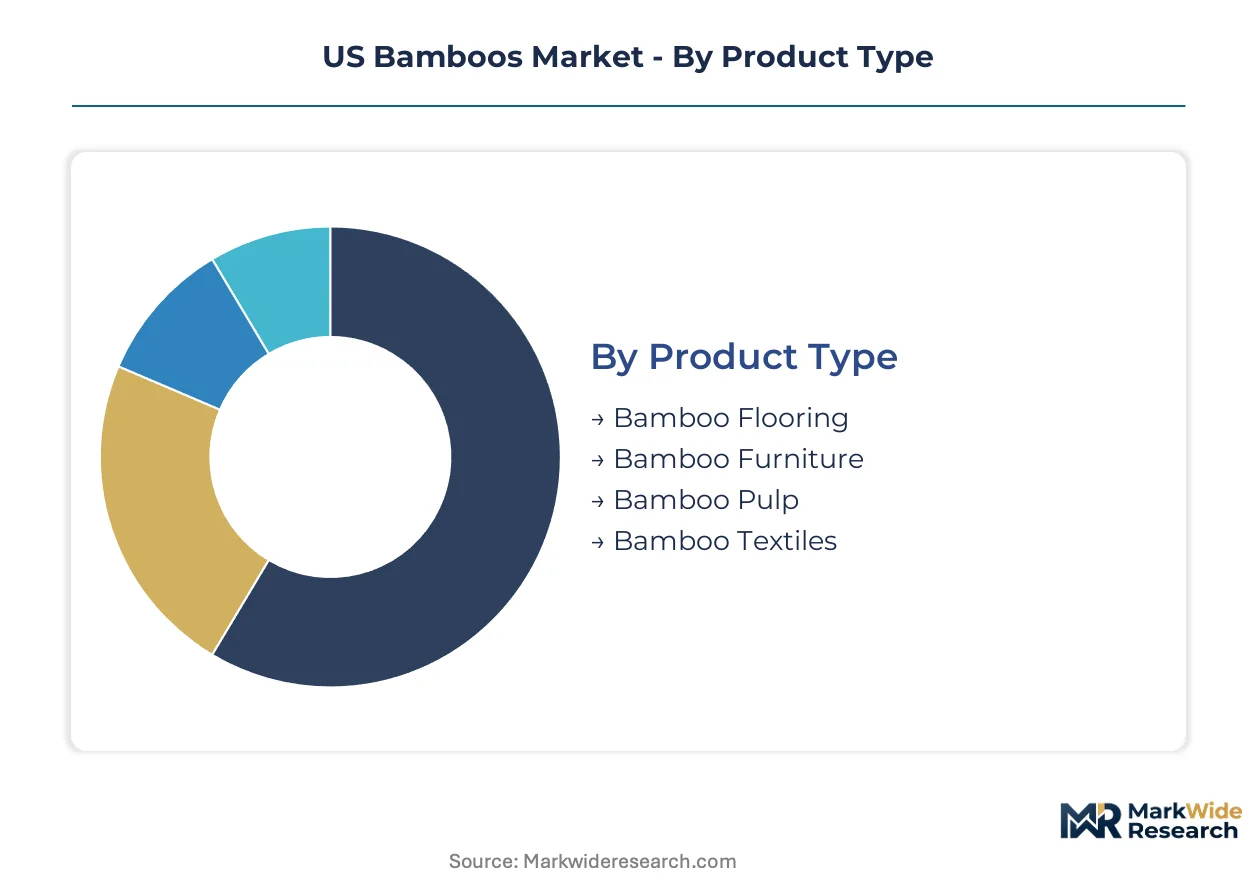
US bamboo demand fragments across product maturity stages, from established flooring installations to emerging pulp applications. Segmentation reveals how material properties, certification requirements, and channel economics allocate margin pools across the value chain.
Product Type:
Mature flooring products coexist with emerging cellulose extraction technologies across the product spectrum.
- Bamboo Flooring:Cross-laminated and strand-woven variants dominate residential specification due to established CARB Phase 2 compliance pathways and performance warranties. Multi-family housing developers in California and Texas specify these products for load-bearing subflooring applications.
- Bamboo Pulp:Cellulose extraction from Moso and Guadua species is displacing virgin softwood fiber in specialty paper grades. Paper manufacturers in the Pacific Northwest are piloting bamboo pulp integration for tissue and packaging substrates.
- Bamboo Furniture:Custom millwork shops in Florida source dimensionally stable lumber grades for high-end interior installations.
- Bamboo Textiles:Viscose and lyocell fiber production from bamboo cellulose serves apparel manufacturers seeking alternatives to cotton.
Bamboo Flooring retains volume leadership; Bamboo Pulp holds the steepest expansion curve.
Application:
Volume concentrates in structural uses while margin pools accumulate in specification-driven design channels.
- Construction:Engineered bamboo panels gain code approval for mid-rise residential framing in Austin, Portland, and Miami-Dade. Load-bearing applications require third-party seismic and fire rating documentation.
- Interior Design:Custom fabrication partnerships with architectural millwork shops capture premium pricing through designer-specified installations in California and Florida luxury residential.
- Paper Manufacturing:Pulp mills evaluate bamboo fiber blends for tissue and packaging grades seeking rapidly renewable certification.
- Fiber Production:Textile manufacturers process bamboo cellulose into viscose staple fiber for apparel and home furnishings.
Construction commands absolute volume; Interior Design secures the widest margin spreads.
End User:
Procurement authority varies by project scale and specification complexity across the customer base.
- Architects:Design-build firms in Austin and Portland specify performance-warranted structural systems with documented fire ratings and seismic testing for commercial projects.
- Manufacturers:Flooring and panel producers source FSC-certified raw material to maintain chain-of-custody documentation for architectural specification wins.
- Retailers:Home improvement channels stock CARB-compliant flooring grades with established installation familiarity among residential contractors.
- Homeowners:Direct procurement concentrates in California, Texas, and Florida where building code amendments permit bamboo in select structural uses.
Architects drive specification value; Manufacturers anchor procurement scale.
Distribution Channel:
Channel economics reflect certification burden, delivery velocity, and technical support requirements.
- Wholesale:Dimensional lumber and panel distributors serve residential contractors with volume pricing and just-in-time delivery for multi-family housing developments.
- Specialty Stores:Independent retailers in California and Florida provide specification support for custom flooring and millwork applications.
- Direct Sales:Engineered bamboo panel manufacturers bypass distribution to capture margin on large commercial projects with documented performance requirements.
- Online Retail:E-commerce platforms serve homeowner direct procurement for prefabricated flooring and furniture with standardized specifications.
Wholesale retains volume leadership; Direct Sales gains share fastest in structural panel categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA Biopreferred Program procurement preferences anchor demand concentration in California, Texas, and Florida, where building code amendments now permit bamboo in select structural uses. State-level adoption curves diverge based on municipal green building incentives and amended residential construction standards.
California
California Air Resources Board Phase 2 compliance requirements drive specification of CARB-certified bamboo flooring in multi-family housing developments. The state's formaldehyde emission standards favor products with third-party testing documentation. Los Angeles and San Francisco architectural firms specify cross-laminated bamboo panels for mid-rise residential framing.
Texas
Austin's municipal building code pilot creates precedent for structural bamboo approvals beyond residential flooring applications. The city's green building incentives reward renewable material substitution in commercial projects. Dallas-Fort Worth contractors expand engineered bamboo panel specification for load-bearing subflooring in multi-family housing.
Florida
Miami-Dade County pilots expanded structural bamboo approvals that could unlock commercial-scale demand for hurricane-resistant construction materials. The state's luxury residential market drives custom millwork fabrication partnerships with high-end interior design channels. Tampa and Orlando contractors specify dimensionally stable bamboo lumber grades for interior installations.
Pacific Northwest
Oregon and Washington paper manufacturers pilot bamboo pulp integration for tissue and packaging substrates seeking rapidly renewable certification. Portland's municipal green building incentives accelerate cross-laminated bamboo panel adoption for mid-rise construction. Seattle-area design-build firms specify performance-warranted structural systems with documented seismic testing.
Southeast
Georgia and North Carolina flooring distributors serve residential contractors with volume pricing and just-in-time delivery for multi-family housing developments. Atlanta and Charlotte retailers provide specification support for custom flooring applications. Regional wholesalers stock CARB-compliant grades with established installation familiarity among residential contractors.
US Bamboos Market Competitive Landscape
Capability concentration sits with vertically integrated specialists controlling fiber sourcing through finished product quality; scale advantage sits with distributors serving volume residential channels. The vendor base separates into three tiers: plantation-integrated producers, specification-focused architectural suppliers, and wholesale distributors. Consolidation pressures concentrate among testing-capable producers facing California's stringent enforcement environment. Competitive moves center on FSC certification timeline acceleration and cross-laminated panel manufacturing capacity expansion.
Within the plantation-integrated tier, EcoPlanet Bamboo Group LLC exemplifies upstream control over fiber sourcing for finished product consistency. Among specification-focused suppliers, Smith & Fong Co. and Cali Bamboo occupy positions anchoring architectural channel relationships through chain-of-custody documentation. These California-based entities represent the certification-capable archetype necessary for government procurement and commercial specification wins.
| Leading Market Players |
|---|
| Bamboo Living |
| Bamboo Supply Co |
| EcoTimber Inc. |
| EcoPlanet Bamboo Group LLC |
| Eldorado Bambu |
| Smith & Fong Co. |
| Cali Bamboo |
| Higuera Hardwoods LLC |
| TIMIOS Trading LLC |
| Others |
Pricing and Supply Chain Analysis
Southeast Asian plantation clusters in Vietnam and Indonesia govern raw material cost structures, with Moso fiber availability fluctuations transmitting directly into engineered bamboo panel pricing power for US distributors.
Pricing Analysis
California-to-Texas price spreads of 12-18 percent reflect CARB Phase 2 certification premiums and logistics positioning. Three-tier pricing structure across FSC-certified architectural grades, CARB-compliant residential flooring, and economy-grade panel stock segments the market. Pricing pressure stems from Southeast Asian plantation capacity constraints narrowing the historical cost advantage over tropical hardwood substitutes. Residential contractors exhibit highest price sensitivity, while design-build firms in Austin and Portland absorb premiums for performance-warranted structural systems with seismic documentation.
Supply Chain Analysis
USDA phytosanitary export controls on untreated bamboo culms restrict direct plantation-to-mill flows, forcing reliance on pre-processed fiber intermediates. Vietnam, Indonesia, and China anchor raw material supply, with Guadua and Moso species dominating cellulose extraction feedstocks. The chain draws from plantation harvesting, fiber processing, adhesive lamination, and finished panel distribution stages. Single-source vulnerability concentrates in Southeast Asian fiber preprocessing nodes subject to climate disruption. Distribution runs through wholesale lumber distributors serving volume residential channels, with direct manufacturer engagement on large commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US bamboo demand tracks residential construction cyclicality, with municipal code amendments in California, Texas, and Florida providing recovery amplification through expanded structural approvals.
For Market Incumbents: Pre-empt cross-laminated timber substitution by accelerating FSC certification timelines and locking architectural specification relationships through documented fire rating and seismic performance libraries. Backward integration into plantation partnerships secures fiber cost stability against Southeast Asian supply volatility. Prioritize capacity expansion in Texas to capture Austin code pilot momentum before mass timber distributors consolidate green building credits. For New Entrants and Emerging Players: Pursue white-space positioning in bamboo pulp supply to Pacific Northwest paper manufacturers seeking rapidly renewable certification alternatives to virgin softwood fiber. The interior design channel in Florida luxury residential offers penetrable entry with custom millwork fabrication partnerships. Lead with specification support capabilities rather than price competition against established flooring distributors. For Investors and Strategic Acquirers: Long-term, this sits as a materials substitution play because building code amendments are structurally displacing timber and steel in mid-rise residential framing. Acquisition targets should emphasize testing-capable producers with CARB Phase 2 compliance infrastructure and architectural channel relationships. Watch municipal green building incentive adoption curves as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Certification Acceleration | Chain-of-custody documentation unlocks federal procurement and commercial specification wins. |
| Cross-Laminated Panel Capacity Expansion | Mid-rise residential code approvals in Austin and Portland drive structural-grade demand. |
| Backward Plantation Integration | Upstream fiber control insulates margin from Southeast Asian supply volatility. |
| Architectural Specification Partnerships | Design-build procurement shift concentrates value with performance-warranted system providers. |
| Bamboo Pulp Supply Agreements | Pacific Northwest paper manufacturers seek rapidly renewable cellulose alternatives. |
Research Methodology
Cross-validation between primary fieldwork and secondary data anchors the qualitative findings for this analysis. Conversations with residential construction contractors, architectural specification leads, flooring distributors, and paper manufacturing procurement officers supplied demand-side intelligence. Secondary sources included USDA Biopreferred Program procurement databases, CARB Phase 2 compliance registries, municipal building code amendment records, and trade flow data from US Customs. Bottom-up segment sizing and top-down market triangulation reconciled volume estimates across product categories.
Calibration against historical adoption curves for engineered wood products and green building material penetration rates shaped the projection framework. Segmentation dimensions modeled include product type, application, end user procurement authority, and distribution channel economics across the analysis window. CAGRs derived from elasticity-adjusted demand drivers incorporating construction cycle positioning, code amendment momentum, and substitution rate assumptions. Industry-specific inputs captured cross-laminated panel performance testing documentation timelines and FSC certification cycle durations.
Macroeconomic conditions sit as an overlay; deviation in residential construction starts, mortgage rate trajectories, or municipal fiscal capacity would shift the trajectory. Forecasts embed assumptions on code amendment adoption velocity and Southeast Asian plantation capacity stability. Material shifts in federal procurement preference enforcement or mass timber product cost positioning would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
US Wallcovering Market
Homecare and Decor
Bookends Market
Homecare and Decor
Fragrant Drawer Liners Market
Homecare and Decor
Europe Mattress Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
Hearth Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
Smart Vase Market
Homecare and Decor
Europe Wall Coverings Market
Homecare and Decor
Asia-Pacific Wall Covering Market
Homecare and Decor
Global Decorative Laminates Market
Homecare and Decor
Terracotta Pots Market
Homecare and Decor
Wall Covering Market
Homecare and Decor
United States Home Decor Market
Homecare and Decor
Smart Bed Mattress Market
Homecare and Decor
Europe Flower Pots and Planters Market