
 Digital Printed Wallpaper Market | 2026-2036
Digital Printed Wallpaper Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Printed Wallpaper Market Analysis
Vinyl substrates are restructuring cost-performance trade-offs across the digital printed wallpaper supply chain as fabric and non-woven alternatives gain share in premium specification channels. Graham and Brown Ltd. leverages vertical integration across design-to-distribution to sustain margin control in European retail. Muraspec Decorative Solutions Ltd. anchors large-format hospitality projects through specialized UV printing capacity. A.S. Création Tapeten AG competes on design velocity, releasing seasonal collections that occupy fast-turnover retail shelf space.
Digital printed wallpaper denotes wallcoverings produced via direct-to-substrate inkjet, UV-cured, latex, or eco-solvent printing systems on vinyl, fabric, paper, or non-woven backings, typically at resolutions exceeding 300 dpi for photographic reproduction fidelity, serving interior decoration and brand environment applications. Vinyl dominates volume production due to durability and washability in commercial settings, while non-woven substrates represent the fastest-growing category among architects specifying breathable, strippable installations. Latex printing technology leads in sustainability-sensitive segments as water-based formulations reduce volatile organic compound emissions without sacrificing color gamut.
EPA guidelines on indoor air quality and REACH restrictions on phthalate plasticizers constrain vinyl formulation choices in North American and European markets, pushing manufacturers toward compliant plasticizer alternatives or substrate diversification. China's GB standards on interior decoration materials and SAMR labeling requirements shape product access for imported wallcoverings. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation adaptation or platform standardization delivers superior compliance economics.
Market Dynamics
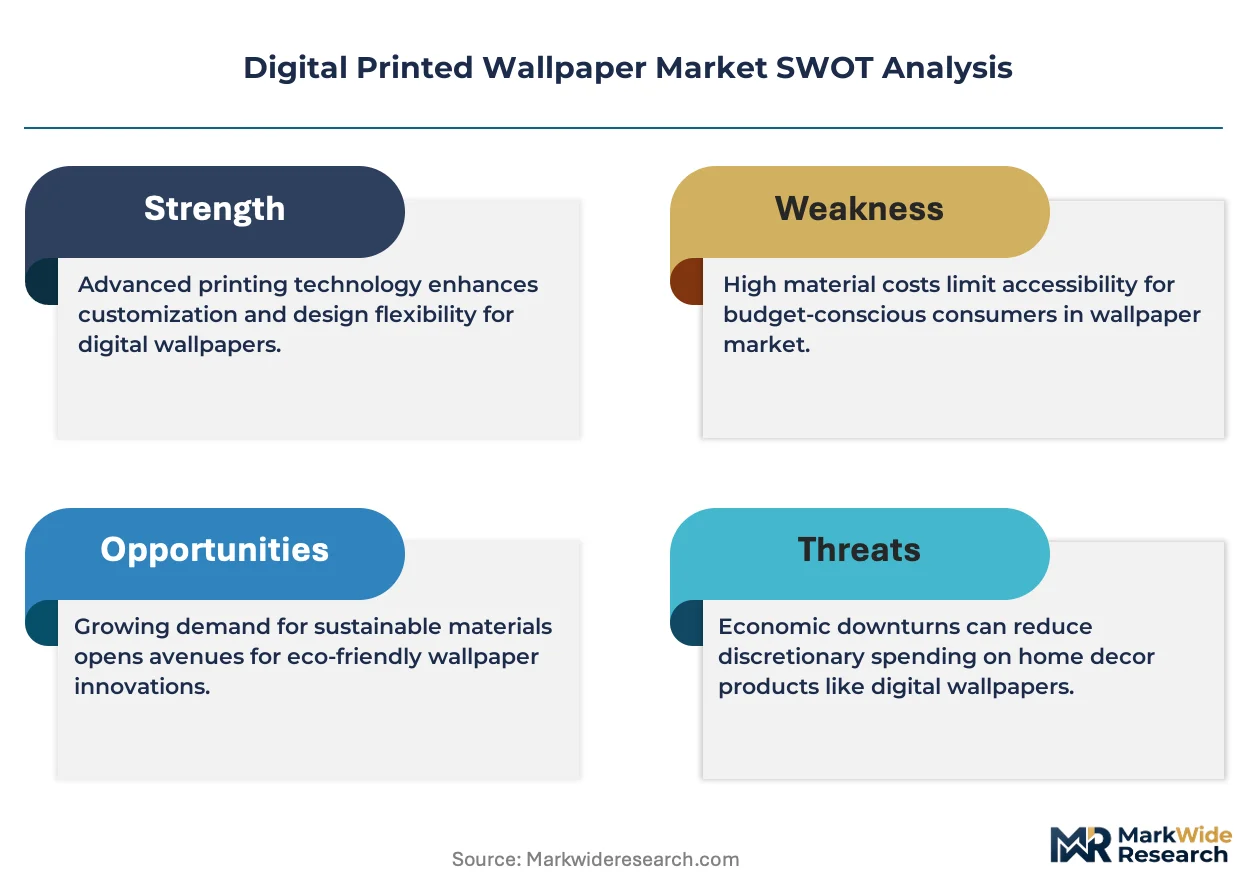
Latex ink technology is unifying sustainability and performance specifications across hospitality and healthcare interiors, forcing substrate and formulation choices that comply with EPA indoor air quality guidelines and REACH phthalate restrictions.
Growth Catalysts
- REACH plasticizer compliance:European manufacturers accelerate compliant vinyl formulation shifts, opening specification access to institutional buyers previously blocked by emission thresholds.
- Guangdong printing cluster concentration:Integrated design-to-print-to-ship facilities in China's Pearl River Delta compress lead times for export orders to Middle Eastern hospitality developers.
- Non-woven substrate breathability:Architects specifying strippable, mold-resistant installations in humid climates drive material substitution away from traditional vinyl backings.
Market Restraints
- Petrochemical input volatility:PVC resin and plasticizer cost swings compress margin predictability for volume producers dependent on spot market sourcing.
- Single-region supply concentration:China's dominance in both substrate manufacturing and printing equipment assembly creates vulnerability to port congestion and trade policy friction.
- Digital file standardization gaps:Absence of unified color profile protocols between design software and RIP systems forces costly pre-press reconciliation on every custom job.
Strategic Opportunities
- Saudi hospitality fit-out wave:Giga-project construction timelines in Riyadh and Jeddah create demand surges for branded interior wallcoverings with 12-week installation windows.
- UV-cured latex hybrid systems:Convergence of instant curing and water-based chemistry enables same-day turnaround on short-run custom orders previously uneconomical.
- Direct-to-designer digital platforms:Bypassing traditional distributor markups, manufacturers capture margin and demand data by serving commercial interior specifiers through proprietary configurators.
Industry Challenges
- Color management specialist scarcity:Shortage of technicians proficient in ICC profiling for textile substrates forces reliance on equipment vendor support contracts.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of CE marking, EPA compliance, and China's GB standards extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Printed Wallpaper Market |
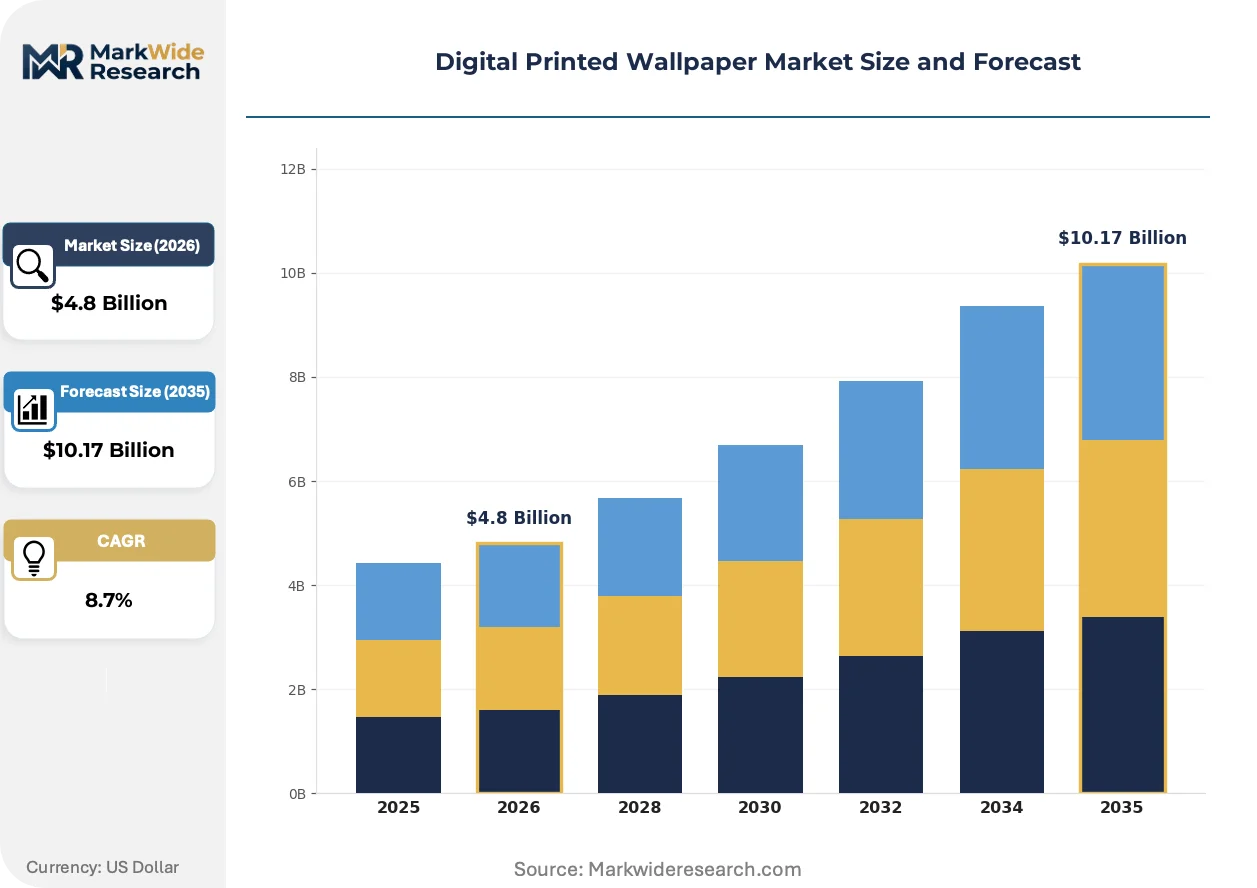
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, Fabric, Paper, Non-Woven End User: Residential, Commercial, Hospitality, Retail Printing Technology: Inkjet, UV Printing, Eco-Solvent, Latex Design Style: Abstract, Floral, Geometric, Scenic |
| Companies Covered | Graham and Brown Ltd., Muraspec Decorative Solutions Ltd., A.S. Création Tapeten AG, Brewster Home Fashions Inc., York Wallcoverings, Flavor Paper, Great Wall Custom Coverings Corporation, Astek Wallcovering, 4Walls Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Printed Wallpaper Market Emerging Trajectories
Wallcovering production is fragmenting across substrate-technology combinations as sustainability mandates and customization demands pull in divergent directions. Three forces dominate current investment patterns.
Latex printing is unifying ecological compliance with commercial durability by eliminating solvent-based curing while maintaining scrub resistance. Hospitality chains in Dubai and Singapore specify latex-printed vinyl for high-traffic corridors, compressing the historical trade-off between LEED-qualifying materials and washability ratings. Equipment vendors report 40% of new installs in 2024 specified aqueous ink configurations.
REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation of legacy vinyl backings across European supply chains. Manufacturers face 18-24 month validation cycles for alternative plasticizer systems, with medical and childcare facilities representing the most price-tolerant early adopters of compliant products. German and French regulators are tightening enforcement timelines, accelerating substitution decisions.
Specification behavior is rotating toward sample-on-demand fulfillment models that compress traditional distributor inventory roles. Commercial interior designers in London and New York now expect 48-hour physical sample delivery from digital file submission, forcing manufacturers to maintain regional finishing capacity rather than centralized production. This pattern is most visible in luxury residential and boutique hospitality verticals where project timelines have compressed by 30% since 2022.
Digital Printed Wallpaper Market Segmentation
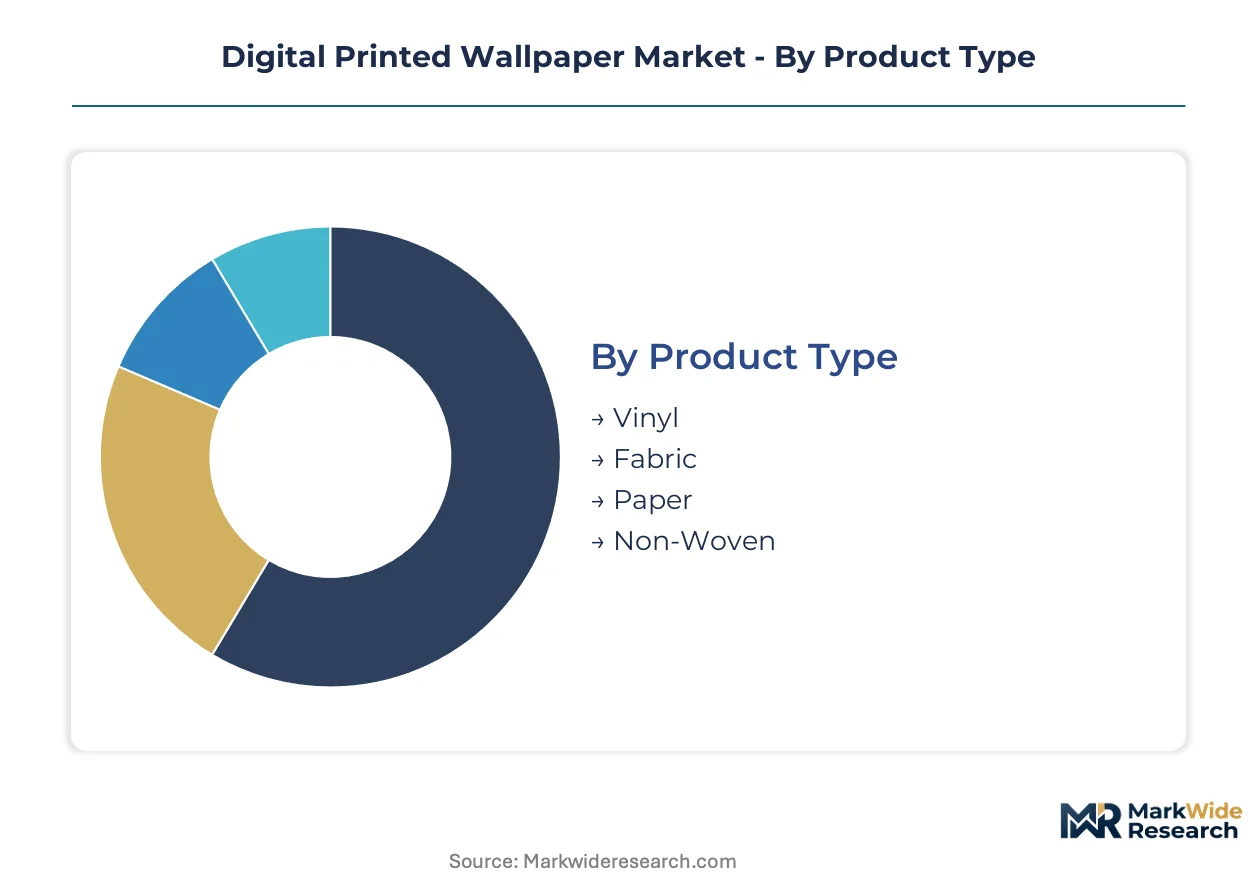
Digital printed wallpaper buyers diverge sharply across durability requirements, installation complexity, and sustainability thresholds. Segmentation reveals how substrate chemistry, end-use environment, and printing system capabilities determine procurement patterns and margin structures.
Product Type:
Purchase decisions in this category pivot on washability ratings, breathability needs, and compliance with indoor air quality standards in institutional settings.
- Vinyl:PVC-based backings with plasticizer formulations deliver scrub resistance exceeding 1,000 cycles per ASTM standards. Hospitality corridors in Dubai and Singapore specify vinyl for high-traffic zones where maintenance protocols demand chemical cleaning compatibility.
- Non-Woven:Cellulose-polyester blends enable strippable installation without wall damage, addressing mold concerns in humid climates. Architects in Guangdong province specify non-woven for healthcare renovations where substrate breathability reduces moisture entrapment liability.
- Fabric:Textile wallcoverings with direct-print capability serve luxury residential segments where tactile surface quality commands specification priority.
- Paper:Lightweight backings dominate cost-sensitive retail refresh cycles where 12-18 month replacement horizons minimize durability investment.
Volume sits with Vinyl; growth tilts toward Non-Woven.
End User:
Project timelines and brand control requirements separate procurement behavior across installation environments.
- Commercial:Office fit-outs and corporate environments drive repeat-order contracts with 3-5 year refresh cycles. Facility managers in Riyadh prioritize LEED-qualifying latex prints to meet Saudi Vision 2030 sustainability mandates.
- Hospitality:Branded interior requirements for hotel chains demand color-matched batch consistency across multiple properties. Singapore-based operators compress lead times to 8 weeks through Guangdong cluster direct sourcing.
- Residential:Single-family and multi-family housing markets concentrate demand in seasonal collection releases with sample-on-demand fulfillment expectations.
- Retail:Store environment refreshes cycle every 18-24 months, prioritizing visual impact over extended durability specifications.
Commercial captures the largest order values; Hospitality posts the steepest expansion trajectory.
Printing Technology:
Capital equipment choices lock manufacturers into ink chemistry ecosystems with divergent regulatory compliance profiles.
- Latex:Water-based formulations cure via thermal drying, eliminating solvent emissions while maintaining color gamut comparable to eco-solvent systems. EPA indoor air quality guidelines and REACH restrictions are accelerating specification shifts in North American and European institutional markets.
- UV Printing:Instant photoinitiated curing enables same-day turnaround on short-run custom orders. Dubai hospitality developers leverage UV capacity for 48-hour sample-to-production workflows on giga-project timelines.
- Inkjet:Piezoelectric drop-on-demand systems dominate entry-level production with lower capital barriers but higher per-square-meter ink costs.
- Eco-Solvent:Mild solvent formulations retain share in outdoor and high-durability applications where substrate adhesion requirements exceed aqueous system capabilities.
Installed base concentrates in Eco-Solvent; capacity additions favor Latex.
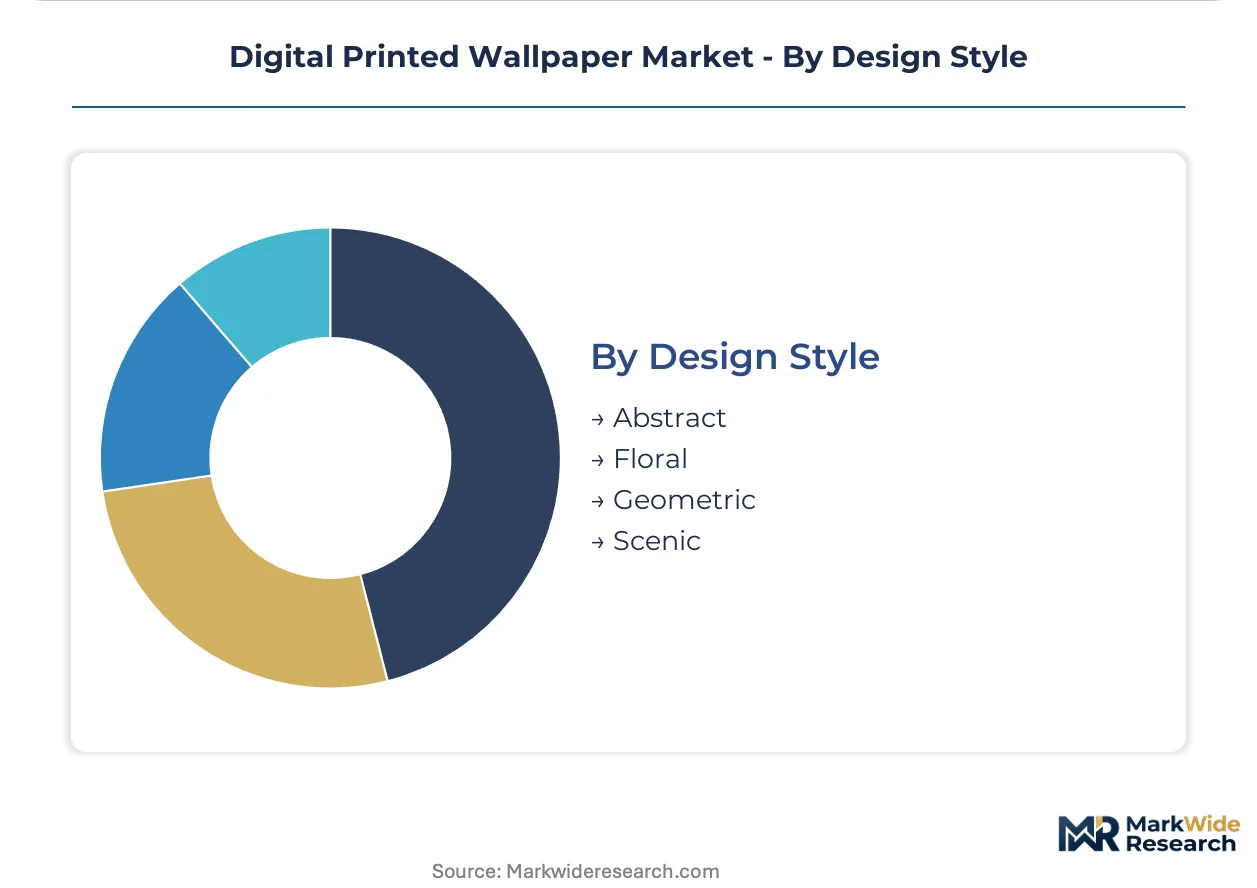
Design Style:
Pattern complexity and color channel requirements influence RIP software selection and pre-press specialist allocation.
- Scenic:Photographic reproductions at 300+ dpi demand ICC profile precision for gradient continuity across wide-format panels. London and New York interior designers specify scenic murals for luxury residential statement walls with 48-hour sample delivery requirements.
- Geometric:Vector-based patterns with solid color fields minimize pre-press reconciliation time and enable faster design-to-print cycles for retail environment refreshes.
- Floral:Botanical motifs with nuanced color transitions require expanded ink sets and extended proofing cycles, concentrating demand among premium specification channels.
- Abstract:Non-representational patterns offer maximum design velocity with reduced licensing complexity, supporting fast-turnover seasonal collection releases.
Geometric dominates production volume; Scenic commands the highest per-square-meter pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality chains in Dubai and Singapore are accelerating specification of custom printed wallcoverings, while REACH compliance in Europe and China's GB standards reshape material formulation requirements across export markets.
China
Guangdong province's integrated printing clusters serve both domestic fit-out and Middle Eastern export demand with compressed lead times. GB standards on interior decoration materials and SAMR labeling requirements govern product access for wallcovering imports. Shenzhen and Dongguan host captive design-to-print-to-ship facilities that supply branded hospitality projects in Riyadh and Jeddah.
United States
Commercial interior designers in New York and Los Angeles now expect 48-hour physical sample delivery from digital file submission. EPA indoor air quality guidelines constrain vinyl formulation choices, pushing manufacturers toward latex ink systems for LEED-qualifying projects. Regional finishing capacity in the Southeast and Southwest replaces centralized production to meet compressed project timelines.
Germany
REACH Annex XVII restrictions on phthalate plasticizers force 18-24 month validation cycles for alternative vinyl formulations. Medical and childcare facilities in Berlin and Munich represent price-tolerant early adopters of compliant products. ECHA enforcement timelines are tightening, accelerating substitution decisions among legacy manufacturers.
United Arab Emirates
Giga-project construction in Riyadh and Jeddah creates demand surges for branded interior wallcoverings with 12-week installation windows. Dubai-based hospitality developers leverage UV-cured capacity for 48-hour sample-to-production workflows. MOHAP and local building codes emphasize fire safety and indoor air quality for high-traffic commercial environments.
Singapore
Hotel operators compress procurement lead times to 8 weeks through direct sourcing from Guangdong printing clusters. Humid climate conditions drive architect specification of non-woven substrates for mold-resistant, strippable installations. The Building and Construction Authority's Green Mark certification rewards low-VOC wallcovering materials in commercial fit-outs.
Digital Printed Wallpaper Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers add regional finishing facilities to meet 48-hour sample delivery expectations. The vendor base separates into three tiers: integrated design-to-distribution houses, specialized hospitality contractors, and digital-native direct-to-designer platforms. Strategic archetypes include vertically integrated European retailers, large-format UV printing specialists, and fast-turnover seasonal collection publishers. M&A activity and geographic expansion into Saudi hospitality markets represent the dominant competitive moves.
Within the integrated retail tier, Graham and Brown Ltd. and A.S. Création Tapeten AG exemplify design-velocity competitors sustaining margin control through captive distribution. Among hospitality-focused specialists, Muraspec Decorative Solutions Ltd. occupies a position aligned with large-format project execution. These three companies represent distinct strategic postures: vertical integration for retail shelf space dominance, rapid collection turnover for seasonal demand capture, and specialized capacity for branded environment installation.
| Leading Market Players |
|---|
| Graham and Brown Ltd. |
| Muraspec Decorative Solutions Ltd. |
| A.S. Création Tapeten AG |
| Brewster Home Fashions Inc. |
| York Wallcoverings |
| Flavor Paper |
| Great Wall Custom Coverings Corporation |
| Astek Wallcovering |
| 4Walls Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists across Germany and northern Italy anchor substrate finishing capacity, translating captive ink formulation expertise into pricing discipline that resists commoditization in custom hospitality specifications. Their ownership structure supports long-dated supplier relationships with Guangdong resin producers, buffering spot market volatility that erodes margin at publicly traded volume competitors.
Pricing Analysis
Volume concentrates in economy-grade vinyl rolls for retail refresh cycles, while margin pools in premium non-woven and fabric substrates specified by Dubai hospitality developers. Three-tier pricing structure across premium, standard, and economy levels reflects washability certification tiers and customization depth. Price erosion runs through economy vinyl as Chinese integrated producers compress export quotes to capture Saudi giga-project tenders. Retail buyers exhibit highest price sensitivity, whereas healthcare facility managers in Singapore accept substantial premiums for REACH-compliant latex formulations.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong province for both PVC resin compounding and wide-format printer assembly. Raw material flows draw from South Korean petrochemical complexes for plasticizer precursors, German specialty chemical producers for latex ink polymers, and Indonesian pulp operations for non-woven cellulose feedstock. Tariff exposure between US and Chinese finished goods trade forces regional finishing investments in Mexico and Poland. Distribution runs through project-specification channels where commercial interior designers in London and New York bypass traditional distributor markups via direct-to-designer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regional finishing capacity constraints prop pricing power for manufacturers with installed latex and UV curing assets, as 48-hour sample delivery requirements eliminate pure trading intermediaries from specification-intensive verticals.
For Market Incumbents: To counter margin compression from Chinese integrated producers, Graham and Brown Ltd. and comparable European houses should deepen backward integration into compliant plasticizer formulation and establish captive regional finishing nodes in Poland and the US Southeast. Certification investment in simultaneous CE marking and EPA compliance creates specification moats that delay challenger entry by 8-14 months. For New Entrants and Emerging Players: UV-cured latex hybrid technology offers a technology-first wedge into Saudi hospitality fit-out timelines where 12-week installation windows punish incumbent lead times. White-space targets include direct-to-designer digital platforms serving London and New York commercial interior specifiers, and non-woven substrate specialization for Singapore healthcare renovations requiring mold-resistant installations. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European printers with stranded REACH validation investments and established architect relationships in Berlin and Munich. Long-term viability hinges on substrate diversification capability and installed latex capacity. The signal to watch is Guangdong port congestion indices, which trigger accelerated regional finishing buildouts and acquisition premiums for European assets with compliant formulation pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Finishing Capacity Expansion | Polish and US Southeast facilities capture 48-hour sample delivery contracts from New York designers. |
| Backward Integration into Compliant Plasticizers | German manufacturers reduce REACH validation cycle exposure through captive alternative formulation development. |
| Direct-to-Designer Platform Launch | Proprietary configurators bypass distributor markups while capturing demand data from commercial interior specifiers. |
| UV-Cured Latex Hybrid System Deployment | Dubai hospitality developers achieve same-day turnaround on giga-project custom orders previously uneconomical. |
| Non-Woven Substrate Specialization | Singapore healthcare architects specify strippable, mold-resistant installations in humid climate conditions. |
Methodological Framework
Trade databases, customs records, and equipment vendor installation disclosures formed the secondary backbone, cross-referenced with primary interviews involving ink formulation chemists, hospitality procurement directors, commercial interior designers, and wide-format printer operations managers. Bottom-up and top-down triangulation reconciled substrate shipment volumes with end-use installation data across hospitality, healthcare, and retail verticals.
Bottom-up modeling anchored volume projections to installed printer capacity by technology type and utilization assumptions, while top-down validation tested aggregate figures against regional construction spend patterns. Segmentation dimensions included substrate chemistry, printing system technology, end-use environment, and design complexity tier. CAGRs were derived from curve-fitting historical adoption patterns against regulatory compliance deadlines and hospitality construction pipeline data.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting Guangdong export flows and unanticipated breakthroughs in solvent-free curing chemistry. Forecasts reflect documented assumptions about REACH enforcement timelines and Saudi giga-project completion schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
ASEAN UPVC Doors and Windows Market
Homecare and Decor
Pillow Market
Homecare and Decor
Wall Covering Products Market
Homecare and Decor
Mattress and Mattress Component Market
Homecare and Decor
India Wall Decor Market
Homecare and Decor
India Wallpapers Market
Homecare and Decor
Corner Pads Market
Homecare and Decor
Soundproof Curtains Market
Homecare and Decor
Europe Flower Pots and Planters Market
Homecare and Decor
US Halloween Decorations Market
Homecare and Decor
Fireplace and Stove Market
Homecare and Decor
United Kingdom Resilient Floor Covering Market
Homecare and Decor
Home Decor and Accessories Market
Homecare and Decor
USA Bed Pillow Market
Homecare and Decor
Bifold Door Market
Homecare and Decor
Global Wallpaper Market